
 DNA Synthesizer Market | 2026-2036
DNA Synthesizer Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Synthesizer Market Analytics
The capital-intensity divergence between benchtop and industrial-scale platforms is redrawing competitive boundaries in DNA synthesis. Danaher sustains integrated reagent-to-instrument workflows that anchor its position in pharmaceutical quality-control environments. Twist Bioscience leverages silicon-based DNA writing technology to dominate high-throughput gene synthesis for synthetic biology applications. Kilobaser competes through compact, lower-throughput systems designed for distributed academic and diagnostic lab deployment.
A DNA synthesizer is an automated instrument that assembles nucleic acid sequences through controlled chemical or enzymatic reactions, typically achieving chain lengths from 20 to 200 bases with cycle times under ten minutes per base addition. Its primary commercial purpose is to produce custom oligonucleotides, gene fragments, and synthetic genes for research, therapeutic development, and diagnostic manufacturing. Solid-phase synthesizers retain the largest installed base among product categories, though enzymatic synthesis platforms represent the fastest-expanding segment as researchers pursue phosphoramidite-free chemistries. Gene therapy applications command premium pricing due to stringent purity requirements, while synthetic biology workflows drive volume demand from biotechnology companies scaling engineered organism programs.
The FDA regulates synthetic nucleic acids intended for therapeutic use under gene therapy guidance, while the EPA monitors oligonucleotide manufacturing waste streams under hazardous chemical discharge rules. ISO 13485 quality management standards shape instrument design for diagnostic applications, particularly in European markets where CE marking requirements apply to in-vitro diagnostic platforms. Stakeholders must weigh enzymatic versus phosphoramidite technology commitments against evolving regulatory frameworks for gene-editing reagents and synthetic biology products.
Market Dynamics
Enzymatic synthesis platforms are compressing cycle times and eliminating hazardous reagent handling, forcing incumbent phosphoramidite-dependent vendors to retool instrument architectures or cede benchtop segments to enzymatic entrants.
Growth Catalysts
- Gene therapy manufacturing scale-up:FDA gene therapy guidance is tightening purity specifications for synthetic oligonucleotides, pushing contract manufacturers toward automated, GMP-grade synthesis platforms with integrated quality analytics.
- Synthetic biology infrastructure investment:Germany, China, and the United States are expanding biotech cluster capacity with dedicated oligo synthesis facilities serving engineered organism programs.
- CE marking alignment for IVD platforms:ISO 13485-certified instruments gain automatic market access across EU member states, accelerating replacement cycles in diagnostic manufacturing.
Market Restraints
- Phosphoramidite reagent cost volatility:Solid-phase synthesis depends on acetonitrile and controlled-pore glass substrates subject to solvent supply disruptions and specialty chemical pricing swings.
- Enzyme supply concentration:Thermostable DNA polymerase production concentrates among a handful of fermentation suppliers, creating single-source vulnerability for enzymatic platform operators.
- Chain length fidelity ceiling:Current enzymatic methods struggle to exceed 300-base accuracy without error-correction overhead, limiting direct gene synthesis applications.
Strategic Opportunities
- Distributed diagnostic lab deployment:Compact, cartridge-based synthesizers address point-of-care nucleic acid manufacturing in India and Southeast Asia where cold-chain oligo logistics remain unreliable.
- Dual-use biosecurity frameworks:Screening algorithms for pathogenic sequence orders are becoming procurement prerequisites, creating software-anchored platform differentiation.
- AI-driven sequence optimization:Machine learning tools for codon optimization and secondary structure prediction are converging with synthesis workflows to compress design-to-synthesis timelines.
Industry Challenges
- Cross-disciplinary talent scarcity:Platform development requires simultaneous expertise in surface chemistry, microfluidics, and bioinformatics, with few training programs producing qualified candidates.
- Legacy instrument integration friction:Academic core facilities face workflow disruption when migrating from phosphoramidite to enzymatic platforms, requiring revalidation of established protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Synthesizer Market |
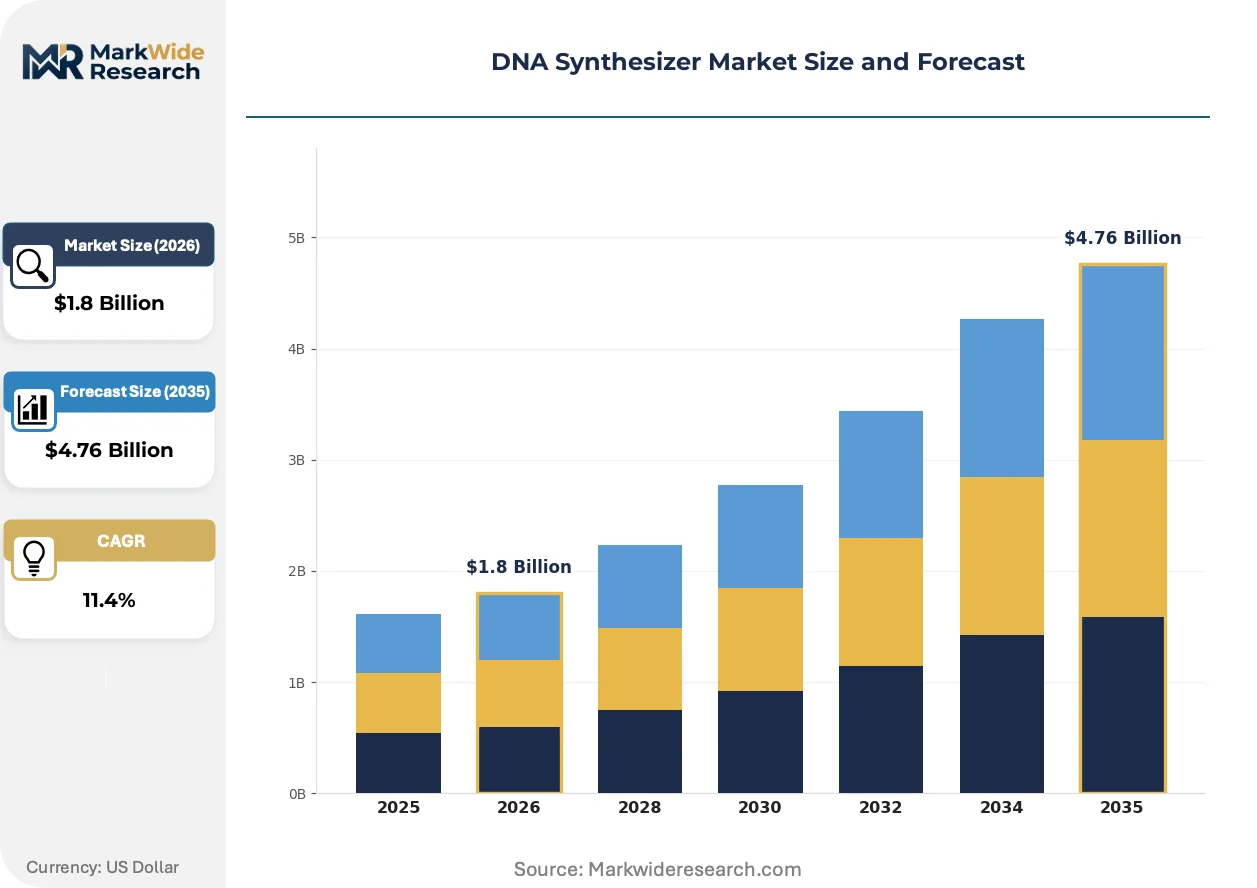
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Synthesizers, Solid-Phase Synthesizers, Microarray Synthesizers, Oligo Synthesis Platforms Technology: Phosphoramidite Chemistry, Polymerase Chain Reaction, Chip-based Synthesis, Enzymatic Synthesis End User: Biotechnology Companies, Academic Research Institutes, Pharmaceutical Firms, Diagnostic Labs Application: Gene Therapy, Synthetic Biology, Vaccine Development, Genomics Research |
| Companies Covered | Danaher, Twist Bioscience, Kilobaser, LGC Limited, CSBio, K&A Labs GmbH, DNA Script, Biolytic Lab Performance Inc., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Synthesizer Market Evolving Landscape
Next-generation synthesis architectures are converging on miniaturization, software-defined chemistry, and biosecurity integration. These shifts are compressing instrument footprints while expanding accessible application spaces.
Terminal deoxynucleotidyl transferase (TdT)-based enzymatic synthesis is displacing phosphoramidite chemistry in next-generation platforms by enabling aqueous-phase reactions without organic solvent handling. Synthetic biology startups and contract research organizations are adopting TdT systems for rapid gene fragment prototyping. This displacement is compressing the addressable market for traditional solid-phase benchtop instruments below 96-well throughput tiers.
REACH authorization requirements for oligonucleotide manufacturing waste streams are tightening discharge standards for acetonitrile and tetrazole derivatives across EU production facilities. German and Swiss instrument vendors are responding with closed-loop solvent recovery modules integrated into industrial-scale platforms. The regulatory pressure is accelerating phosphoramidite-to-enzymatic transition timelines for European pharmaceutical manufacturers.
Consolidated procurement through centralized core facilities is fragmenting toward distributed, department-level instrument placement as compact enzymatic systems reduce capital barriers. Research universities in the United States are deploying satellite synthesis stations within individual biology departments rather than routing all orders through central chemistry cores. This pattern is most visible in Boston and San Francisco biotech corridors where principal investigators prioritize turnaround time over per-base cost minimization.
DNA Synthesizer Market Segmentation
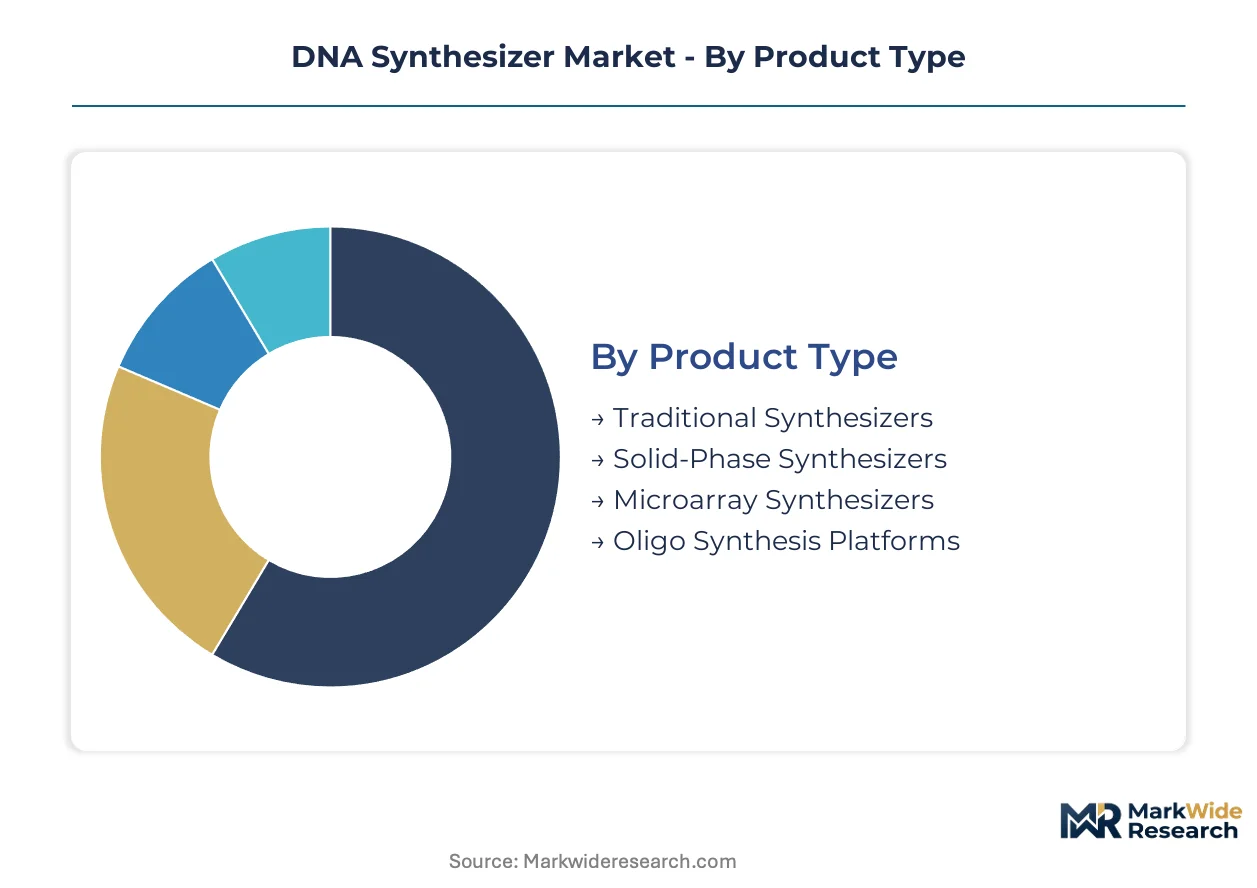
DNA synthesizer segmentation reveals divergent technology commitments across customer tiers. Academic core facilities favor established phosphoramidite workflows, while synthetic biology startups drive enzymatic platform adoption. Pharmaceutical manufacturers select instruments based on regulatory compliance requirements rather than throughput alone.
Product Type:
Solid-phase systems dominate domestic pharmaceutical manufacturing, while microarray platforms serve export-oriented gene synthesis services. Traditional synthesizers retain installed base in budget-constrained academic settings.
- Solid-Phase Synthesizers:These instruments anchor pharmaceutical quality-control environments through controlled-pore glass substrate compatibility and GMP-grade reagent integration. German and Swiss contract manufacturers deploy industrial-scale solid-phase systems for gene therapy oligonucleotide production under EMA guidance. FDA tightening of purity specifications accelerates replacement cycles in United States therapeutic manufacturing.
- Microarray Synthesizers:Silicon-based DNA writing enables parallel synthesis of thousands of sequences with sub-microliter reagent volumes. China-based synthetic biology service providers scale microarray capacity to serve engineered organism programs across Asia-Pacific biotech clusters. Cost per base compression drives adoption among high-throughput gene foundries.
- Traditional Synthesizers:Phosphoramidite-dependent benchtop units persist in academic core facilities with established protocol libraries.
- Oligo Synthesis Platforms:Integrated cartridge-based systems reduce operator training requirements for diagnostic lab deployment.
Solid-phase synthesizers command the established base. The steepest expansion runs through microarray synthesizers.
Technology:
Cost tier separation is pronounced: phosphoramidite chemistry requires expensive controlled-pore glass and acetonitrile solvent handling, while enzymatic methods shift cost structure toward recombinant enzyme supply.
- Enzymatic Synthesis:Terminal deoxynucleotidyl transferase-based aqueous-phase reactions eliminate hazardous organic solvent handling and compress cycle times. Synthetic biology startups in Boston and San Francisco corridors adopt TdT systems for rapid gene fragment prototyping without cleanroom infrastructure. Chain length fidelity constraints below 300 bases limit direct gene synthesis applications.
- Phosphoramidite Chemistry:Four-decade maturity delivers predictable stepwise coupling efficiency above 99.5% per base addition. Pharmaceutical manufacturers in Germany and Switzerland retain phosphoramidite workflows for therapeutic oligonucleotides requiring REACH-compliant waste stream documentation. Acetonitrile supply volatility creates procurement risk for high-volume operators.
- Chip-based Synthesis:Photolithographic or electrochemical patterning enables massive parallelism on semiconductor substrates.
- Polymerase Chain Reaction:PCR-dependent amplification workflows supplement de novo synthesis for template extension applications.
Phosphoramidite chemistry anchors current revenue. Enzymatic synthesis gains share fastest among new platform procurement.
End User:
Volume concentration differs sharply: diagnostic labs generate high oligo consumption with short turnaround requirements, while academic institutes prioritize cost per base over speed.
- Biotechnology Companies:Engineered organism programs demand scalable gene synthesis for pathway construction and host strain optimization. Synthetic biology startups in United States biotech corridors deploy distributed synthesis stations to compress design-build-test cycles. Venture capital inflows into German and Chinese biotech clusters expand oligo synthesis infrastructure.
- Diagnostic Labs:Point-of-care nucleic acid manufacturing requires compact, cartridge-based systems with minimal cold-chain dependence. Indian and Southeast Asian diagnostic networks adopt benchtop enzymatic synthesizers where oligo logistics remain unreliable. ISO 13485 certification requirements shape instrument selection for in-vitro diagnostic platforms.
- Academic Research Institutes:Core facilities balance per-base cost minimization against principal investigator turnaround demands.
- Pharmaceutical Firms:Gene therapy manufacturing imposes stringent purity specifications with integrated quality analytics.
Biotechnology companies command the established base. The steepest expansion runs through diagnostic labs.
Application:
Margin structure varies: gene therapy applications command premium pricing for GMP-grade oligonucleotides, while genomics research operates at commoditized per-base rates.
- Gene Therapy:Synthetic oligonucleotides for antisense, siRNA, and mRNA therapeutics require purity levels exceeding 99.9% with comprehensive impurity profiling. FDA gene therapy guidance tightens specifications for clinical-grade material, pushing contract manufacturers toward automated platforms with integrated analytics. United States and European pharmaceutical manufacturers absorb premium instrument costs to secure regulatory compliance.
- Synthetic Biology:Engineered organism construction drives volume demand for gene fragments and synthetic operons with rapid iteration cycles. Chinese biotech clusters expand dedicated oligo synthesis facilities to serve domestic engineered organism programs. Codon optimization software integration compresses design-to-synthesis timelines for pathway engineering.
- Vaccine Development:mRNA vaccine manufacturing surge established scalable synthesis infrastructure now repurposed for infectious disease programs.
- Genomics Research:CRISPR guide RNA and probe synthesis generates steady demand from academic sequencing centers.
Gene therapy commands the established base. The steepest expansion runs through synthetic biology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium instrument pricing in Switzerland and Germany exceeds comparable United States deployments by margins reflecting REACH compliance overhead and precision manufacturing labor costs. This asymmetry concentrates profit pool capture in Alpine and Central European production zones while North American demand absorbs volume leadership.
United States
FDA gene therapy guidance tightening drives pharmaceutical manufacturers toward automated GMP-grade synthesis platforms with integrated quality analytics. The EPA monitors oligonucleotide manufacturing waste streams under hazardous chemical discharge rules. Boston and San Francisco biotech corridors deploy distributed enzymatic synthesis stations within individual biology departments.
Germany
EMA purity specifications for therapeutic oligonucleotides push contract manufacturers toward industrial-scale solid-phase systems. REACH authorization requirements accelerate phosphoramidite-to-enzymatic transition timelines for pharmaceutical producers. Munich and Heidelberg biotech clusters expand dedicated oligo synthesis facilities serving engineered organism programs.
China
Domestic biotech clusters scale microarray synthesis capacity to serve Asia-Pacific engineered organism demand. NMPA regulatory frameworks shape instrument selection for therapeutic nucleic acid manufacturing. Shanghai and Shenzhen synthetic biology service providers compress cost per base through silicon-based DNA writing technology.
Switzerland
Swissmedic oversight of gene therapy manufacturing imposes stringent purity documentation requirements favoring premium instrument procurement. Closed-loop solvent recovery modules address tightening waste discharge standards. Basel pharmaceutical manufacturing anchors demand for REACH-compliant industrial-scale platforms.
India
Diagnostic networks adopt compact enzymatic synthesizers where cold-chain oligo logistics remain unreliable. CDSCO regulatory pathways for in-vitro diagnostic platforms shape instrument certification requirements. Bangalore and Hyderabad molecular diagnostic labs deploy cartridge-based systems for point-of-care nucleic acid manufacturing.
DNA Synthesizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated conglomerates with reagent-to-instrument workflows anchor pharmaceutical quality-control environments, while specialized disruptors capture synthetic biology volume through novel substrate technologies. The field separates into three strategic archetypes: precision instrumentation conglomerates, silicon-based synthesis specialists, and compact distributed-system providers. Dominant competitive moves include enzymatic platform retooling and biosecurity software integration.
Within the precision instrumentation tier, Danaher and Thermo Fisher Scientific occupy positions defined by integrated reagent supply chains and regulatory compliance documentation. Twist Bioscience exemplifies the silicon-based synthesis specialist archetype, leveraging semiconductor manufacturing approaches to DNA writing. Kilobaser represents compact distributed-system positioning, targeting academic and diagnostic deployment with reduced footprint architectures.
| Leading Market Players |
|---|
| Danaher |
| Twist Bioscience |
| Kilobaser |
| LGC Limited |
| CSBio |
| K&A Labs GmbH |
| DNA Script |
| Biolytic Lab Performance Inc. |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day enzyme inventory cycles at enzymatic platform operators concentrate pricing power among thermostable polymerase fermentation suppliers, while phosphoramidite-dependent manufacturers absorb acetonitrile cost volatility through long-term solvent offtake contracts. This divergence between aqueous-phase and solvent-based supply architectures fragments procurement leverage across customer tiers.
Pricing Analysis
The customization-premium spread separates GMP-grade gene therapy oligonucleotides from research-grade gene fragments by certification tier and purity documentation depth. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 compliance status, integrated analytics bundling, and after-sales service intensity. Cost compression in research-grade synthesis intensifies as Chinese microarray foundries expand silicon-based DNA writing capacity. Academic core facilities exhibit highest price sensitivity, while pharmaceutical manufacturers absorbing FDA gene therapy guidance costs demonstrate lowest sensitivity.
Supply Chain Analysis
Germany and Switzerland anchor precision instrumentation manufacturing for REACH-compliant industrial-scale platforms, while China scales microarray synthesis capacity through semiconductor substrate integration. Thermostable DNA polymerase production concentrates among fermentation specialists in Denmark and the United States. Single-source vulnerability for enzymatic platform operators rests on recombinant enzyme supply concentration. Distribution runs through direct instrument sales for pharmaceutical manufacturers and distributor networks serving academic and diagnostic lab deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power shifts toward synthetic biology startups and contract research organizations consolidating procurement through multi-year platform agreements, fragmenting the historically concentrated academic core facility channel.
For Market Incumbents: Secure enzymatic platform retooling timelines ahead of REACH authorization deadlines for phosphoramidite waste streams. Backward integration into recombinant enzyme supply through captive fermentation capacity or exclusive supply agreements addresses single-source vulnerability threatening production continuity. For New Entrants and Emerging Players: Differentiate on biosecurity software integration for pathogenic sequence screening algorithms becoming procurement prerequisites. Point-of-care nucleic acid manufacturing in India and Southeast Asia represents the most penetrable geography where cold-chain oligo logistics failures create demand for compact cartridge-based systems. Direct sales partnerships with diagnostic network procurement heads accelerate market entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized DNA synthesis divisions lacking synthetic biology application focus. Five-to-ten-year viability hinges on enzymatic technology transition completion and biosecurity compliance infrastructure. Watch FDA gene therapy guidance enforcement intensity as inflection indicator for GMP-grade platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Retooling | REACH authorization deadlines force phosphoramidite-to-aqueous transition timelines for European pharmaceutical manufacturers. |
| Biosecurity Software Integration | Pathogenic sequence screening algorithms become mandatory procurement filters for synthetic biology service providers. |
| Recombinant Enzyme Supply Agreement | Exclusive fermentation partnerships address single-source vulnerability threatening enzymatic platform production continuity. |
| Distributed Diagnostic Deployment | Compact cartridge-based systems penetrate Indian and Southeast Asian markets with unreliable cold-chain logistics. |
| Synthetic Biology Infrastructure Partnership | Munich and Heidelberg biotech clusters expand dedicated oligo synthesis facilities serving engineered organism programs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with synthetic biology startup founders, pharmaceutical manufacturing executives, diagnostic lab procurement managers, and academic core facility directors; and secondary validation through FDA gene therapy guidance documents, EMA submissions, REACH authorization databases, and SEC instrument manufacturer filings. Bottom-up triangulation across segment-level demand estimates and top-down cross-checks against aggregate market sizing anchored quantitative outputs.
Across the analysis window, forecasts model technology transition timelines, regulatory compliance cost absorption, and segment-specific procurement patterns across product type, synthesis chemistry, end-user concentration, and application purity requirements. CAGRs derive from instrument replacement cycle analysis, capacity expansion announcements, and venture capital inflow trajectories into biotech clusters. Enzymatic platform adoption curves and gene therapy manufacturing scale-up rates constitute primary forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA gene therapy guidance enforcement, stable acetonitrile supply continuity, or thermostable polymerase fermentation capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding enzymatic fidelity improvement trajectories and REACH implementation timelines. Recalibration cycles align with material shifts in regulatory enforcement intensity, enzyme supply concentration events, and synthetic biology venture funding velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Difficult-To-Express Proteins Market