
 Europe Zero Trust Security Market | 2026-2036
Europe Zero Trust Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Zero Trust Security Market Analytics
Subscription-based managed detection and response is hardening the commercial model for zero trust delivery across Europe. Palo Alto Networks leverages extensive channel partnerships to dominate enterprise deployments in Germany and France. Cisco Systems anchors its position through deep integration with existing networking infrastructure. Darktrace specializes in AI-native behavioral analytics that differentiates its offering from rules-based competitors.
Zero Trust Security denotes an architectural framework requiring continuous verification of every user, device, and transaction regardless of network location, built on micro-segmentation, least-privilege access controls, and real-time policy enforcement with session timeouts typically under 15 minutes. Its primary purpose is to eliminate implicit trust within IT environments and contain breach lateral movement. Identity Management commands the largest addressable spend as organizations consolidate fragmented credential systems. Cloud-Based deployment is expanding fastest where financial institutions seek to reduce capital intensity. Managed Services captures concentrated margin pools by bundling expertise-scarce security operations.
The EU AI Act, GDPR, and NIS2 Directive collectively mandate demonstrable access controls, audit logging, and incident reporting that directly shape procurement specifications for zero trust platforms. EMA cybersecurity guidelines for pharmaceutical data integrity and ECB operational resilience standards for payment infrastructure further tighten compliance-driven demand. Stakeholders must weigh sovereign cloud requirements against interoperability costs when selecting architecture partners.
Market Dynamics
The EU AI Act and NIS2 Directive are forcing architectural overhauls across European enterprises, compelling security teams to replace perimeter-based models with continuous verification frameworks that satisfy demonstrable access control mandates.
Growth Catalysts
- GDPR audit requirements:Financial institutions in Germany and France must maintain granular access logs and real-time policy enforcement, directly accelerating zero trust procurement cycles.
- Cloud migration velocity:Banks and insurers are retiring on-premise identity systems for cloud-native architectures that embed micro-segmentation by default.
- ECB operational resilience standards:Payment infrastructure operators face mandatory incident reporting deadlines that legacy security models cannot satisfy.
Market Restraints
- Skills scarcity:Zero trust architecture expertise concentrates among a limited pool of certified practitioners, inflating implementation costs and extending deployment timelines.
- Legacy infrastructure drag:Deep integration with existing networking equipment creates technical debt that slows migration in established European enterprises.
- Sovereign cloud fragmentation:National data localization requirements in France, Germany, and Italy force vendors to maintain separate infrastructure instances, raising operational complexity.
Strategic Opportunities
- Managed detection and response bundling:Subscription-based service models capture margin pools from organizations lacking in-house security operations centers.
- AI-native behavioral analytics convergence:Integration of machine learning with identity verification creates differentiated positioning against rules-based competitors.
- Pharmaceutical sector penetration:EMA cybersecurity guidelines for clinical data integrity create compliance-driven demand among drug manufacturers in Switzerland and the Netherlands.
Industry Challenges
- Micro-segmentation complexity:Financial services teams struggle to map thousands of application dependencies for least-privilege policy design without disrupting operations.
- Certificate lifecycle management:Short-session timeout requirements under 15 minutes demand automated credential rotation that existing identity systems cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Zero Trust Security Market |
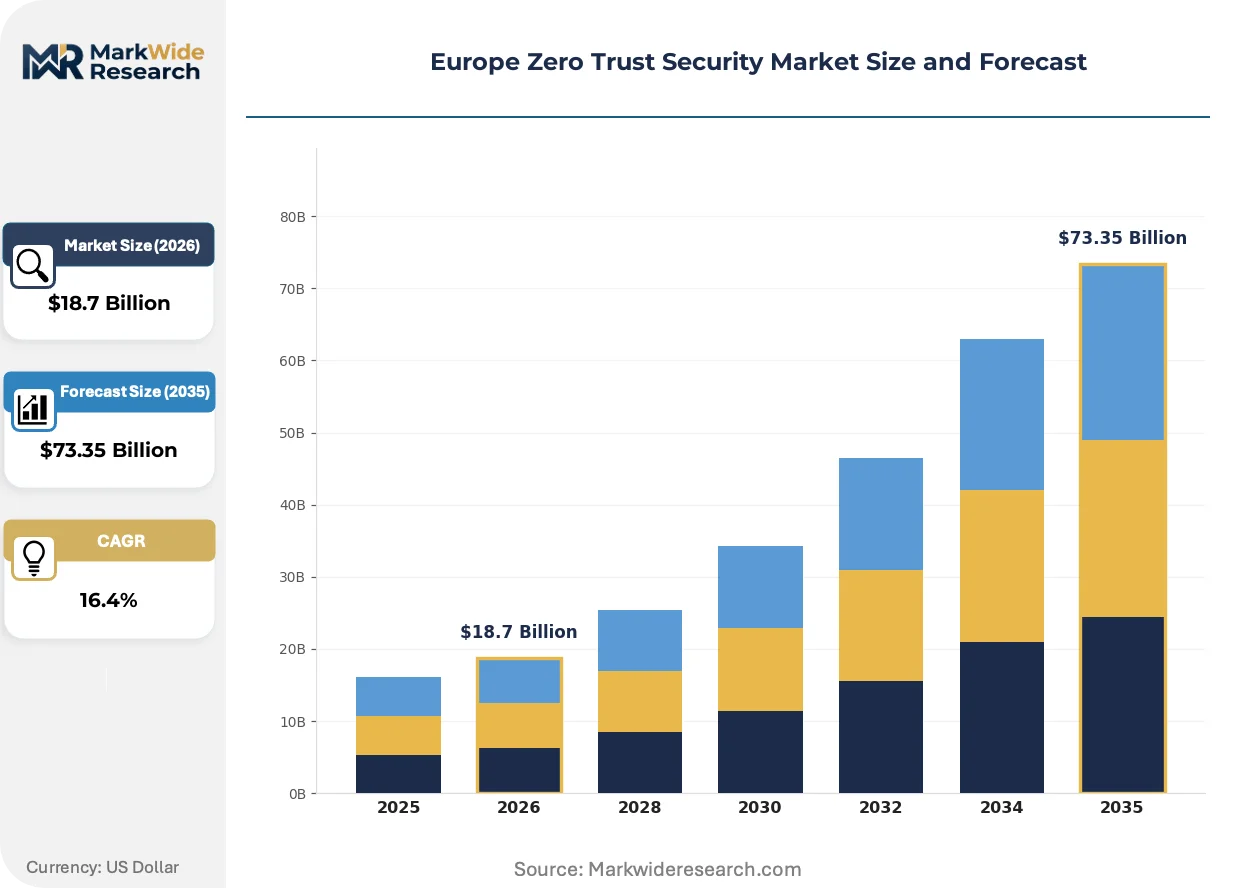
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Identity Management, Network Security, Endpoint Security, Data Protection Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Financial Institutions, Government, Manufacturing Technology: Multi-Factor Authentication, Encryption, Behavioral Analytics, Threat Intelligence |
| Companies Covered | Cisco Systems, Palo Alto Networks, Fortinet, Microsoft Corporation, IBM Corporation, Check Point Software Technologies, Zscaler, Thales Group, Darktrace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Zero Trust Security Market Evolving Landscape
Artificial intelligence is rewiring how European enterprises detect and respond to identity-based threats, shifting competitive advantage toward platforms that automate policy enforcement without human intervention.
AI-native behavioral analytics is rewriting threat detection paradigms by establishing baseline user activity patterns and flagging anomalies in real time. German automotive suppliers and French pharmaceutical groups are deploying these systems at scale. The technology is compressing dwell time for credential-based attacks from months to minutes.
NIS2 Directive enforcement deadlines are mandating sector-specific incident reporting protocols that legacy security architectures cannot accommodate. Critical infrastructure operators in energy and transport must demonstrate continuous verification capabilities by 2025. Dutch water utilities and Spanish telecom providers are accelerating procurement to meet these obligations.
Subscription-based managed security services are displacing capital-intensive appliance purchases among mid-market European enterprises. Channel partners in the United Kingdom and Scandinavia are building recurring revenue streams around 24/7 security operations. This shift is most visible among regional banks lacking dedicated cybersecurity teams.
Europe Zero Trust Security Market Segmentation
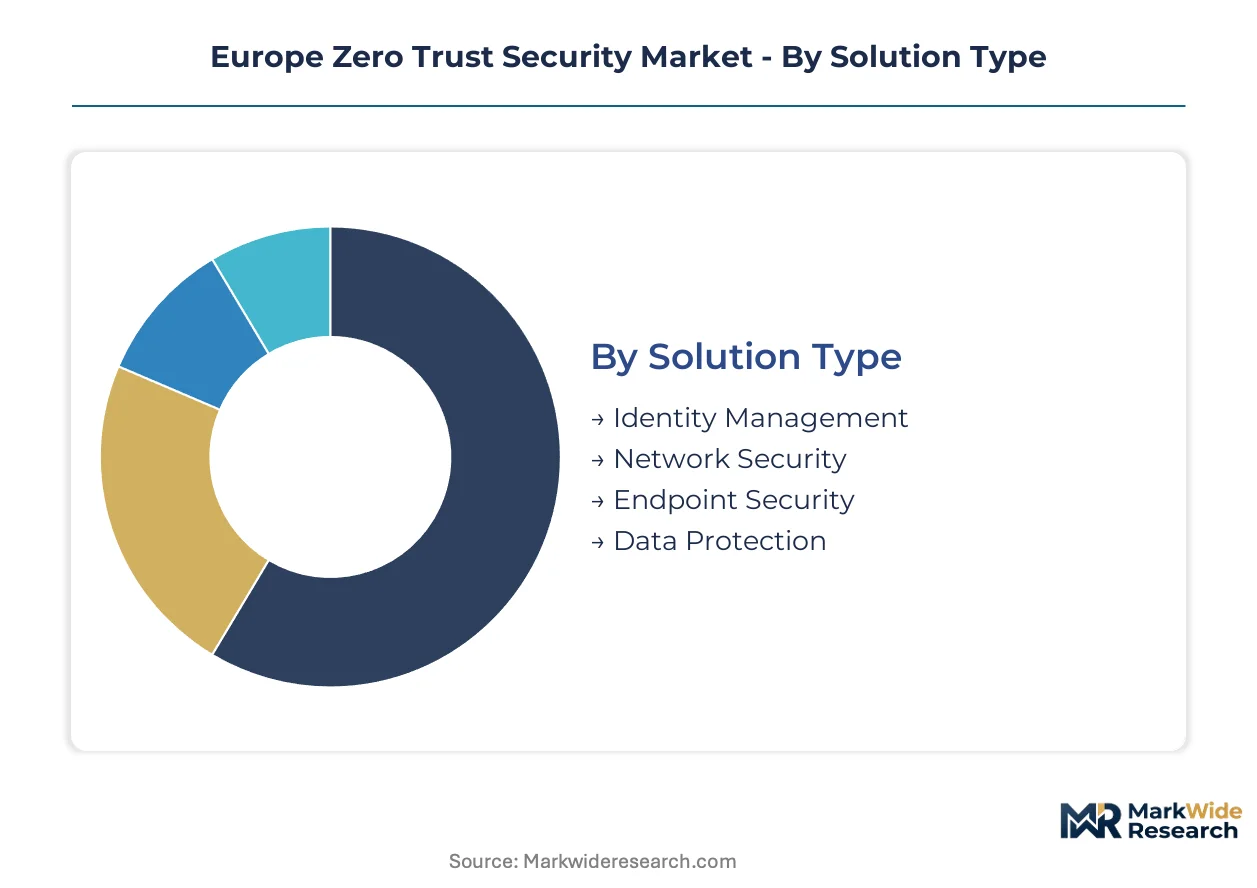
Zero trust procurement patterns across Europe diverge sharply by organizational maturity, regulatory exposure, and existing infrastructure debt. Buyers prioritize segments that compress compliance timelines while containing integration complexity.
Solution Type:
Deployment priorities separate enterprises consolidating fragmented credential systems from those hardening network perimeters.
- Identity Management:Centralized platforms governing user authentication, privilege assignment, and session lifecycle management across heterogeneous application estates. German financial institutions and French healthcare networks are consolidating legacy Active Directory instances to satisfy GDPR demonstrable access mandates.
- Network Security:Micro-segmentation controllers and software-defined perimeters that enforce least-privilege traffic policies between workloads. Dutch energy utilities and Spanish telecom operators are deploying these under NIS2 Directive pressure to contain lateral breach movement.
- Endpoint Security:Device trust verification and continuous posture assessment for roaming corporate assets.
- Data Protection:Classification-aware encryption and access controls for regulated data repositories.
Volume sits with Identity Management; growth tilts toward Network Security.
Deployment Model:
Capital intensity preferences and in-house security operations maturity determine architecture selection.
- Cloud-Based:Native zero trust stacks delivered via SaaS with embedded micro-segmentation and automated policy propagation. Regional banks in Scandinavia and the United Kingdom are retiring on-premise identity appliances to reduce fixed infrastructure commitments.
- Managed Services:Subscription-based security operations centers providing 24/7 monitoring, incident response, and compliance reporting. Mid-market manufacturers in Italy and Belgium are adopting these bundles to compensate for acute cybersecurity skills scarcity.
- On-Premises:Self-hosted control planes for organizations with sovereign data requirements or deep legacy integration.
- Hybrid:Split architectures preserving sensitive authentication flows on-premise while extending policy enforcement to cloud workloads.
On-Premises retains installed base dominance; Managed Services climbs the fastest.
End User:
Sector-specific regulatory deadlines and breach consequence severity shape investment urgency.
- Financial Institutions:Banks, insurers, and payment processors facing ECB operational resilience standards and granular audit logging mandates. German and French institutions are replacing perimeter VPNs with continuous verification frameworks to satisfy incident reporting deadlines.
- Government:National and regional agencies subject to NIS2 critical infrastructure designations and sovereign cloud requirements. Italian and Polish public sector bodies are accelerating procurement to meet continuous verification demonstration obligations.
- Healthcare:Hospital networks and pharmaceutical manufacturers balancing EMA data integrity guidelines against clinical workflow continuity.
- Manufacturing:Industrial operators securing operational technology environments against supply chain-targeted intrusion campaigns.
Financial Institutions command current spend; Government expands most quickly.
Technology:
Automation depth and threat detection latency separate competitive offerings.
- Behavioral Analytics:Machine learning systems establishing baseline user activity patterns and flagging credential misuse in real time. French pharmaceutical groups and German automotive suppliers are deploying these to compress dwell time for compromised accounts.
- Multi-Factor Authentication:Adaptive step-up verification combining biometrics, hardware tokens, and contextual risk signals. Healthcare networks in Switzerland and the Netherlands are standardizing FIDO2-compliant implementations to satisfy EMA cybersecurity guidelines.
- Encryption:Data-at-rest and in-transit protection with centralized key lifecycle management.
- Threat Intelligence:External indicator feeds and adversary pattern recognition integrated into policy enforcement decisions.
Multi-Factor Authentication saturates baseline deployments; Behavioral Analytics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deployment activity concentrates in Western European financial centers while Eastern European governments accelerate procurement to satisfy NIS2 deadlines. Production of zero trust architecture expertise clusters in Germany, France, and the United Kingdom, with implementation services radiating outward.
Germany
Frankfurt's banking concentration and Stuttgart's automotive supplier networks drive identity management consolidation. The Bundesbank's operational resilience guidelines mandate continuous verification for payment infrastructure operators. Bavarian industrial manufacturers are replacing perimeter VPNs with micro-segmentation controllers to satisfy audit logging requirements.
France
Parisian financial institutions and Lyon-based pharmaceutical groups anchor demand for AI-native behavioral analytics. ANSSI's certification framework shapes procurement specifications for critical infrastructure operators. Île-de-France healthcare networks are deploying FIDO2-compliant multi-factor authentication to satisfy CNIL data protection mandates.
United Kingdom
London's fintech density and Edinburgh's insurance sector propel cloud-native zero trust adoption. The Bank of England's operational resilience standards impose incident reporting deadlines that legacy architectures cannot meet. Manchester-based managed security service providers are bundling 24/7 monitoring for regional banks lacking in-house security operations centers.
Netherlands
Amsterdam's payment processing hub and Rotterdam port logistics operators require micro-segmentation for supply chain security. The Dutch Authority for Digital Infrastructure enforces NIS2-aligned continuous verification mandates for critical sectors. Eindhoven's high-tech manufacturing cluster is deploying endpoint trust verification for operational technology environments.
Italy
Milan's banking consortium and Turin automotive manufacturers are accelerating zero trust procurement ahead of NIS2 enforcement deadlines. The National Cybersecurity Agency's guidelines require demonstrable access controls for critical infrastructure operators. Rome-based government agencies are adopting sovereign cloud architectures to satisfy data localization requirements.
Europe Zero Trust Security Market Competitive Landscape
Top-tier vendors anchor enterprise deployments, while mid-market specialists capture recurring revenue through managed service bundles. The vendor base stratifies across three tiers: full-stack platform providers, network-integrated incumbents, and AI-native specialists. Strategic archetypes include channel-heavy distribution models, deep infrastructure integration plays, and behavioral analytics differentiation. Dominant competitive moves encompass subscription-based service packaging and sovereign cloud infrastructure expansion.
Within the full-stack platform tier, Palo Alto Networks and Cisco Systems occupy positions shaped by channel depth and infrastructure integration respectively. Darktrace exemplifies the AI-native behavioral analytics archetype that differentiates against rules-based competitors. These three anchors represent distinct competitive vectors: Palo Alto Networks through extensive partner ecosystems in Germany and France, Cisco Systems through embedded networking relationships, and Darktrace through machine learning-based threat detection.
| Leading Market Players |
|---|
| Cisco Systems |
| Palo Alto Networks |
| Fortinet |
| Microsoft Corporation |
| IBM Corporation |
| Check Point Software Technologies |
| Zscaler |
| Thales Group |
| Darktrace |
| Others |
Value Network & Pricing Analysis
Silicon wafer pricing indices cascade through European zero trust hardware manufacturing, compressing margins on appliance-based deployments while subscription SaaS models absorb volatility through recurring revenue structures. German system integrators and French managed service providers pass component cost fluctuations into tiered service bundles, separating premium consulting engagements from standardized monitoring packages.
Pricing Analysis
Margin tightening in on-premise appliance tiers reflects NAND flash memory and specialized processor cost volatility from Asian foundries. Three-tier pricing structure across premium consulting, standard platform subscriptions, and economy self-service tiers separates buyers by in-house security operations maturity. Cost-down pressure on hardware-dependent deployments accelerates as Dutch and Belgian mid-market enterprises shift capex to opex models. Financial institutions in Frankfurt and Paris exhibit lowest price sensitivity due to ECB-mandated operational resilience deadlines, while regional Italian manufacturers negotiate hardest on per-seat licensing.
Supply Chain Analysis
Specialized encryption hardware supply rests on semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with European packaging and testing operations in Germany and the Netherlands. Cloud-native zero trust stacks draw from hyperscaler infrastructure anchored in Ireland, Germany, and Sweden under GDPR data localization requirements. Single-source vulnerability in hardware security module production creates procurement risk for sovereign cloud deployments. Distribution runs through certified channel partners in London, Frankfurt, and Paris who bundle implementation services with platform licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European zero trust security is consolidating around full-stack platform providers as NIS2 compliance complexity eliminates point-solution vendors lacking managed service capabilities. Architectural integration requirements and skills scarcity are forcing mid-tier security software vendors toward acquisition or exit.
For Market Incumbents: Lock in enterprise relationships through sovereign cloud infrastructure expansion in Germany, France, and Italy, addressing national data localization mandates that block pure-cloud competitors. Deepen channel certification programs to capture scarce zero trust architecture talent before emerging AI-native specialists can scale delivery capacity. Bundle managed detection and response services to convert perpetual license customers into recurring revenue streams before subscription fatigue sets in among mid-market buyers. For New Entrants and Emerging Players: Enter via pharmaceutical and healthcare verticals in Switzerland and the Netherlands where EMA cybersecurity guidelines create compliance-driven demand underserved by horizontal platforms. Target mid-market Italian and Belgian manufacturers lacking dedicated security operations centers, offering pre-configured managed service bundles that eliminate implementation complexity. Position around AI-native behavioral analytics differentiation against rules-based incumbents in French and German automotive supplier networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed security service providers with established 24/7 operations centers in the United Kingdom and Scandinavia, where recurring revenue visibility supports valuation resilience. Long-term viability centers on platforms demonstrating automated policy enforcement without human intervention, compressing operational costs as skills scarcity intensifies. Watch NIS2 enforcement deadline adherence rates among Italian and Polish critical infrastructure operators as inflection indicator for compliance-driven procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding zero trust controls directly into existing Cisco networking infrastructure accelerates German enterprise procurement cycles. |
| Managed Service Bundling | 24/7 security operations subscriptions capture margin pools from regional UK banks lacking in-house cybersecurity teams. |
| Sovereign Cloud Expansion | France and Germany data residency instances satisfy ANSSI and BSI certification requirements blocking pure-cloud competitors. |
| AI-Native Behavioral Analytics | Machine learning threat detection differentiates against rules-based platforms in French pharmaceutical group deployments. |
| Channel Certification Programs | Scarce zero trust architecture expertise concentrates among certified practitioners in Palo Alto Networks partner ecosystems. |
Research Methodology
Multi-period observation of NIS2 compliance deadline adherence, GDPR audit enforcement patterns, and cloud migration velocity among European financial institutions anchored the trend analysis, supplemented by interviews with CISOs at German and French banks, security procurement officers at Dutch energy utilities, channel partners in the United Kingdom, and managed service providers in Italy and Belgium. Secondary validation drew from ECB operational resilience guideline publications, ENISA threat landscape reports, ANSSI certification frameworks, and hyperscaler European region capex disclosures. Bottom-up deployment sizing across solution types and top-down macroeconomic scenario weighting were triangulated against vendor revenue segmentation.
Segment-weighting approaches distributed total addressable spend across identity management, network security, endpoint security, and data protection solution types, with cross-cutting dimensions for cloud-based versus on-premises deployment models and financial institution versus government versus healthcare end-user categories. CAGRs were derived from regression analysis of historical procurement velocity against regulatory deadline proximity, with inputs including NIS2 enforcement timeline acceleration, ECB incident reporting mandate compliance rates, and EMA pharmaceutical cybersecurity guideline adoption curves across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sovereign cloud fragmentation intensification or accelerated AI-native platform disruption. Assumptions reflect current regulatory enforcement posture and vendor delivery capacity constraints. A small set of named triggers—including NIS2 deadline extensions, major breach disclosures, and hyperscaler European infrastructure investment shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
North America Cyber Security Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Mainframe Security Market
Cybersecurity
Cloud Endpoint Protection Market
Cybersecurity
Data Protection Market
Cybersecurity
Philippines Cybersecurity Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Sweden Cybersecurity Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
Global Mobile Anti Malware Market