
 Disinfection Cap Market | 2026-2036
Disinfection Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfection Cap Market Intelligence
ISO 80369-7 compliance tier is collapsing the gap between premium disinfection caps and commodity alternatives, forcing manufacturers to recertify entire product lines. ICU Medical leverages backward integration into polymer compounding to sustain margin control across its cap portfolio. BD anchors North American hospital supply contracts through dense GPO relationships. B. Braun Melsungen AG dominates European manufacturing with dedicated cleanroom capacity for silicone-based caps.
A disinfection cap is a sealed, threaded or luer-activated closure containing antimicrobial agents—typically isopropyl alcohol or chlorhexidine-impregnated foam—that disinfects needleless connector hubs upon attachment, engineered to maintain sterility for up to seven days per activation. Polypropylene formulations lead unit volume due to cost-efficient injection molding compatibility and broad chemical resistance, while silicone variants command premium positioning in long-dwell catheter applications where material biocompatibility is non-negotiable. Single-use caps capture the dominant revenue share as hospitals abandon reusable protocols to eliminate cross-contamination liability, whereas cap accessories represent the fastest-expanding margin pool as manufacturers bundle disinfection caps with complementary needleless connectors.
FDA 510(k) clearance requirements govern device-level antimicrobial claims in the United States, while the EU MDR's tightened biocompatibility testing under ISO 10993 is extending certification timelines for European market entrants. EPA regulations on antimicrobial pesticide residues intersect with state-level hospital accreditation standards to create layered compliance obligations. Stakeholders must monitor evolving connector standard harmonization between ISO 80369 and proprietary legacy designs to anticipate which platform investments will retain contractual relevance.
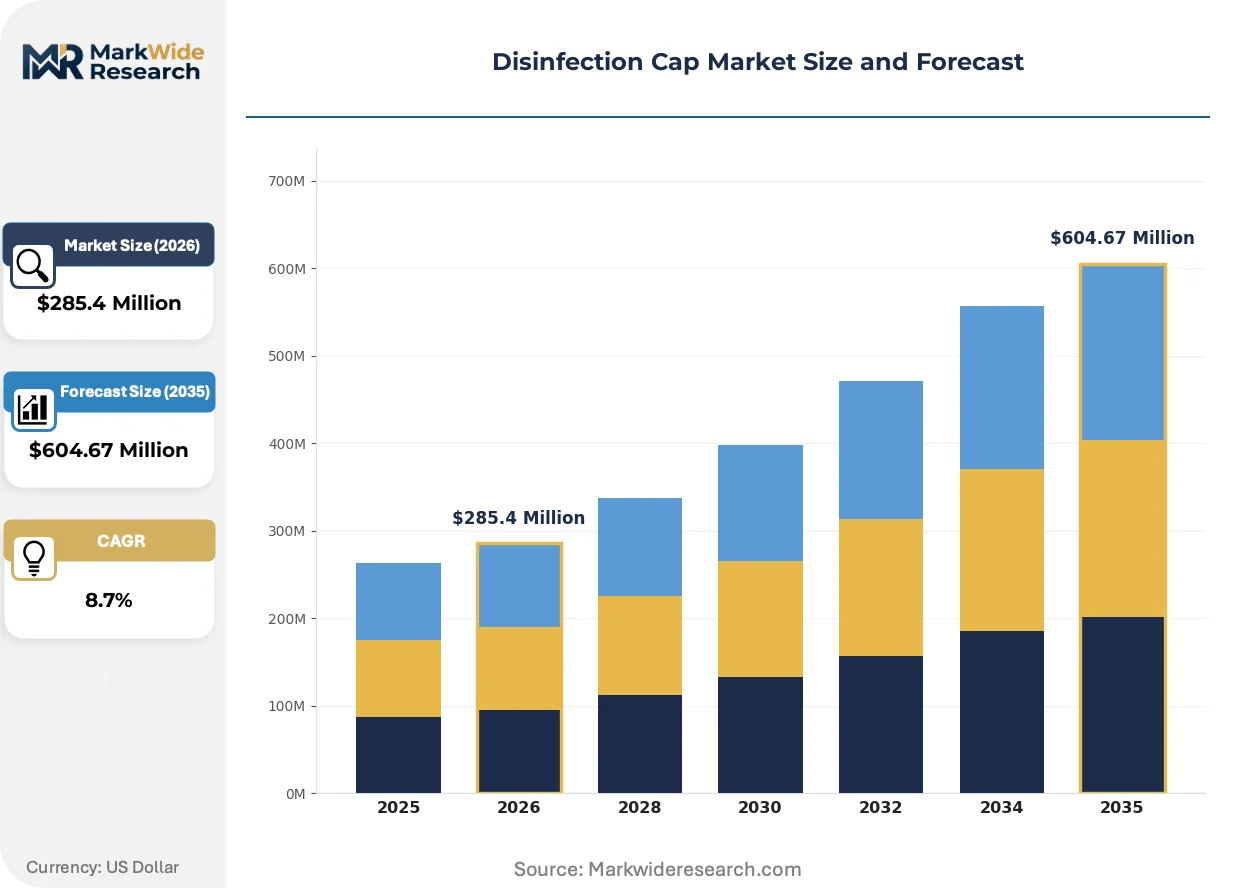
Market Dynamics
ISO 80369-7 compliance mandates are compressing product differentiation and forcing manufacturers to recertify entire portfolios, collapsing the historical gap between premium and commodity disinfection caps.
Growth Catalysts
- Hospital-acquired infection protocols:Acute care facilities in the United States are standardizing needleless connector disinfection as core infection control infrastructure, mandating cap attachment for every vascular access device.
- FDA 510(k) pathway clarity:Updated antimicrobial device guidance is streamlining validation requirements for alcohol-impregnated foam formulations, accelerating product iterations.
- Silicone biocompatibility premium:Long-dwell catheter applications are driving material substitution toward medical-grade silicone variants in oncology and parenteral nutrition settings.
Market Restraints
- Polypropylene feedstock volatility:Injection-molding resin costs fluctuate with propylene monomer supply from Gulf Coast petrochemical complexes, squeezing margin on standard-cap portfolios.
- EU MDR certification timelines:Extended ISO 10993 biocompatibility testing under the Medical Device Regulation is delaying European market entry for new entrants by 12-18 months.
- Chlorhexidine gluconate substitution limits:EPA antimicrobial pesticide residue thresholds restrict alcohol-chlorhexidine combination formulations in certain state hospital accreditation frameworks.
Strategic Opportunities
- Bundle economics with needleless connectors:Cap-accessory pairings represent margin expansion as manufacturers integrate disinfection caps into connector supply contracts.
- Seven-day dwell protocol extension:Extended sterility maintenance claims open replacement of 72-hour cap protocols in home infusion settings.
- Cleanroom capacity scarcity:Dedicated silicone molding infrastructure in Central Europe creates acquisition targets for manufacturers seeking European manufacturing footprint.
Industry Challenges
- ISO 80369-7 recertification complexity:Legacy luer-activated designs require engineering redesign to meet dimensional tolerances, consuming R&D resources.
- Antimicrobial claim validation:FDA 510(k) substantiation for novel active agents demands clinical evidence generation that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfection Cap Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Caps, Reusable Caps, Cap Accessories, Specialty Caps Material: Polyethylene, Polypropylene, Silicone, PVC Application: Medical Equipment, Pharmaceutical Bottles, Laboratory Use, Household Products End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Home Users |
| Companies Covered | ICU Medical, BD (Becton, Dickinson and Company), 3M Company, B. Braun Melsungen AG, Merit Medical Systems, Baxter International, Agilent Technologies, JCM MED, Eloquest Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfection Cap Market Strategic Shifts & Innovations
Antimicrobial formulation science and connector standardization are converging to redefine product architectures, with material selection and regulatory positioning becoming the primary axes of competition.
Luer-activated foam delivery mechanisms are fragmenting the interface between cap and needleless connector. These devices deploy alcohol-saturated foam upon thread engagement, eliminating manual hub scrubbing. Oncology and home infusion providers are adopting these systems fastest. The technology is fragmenting procurement decisions away from standalone caps toward integrated connector-cap systems.
EU MDR biocompatibility testing expansion is extending certification burdens for European market access. The regulation mandates cytotoxicity and sensitization assays under ISO 10993 that exceed prior CE-mark requirements. Small and mid-sized manufacturers are responding by withdrawing marginal SKUs rather than absorbing retesting costs, concentrating European supply among dedicated cleanroom operators.
Hospital supply chain rationalization is compressing vendor counts for needleless connector accessories. Materials management departments are consolidating disinfection cap procurement into existing GPO contracts for vascular access devices, displacing independent cap distributors. This consolidation is most visible in United States integrated delivery networks where standardization committees mandate single-source connector platforms.
Disinfection Cap Market Segmentation
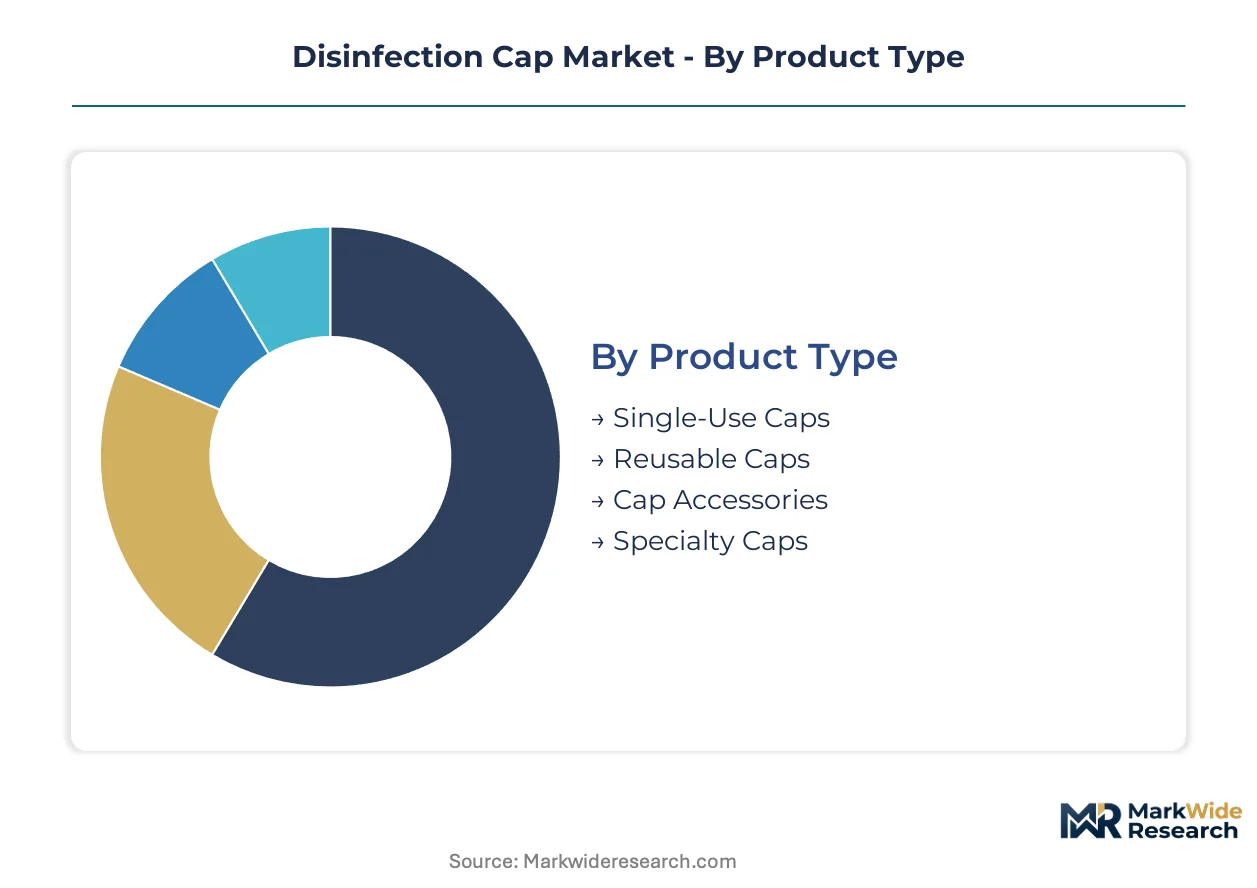
Disinfection cap procurement decisions fragment across material specifications, sterility protocols, and end-use environments. Each segment carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
FDA 510(k) clearance pathways diverge sharply between single-use and reusable formats, with antimicrobial claim substantiation driving validation costs.
- Single-Use Caps:These sealed, luer-activated closures impregnated with isopropyl alcohol or chlorhexidine-impregnated foam eliminate cross-contamination liability. Acute care facilities in the United States mandate attachment for every vascular access device under intensifying hospital-acquired infection protocols.
- Cap Accessories:Complementary needleless connectors and extension sets bundled with disinfection caps expand margin pools as manufacturers integrate into vascular access supply contracts. Home infusion providers are adopting these pairings fastest as seven-day dwell protocols replace 72-hour replacement cycles.
- Reusable Caps:Autoclavable designs with replaceable antimicrobial inserts serve cost-constrained outpatient settings where sterilization infrastructure exists.
- Specialty Caps:Oncology-specific variants with enhanced chlorhexidine concentrations address immunocompromised patient requirements.
Single-use caps handle the majority of throughput; cap accessories are expanding most quickly on share.
Material:
Cost tiers stratify sharply between commodity thermoplastics and medical-grade silicone, with biocompatibility certification extending lead times for premium grades.
- Polypropylene:Injection-molding compatibility and broad chemical resistance dominate unit volume. Gulf Coast propylene monomer supply volatility squeezes margin on standard-cap portfolios.
- Silicone:Medical-grade variants command premium positioning in long-dwell catheter applications where material biocompatibility is non-negotiable. Oncology and parenteral nutrition settings in Germany and Switzerland drive substitution toward dedicated cleanroom-molded silicone.
- Polyethylene:Lower-density formulations serve cost-sensitive laboratory and household segments with reduced chemical resistance requirements.
- PVC:Legacy compatibility with existing connector infrastructure sustains niche demand in pharmaceutical bottle sealing applications.
Polypropylene captures the volume base; silicone posts the steepest expansion trajectory.
Application:
End-use environment dictates sterility maintenance duration and antimicrobial formulation intensity, with clinical settings imposing the most stringent validation requirements.
- Medical Equipment:Needleless connector hubs for vascular access devices require seven-day sterility maintenance per activation. FDA 510(k) antimicrobial device guidance streamlines validation for alcohol-impregnated foam formulations in this segment.
- Pharmaceutical Bottles:Multi-dose vial sealing applications demand EPA-compliant antimicrobial pesticide residue thresholds that restrict alcohol-chlorhexidine combinations in certain state hospital accreditation frameworks.
- Laboratory Use:Cell culture and analytical equipment protection prioritizes material inertness over extended antimicrobial persistence.
- Household Products:Consumer-grade disinfection caps for home medical devices face reduced regulatory scrutiny but price elasticity constraints.
Medical equipment absorbs the dominant procurement volume; pharmaceutical bottles are climbing the fastest on specification upgrades.
End User:
Customer scale determines contract structure, with integrated delivery networks consolidating vendor counts through GPO relationships.
- Hospitals:Materials management departments standardize needleless connector platforms across catheter protocols, displacing independent cap distributors. United States health systems are mandating single-source connector platforms through standardization committees.
- Pharmaceutical Companies:Aseptic manufacturing lines for injectable drug production require validated cap-connector systems with documented sterility assurance levels.
- Research Laboratories:Academic and commercial R&D facilities prioritize flexibility over standardization, sustaining fragmented procurement patterns.
- Home Users:Home infusion therapy expansion creates demand for extended-dwell protocols with simplified attachment mechanisms.
Hospitals command the contractual leverage; pharmaceutical companies are gaining share fastest on manufacturing compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports silicone-based disinfection caps to Swiss and Austrian hospital networks, establishing a Central European manufacturing corridor that supplies premium-grade products for long-dwell catheter applications.
United States
Acute care facilities in Texas and Florida are mandating needleless connector disinfection protocols under intensifying hospital-acquired infection control standards. FDA 510(k) clearance requirements for antimicrobial device claims are streamlining validation pathways for alcohol-impregnated foam formulations. The Greater Boston medical device cluster hosts contract manufacturers serving integrated delivery networks standardizing single-source connector platforms.
Germany
Oncology centers in Baden-Württemberg and Bavaria are driving substitution toward medical-grade silicone caps for parenteral nutrition applications. EU MDR biocompatibility testing under ISO 10993 is extending certification timelines for new market entrants by 12-18 months. The Tuttlingen surgical instrument corridor hosts dedicated cleanroom capacity for silicone molding that supplies Austrian and Swiss hospital systems.
Switzerland
Swissmedic oversight of medical device biocompatibility is reinforcing premium positioning for silicone variants in immunocompromised patient settings. Basel-based pharmaceutical manufacturing lines require validated cap-connector systems with documented sterility assurance levels for aseptic injectable production. The Zurich medical technology cluster concentrates R&D resources for seven-day dwell protocol extensions.
China
NMPA medical device registration requirements are reshaping import substitution dynamics for polypropylene-based standard caps. Yangtze River Delta injection molders are expanding capacity to serve domestic hospital procurement consolidation under centralized volume-based purchasing schemes. Shanghai-based distributors are bundling disinfection caps with complementary needleless connectors for provincial health system contracts.
Japan
PMDA quality management system inspections are extending lead times for foreign manufacturer registration in the vascular access device segment. Kansai region home infusion providers are adopting extended-dwell protocols with simplified attachment mechanisms for aging patient populations. Osaka-based polymer compounders supply medical-grade polypropylene formulations meeting JIS biocompatibility standards.
Disinfection Cap Market Key Industry Players
Listed leaders compete with private specialists across regulatory certification resources, creating a tiered structure where scale-driven public companies anchor GPO contracts while family-owned manufacturers retain niche premium positioning. The vendor base concentrates among three strategic archetypes: diversified medical device conglomerates with backward integration into polymer compounding, pure-play vascular access specialists with dedicated cleanroom infrastructure, and regional fabricators serving localized hospital procurement networks. Competitive dynamics center on ISO 80369-7 recertification speed and bundle economics with needleless connector portfolios.
Within the diversified conglomerate tier, ICU Medical and BD exemplify scale-driven positioning through dense Group Purchasing Organization relationships and captive supply chain control. B. Braun Melsungen AG occupies a distinct European manufacturing position with dedicated cleanroom capacity for silicone-based caps serving German, Swiss, and Austrian hospital networks. These three entities represent contrasting geographic anchoring strategies—United States-centric contract consolidation, European premium manufacturing, and diversified global presence—while competing on regulatory certification breadth rather than unit cost alone.
| Leading Market Players |
|---|
| ICU Medical |
| BD (Becton, Dickinson and Company) |
| 3M Company |
| B. Braun Melsungen AG |
| Merit Medical Systems |
| Baxter International |
| Agilent Technologies |
| JCM MED |
| Eloquest Healthcare |
| Others |
Cost & Logistics Intelligence
Ninety-day EU MDR certification timelines for silicone-based caps concentrate pricing power among German cleanroom operators while compressing margins on polypropylene alternatives sourced from volatile Gulf Coast petrochemical corridors. This lead-time asymmetry between premium and commodity tiers shapes how manufacturers allocate polymer compounding capacity and negotiate hospital supply contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across ISO 80369-7 certification grade, silicone versus polypropylene material tier, and volume scale commitments. Price differentiation hinges on FDA 510(k) clearance status and dedicated cleanroom manufacturing pedigree versus standard injection-molding output. Cost compression in polypropylene standard caps is intensifying because propylene monomer feedstock volatility from Gulf Coast complexes squeezes margin on non-premium portfolios. Research laboratories and outpatient clinics exhibit highest price sensitivity, while German oncology centers and Swiss pharmaceutical manufacturing lines demonstrate lowest sensitivity due to biocompatibility non-negotiability.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement through Group Purchasing Organization contracts, though silicone cap buyers maintain strategic stockpiles against EU MDR certification bottlenecks. Manufacturing concentrates in Germany, the United States, and China, with German Tuttlingen corridor facilities feeding Swiss and Austrian networks. Raw material dependencies rest on propylene monomer from Gulf Coast petrochemical complexes, medical-grade silicone from specialized European compounders, and isopropyl alcohol from industrial chemical processors. Single-source vulnerability in FDA-registered cleanroom capacity for silicone molding creates supply chain risk. Distribution runs through GPO-anchored hospital supply contracts in the United States and direct manufacturer relationships with European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disinfection cap procurement is hardening into a service-attach opportunity as seven-day dwell protocol extensions and bundled needleless connector implementations expand recurring revenue streams faster than standalone hardware transactions.
For Market Incumbents: Shield market position by accelerating backward integration into polymer compounding to offset propylene monomer volatility squeezing standard-cap margins, while simultaneously locking hospital integrated delivery networks into single-source connector platform contracts that displace independent cap distributors. ISO 80369-7 recertification speed serves as the critical defensive lever against emerging cleanroom operators in Central Europe. For New Entrants and Emerging Players: Extended-dwell home infusion protocol gaps where incumbents under-serve create entry points for simplified attachment mechanisms targeting aging patient populations in Japan's Kansai region and United States Medicare-funded home health networks. Penetrate the cap accessories segment fastest by bundling disinfection caps with complementary needleless connectors for provincial Chinese health system contracts, leveraging Yangtze River Delta molding capacity to undercut established GPO pricing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because FDA 510(k) and EU MDR certification burdens extend development cycles and consolidate supply among cleanroom-capable operators with demonstrated biocompatibility testing resources. Target acquisition candidates with dedicated silicone molding infrastructure in Germany's Tuttlingen corridor and existing Swissmedic or FDA registrations. Monitor NMPA import substitution progress in China as the inflection signal for when domestic Yangtze River Delta capacity will displace foreign supply in provincial volume-based purchasing schemes.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | ISO 10993 biocompatibility testing investments secure 12-18 month lead times over new entrants in German hospital networks. |
| Backward Integration into Polymer Compounding | Captive propylene monomer supply insulates margin control from Gulf Coast petrochemical volatility in standard-cap portfolios. |
| Seven-Day Dwell Protocol Extension | Extended sterility claims open home infusion replacement of 72-hour cap cycles in Medicare-funded patient populations. |
| Hospital System Partnership | Single-source connector platform mandates through United States integrated delivery network standardization committees displace independent distributors. |
| Cleanroom Capacity Acquisition | Dedicated silicone molding infrastructure in Central Europe creates defensible supply position for oncology and parenteral nutrition applications. |
Research Approach
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors and secondary validation through FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and customs trade data anchors the qualitative findings. Bottom-up demand modeling from catheter protocol standardization trends triangulates against top-down market sizing from vascular access device production estimates.
Sensitivity analysis across material substitution scenarios, certification timeline variations, and hospital consolidation patterns informs the analytical framework. Segmentation dimensions span product type, material grade, application environment, and end-user scale across the modeling period. CAGRs derive from weighted average of historical protocol adoption curves and projected infection control mandate expansion. Forecast inputs incorporate propylene monomer price band assumptions and EU MDR implementation pace.
Underlying assumptions cover sustained hospital-acquired infection protocol intensification and ISO 80369-7 standard harmonization, with deviation risk concentrated in EPA antimicrobial pesticide residue threshold adjustments and state-level hospital accreditation framework fragmentation. Revision becomes warranted when NMPA import substitution progress or EU MDR certification backlog duration crosses material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Warehouse Fumigants Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Global Animal Disinfectants Market