
 Disinfecting Wipes Market | 2026-2036
Disinfecting Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfecting Wipes Market Analytics
Janitorial labor shortages across North American healthcare and commercial cleaning sectors is redrawing how facilities source and deploy surface disinfection products. The Clorox Company leverages its EPA-registered portfolio and retail shelf dominance to sustain volume leadership in consumer and institutional channels. Kimberly-Clark Corporation anchors its position through healthcare-focused private-label and branded wipe lines with established hospital group purchasing organization contracts. Reckitt Benckiser Group PLC competes on clinical credibility, extending Lysol brand equity into professional settings through expanded kill-claim certifications.
Disinfecting wipes are non-woven or paper substrates impregnated with quaternary ammonium compounds, alcohol blends, or other EPA-registered active ingredients, manufactured through saturation and sealing processes to maintain solution stability and substrate integrity through stated shelf lives; their primary purpose is rapid surface decontamination in settings where cross-contamination risks demand documented kill logs. Alcohol-based formulations lead in healthcare application due to fast evaporation and compatibility with electronic medical equipment, while biodegradable material substrates represent the fastest-growing segment as institutional procurement policies embed plastic-reduction mandates. Multi-surface product types occupy the broadest margin pool by spanning household, automotive, and commercial channels without segment-specific reformulation costs.
The EPA regulates disinfecting wipes as pesticides under FIFRA, requiring substantiated efficacy claims and label compliance that shapes both product development timelines and market access barriers for new entrants. The EU Biocidal Products Regulation and REACH framework govern active substance approval and chemical safety documentation, creating divergent compliance pathways that fragment formulation strategies across Atlantic markets. Stakeholders must monitor pending EPA guidance on per- and polyfluoroalkyl substance contamination in non-woven substrates, as material sourcing decisions made now will determine eligibility for federal and state procurement contracts under tightening chemical disclosure rules.
Market Dynamics
Hospital-grade formulation mandates and janitorial labor compression are forcing facilities to consolidate wipe suppliers around EPA-registered portfolios with documented kill logs. Procurement officers now prioritize pre-saturated substrates that reduce mixing errors and surface contact time variability.
Growth Catalysts
- EPA Emerging Viral Pathogen Claims Framework:Manufacturers submitting data under this pathway gain expedited label expansion for novel pathogens, accelerating hospital adoption cycles.
- Quaternary ammonium compound saturation advances:Improved substrate binding chemistry extends solution stability, reducing waste from dried-out canisters in extended-stay healthcare settings.
- India:Central government hospital procurement standardization under the National Health Mission is consolidating fragmented state-level purchasing into volume contracts.
Market Restraints
- Isopropyl alcohol feedstock volatility:Refinery output fluctuations and bioethanol competition constrain consistent input pricing for alcohol-based formulations.
- Non-woven substrate concentration:Three suppliers control over 70% of spunlace capacity for medical-grade wipes, creating bottleneck risk.
- EU Biocidal Products Regulation active substance review timelines:Pending substance-specific decisions on quaternary ammonium compounds are freezing formulation investments.
Strategic Opportunities
- Brazil:ANVISA's accelerated medical device registration pathway for infection control products opens private hospital procurement previously dominated by local chemical suppliers.
- Electrostatic wipe compatibility:Formulations engineered for compatibility with electrostatic sprayer systems capture facility-wide disinfection contracts.
- EU Green Deal procurement criteria:Biodegradable substrate mandates in public tenders create first-mover advantage for plastic-free wipe lines.
Industry Challenges
- EPA FIFRA label amendment cycles:Substantiated efficacy claims require 12-18 month review timelines, delaying new active ingredient introductions.
- Substrate-electronics compatibility testing:Medical device OEMs demand material safety documentation for touchscreen and monitor surfaces, fragmenting SKU requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfecting Wipes Market |
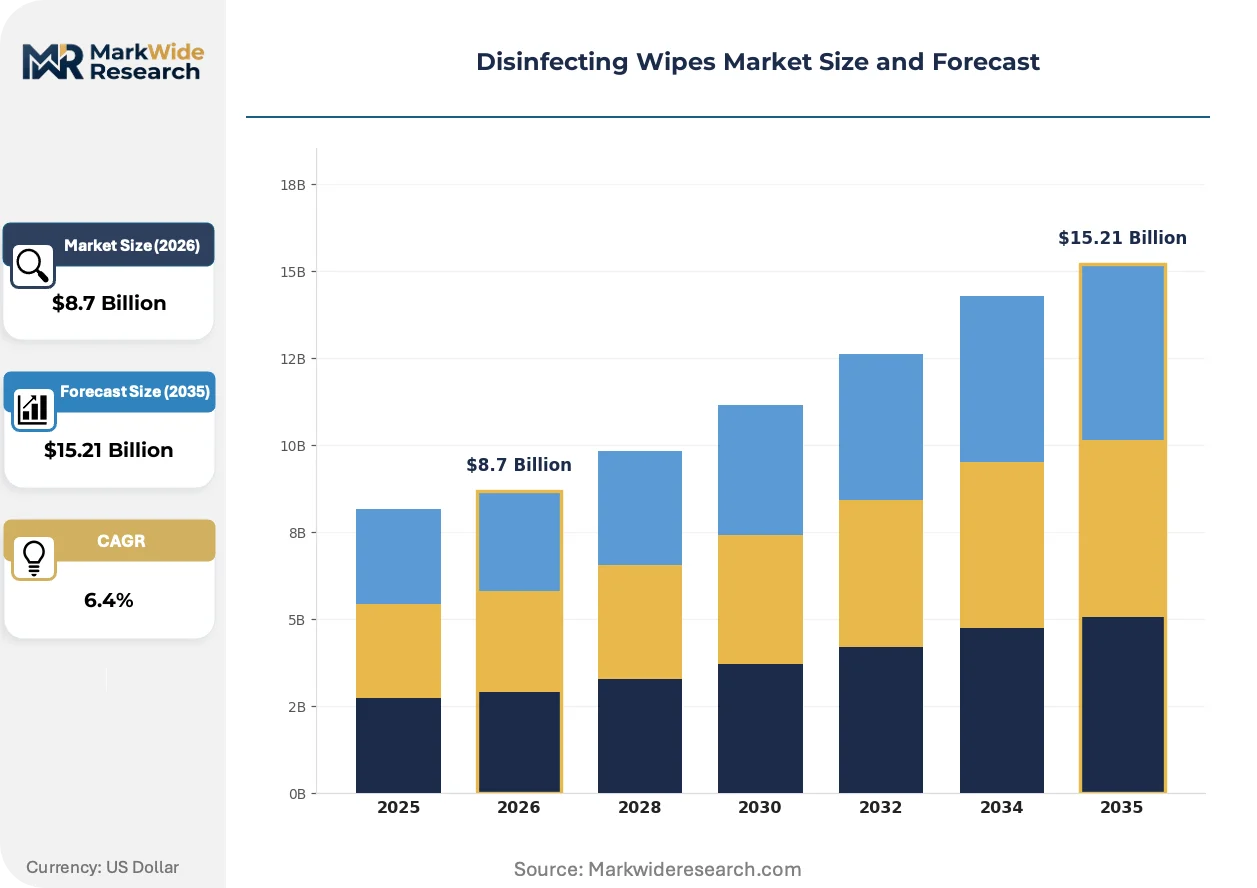
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibacterial, Alcohol-based, Disposable, Multi-surface Application: Healthcare, Household, Automotive, Commercial End User: Healthcare Facilities, Schools, Offices, Retail Material: Non-woven Fabric, Paper, Biodegradable, Plastic |
| Companies Covered | The Clorox Company, Procter & Gamble, Reckitt Benckiser Group PLC, Kimberly-Clark Corporation, Ecolab Inc., Johnson & Johnson, S.C. Johnson & Son, GOJO Industries, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfecting Wipes Market Evolving Landscape
Formulation chemistry and substrate engineering are diverging along healthcare-versus-consumer performance requirements. Manufacturers must now maintain parallel R&D tracks for divergent regulatory and efficacy standards.
Plant-derived non-woven substrates derived from bamboo and wood pulp are bifurcating the material supply base. European hospital procurement consortia have adopted plastic-reduction mandates with 2027 compliance deadlines. This shift is compressing conventional polypropylene wipe margins while elevating certified biodegradable suppliers into premium contract tiers.
REACH substance restriction proposals on persistent quaternary ammonium compounds are forcing reformulation investments across EU-destined product lines. German and French health authorities have issued preliminary guidance favoring alcohol-dominant blends. Manufacturers are responding by dual-registering formulations under both BPR streamlined assessment and full active substance approval pathways.
Healthcare facilities are consolidating vendor relationships around integrated surface disinfection programs. Group purchasing organizations now bundle wipe contracts with compliance training and usage analytics. This pattern is most visible in United States hospital systems, where supply chain officers seek single-source accountability for infection control outcomes.
Disinfecting Wipes Market Segmentation
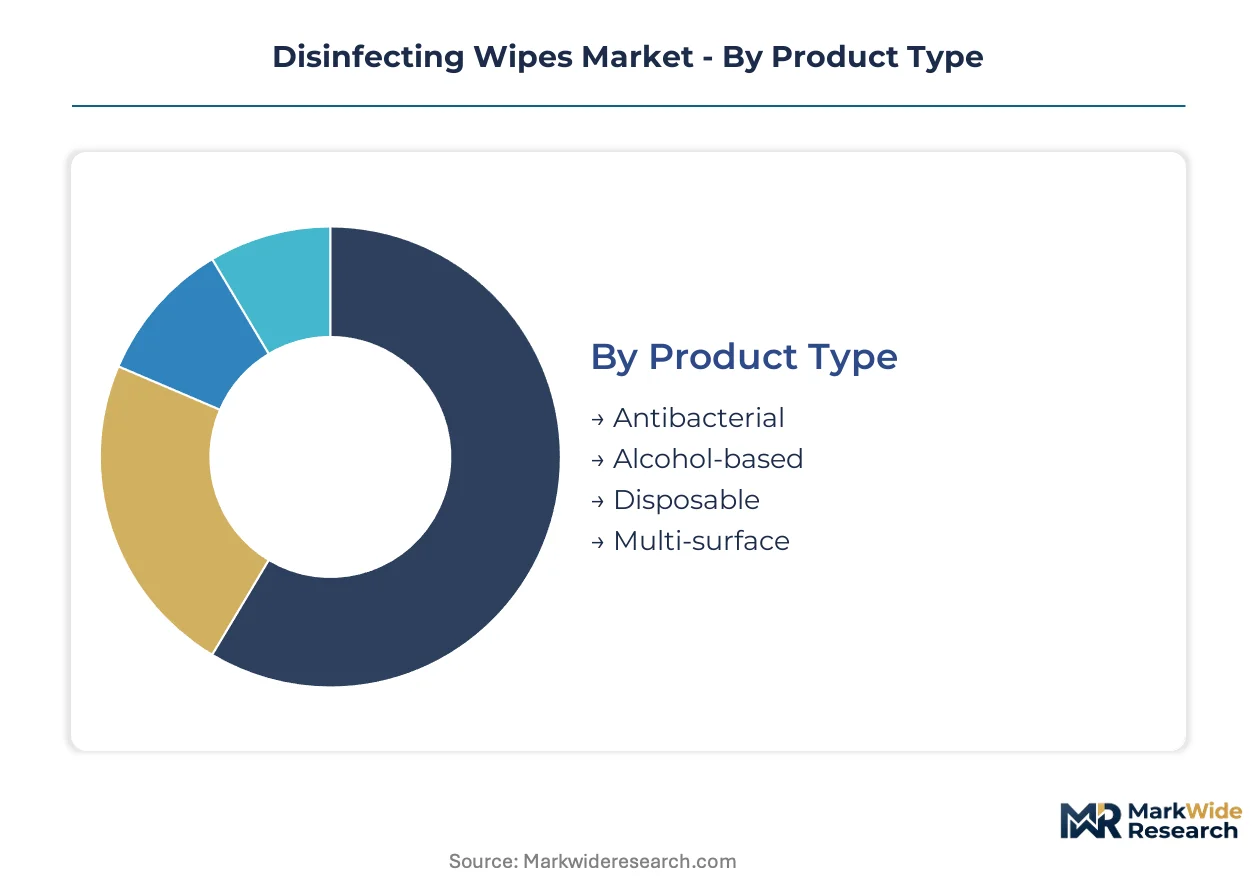
Segmentation in disinfecting wipes reveals how formulation chemistry, substrate engineering, and procurement policy intersect to create distinct competitive battlegrounds. Procurement officers now segment suppliers by kill-log documentation and EPA registration status rather than price alone.
Product Type:
Substitution pressure from spray disinfectants and UV-C systems weighs heaviest on commodity antibacterial formats, while alcohol-based lines defend their position through equipment compatibility claims.
- Antibacterial:Quaternary ammonium compound formulations dominate institutional contracts requiring residual antimicrobial activity. Healthcare procurement in the United States favors these for high-touch surface protocols where extended dwell time is operationally feasible.
- Alcohol-based:Isopropyl and ethanol blends evaporate within 30 seconds, satisfying medical device OEM compatibility requirements for touchscreen and monitor disinfection. Demand concentrates in acute care settings where electronics saturation demands rapid drying.
- Disposable:Single-use canisters and flow-pack formats reduce cross-contamination risk in outbreak response scenarios. Schools and transit authorities specify these for high-frequency surface rotation.
- Multi-surface:pH-neutral formulations span granite, stainless steel, and sealed wood without etching or residue. Residential and automotive channels absorb volume here where surface diversity exceeds specialized knowledge.
Multi-surface retains volume leadership across retail and commercial channels; alcohol-based holds the steepest expansion curve as healthcare electronics proliferation accelerates.
Application:
Cost tier stratification separates hospital-grade certified products from private-label retail formats, with margin compression most severe in household segments where private-label share has climbed.
- Healthcare:EPA-registered hospital-grade formulations with documented kill logs against C. difficile, MRSA, and SARS-CoV-2 command premium pricing. Group purchasing organization contracts in the United States consolidate volume around three to five approved suppliers per system.
- Household:Lemon-scented and bleach-alternative formulations compete on shelf placement and coupon elasticity. Mass retailers rotate promotional slots quarterly, eroding brand loyalty and compressing manufacturer margins.
- Automotive:Dashboard-safe formulations avoid plasticizer leaching and UV coating damage. Detailing shops and dealership service departments specify these for customer-facing vehicle preparation.
- Commercial:Janitorial service contractors source bulk canisters through distribution cooperatives. The segment absorbs volume from office reopening protocols, though hybrid work patterns have slowed replacement rates versus pre-pandemic baselines.
Healthcare commands the highest per-unit margins; commercial is climbing fastest as facilities management outsourcing expands.
End User:
Customer type determines packaging format, with healthcare facilities accepting large-format refills while schools and offices prioritize single-canister portability.
- Healthcare Facilities:Infection control committees mandate EPA registration numbers and efficacy data sheets. Acute care hospitals in the United States specify quaternary ammonium or alcohol-based chemistry based on surface material inventories.
- Schools:K-12 districts balance efficacy against student safety, favoring bleach-free formulations with shorter contact times. Custodial staffing shortages drive demand for pre-saturated substrates that eliminate mixing protocols.
- Offices:Facility managers specify multi-surface products for desk and common area rotation. Corporate sustainability policies increasingly require biodegradable substrate documentation.
- Retail:Grocery and big-box stores deploy wipes for cart handle sanitation and checkout surface protocols. High-frequency use patterns favor large-count canisters with moisture-retention sealing.
Healthcare Facilities anchor premium pricing power; Schools are expanding most quickly as federal pandemic relief funds upgrade custodial supply closets.
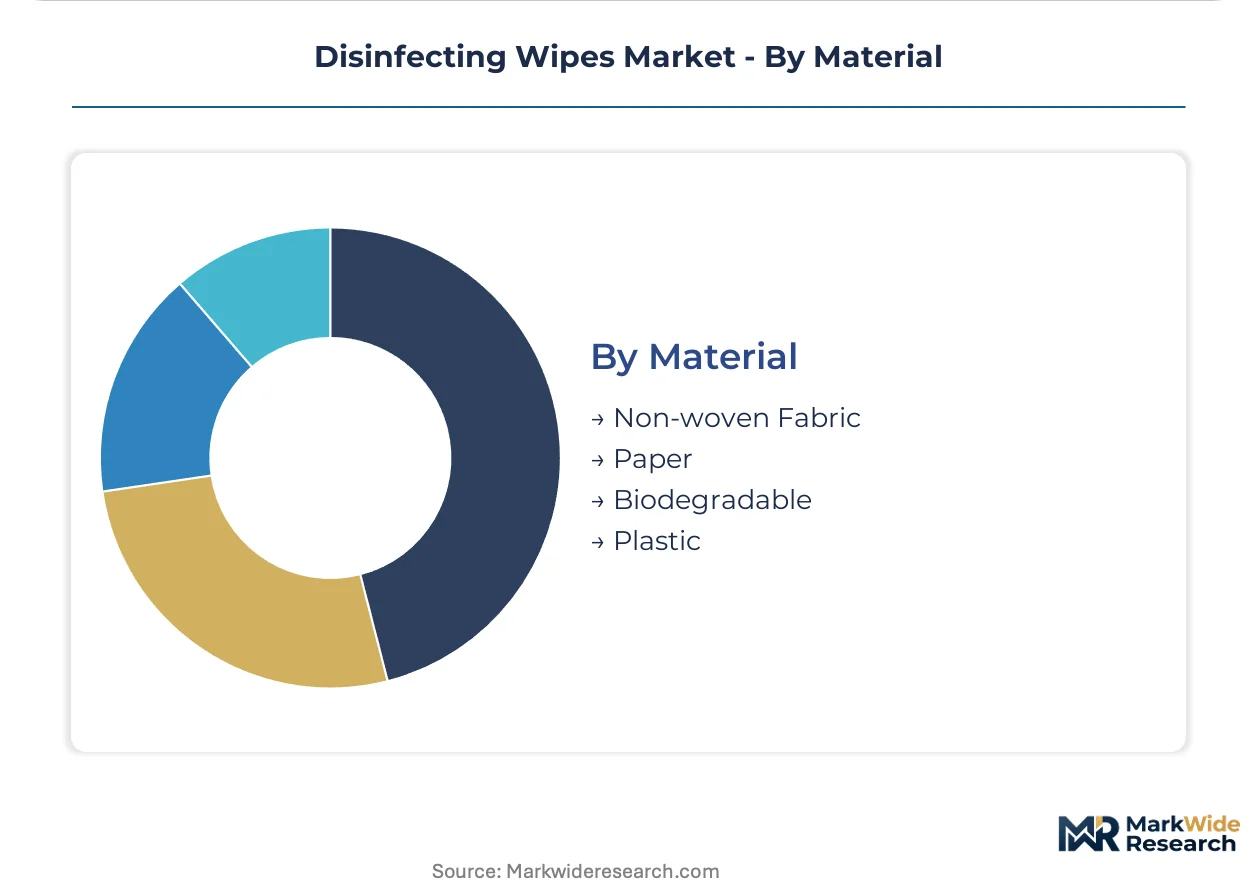
Material:
Supply concentration in spunlace non-woven manufacturing creates bottleneck risk, while biodegradable alternatives face certification fragmentation across EU member states.
- Non-woven Fabric:Spunlace and spunbond polypropylene substrates dominate medical-grade applications for tensile strength and liquid retention. Three suppliers control the majority of North American capacity, constraining new entrant sourcing.
- Paper:Cellulose-based wipes serve price-sensitive consumer segments and limited-durability tasks. Fast-food and casual dining chains specify these for table surface turnover.
- Biodegradable:Bamboo and wood pulp substrates satisfy EU Green Deal procurement criteria and corporate plastic-reduction pledges. German and French hospital consortia have adopted 2027 compliance deadlines for certified compostable materials.
- Plastic:Conventional polypropylene remains cost-advantaged for industrial and automotive degreasing applications where substrate disposal is not customer-visible.
Non-woven Fabric retains volume leadership across healthcare and commercial segments; Biodegradable is gaining share fastest as European public tender mandates take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. The United States favors pre-saturated hospital-grade formats with documented kill logs, while European procurement prioritizes biodegradable substrates under tightening plastic-reduction mandates. Developing markets concentrate demand in cost-optimized formats for institutional buyers.
United States
Healthcare facilities and retail consumers drive above-average per-capita consumption. The EPA's emerging viral pathogen claims framework accelerates hospital adoption cycles for manufacturers with expedited label expansions. Group purchasing organization contracts in the Midwest and Southeast consolidate volume around EPA-registered portfolios.
Germany
Hospital consortia and federal procurement standards anchor demand for certified compostable materials. The EU Biocidal Products Regulation and REACH framework govern active substance approval, forcing dual-registration strategies for quaternary ammonium formulations. Industrial clusters in North Rhine-Westphalia host spunlace substrate engineering facilities serving premium contract tiers.
China
Central government hospital standardization under public health initiatives consolidates fragmented provincial purchasing. The National Health Commission issues technical guidelines for surface disinfection in medical institutions. Manufacturing concentration in the Yangtze River Delta supplies both domestic institutional buyers and export markets.
Brazil
Private hospital chains and outpatient clinic networks expand procurement of imported infection control products. ANVISA's accelerated medical device registration pathway opens segments previously dominated by local chemical suppliers. São Paulo's healthcare infrastructure anchors premium product demand in the Southeast region.
India
Central government hospital procurement standardization under the National Health Mission consolidates state-level purchasing into volume contracts. The Central Drugs Standard Control Organization oversees medical device classification for infection control products. Metro hospital clusters in Maharashtra and Karnataka drive initial uptake of hospital-grade formats.
Disinfecting Wipes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling EPA-registered portfolios and established group purchasing organization relationships. Mid-scale players compete on substrate engineering and regional compliance expertise. Two strategic archetypes dominate: diversified consumer goods conglomerates with institutional extensions, and healthcare-focused specialists with hospital-grade certifications. Competitive moves concentrate on portfolio diversification into biodegradable substrates and strategic partnerships with electrostatic sprayer system manufacturers.
Within the diversified conglomerate tier, The Clorox Company and Reckitt Benckiser Group PLC exemplify players leveraging retail shelf dominance into institutional channels. Among healthcare-focused specialists, Kimberly-Clark Corporation occupies a position anchored by established hospital group purchasing organization contracts. These three represent distinct archetypes: retail-to-institutional bridge, clinical credibility extension, and healthcare-native supply chain integration.
| Leading Market Players |
|---|
| The Clorox Company |
| Procter & Gamble |
| Reckitt Benckiser Group PLC |
| Kimberly-Clark Corporation |
| Ecolab Inc. |
| Johnson & Johnson |
| S.C. Johnson & Son |
| GOJO Industries |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between spunlace substrate suppliers and wipe manufacturers lock in both raw material access and cost visibility across the analysis window, insulating EPA-registered producers from isopropyl alcohol feedstock volatility while freezing out price-sensitive new entrants lacking procurement scale.
Pricing Analysis
Contract-based long-term offtake dominates hospital-grade procurement, with pricing stratifying across premium, standard, and economy tiers based on EPA registration status and kill-log documentation depth. Brand premium and certification tier separate hospital-grade quaternary ammonium formulations from private-label retail alternatives. Cost compression in household segments intensifies because mass retailers rotate promotional slots quarterly, eroding manufacturer margins. Schools and janitorial contractors exhibit highest price sensitivity, while acute care hospitals accepting group purchasing organization contracts demonstrate lowest sensitivity due to infection control liability exposure.
Supply Chain Analysis
China, the United States, and Germany anchor spunlace non-woven substrate production for medical-grade applications, with the Yangtze River Delta and North Rhine-Westphalia hosting concentrated engineering facilities. Supply chains draw from isopropyl alcohol refineries, quaternary ammonium compound chemical processors, and polypropylene resin suppliers. Single-source vulnerability concentrates in spunlace capacity where three suppliers control majority North American medical-grade output. Distribution runs through group purchasing organization contracts in healthcare, mass retail consolidation in consumer channels, and distribution cooperatives serving janitorial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around group purchasing organization consolidation in United States hospital systems and European hospital procurement consortia, shifting negotiation leverage toward institutional purchasers with single-source accountability demands.
For Market Incumbents: Consolidate supplier relationships around integrated surface disinfection programs bundling wipe contracts with compliance training and usage analytics. Deepen backward integration into biodegradable substrate engineering to capture EU Green Deal procurement premiums before 2027 compliance deadlines lock in contract tiers. Channel control through established group purchasing organization relationships represents the critical defensive lever against electrostatic sprayer system manufacturers expanding into wipe-compatible formulations. For New Entrants and Emerging Players: Electrostatic wipe compatibility engineering services present a service-layer gap where incumbents under-serve facility-wide disinfection contract requirements. Target Brazil's private hospital chains through ANVISA's accelerated medical device registration pathway, the most penetrable geography given previous local chemical supplier dominance. Position through certified biodegradable substrate lines as a go-to-market angle capturing EU public tender mandates ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors substrate engineering specialists with dual BPR-EPA registration capabilities and established biodegradable certification. Long-term viability across a 5-10 year window hinges on plastic-reduction mandate compliance rather than commodity cost position. Watch pending EPA guidance on per- and polyfluoroalkyl substance contamination in non-woven substrates as the inflection indicator determining federal and state procurement contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | EU Green Deal procurement criteria in Germany and France elevate certified compostable suppliers into premium contract tiers by 2027. |
| EPA Emerging Viral Pathogen Label Expansion | Expedited kill-claim certifications accelerate hospital adoption cycles against C. difficile, MRSA, and SARS-CoV-2. |
| Electrostatic Sprayer Compatibility Engineering | Formulations compatible with facility-wide disinfection systems capture integrated contract bundles from GPOs. |
| Backward Integration into Spunlace Manufacturing | Captive substrate production insulates against single-source vulnerability in medical-grade non-woven supply. |
| Dual BPR-EPA Registration Pathway | REACH substance restriction proposals on quaternary ammonium compounds necessitate parallel regulatory strategies. |
Research Methodology
Operator-level perspectives from infection control committee members, hospital procurement officers, janitorial service contractors, and spunlace substrate plant managers anchored the qualitative base for this study. Primary interview data combined with secondary validation from EPA registration databases, EU Biocidal Products Regulation active substance review filings, hospital group purchasing organization contract disclosures, and customs trade records. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from manufacturer capacity disclosures.
Sensitivity analysis tested forecast outputs against variable assumptions for isopropyl alcohol feedstock pricing, spunlace capacity expansion timelines, and regulatory approval delays across the projection horizon. Segmentation dimensions modeled include formulation chemistry, substrate material, application setting, and end-user procurement policy. CAGRs derived from trend extrapolation of volume contracts and per-capita consumption patterns, incorporating EPA emerging viral pathogen claim adoption curves and EU biodegradable mandate compliance schedules as industry-specific inputs.
Forecasts assume regulatory continuity in EPA FIFRA enforcement and EU BPR active substance review timelines; material policy shifts on quaternary ammonium compound restrictions or per- and polyfluoroalkyl substrate contamination thresholds would require re-modeling. Recalibration cycles align with material shifts in hospital procurement standardization, janitorial labor availability, and spunlace manufacturing capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Global Animal Disinfectants Market