
 Global Fusidic Acid Market | 2026-2036
Global Fusidic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fusidic Acid Market Foresight
Asset-light contract manufacturing partnerships is rewriting competitive dynamics for mid-tier API producers seeking fusidic acid capacity without heavy capex burdens. LEO Pharma leverages its vertical integration into fermentation-based corticosteroid and antibiotic production to sustain cost advantages in European hospital tenders. Sun Pharma anchors its position through backward integration into active pharmaceutical ingredient supply, competing on volume across emerging markets where price sensitivity shapes procurement.
Fusidic acid is a steroidal antibiotic derived from Fusidium coccineum fermentation, characterized by a 29-carbon fusidane skeleton with selective protein synthesis inhibition against Gram-positive bacteria including methicillin-resistant Staphylococcus aureus. The compound serves primarily as a topical and systemic antibacterial agent in dermatology, ophthalmology, and orthopedic infection protocols. Cream and ointment formulations dominate current revenue pools due to established prescribing patterns in dermatology centers, while ophthalmic infections represent the fastest-expanding therapy area as resistance patterns drive specialist preference for fusidic acid eye drops. Hospital pharmacies control the largest distribution channel share through centralized procurement of parenteral and high-potency topical presentations.
FDA antimicrobial resistance stewardship programs and EMA updated quality guidelines for fermentation-derived APIs are tightening purity specifications and documentation requirements for fusidic acid manufacturers seeking market access. India's CDSCO schedule H regulations and China's NMPA drug master file requirements add layered compliance costs that favor producers with established regulatory affairs capabilities across multiple jurisdictions. Stakeholders must monitor evolving pharmacovigilance obligations and resistance surveillance data to anticipate shifts in formulary placement and reimbursement thresholds.
Market Dynamics
Hospital procurement consolidation across India and Southeast Asia is compressing supplier margins while amplifying volume concentration toward fermentation-based API producers with demonstrated MRSA efficacy data.
Growth Catalysts
- CDSCO Schedule H enforcement:India's tightened prescription controls for systemic antibiotics are channeling demand toward topical fusidic acid formulations in dermatology centers.
- Ophthalmic resistance surveillance:Specialist preference for fusidic acid eye drops is accelerating as methicillin-resistant Staphylococcus aureus patterns render fluoroquinolones less viable in tertiary eye hospitals.
- Fermentation yield optimization:Continuous bioprocessing advances in Fusidium coccineum cultivation are lowering unit production costs for pharmaceutical-grade API.
Market Restraints
- REACH compliance costs:ECHA documentation requirements for fermentation-derived APIs are elevating regulatory overhead for European contract manufacturers.
- Mupirocin substitution:Alternative topical antibiotics with broader Gram-negative coverage are displacing fusidic acid in uncomplicated skin infection protocols.
- Single-source fermentation feedstock:Concentrated supply of specialized yeast extracts for Fusidium coccineum cultivation creates input vulnerability.
Strategic Opportunities
- Vietnam hospital network expansion:Underpenetrated provincial health systems are establishing centralized pharmacy procurement for parenteral antibiotic protocols.
- Combination formulation development:Fixed-dose pairing with betamethasone is opening dermatology segments resistant to monotherapy prescribing.
- EMA quality guideline alignment:Updated fermentation API purity specifications are creating competitive moats for producers with advanced analytical capabilities.
Industry Challenges
- Pharmacovigilance data management:Resistance surveillance reporting obligations across multiple jurisdictions are straining regulatory affairs functions.
- Legacy equipment retrofitting:Stainless steel fermentation vessels require costly upgrades to meet current good manufacturing practice for containment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fusidic Acid Market |
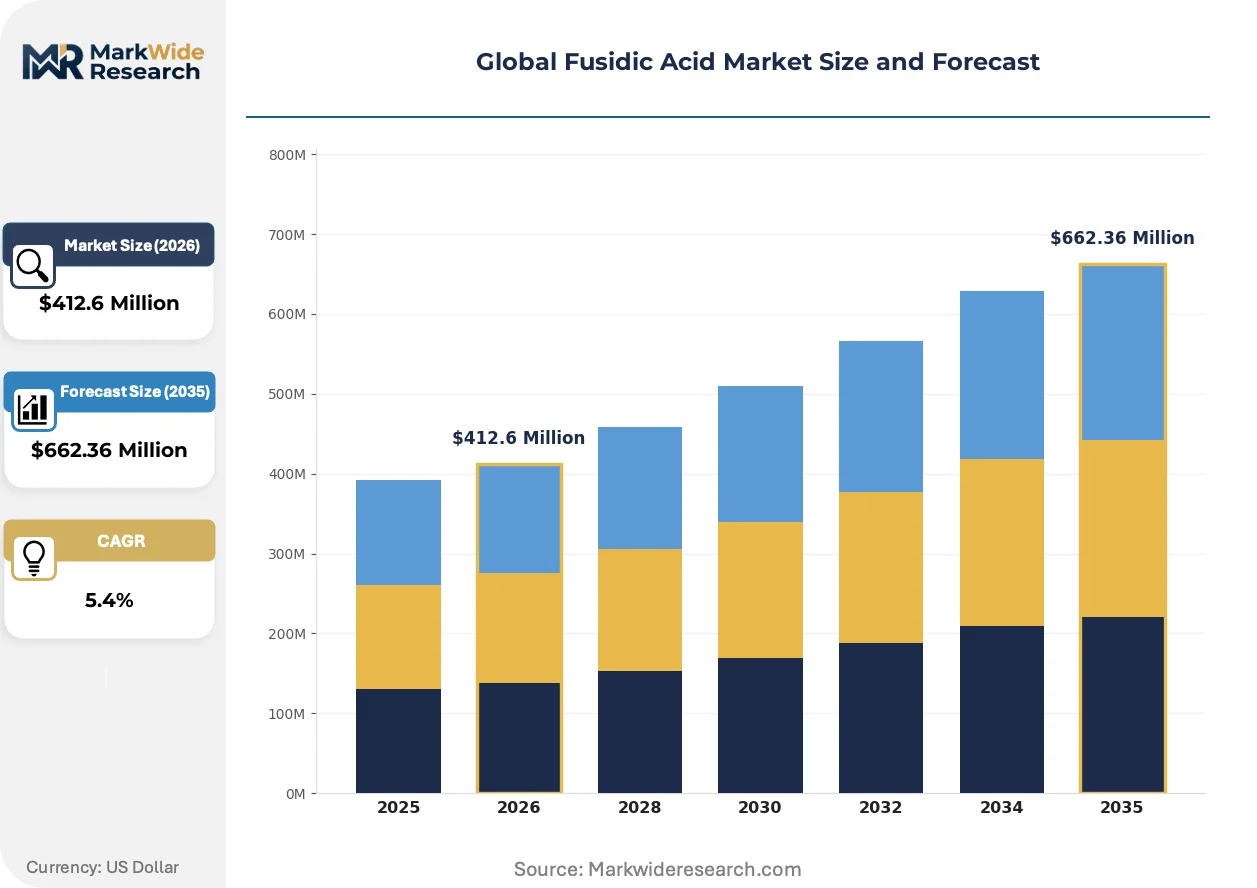
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Ointment, Eye Drops, Powder, Tablets Therapy Area: Skin Infections, Wound Care, Ophthalmic Infections, Respiratory Infections, Bone Infections End User: Hospitals, Clinics, Pharmacies, Dermatology Centers, Ophthalmology Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Joyang Labs, Wellona Pharma, LEO Pharma, Sun Pharma, Sandoz, Ercros S.A., Hoyoo Chemical, GlaxoSmithKline, Contay Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fusidic Acid Market Shifts & Advancements
Fermentation process intensification and regulatory data integrity requirements are redefining competitive advantage in fusidic acid manufacturing. Quality-by-design principles are displacing traditional batch-release testing.
Continuous bioprocessing technology is hybridizing batch fermentation with perfusion cell retention systems. Mid-tier API producers in India are adopting this hybrid approach to reduce cycle times by half. The technology is hybridizing cost structures between capital-intensive single-use systems and conventional stainless steel infrastructure, enabling smaller players to achieve pharmaceutical-grade yields without full facility replacement.
EMA updated quality guidelines for fermentation-derived APIs are mandating enhanced impurity profiling and extended stability data packages. European manufacturers are restructuring quality management systems to accommodate real-time release testing protocols. Parenteral formulation suppliers face the steepest compliance burden as sterility assurance requirements tighten documentation thresholds.
Specialist prescribing patterns are rotating toward resistance-guided therapy selection in dermatology and ophthalmology. Academic medical centers in India and Thailand are replacing empiric fluoroquinolone use with culture-directed fusidic acid protocols. This behavioral shift is compressing switching cycles as formulary committees demand local resistance data before contract renewal.
Global Fusidic Acid Market Segmentation
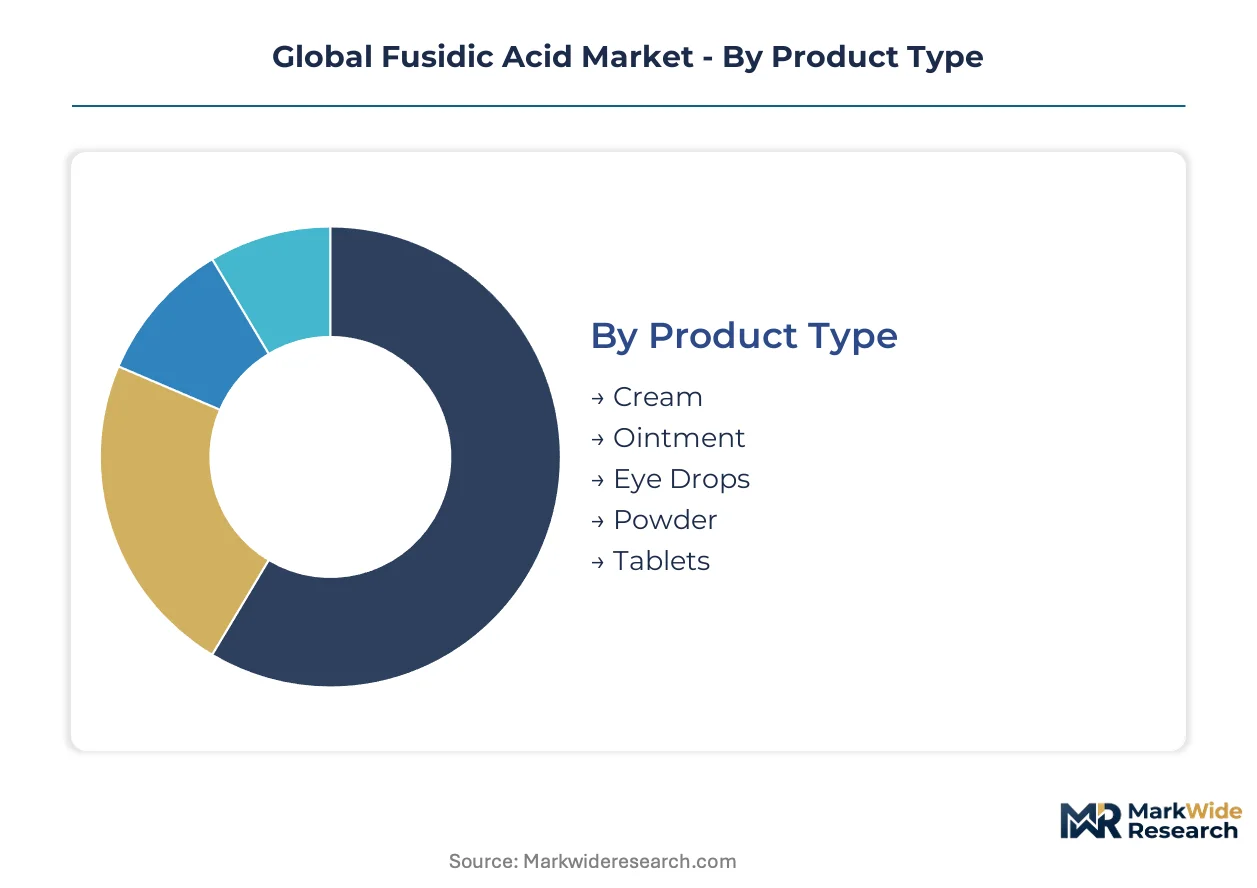
Fusidic acid market segmentation reveals distinct service intensity patterns across formulation types and clinical settings. After-sales requirements vary sharply between hospital parenteral procurement and retail dermatology channels, reshaping manufacturer resource allocation.
Product Type:
After-sales service intensity peaks with sterile parenteral formats requiring cold chain verification and batch traceability support, while semi-solid topicals demand minimal technical follow-through.
- Cream:Oil-in-water emulsion bases with 2% fusidic acid concentration dominate dermatology prescribing in temperate climates. Hospital formularies in Germany and France favor cream vehicles for inpatient wound protocols due to ease of removal and dressing compatibility.
- Ointment:Occlusive petrolatum-based preparations with superior skin penetration for dry, lichenified lesions. Indian dermatology centers prescribe ointments heavily during winter months, though adherence drops in humid monsoon conditions.
- Eye Drops:Sterile isotonic solutions with pH buffering for corneal tolerance. Tertiary eye hospitals in Thailand and Vietnam are expanding formulary inclusion as fluoroquinolone resistance accumulates.
- Powder:Bulk API for hospital compounding and regional manufacturing. CDSCO-registered facilities in Hyderabad and Ahmedabad source powder for captive formulation production.
- Tablets:Systemic formulations reserved for deep-seated staphylococcal infections unresponsive to topical therapy. Oral bioavailability constraints limit prescribing to specialist infectious disease units.
By volume, Cream leads. By growth pace, Eye Drops is ahead.
Therapy Area:
Cost tier stratification separates commodity wound care from premium ophthalmic protocols, with reimbursement thresholds determining accessible patient populations.
- Skin Infections:Impetigo, folliculitis, and secondarily infected eczema constitute the foundational indication. Primary care networks in England and Australia maintain fusidic acid as first-line for uncomplicated staphylococcal presentations.
- Wound Care:Surgical site prophylaxis and chronic ulcer management in diabetic populations. Hospital procurement in Mumbai and Delhi concentrates volume through centralized tendering for parenteral and high-potency topical presentations.
- Ophthalmic Infections:Bacterial conjunctivitis and blepharitis with culture-directed selection. Academic medical centers in Bangkok are replacing empiric fluoroquinolone protocols with resistance-guided fusidic acid monotherapy.
- Respiratory Infections:Limited systemic use for staphylococcal pneumonia in cystic fibrosis cohorts. Narrow therapeutic index restricts application to specialist centers with therapeutic drug monitoring capacity.
- Bone Infections:Adjunctive therapy for chronic osteomyelitis requiring prolonged antibiotic exposure. Orthopedic units in São Paulo combine fusidic acid with rifampicin for biofilm-active regimens.
Skin Infections anchors volume share. Ophthalmic Infections climbs the fastest.
End User:
Customer type fragmentation creates divergent purchasing behaviors, with institutional buyers demanding extended stability data and individual practitioners prioritizing convenience formats.
- Hospitals:Centralized pharmacy procurement with formulary committee oversight. EMA-compliant manufacturers capture European tenders through documented fermentation batch consistency.
- Clinics:Mixed private and public outpatient settings with flexible prescribing authority. Indian polyclinics in tier-2 cities drive eye drop volume through direct pharmaceutical representative access.
- Pharmacies:Over-the-counter availability for topical presentations in deregulated markets. Australian community pharmacies retain strong dispensing volumes for uncomplicated skin infection self-treatment.
- Dermatology Centers:Specialist referral networks with preference for combination steroid-antibiotic preparations. Mumbai and Bangalore dermatology chains influence prescribing patterns across western and southern India.
- Ophthalmology Clinics:Concentrated specialist demand with resistance surveillance integration. Tertiary eye hospitals in Ho Chi Minh City are establishing local antibiogram databases to guide formulary decisions.
Hospitals command volume leadership. Ophthalmology Clinics is expanding most quickly.
Distribution Channel:
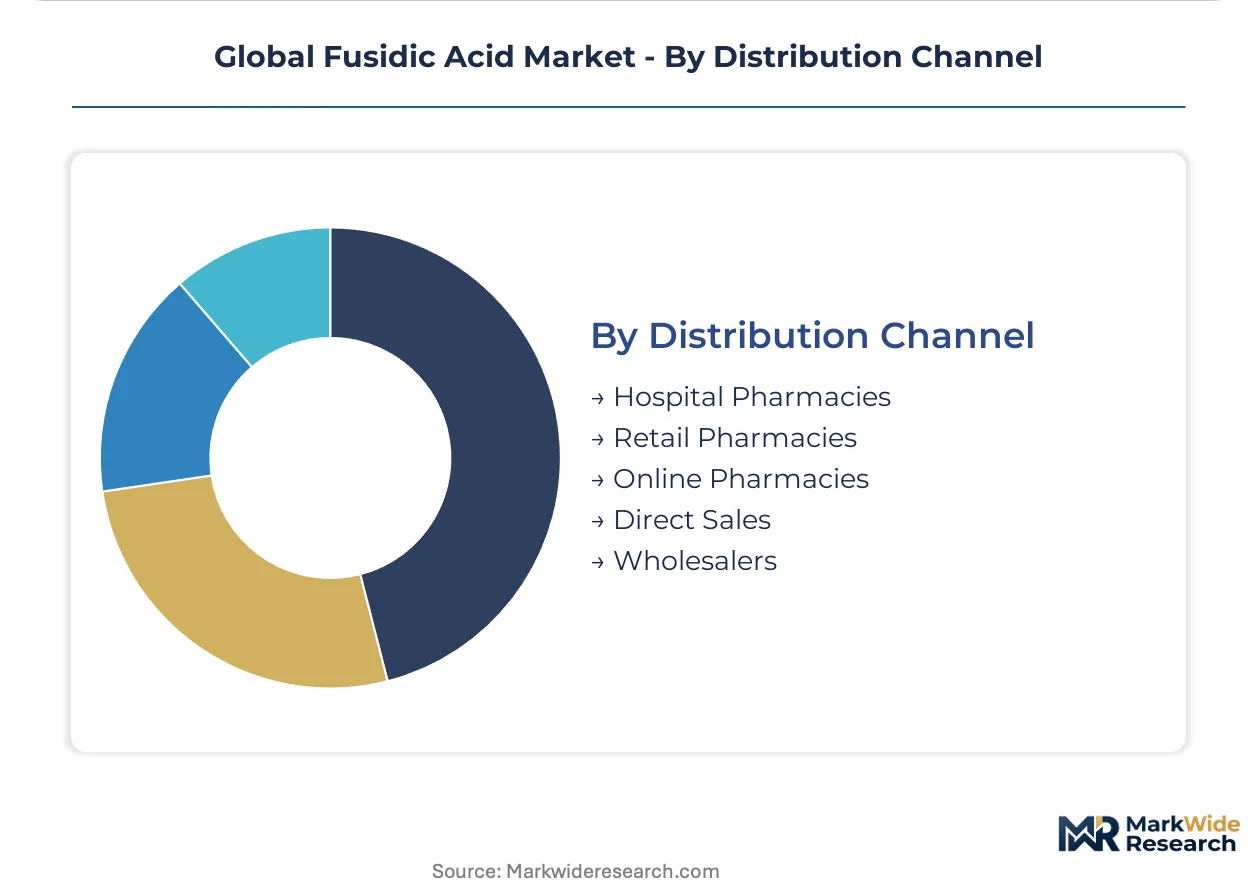
Supply concentration tilts toward direct institutional contracting, with retail and digital channels capturing residual consumer-directed demand.
- Hospital Pharmacies:Captive dispensing with inventory management integration. European hospital networks in the Netherlands and Belgium consolidate fusidic acid procurement through regional purchasing cooperatives.
- Retail Pharmacies:Community-based dispensing with pharmacist counseling obligations. Australian retail chains maintain distinct generic and originator product tiers with price differentiation.
- Online Pharmacies:Digital prescription fulfillment with cold chain logistics requirements. Indian e-pharmacy platforms in Delhi and Bengaluru are expanding dermatology and ophthalmology product availability.
- Direct Sales:Manufacturer-to-institution contracting for high-volume parenteral supply. LEO Pharma deploys direct sales teams for European hospital antibiotic stewardship programs.
- Wholesalers:Regional distribution intermediaries with inventory financing functions. Indian pharmaceutical distributors in Ahmedabad and Vadodara manage powder API flows to formulation manufacturers.
Hospital Pharmacies leads by volume. Online Pharmacies gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO Schedule H enforcement in India and EMA quality guideline updates in Europe are redirecting procurement toward fermentation-based API producers with documented MRSA efficacy. Hospital network consolidation across Southeast Asia and antimicrobial stewardship programs in Western markets are concentrating demand in compliant supply chains.
India
Mumbai and Delhi hospital procurement programs are driving volume for parenteral fusidic acid as MRSA prevalence rises in tertiary care centers. CDSCO Schedule H regulations now mandate prescription tracking for systemic antibiotics, channeling demand toward topical formulations in dermatology. Hyderabad and Ahmedabad manufacturing clusters supply bulk API powder to domestic formulation producers.
Germany
EMA fermentation API purity specifications are elevating compliance costs for contract manufacturers serving European hospital tenders. REACH documentation requirements from ECHA strain mid-tier producers lacking dedicated regulatory affairs capacity. Bavaria and North Rhine-Westphalia pharmaceutical clusters host vertically integrated corticosteroid-antibiotic producers with established analytical capabilities.
United States
FDA antimicrobial resistance stewardship programs are tightening formulary placement criteria for topical antibiotics in academic medical centers. Hospital procurement consolidation favors suppliers with real-time release testing protocols. New Jersey and Massachusetts biopharma corridors concentrate fermentation expertise for high-potency API production.
Vietnam
Provincial hospital network expansion is establishing centralized pharmacy procurement for parenteral antibiotic protocols in underpenetrated health systems. Ministry of Health antibiotic guidelines are integrating resistance surveillance data into formulary decisions. Ho Chi Minh City tertiary eye hospitals are expanding fusidic acid eye drop utilization as fluoroquinolone resistance accumulates.
China
NMPA drug master file requirements are layering compliance costs that favor producers with established multi-jurisdictional regulatory capabilities. Fermentation yield optimization investments in Fusidium coccineum cultivation are lowering unit production costs for pharmaceutical-grade API. Zhejiang and Jiangsu chemical-pharmaceutical clusters supply specialized yeast extracts for antibiotic fermentation feedstock.
Global Fusidic Acid Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Hospital pharmacy consolidation in Europe and India favors vertically integrated fermentation operators with batch consistency documentation. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with captive API supply, mid-tier fermentation specialists leveraging continuous bioprocessing, and contract manufacturers serving regional formulation markets. Capacity expansion and regulatory compliance investments constitute the dominant competitive moves as purity specifications tighten.
Among European-origin pharmaceutical conglomerates, LEO Pharma and Sandoz occupy positions anchored in fermentation-based antibiotic production heritage. Joyang Labs and Hoyoo Chemical represent Chinese fermentation specialists with cost-optimized cultivation capabilities. Sun Pharma anchors the Indian integrated producer archetype through backward control over active pharmaceutical ingredient supply chains.
| Leading Market Players |
|---|
| Joyang Labs |
| Wellona Pharma |
| LEO Pharma |
| Sun Pharma |
| Sandoz |
| Ercros S.A. |
| Hoyoo Chemical |
| GlaxoSmithKline |
| Contay Biotechnology |
| Others |
Supply & Pricing Matrix
The Mumbai-Ahmedabad pharmaceutical freight corridor channels fermentation-derived API shipments from Gujarat manufacturing clusters to Maharashtra hospital procurement hubs, with logistics cost differentials widening price spreads between certified pharmaceutical-grade and technical-grade fusidic acid powder. This corridor's freight economics concentrate pricing power among EMA-compliant producers with documented batch consistency, while compressing margins for regional compounders serving price-sensitive dermatology centers.
Pricing Analysis
Certification level (EMA/FDA-grade versus technical-grade) creates the primary spread between contract manufacturers serving European hospital tenders and regional Indian formulators. Three-tier pricing structure across premium, standard, and economy levels tracks backward integration depth, with captive fermentation operators capturing 15-20% cost advantages over toll manufacturers. Pricing pressure stems from mupirocin substitution in uncomplicated skin infection protocols, particularly in Australian and English primary care networks. Hospital procurement managers demonstrate lowest price sensitivity due to formulary lock-in, while retail pharmacy buyers in India's tier-2 cities drive aggressive generic substitution.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus as Zhejiang yeast extract suppliers feed fermentation cultivations in Hyderabad and Ahmedabad. API production concentrates in India, China, and Denmark, with European hospital tenders drawing from Bavarian and North Rhine-Westphalia pharmaceutical clusters. Raw material dependencies center on specialized yeast extracts, pharmaceutical-grade solvents, and sterile packaging components. Single-source vulnerability in Fusidium coccineum cultivation feedstock creates input concentration risk. Distribution runs through hospital pharmacy cooperatives in Europe, direct manufacturer contracting for high-volume parenteral supply, and regional pharmaceutical distributors managing powder API flows to formulation producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
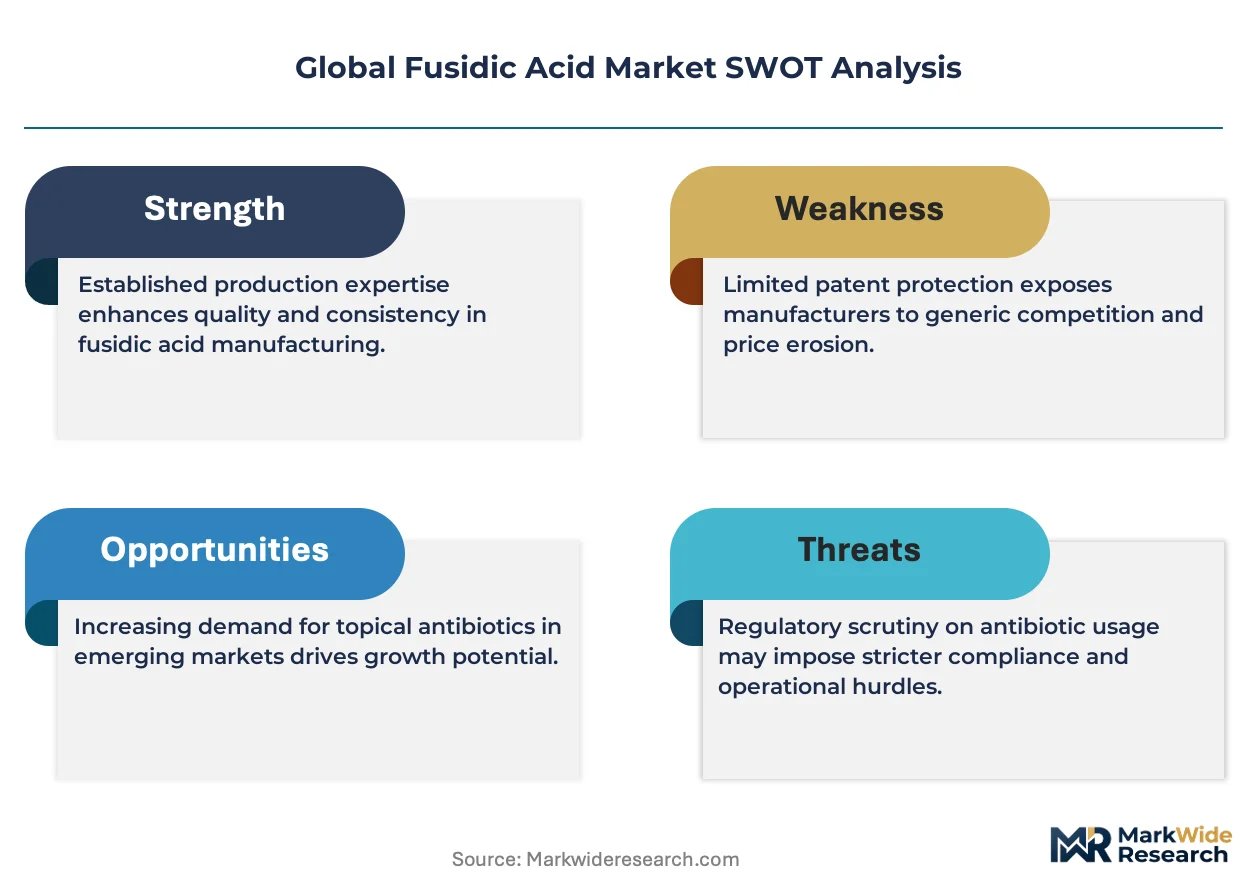
Mupirocin and newer topical antibiotics with broader Gram-negative coverage threaten fusidic acid's position in empiric skin infection protocols, forcing incumbents to defend through resistance surveillance data and ophthalmic specialization.
For Market Incumbents: Pre-empt substitution threats by deepening backward integration into Fusidium coccineum fermentation capacity in India or China, locking in yeast extract supply through long-term offtake agreements with Zhejiang suppliers. Anchor hospital formulary position through real-time release testing protocols that satisfy EMA updated quality guidelines, creating compliance moats against mid-tier challengers. For New Entrants and Emerging Players: Build out continuous bioprocessing capabilities targeting Vietnamese provincial hospital networks, where centralized pharmacy procurement for parenteral antibiotics remains underpenetrated and fluoroquinolone resistance drives formulary opening. Capture share through fixed-dose combination development with betamethasone, accessing dermatology segments resistant to monotherapy prescribing. For Investors and Strategic Acquirers: Fermentation-specialist mid-cap producers with EMA-registered facilities and established CDSCO compliance capabilities offer the most defensible acquisition profile. Monitor ophthalmic resistance surveillance data from Bangkok and Ho Chi Minh City tertiary eye hospitals as the signal indicating sustained demand inflection for fusidic acid eye drops versus fluoroquinolone alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Hybrid perfusion systems halve cycle times for Indian API producers without full facility replacement. |
| EMA Quality Guideline Alignment | Enhanced impurity profiling mandates separate compliant producers from documentation-deficient competitors. |
| Combination Formulation Development | Betamethasone pairing opens dermatology segments resistant to monotherapy prescribing patterns. |
| Hospital Pharmacy Direct Contracting | LEO Pharma's European antibiotic stewardship deployment captures formulary lock-in through clinical education. |
| Yeast Extract Supply Security | Long-term offtake agreements with Zhejiang suppliers mitigate single-source feedstock vulnerability. |
Research Methodology
Cross-validation between primary interviews with fermentation process engineers, hospital pharmacy procurement directors, and regulatory affairs specialists and secondary validation through EMA submission databases, CDSCO registration filings, and ClinicalTrials.gov anchors the qualitative findings. Bottom-up triangulation against customs trade data for fusidic acid API shipments and top-down reconciliation with hospital procurement expenditure patterns ensures dimensional consistency.
Calibration against historical volume trajectories in dermatology and ophthalmic prescribing segments informs the analytical framework across the analysis window. Segmentation dimensions include formulation type, therapy area, end-user channel, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand modeling incorporating MRSA prevalence surveillance and formulary placement probability. Forecast inputs center on continuous bioprocessing adoption curves and EMA compliance cost trajectories for fermentation-derived APIs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fermentation specialists or accelerated mupirocin substitution in European primary care would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Sodium Bisulphite Market