
 Disinfectant Wipes Market | 2026-2036
Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant Wipes Market Intelligence
Premium clinical-grade formulations and commodity retail offerings is decoupling across pricing, substrate quality, and active ingredient concentration. The Clorox Company leverages its EPA-registered portfolio to anchor the institutional channel, while Kimberly-Clark Corporation sustains manufacturing scale through integrated non-woven supply chains. Nice-Pak Products specializes in private-label production, competing on cost efficiency for mass-market retail placement.
Disinfectant wipes are pre-moistened non-woven substrates impregnated with quaternary ammonium compounds, sodium hypochlorite, or hydrogen peroxide solutions, designed to eliminate pathogens on hard surfaces within a specified contact time, typically one to ten minutes. Hard surface formulations dominate volume in the product type dimension, though healthcare-grade segments command superior margin pools due to validated sporicidal claims and FDA-cleared device classifications. Biodegradable material substrates represent the fastest-growing structural category, as commercial buyers face mounting pressure to reduce synthetic polyester waste streams across hospital and foodservice procurement frameworks.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern active ingredient efficacy claims and label instructions for U.S.-marketed disinfectant wipes, while OSHA bloodborne pathogen standards mandate surface disinfection protocols in healthcare and industrial workplaces. The FDA regulates wipes marketed as medical devices with antimicrobial properties, creating dual compliance pathways that fragment vendor qualification requirements. Stakeholders must monitor emerging state-level restrictions on quaternary ammonium compounds and peracetic acid, as these chemistry shifts will force reformulation investments and supply chain recertification across institutional customer bases.
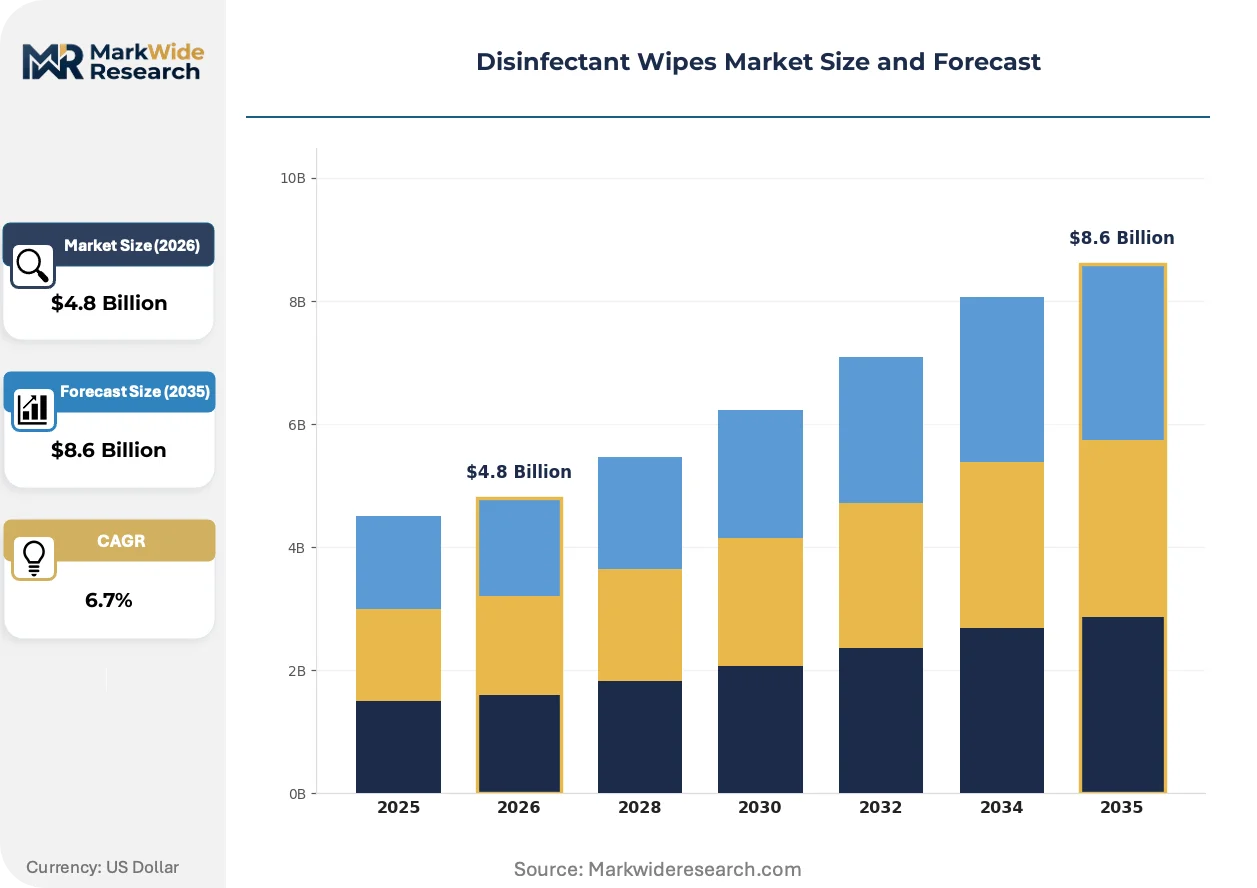
Market Dynamics
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act are fragmenting vendor qualification pathways and forcing reformulation investments across institutional customer bases. This regulatory pressure is compressing margins for non-compliant suppliers while rewarding established players with validated sporicidal claims.
Growth Catalysts
- Healthcare infection control protocols:Acute care facilities in the United States are tightening surface disinfection standards, driving hospital-grade wipe procurement. OSHA bloodborne pathogen standards mandate these protocols in clinical settings.
- EPA FIFRA registration framework:Stricter efficacy validation requirements are creating competitive moats for compliant manufacturers. Institutional buyers now require documented contact-time performance.
- Biodegradable substrate innovation:Cellulose-based non-woven materials are displacing synthetic polyester in hospital and foodservice procurement frameworks. Commercial buyers face waste-reduction mandates.
Market Restraints
- Active ingredient cost volatility:Quaternary ammonium compound feedstock prices fluctuate with petrochemical supply chains. Formulators absorb margin compression or pass costs to price-sensitive retail channels.
- Supply concentration in spunlace non-wovens:Integrated manufacturers control substrate quality tiers. Independent wipe converters face allocation risk during demand spikes.
- Technical limitation in sporicidal efficacy:Hydrogen peroxide formulations require extended contact times impractical for high-turnover surfaces. Healthcare facilities default to sodium hypochlorite despite corrosion concerns.
Strategic Opportunities
- Underpenetrated food processing sector:USDA-inspected facilities lack standardized wipe protocols compared to healthcare. Peracetic acid formulations could capture this whitespace with validated organic residue claims.
- Regulatory tailwind from state-level chemistry restrictions:California and New York are advancing quaternary ammonium compound limitations. Early reformulators to alternative actives secure institutional procurement lock-in.
- Direct-to-facility distribution channels:Group purchasing organizations are consolidating hospital supply contracts. Bypassing traditional distribution unlocks margin capture for specialized clinical-grade suppliers.
Industry Challenges
- Dual-pathway compliance complexity:EPA FIFRA and FDA medical device regulations create overlapping validation requirements. Wipes with antimicrobial claims face extended certification timelines.
- Substrate-finished goods integration:Non-woven production requires capital-intensive spunlace lines. Wipe converters without captive supply struggle to secure consistent biodegradable material quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant Wipes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Surface, Multi-Surface, Bathroom, Kitchen Use Case: Household, Commercial, Industrial, Healthcare Material: Non-Woven Fabric, Synthetic, Biodegradable, Cotton Distribution Channel: Online, Supermarket, Pharmacy, Convenience Store |
| Companies Covered | Procter & Gamble, 3M Company, The Clorox Company, SC Johnson & Son, GOJO Industries, Reckitt Benckiser, Johnson & Johnson, Nice-Pak Products, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant Wipes Market Strategic Shifts & Innovations
Formulation chemistry and substrate engineering are converging to redefine performance benchmarks across clinical and commercial applications. Regulatory chemistry shifts and procurement centralization are accelerating vendor consolidation.
Plant-derived cellulose substrates impregnated with stabilized hydrogen peroxide are unifying biodegradability claims with sporicidal efficacy. Hospital systems in the Northeast United States are piloting these materials for operating room terminal cleaning. The technology is compressing the historical trade-off between environmental credentials and pathogen elimination performance.
REACH restrictions on peracetic acid precursors in the European Union are forcing reformulation toward quaternary ammonium alternatives. Industrial wipe manufacturers serving EU foodservice markets face supply chain recertification. Germany and France are seeing accelerated adoption of pre-moistened alcohol-based wipes as interim compliance pathways.
Consolidated procurement through healthcare group purchasing organizations is displacing decentralized facility-level buying. Hospital networks are mandating single-source contracts for standardized infection control protocols. This concentration is most visible in the United States, where ten health systems control substantial acute care bed capacity and dictate supplier qualification requirements.
Disinfectant Wipes Market Segmentation
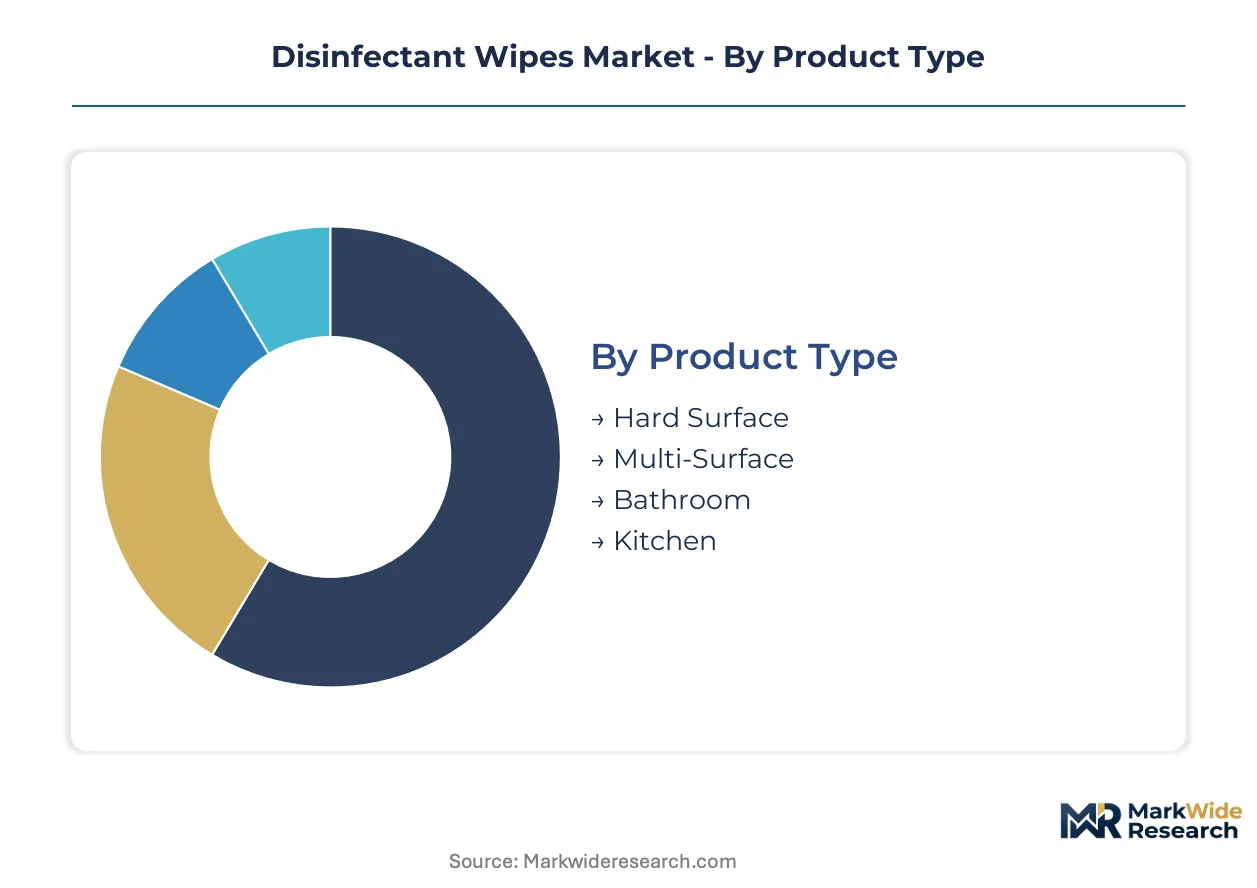
Segmentation in disinfectant wipes reveals divergent performance requirements across clinical and consumer environments. Material chemistry and substrate engineering separate premium institutional formulations from commodity retail offerings. Distribution channel dynamics further fragment competitive positioning between direct-procurement healthcare networks and mass-market retail placements.
Product Type:
Replacement cycles vary dramatically across surface-specific formulations, with healthcare facilities upgrading to validated sporicidal grades while households rotate through lower-performance commodity SKUs.
- Hard Surface:Formulations carry EPA-registered efficacy claims against healthcare-relevant pathogens including C. difficile and MRSA. Acute care facilities in the United States mandate these wipes for patient room terminal cleaning under OSHA bloodborne pathogen compliance protocols.
- Multi-Surface:General-purpose substrates balance compatibility across sealed wood, laminate, and stainless steel. Commercial office buildings favor these wipes for janitorial standardization, though healthcare procurement excludes them from sterile zones due to unvalidated contact times.
- Bathroom:Acidic or bleach-based chemistries target soap scum and mineral deposits alongside disinfection. Residential demand concentrates in North American markets with larger average bathroom square footage.
- Kitchen:Food-contact-safe actives replace quaternary ammonium compounds in formulations targeting residential meal preparation surfaces. FDA clearance for indirect food contact separates premium kitchen wipes from standard household grades.
Hard Surface sits at the top of the volume ranking, with Biodegradable climbing the fastest.
Use Case:
Cost tier stratification separates validated clinical procurement from price-sensitive consumer purchasing, with industrial applications occupying an intermediate specification band.
- Household:Mass-market SKUs compete on shelf price and fragrance differentiation. Retail placement in Walmart and Target determines volume concentration, with private-label capture accelerating in inflationary consumer environments.
- Commercial:Facility management contracts specify bulk canister formats for janitorial services. LEED-certified building managers increasingly mandate biodegradable substrate minimums in RFP specifications.
- Industrial:Heavy-duty substrates withstand grease and solvent exposure in manufacturing environments. OSHA hazard communication standards govern wipe selection for chemical spill response protocols.
- Healthcare:Hospital-grade formulations require FDA-cleared device status or EPA List K sporicidal registration. Group purchasing organizations consolidate acute care contracts around single-source suppliers with validated supply continuity.
Healthcare commands the steepest margin tier, with Industrial expanding most quickly as manufacturing hygiene protocols tighten.
Material:
Substrate sourcing concentration among spunlace non-woven producers creates supply bottlenecks for converters seeking sustainable material transitions.
- Non-Woven Fabric:Spunlace cellulose-polyester blends dominate institutional procurement for tensile strength and liquid retention. Kimberly-Clark and integrated manufacturers control captive supply of pharmaceutical-grade substrate tiers.
- Synthetic:Petroleum-derived polyester substrates face procurement headwinds as hospital sustainability mandates advance. The material retains cost advantages in price-competitive retail channels.
- Biodegradable:Plant-based cellulose from sustainably managed forestry displaces synthetic components. European Union procurement frameworks under the EU Green Deal accelerate adoption timelines for public sector contracts.
- Cotton:Natural fiber substrates serve premium cosmetic and personal care adjacent markets. Limited disinfection efficacy restricts penetration into clinical surface cleaning applications.
Non-Woven Fabric retains volume leadership, with Biodegradable gaining share fastest on regulatory tailwinds.
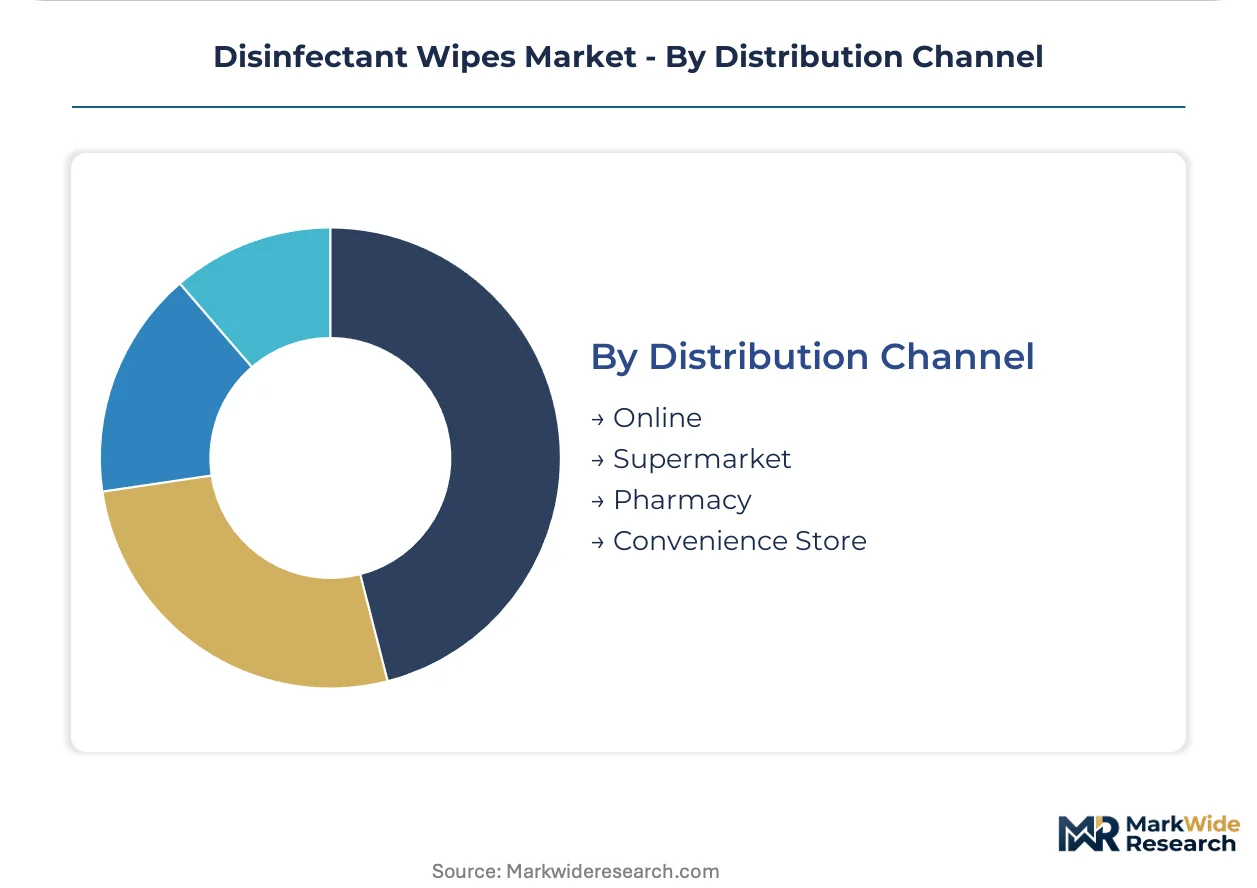
Distribution Channel:
Customer type fragmentation separates institutional procurement professionals from impulse-driven retail consumers, with channel-specific packaging formats reinforcing segmentation boundaries.
- Online:E-commerce penetration concentrates in subscription replenishment models for household segments. Amazon and direct-to-consumer specialists capture repeat purchase loyalty through auto-delivery incentives.
- Supermarket:Mass merchandisers drive volume through promotional pricing and end-cap placement. Private-label penetration exceeds national brand growth in price-sensitive post-pandemic purchasing patterns.
- Pharmacy:CVS and Walgreens position clinical-grade wipes adjacent to cough-cold and first-aid categories. Pharmacist recommendation influence sustains premium pricing for healthcare-positioned SKUs.
- Convenience Store:Single-use and travel formats target immediate-need purchasing in transit corridors. Limited SKU depth restricts penetration to commodity household formulations.
Supermarket maintains volume dominance, with Online expanding most rapidly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's healthcare procurement frameworks drive institutional-grade wipe adoption at a faster clip than France, where retail channel concentration sustains commodity volume leadership. Brazil and India present divergent growth trajectories shaped by regulatory maturity and hospital infrastructure investment cycles.
United States
Acute care bed expansion in Texas and Florida drives hospital-grade wipe procurement through group purchasing organizations. EPA FIFRA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act fragment vendor qualification pathways. The Northeast corridor pilots biodegradable cellulose substrates for operating room terminal cleaning protocols.
Germany
REACH restrictions on peracetic acid precursors force reformulation toward quaternary ammonium alternatives in foodservice applications. ECHA chemical safety assessments accelerate supply chain recertification timelines. The Rhine-Ruhr industrial cluster sees accelerated adoption of alcohol-based wipes as interim compliance pathways.
China
Hospital infrastructure modernization in the Yangtze River Delta and Pearl River Delta regions expands clinical-grade wipe demand. NMPA medical device regulations create dual-pathway compliance complexity for antimicrobial claims. Shanghai-based manufacturers pilot hydrogen peroxide formulations for healthcare procurement frameworks.
Brazil
Private hospital network expansion in São Paulo and Minas Gerais states drives institutional disinfectant wipe procurement. ANVISA medical device regulations govern antimicrobial product registrations with extended certification timelines. The São Paulo industrial corridor concentrates non-woven substrate conversion capacity for regional supply.
India
Hospital accreditation standards under the National Accreditation Board for Hospitals tighten surface disinfection protocols in Maharashtra and Karnataka. CDSCO medical device regulations create compliance barriers for imported antimicrobial formulations. The Mumbai-Pune pharmaceutical corridor anchors domestic wipe manufacturing scale-up.
Disinfectant Wipes Market Key Industry Players
Top-tier vendors anchor institutional procurement channels, while mid-scale converters compete on cost efficiency for private-label retail placement. The vendor base stratifies across EPA-registered portfolio holders, integrated non-woven substrate producers, and specialized clinical-grade formulators. Strategic archetypes include regulatory compliance specialists, captive supply chain integrators, and private-label cost optimizers. Dominant competitive moves encompass backward integration into spunlace non-woven production and direct-to-facility distribution channel development.
Among U.S.-based institutional suppliers, The Clorox Company and Kimberly-Clark Corporation exemplify divergent strategic positions. Clorox occupies a position within the regulatory compliance archetype through its EPA-registered portfolio concentration. Kimberly-Clark represents the captive supply chain integrator archetype via its in-house non-woven substrate production capabilities. Nice-Pak Products sits within the private-label cost optimizer tier, competing on manufacturing efficiency for mass-market retail placement.
| Leading Market Players |
|---|
| Procter & Gamble |
| 3M Company |
| The Clorox Company |
| SC Johnson & Son |
| GOJO Industries |
| Reckitt Benckiser |
| Johnson & Johnson |
| Nice-Pak Products |
| Kimberly-Clark Corporation |
| Others |
Cost & Logistics Intelligence
Quaternary ammonium compound feedstock costs transmit directly from petrochemical supply chains through spunlace non-woven substrate pricing into hospital-grade wipe premiums, while biodegradable cellulose alternatives command sourcing premiums that retail channels resist absorbing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for synthetic polyester substrates. Three-tier pricing structure across EPA-registered clinical, commercial-grade, and private-label economy levels separates validated sporicidal claims from unvalidated household formulations. Cost compression in retail channels intensifies because private-label capture accelerates in inflationary consumer environments. Mass-market household buyers exhibit highest price sensitivity; hospital procurement committees locked into GPO contracts show lowest.
Supply Chain Analysis
Regional distribution centers in the United States Midwest and Rhine-Ruhr industrial cluster in Germany anchor hub-and-spoke patterns for institutional-grade wipe fulfillment. Manufacturing concentrates in the United States, China, and Germany for non-woven substrate production. Active ingredient sourcing draws from petrochemical complexes in Texas and Louisiana, plus peracetic acid precursors subject to REACH restrictions. Single-source vulnerability in spunlace cellulose supply threatens biodegradable material transitions. Distribution runs through healthcare GPOs and mass-market retail procurement divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA FIFRA registration timelines in the United States and ECHA REACH reformulation mandates in Germany creates geographic-arbitrage opportunities for multi-registered suppliers with compliance infrastructure spanning both jurisdictions.
For Market Incumbents: Deploy backward integration into spunlace non-woven production to secure biodegradable substrate allocation during demand spikes. Capture GPO contract consolidation by accelerating EPA List K sporicidal validation. Threat of independent wipe converters without captive supply demands preemptive capacity positioning. For New Entrants and Emerging Players: Enter via USDA-inspected food processing facilities lacking standardized wipe protocols compared to healthcare. Target peracetic acid formulation whitespace with validated organic residue claims. Go-to-market leverage rests on direct-to-facility distribution bypassing traditional healthcare supply intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-pathway EPA-FDA compliance complexity fragments vendor qualification timelines. Long-term viability favors specialized clinical-grade formulators with validated supply continuity over commodity retail converters. Acquisition target archetype: mid-scale EPA-registered specialists with biodegradable substrate partnerships. Signal to watch: state-level quaternary ammonium restrictions triggering institutional procurement lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spunlace Production | Kimberly-Clark's captive non-woven supply secures pharmaceutical-grade substrate tiers against allocation risk. |
| EPA List K Sporicidal Registration Investment | Validated C. difficile claims unlock acute care terminal cleaning contracts under OSHA bloodborne pathogen mandates. |
| Biodegradable Cellulose Substrate Partnership | Hospital sustainability mandates in the EU Green Deal and US Northeast accelerate plant-based material transitions. |
| Direct-to-Facility Distribution Channel Development | Bypassing GPO intermediaries captures margin for specialized clinical-grade suppliers in consolidated procurement environments. |
| Peracetic Acid Reformulation for Foodservice | USDA-inspected facilities present whitespace capture opportunity with validated organic residue chemistry claims. |
Research Approach
Bottom-up healthcare procurement modeling reconciled against top-down non-woven substrate production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, GPO contracts managers, EPA regulatory affairs specialists, and spunlace manufacturing plant engineers combined with secondary validation from EPA registration databases, FDA 510(k) filings, hospital procurement databases, and customs trade records. Triangulation across stakeholder inputs and documentary sources anchored volume and value estimates.
Historical trendline analysis of wipe consumption patterns across acute care bed expansion, retail channel velocity, and foodservice hygiene protocol adoption informed projection parameters. Segmentation dimensions modeled include product type tier, use case environment, material substrate category, and distribution channel structure. CAGRs derived from fitted growth curves applied to validated baseline consumption figures, with hospital infection control protocol tightening and biodegradable procurement mandates as key demand drivers across the projection horizon.
Inputs from EPA registration databases and hospital GPO contract disclosures were available through the study window; gaps in real-time spunlace capacity utilization data introduce uncertainty bands around substrate supply assumptions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and procurement centralization trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Continuously Sterilized Product Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Global Potassium Sorbate Market