
 Aerosol Disinfectants Market | 2026-2036
Aerosol Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Disinfectants Market Analysis
Consolidation among healthcare facility buyers is recalibrating procurement leverage across the aerosol disinfectants landscape. Procter & Gamble leverages its institutional distribution networks to sustain shelf presence in hospital supply chains. Reckitt Benckiser Group plc anchors its position through concentrated R&D investment in virucidal formulations. The Clorox Company competes by controlling private-label manufacturing partnerships that extend its reach into cost-sensitive accounts.
Aerosol disinfectants are pressurized formulations typically containing quaternary ammonium compounds, ethanol, or hydrogen peroxide in propellant-driven delivery systems designed for uniform surface coverage without mechanical wiping. These products serve critical infection control functions across healthcare, commercial, and residential environments where rapid pathogen elimination and minimal residue are operational priorities. Disinfectant Sprays dominate value capture given their versatility across healthcare and commercial applications, while Fogging Solutions represent the fastest-expanding segment as automated disinfection protocols gain traction in large-format facilities. Multi-Surface Cleaners occupy a mature margin pool where formulation differentiation has compressed, pushing manufacturers toward specialized virucidal claims to sustain price realization.
The EPA regulates aerosol disinfectants through stringent pesticide registration requirements under FIFRA, mandating efficacy data against specified pathogen classes before market authorization. OSHA's bloodborne pathogen standards and the CDC's healthcare infection control guidelines collectively shape institutional purchasing criteria and product specification thresholds. Ecolab Inc. specializes in navigating this regulatory complexity through dedicated compliance infrastructure that supports co-manufacturing clients. Stakeholders must monitor evolving EPA guidance on emerging pathogens and state-level chemical disclosure mandates that will determine which formulations retain market access across fragmented regulatory jurisdictions.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating compliance requirements for aerosol disinfectant manufacturers serving institutional accounts. Federal purchasing mandates in the United States are reshaping competitive positioning toward EPA-registered, hospital-grade formulations.
Growth Catalysts
- Terminal Cleaning Protocols:Healthcare facilities are mandating aerosol-based terminal disinfection for patient discharge rooms, driving volume through infection control departments.
- EPA Emerging Pathogen Guidance:The agency's framework for virucidal claims is accelerating product registration investments by manufacturers seeking authorized marketing for novel pathogens.
- Fogging Automation:Robotic dispensing systems in large-format facilities are expanding addressable demand beyond manual spray applications into automated protocols.
Market Restraints
- Propellant Cost Volatility:Hydrocarbon and compressed gas propellant prices fluctuate with petrochemical feedstock markets, pressuring formulation economics.
- Registration Timeline Friction:EPA's FIFRA pesticide registration process extends months to years before market authorization, constraining product pipeline velocity.
- Electrostatic Sprayer Substitution:Charged-particle application systems are displacing traditional aerosol delivery in select healthcare environments, threatening share in premium accounts.
Strategic Opportunities
- Long-Term Care Penetration:Skilled nursing facilities remain underpenetrated relative to acute care hospitals, presenting expansion potential for terminal cleaning protocols.
- Green Chemistry Incentives:EPA's Safer Choice program and state-level chemical disclosure mandates are creating preference premiums for hydrogen peroxide-based formulations.
- E-Commerce Channel Development:Direct-to-facility purchasing platforms are disintermediating traditional distribution, enabling margin recovery for compliant manufacturers.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in pressurized delivery systems and virucidal efficacy testing commands premium compensation, constraining R&D scaling.
- Legacy Equipment Integration:Automated fogging systems require retrofitting existing HVAC and fire suppression infrastructure, complicating facility adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Disinfectants Market |
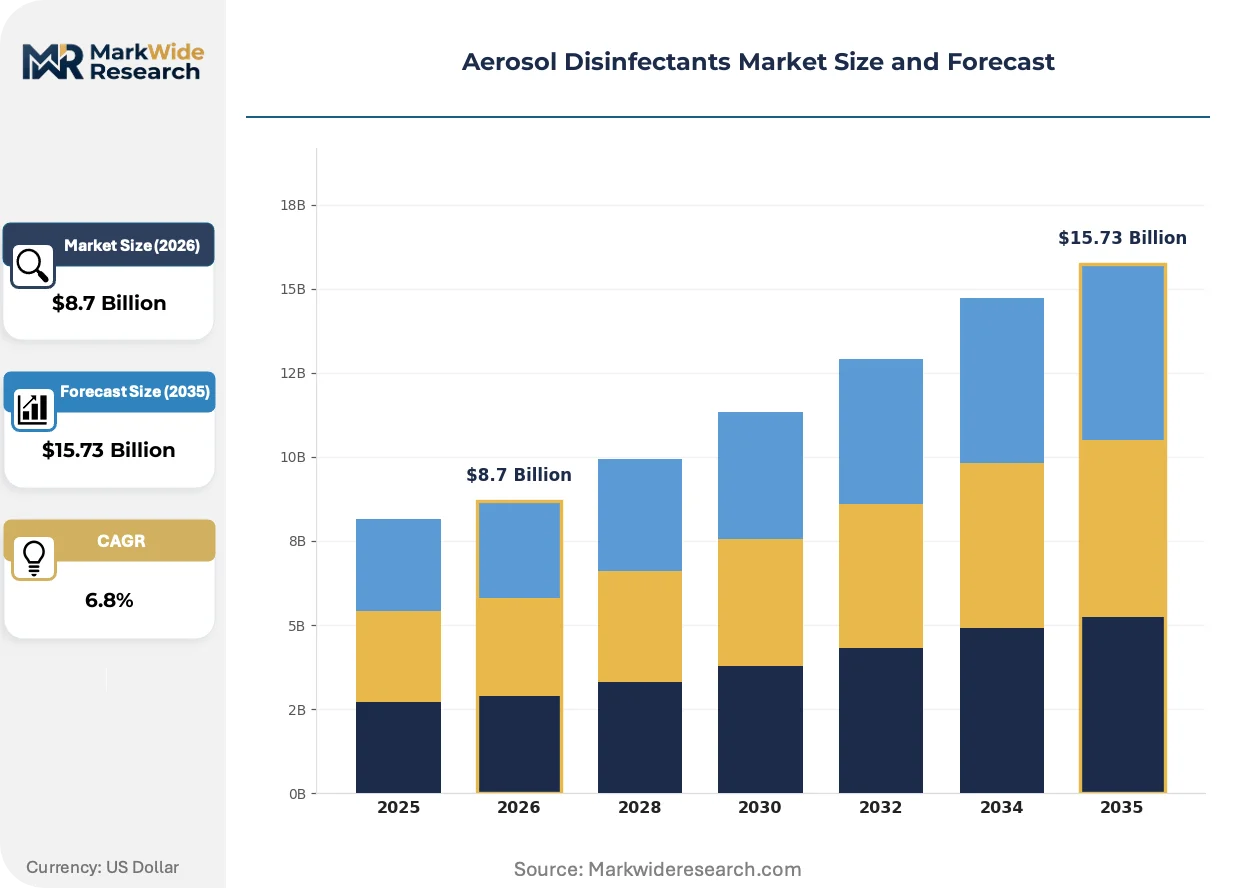
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectant Sprays, Surface Sanitizers, Fogging Solutions, Multi-Surface Cleaners Application: Healthcare Facilities, Residential Use, Commercial Spaces, Automotive End User: Hospitals, Households, Schools, Offices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Procter & Gamble, Reckitt Benckiser Group plc, The Clorox Company, SC Johnson & Son, Ecolab Inc., Henkel AG & Co. KGaA, 3M Company, Diversey Holdings, Zep Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Disinfectants Market Emerging Trajectories
Formulation science and regulatory classification are converging to redefine product positioning in aerosol disinfectants, with sustainability credentials and pathogen specificity emerging as primary differentiation vectors.
Hydrogen peroxide-based aerosol systems are absorbing market attention as healthcare facilities seek residue-minimizing alternatives to quaternary ammonium compounds. Hospital environmental services departments are piloting these formulations in operating suites and isolation rooms. The technology is absorbing share from legacy chemistries by satisfying joint requirements for broad-spectrum efficacy and surface compatibility.
EPA's enforcement of emerging viral pathogen claims is tightening evidentiary standards for product registration. Manufacturers must now submit efficacy data against surrogate viruses before marketing authorization. Hospital-grade aerosol lines face the most acute compliance burden, with reformulation costs concentrating among mid-tier suppliers lacking dedicated regulatory infrastructure.
Group purchasing organizations are consolidating procurement decisions for multi-hospital systems, compressing vendor counts and elevating price transparency. Traditional medical supply distributors are losing volume to integrated delivery networks negotiating direct manufacturer contracts. This concentration is most visible in the United States, where federal contracting vehicles and GPO consolidation have synchronized purchasing cycles across formerly fragmented accounts.
Aerosol Disinfectants Market Segmentation
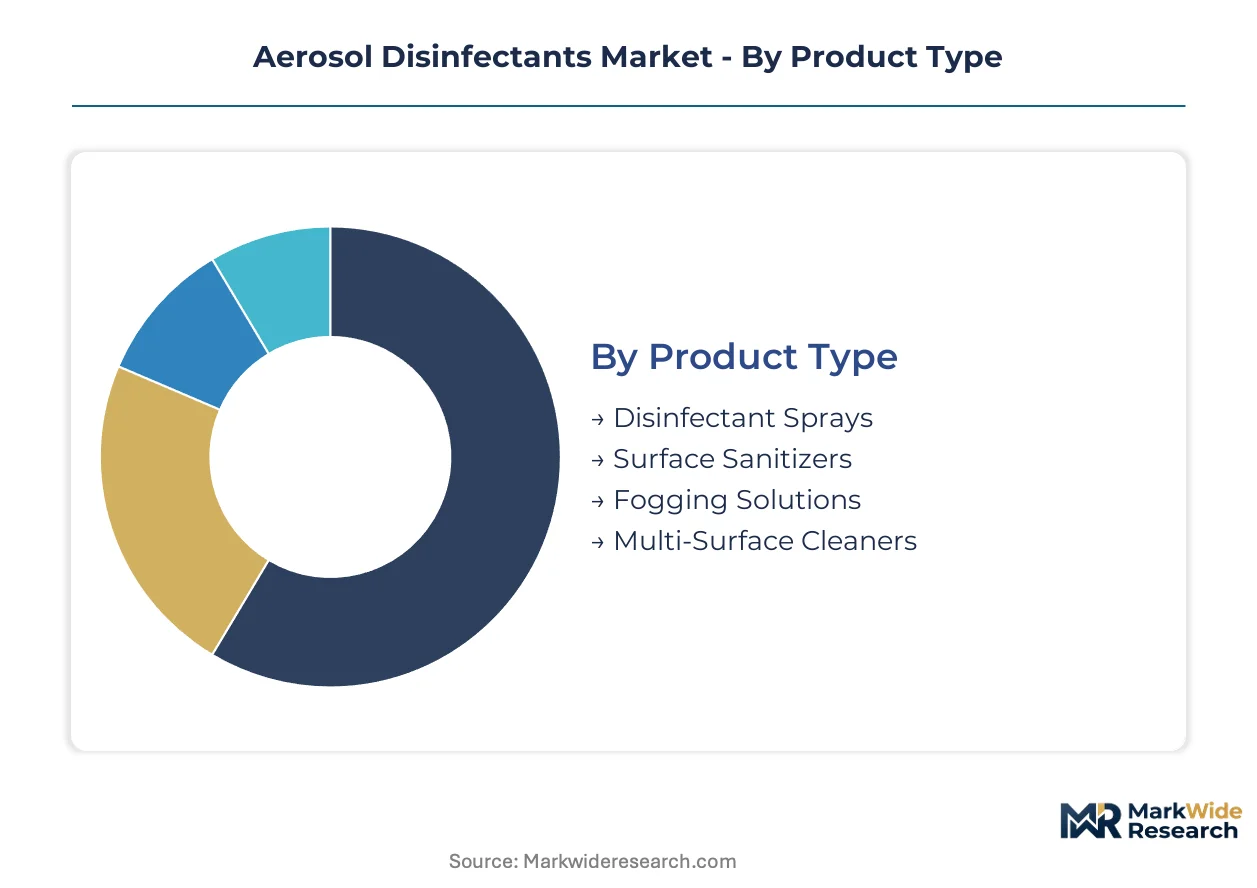
Product differentiation in aerosol disinfectants hinges on delivery mechanism sophistication and surface compatibility requirements. Buyers prioritize EPA registration status, residue profiles, and automation integration potential when segmenting procurement decisions across institutional and consumer channels.
Product Type:
Hospital environmental services departments drive selection based on terminal cleaning throughput requirements and surface material constraints.
- Disinfectant Sprays:Pressurized formulations containing quaternary ammonium compounds or ethanol in hydrocarbon propellant systems. Healthcare facilities in the United States concentrate procurement here, driven by federal purchasing mandates for EPA-registered hospital-grade products.
- Fogging Solutions:Fine-mist delivery systems designed for automated dispensing across large-format spaces. Demand is climbing fastest in skilled nursing facilities and ambulatory surgery centers retrofitting HVAC infrastructure for robotic disinfection protocols.
- Surface Sanitizers:Reduced-claim formulations targeting non-pathogenic microbial reduction on food-contact surfaces.
- Multi-Surface Cleaners:Broad-compatibility formulations with compressed margins where hydrogen peroxide chemistries now command preference premiums.
Volume sits with Disinfectant Sprays; growth tilts toward Fogging Solutions.
Application:
Risk tolerance and regulatory scrutiny intensity separate procurement budgets across use environments.
- Healthcare Facilities:Acute care hospitals, outpatient clinics, and long-term care institutions requiring virucidal efficacy validation. Terminal cleaning protocols in United States federal health systems sustain above-average category velocity through infection control department budgets.
- Residential Use:Consumer households purchasing through retail and e-commerce channels. Formulation simplicity and fragrance profiles outweigh institutional-grade efficacy claims in this cost-sensitive segment.
- Commercial Spaces:Hospitality, retail, and corporate facilities balancing disinfection frequency with operational downtime constraints.
- Automotive:Fleet maintenance and vehicle detailing applications where propellant residue and material compatibility determine product selection.
Revenue concentrates in Healthcare Facilities; expansion potential concentrates in Residential Use.
End User:
Procurement authority and compliance burden distribution shape vendor relationship structures.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidating multi-facility contracts. United States acute care systems leverage federal contracting vehicles to synchronize purchasing cycles and compress vendor counts.
- Households:Individual consumers making fragmented purchase decisions through retail and direct-to-facility platforms.
- Schools:K-12 and higher education institutions with state-mandated disinfection protocols and constrained custodial budgets.
- Offices:Corporate facilities managers balancing employee density with surface turnover requirements.
Margin capture favors Hospitals; volume dispersion characterizes Households.
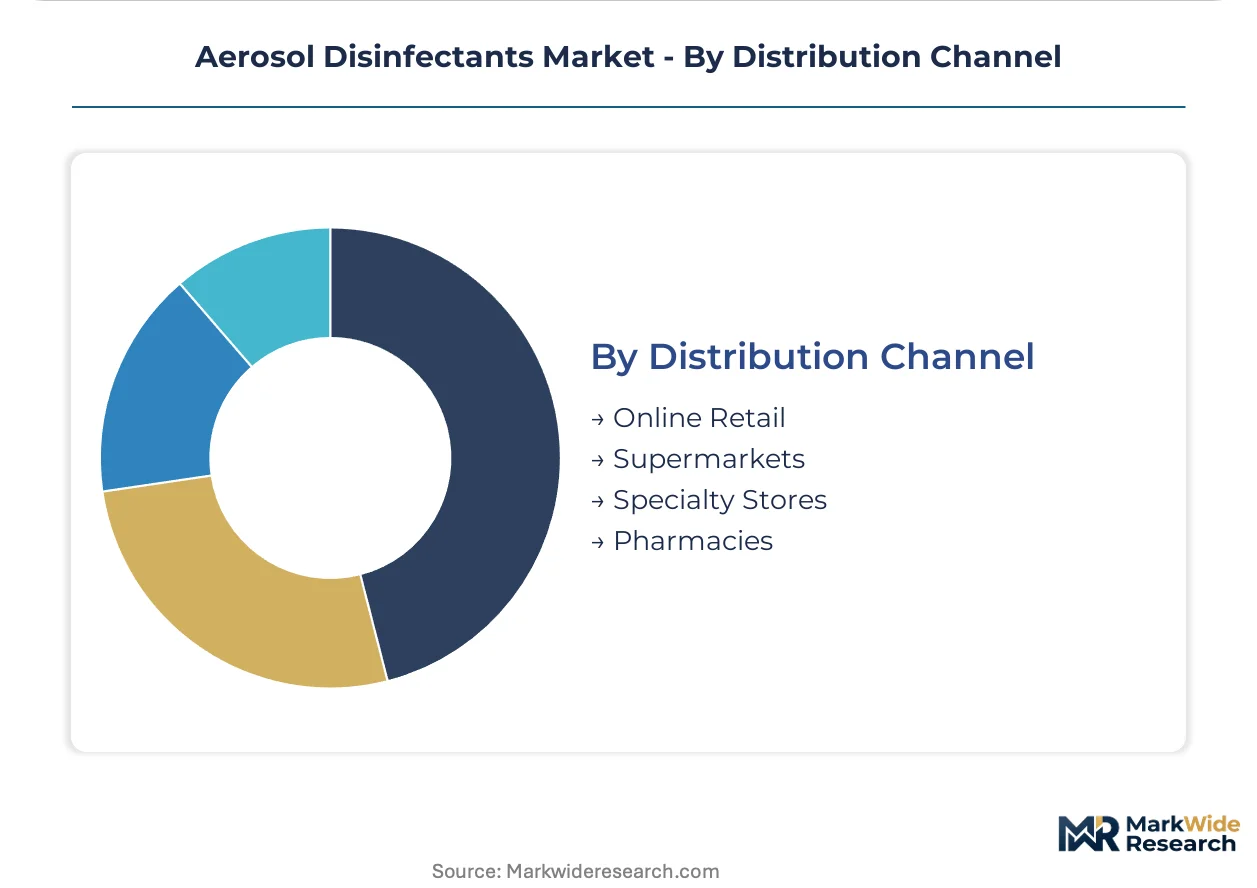
Distribution Channel:
Channel selection determines margin recovery potential and regulatory compliance support availability.
- Online Retail:Direct-to-facility and direct-to-consumer platforms disintermediating traditional medical supply distributors. E-commerce channel development enables margin recovery for compliant manufacturers navigating fragmented state-level chemical disclosure mandates.
- Supermarkets:Mass-market retail placement for consumer-grade formulations with simplified efficacy claims.
- Specialty Stores:Janitorial supply and industrial distribution serving commercial accounts with technical specification support.
- Pharmacies:Healthcare-adjacent retail with institutional buyer crossover and formulary alignment potential.
Share is shifting toward Online Retail; Supermarkets retain mass-market density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement concentration in the United States sustains the largest national market for aerosol disinfectants, with federal purchasing mandates and infection control standards driving above-average category velocity. Regulatory frameworks and facility consolidation patterns vary significantly across major economies, creating distinct competitive environments for manufacturers.
United States
Acute care hospitals and long-term care facilities drive institutional demand through terminal cleaning protocols and infection control department budgets. The EPA's FIFRA pesticide registration requirements and emerging viral pathogen guidance reshape product authorization timelines and compliance investments. Federal contracting vehicles and group purchasing organization consolidation in the Midwest and Southeast synchronize procurement cycles across multi-hospital systems.
Germany
Industrial and healthcare sectors prioritize residue-minimizing hydrogen peroxide formulations amid REACH chemical disclosure mandates and the EU Green Deal sustainability framework. The ECHA regulates biocidal products through the BPR, requiring extensive efficacy documentation before market entry. Manufacturing and R&D activity concentrates in North Rhine-Westphalia and Bavaria, where chemical industry clusters support specialized formulation development.
China
Hospital infrastructure expansion and heightened infection control standards in tier-one cities accelerate demand for automated fogging systems and manual spray applications. The NMPA and MIIT coordinate standards for disinfectant registration under GB requirements, with provincial implementation varying across administrative regions. Production and consumption gravity centers on the Yangtze River Delta and Pearl River Delta, where healthcare facility density and manufacturing capability overlap.
Japan
Aging demographics and hospital consolidation elevate terminal cleaning protocol stringency in acute care and long-term care settings. METI oversees chemical product standards while PMDA guidelines influence healthcare facility procurement specifications. The Kanto region around Tokyo and the Kansai region around Osaka concentrate institutional demand and distribution infrastructure for hospital-grade formulations.
India
Healthcare infrastructure expansion and rising infection control awareness in private hospital chains drive procurement growth for EPA-registered equivalent formulations. The CDSCO and BIS govern disinfectant standards, with state-level procurement variations complicating national market access. Maharashtra and Karnataka host the densest concentrations of hospital and pharmaceutical manufacturing facilities, creating localized demand clusters for institutional-grade products.
Aerosol Disinfectants Market Vendor Landscape
United States producers anchor the premium institutional tier; European specialists hold formulation chemistry advantages. The market exhibits consolidated structure at the top with fragmented mid-tier competition, as regulatory compliance burdens and registration timelines favor established players with dedicated infrastructure. Three archetypes dominate: diversified consumer goods conglomerates with institutional distribution networks, specialized chemical companies with R&D depth in virucidal formulations, and facility services integrators bundling disinfection with broader hygiene management. Competitive moves center on portfolio diversification toward hydrogen peroxide chemistries and strategic partnerships with automated fogging equipment manufacturers.
Among diversified consumer goods conglomerates, Procter & Gamble and Reckitt Benckiser Group plc occupy positions representing institutional distribution scale and concentrated formulation investment respectively. The Clorox Company exemplifies private-label manufacturing leverage extending reach into cost-sensitive accounts. Ecolab Inc. sits within the facility services integration archetype, specializing in regulatory compliance infrastructure that supports co-manufacturing relationships. These named entities represent strategic positioning patterns rather than exhaustive market coverage, with each anchoring distinct competitive vectors in procurement consolidation environments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Reckitt Benckiser Group plc |
| The Clorox Company |
| SC Johnson & Son |
| Ecolab Inc. |
| Henkel AG & Co. KGaA |
| 3M Company |
| Diversey Holdings |
| Zep Inc. |
| Others |
Supply Flow & Price Mechanics
EPA's Safer Choice program gates qualified supply and premium-tier pricing access for hydrogen peroxide-based formulations, compressing margins for quaternary ammonium compound manufacturers while elevating residue-minimizing alternatives. Federal purchasing mandates in the United States synchronize procurement cycles across multi-hospital systems, amplifying price transparency and vendor consolidation pressure.
Pricing Analysis
Volume sits with economy-tier disinfectant sprays while margin capture concentrates in premium fogging solutions with automated dispensing integration. Price differentiation hinges on EPA registration tier and virucidal claim specificity, with hospital-grade formulations commanding substantial premiums over consumer alternatives. Cost compression in the mid-tier is intensifying because group purchasing organizations consolidate vendor counts and standardize specifications. Long-term care facilities exhibit the highest price sensitivity due to constrained custodial budgets, whereas acute care hospitals prioritize efficacy validation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with hydrocarbon propellant suppliers concentrated in the United States Gulf Coast and petrochemical corridors of Germany and China. Active ingredient production draws from quaternary ammonium compound manufacturers in India, ethanol processors in Brazil and the United States, and hydrogen peroxide specialists in Belgium and Japan. Tariff exposure on propellant feedstocks threatens formulation economics across North American production. Distribution runs through integrated delivery networks and group purchasing organizations that disintermediate traditional medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity props pricing for qualified manufacturers, constraining R&D scaling and sustaining margin premiums for incumbents with captive technical expertise.
For Market Incumbents: Hedge against electrostatic sprayer substitution by deepening partnerships with automated fogging equipment manufacturers and accelerating hydrogen peroxide portfolio transitions. Secure backward integration into propellant supply through long-term offtake agreements with Gulf Coast petrochemical producers. EPA registration timeline friction threatens pipeline velocity; invest in dedicated regulatory infrastructure to compress authorization cycles. For New Entrants and Emerging Players: Capture share in skilled nursing facilities and ambulatory surgery centers where terminal cleaning protocols remain underpenetrated relative to acute care hospitals. Target direct-to-facility e-commerce channels that disintermediate established distribution and enable margin recovery despite smaller scale. Lead with green chemistry positioning aligned with state-level chemical disclosure mandates to differentiate from legacy formulations. For Investors and Strategic Acquirers: FDA emergency use authorization for novel pathogen claims is the leading indicator that virucidal formulation specialists will command acquisition premiums. Position for five-to-ten year holding periods centered on regulatory compliance infrastructure as a moat. Monitor EPA enforcement actions on emerging viral pathogen evidentiary standards as the signal for which mid-tier suppliers face existential reformulation costs versus acquisition attractiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Transition | Hydrogen peroxide formulations satisfy EPA Safer Choice and EU REACH mandates while capturing hospital preference premiums. |
| Automated Fogging Partnership | Robotic dispensing integration extends addressable demand beyond manual applications into large-format facility protocols. |
| Regulatory Infrastructure Buildout | Dedicated FIFRA compliance teams compress registration timelines and sustain market access across fragmented state jurisdictions. |
| Direct E-Commerce Channel | Direct-to-facility platforms disintermediate traditional distributors and recover margins for compliant manufacturers. |
| Long-Term Care Penetration | Skilled nursing facilities present expansion potential where terminal cleaning protocols lag acute care adoption. |
Methodological Framework
Independent corroboration across formulation chemists, hospital environmental services directors, and group purchasing organization contract managers underwrites the qualitative findings in this study. Primary fieldwork engaged regulatory affairs specialists at EPA-registered manufacturers, procurement leads at integrated delivery networks, and distribution channel partners in institutional supply chains. Secondary validation drew from EPA pesticide registration databases, FIFRA submission records, hospital procurement contract filings, and customs trade data on propellant feedstock imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, disaggregating volume growth by delivery mechanism sophistication and surface compatibility requirements. Segmentation dimensions modeled include product type tier, end-use environment risk tolerance, procurement authority concentration, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for registration timeline friction and facility adoption curve dynamics. Forecast inputs incorporated propellant cost volatility indices, EPA enforcement pattern shifts, and GPO consolidation trajectories.
The model holds under stable regulatory enforcement intensity and propellant feedstock availability; deviation in EPA emerging pathogen guidance stringency or hydrocarbon supply disruption would shift trajectory bounds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Disinfecting Wipes Market