
 Deltamethrin Market | 2026-2036
Deltamethrin Market Size, Share, and Industry Trends Forecast 2026-2036
Deltamethrin Market Analysis
Agronomic entomology expertise is unwinding capacity constraints across the deltamethrin value chain as specialized formulation knowledge becomes scarcer in mature markets. Bayer CropScience AG leverages its integrated seed-and-crop-protection platform to dominate pyrethroid distribution in Latin American row-crop segments. FMC Corporation anchors North American technical supply through captive active-ingredient manufacturing and EPA-registered formulation facilities. Tagros Chemicals India Ltd. specializes in export-oriented technical-grade production, competing on cost-adjusted purity specifications for African and Southeast Asian markets.
Deltamethrin is a synthetic pyrethroid insecticide with the chemical formula C22H19Br2NO3, characterized by a cis-configuration ester linkage that delivers rapid knockdown against Lepidoptera and Coleoptera pests at application rates typically ranging from 12.5 to 25 grams active ingredient per hectare. The molecule functions as a sodium channel modulator, disrupting insect nervous system signaling for agricultural, veterinary, and public health vector control applications. Agricultural formulations sustain the largest revenue pool given recurring seasonal demand from cotton, soybean, and vegetable protection programs, while residential wettable powders represent the fastest-expanding margin segment as peri-urban pest control services professionalize. Emulsifiable concentrate formulations retain volume leadership in mechanized spray operations, though liquid ready-to-use products are displacing farmer-mixed concentrates in emerging market smallholder segments.
EPA residue tolerance schedules and EU MRL harmonization under EFSA oversight constrain formulation export eligibility and dictate maximum residue limits for food commodities entering transatlantic trade channels. China's MEE enforces GB standard discharge limits on brominated intermediate production, elevating environmental compliance costs for technical-grade manufacturers in Jiangsu province. India's CDSCO and Central Insecticides Board regulate end-use registration timelines, creating staggered market access for new formulation entrants. Stakeholders must monitor evolving bioequivalence requirements for generic deltamethrin registrations as regulatory agencies tighten analytical method specifications for impurity profiling.
Market Dynamics
Agronomic entomology expertise is unwinding capacity constraints across the deltamethrin value chain as specialized formulation knowledge becomes scarcer in mature markets. Supply concentration in South Asian manufacturing clusters is reshaping sourcing patterns for technical-grade active ingredients.
Growth Catalysts
- EPA-registered formulation demand:North American row-crop protection programs sustain recurring seasonal procurement for cotton and soybean applications.
- MEE environmental compliance mandates:China's tightening discharge standards on brominated intermediate production are accelerating technical-grade capacity consolidation in Jiangsu province.
- Peri-urban vector control services:Residential wettable powder demand from professional pest management operators is expanding margin pools in emerging market cities.
Market Restraints
- Brominated intermediate cost volatility:Technical-grade manufacturers face input price pressure from specialty chemical feedstock markets.
- EU F-Gas Regulation restrictions:Formulation export eligibility constraints under EFSA residue tolerance schedules limit transatlantic trade channel access.
- Biological insecticide substitution:Bacillus thuringiensis and spinosad alternatives are capturing share in organic-certified agricultural segments.
Strategic Opportunities
- Brazilian soybean protection expansion:Agricultural pest management programs are scaling deltamethrin procurement for mechanized spray operations in Mato Grosso.
- India PLI scheme incentives:Domestic formulation manufacturing subsidies are attracting technical-grade investment into Gujarat contract manufacturing clusters.
- Microencapsulation technology convergence:Controlled-release polymer systems combined with precision application equipment are opening premium formulation tiers.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in emulsifiable concentrate stability and adjuvant compatibility is retiring from European and North American R&D facilities.
- CDSCO registration timeline compression:India's Central Insecticides Board bioequivalence requirements for generic deltamethrin are extending market access timelines for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deltamethrin Market |
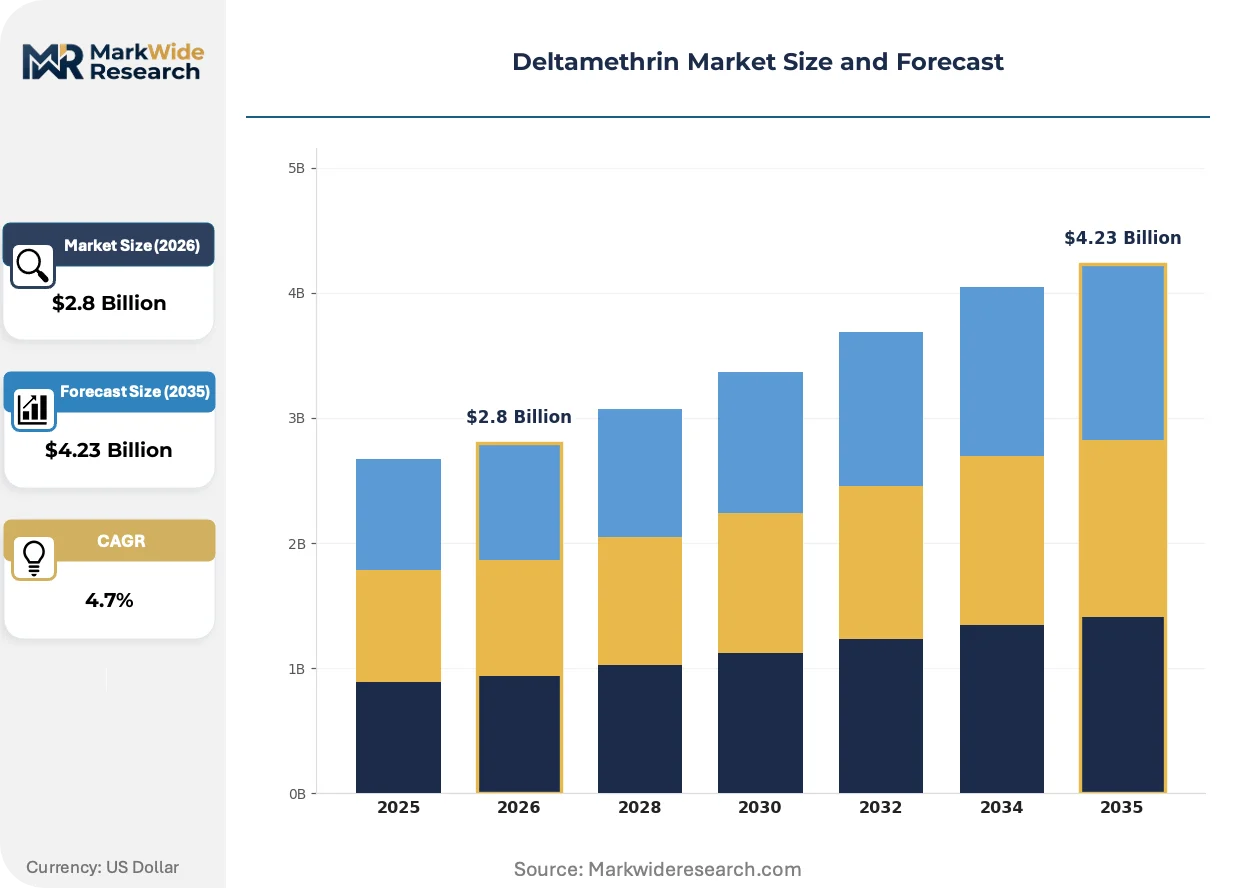
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural, Residential, Veterinary, Industrial Formulation Type: Emulsifiable Concentrate, Wettable Powder, Granules, Liquid Application Method: Spray, Drench, Granular, Fogging End User: Agriculture, Pest Control Companies, Homeowners, Commercial Establishments |
| Companies Covered | Bayer CropScience AG, FMC Corporation, Nufarm Limited, Heranba Industries Ltd., Tagros Chemicals India Ltd., Rotam, Virbac, Jiangsu Yangnong Chemical, Gharda Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deltamethrin Market Emerging Trajectories
Formulation technology and regulatory compliance architectures are actively restructuring competitive positioning in pyrethroid insecticide markets. Product evolution, policy harmonization, and procurement model changes are converging to reshape value capture.
Microencapsulation polymer systems are decomposing traditional emulsifiable concentrate volume leadership by enabling extended residual activity at reduced application rates. Large-scale agricultural cooperatives in Brazil and Argentina are adopting these formulations for soybean rust vector suppression. The technology is decomposing farmer-mixed concentrate preparation habits and compressing pricing power for standard wettable powder suppliers.
EU F-Gas Regulation alignment with EFSA MRL harmonization is tightening maximum residue limit enforcement for food commodities entering European trade channels. Technical-grade manufacturers in Jiangsu province are retrofitting brominated intermediate production lines to meet GB standard discharge limits. Formulation exporters targeting German and French agricultural markets are reconfiguring impurity profiling analytical methods to satisfy tightened bioequivalence specifications.
Smallholder cooperatives are consolidating input purchasing through digital procurement platforms that disintermediate traditional agrochemical distributors. Vegetable protection programs in Vietnam and Indonesia are migrating toward liquid ready-to-use products that eliminate farmer mixing errors. This channel shift is most visible in peri-urban production zones surrounding Ho Chi Minh City and Jakarta where professional spray service providers specify pre-formulated solutions.
Deltamethrin Market Segmentation
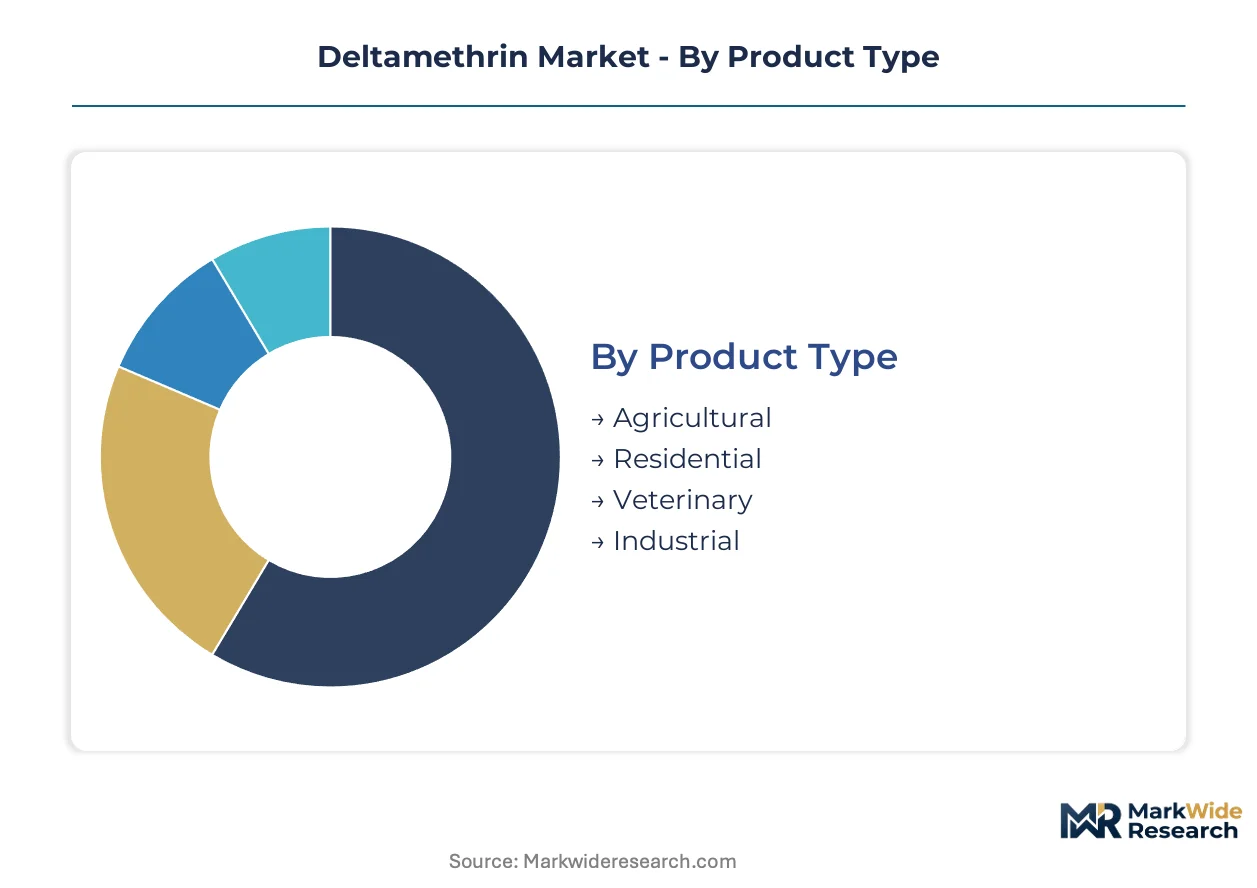
Formulation chemistry and application method dictate margin architecture across deltamethrin value chains. Segmentation reveals where biological substitutes exert maximum pressure and where technical-grade sourcing advantages concentrate procurement power.
Product Type:
Biological insecticide substitution threatens agricultural and residential segments most acutely, while veterinary and industrial applications retain synthetic pyrethroid dependency due to regulatory registration barriers for alternatives.
- Agricultural:Cotton, soybean, and vegetable protection programs drive recurring seasonal procurement in Brazil and India. Bacillus thuringiensis alternatives capture share in organic-certified segments, compressing standard formulation pricing power in Mato Grosso and Gujarat.
- Residential:Peri-urban pest management operators in Ho Chi Minh City and Jakarta specify wettable powders for vector control services. Professionalization of spray services is displacing homeowner-mixed concentrates and opening premium margin tiers.
- Veterinary:Ectoparasite control formulations for livestock and companion animals face limited biological substitute penetration due to efficacy requirements.
- Industrial:Stored grain protection and timber treatment applications sustain technical-grade demand with stable specification requirements.
Agricultural anchors the volume base while residential gains share at the steepest rate.
Formulation Type:
Cost tier stratification separates mechanized spray operations from smallholder convenience segments, with polymer technology disrupting traditional concentrate economics.
- Emulsifiable Concentrate:Mechanized cotton and soybean spraying in Brazil and Argentina sustains volume leadership through established adjuvant compatibility and tank-mix flexibility with fungicides.
- Wettable Powder:Professional pest control operators in peri-urban Southeast Asian markets favor pre-packaged dosing accuracy over farmer-mixed alternatives, expanding margin pools in Vietnam and Indonesia.
- Granules:Soil-applied formulations target root-feeding Coleoptera in vegetable protection programs with extended residual requirements.
- Liquid:Ready-to-use products eliminate mixing errors for smallholder cooperatives consolidating purchases through digital procurement platforms.
Emulsifiable concentrate retains the largest revenue pool while liquid formulations climb the fastest.
Application Method:
Customer type determines equipment investment thresholds, with spray infrastructure concentrating among agricultural cooperatives and fogging systems dominating municipal vector control.
- Spray:Ground-based hydraulic and aerial application equipment dominates mechanized row-crop protection in Brazil's Cerrado region, requiring formulation stability under high-volume, low-drift parameters.
- Drench:Root-zone applications for soil-dwelling pests in vegetable production systems demand solubility profiles distinct from foliar formulations.
- Granular:Pre-plant incorporation methods for termite and rootworm control sustain steady demand in specialty crop segments.
- Fogging:Thermal and cold fogging equipment for adult mosquito control in municipal programs operates on ultra-low volume specifications with specific droplet size requirements.
Spray operations anchor the installed equipment base while fogging expands most quickly in urban vector control budgets.
End User:
Volume concentration among large-scale agricultural operators contrasts with margin capture in professional service channels where technical expertise commands premium pricing.
- Agriculture:Large-scale cooperatives in Mato Grosso and Gujarat consolidate procurement through direct manufacturer relationships, compressing distributor margins while scaling technical-grade volume.
- Pest Control Companies:Professional operators in peri-urban Indonesian and Vietnamese markets specify pre-formulated solutions and bundle application services, capturing value beyond commodity chemistry.
- Homeowners:Retail channel consumers in emerging market cities shift toward ready-to-use convenience formats as urban pest concerns intensify.
- Commercial Establishments:Food processing and hospitality sectors face stringent residue compliance requirements under EFSA and FDA tolerance schedules, favoring certified formulation suppliers.
Agriculture commands the volume base while pest control companies achieve the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA residue tolerance schedules in the United States anchor the regulatory framework that shapes transatlantic trade eligibility for deltamethrin formulations. Brazil's agricultural pest management programs drive procurement volume for soybean protection. China's MEE discharge mandates and India's CDSCO registration timelines create staggered compliance requirements across manufacturing clusters.
Brazil
Mechanized soybean spraying operations in Mato Grosso sustain recurring seasonal demand for emulsifiable concentrate formulations. ANVISA pesticide registration requirements dictate bioequivalence specifications for generic deltamethrin entrants. Agricultural cooperatives in the Cerrado region consolidate procurement through direct manufacturer relationships, compressing traditional distributor margins.
China
Brominated intermediate production for technical-grade active ingredients concentrates in Jiangsu province manufacturing facilities. MEE environmental compliance mandates enforce GB standard discharge limits on chemical production lines. Retrofitting investments in Yangtze River Delta chemical parks are elevating environmental compliance costs for export-oriented suppliers.
India
Cotton protection programs in Gujarat and Maharashtra drive contract manufacturing demand for export-oriented technical-grade production. CDSCO and Central Insecticides Board registration timelines create staggered market access for new formulation entrants. Domestic formulation manufacturing subsidies under the PLI scheme are attracting technical-grade investment into Gujarat chemical clusters.
United States
North American row-crop protection programs sustain EPA-registered formulation demand for cotton and soybean applications. EPA residue tolerance schedules constrain export eligibility for food commodities entering transatlantic trade channels. Formulation facilities in agricultural belt states maintain captive active-ingredient supply relationships with technical-grade manufacturers.
Germany
EFSA maximum residue limit harmonization under EU F-Gas Regulation alignment dictates formulation export specifications for European agricultural markets. REACH compliance requirements shape impurity profiling analytical methods for technical-grade suppliers. Bayer CropScience AG leverages integrated seed-and-crop-protection platforms to dominate pyrethroid distribution across continental row-crop segments.
Deltamethrin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the deltamethrin value chain, with formulation expertise and captive technical supply creating separation. The upper tier combines seed-and-crop-protection platforms with EPA-registered manufacturing infrastructure, while mid-tier specialists compete on cost-adjusted purity specifications for export markets. Three archetypes dominate: integrated agrochemical conglomerates with captive active-ingredient production, export-oriented technical-grade specialists in South Asian manufacturing clusters, and regional formulation distributors serving peri-urban pest control channels. Capacity consolidation and microencapsulation technology licensing represent the primary competitive moves reshaping positioning.
Among integrated agrochemical conglomerates, Bayer CropScience AG and FMC Corporation exemplify the captive-supply archetype through combined technical manufacturing and formulation registration assets. Tagros Chemicals India Ltd. occupies a position within the export-oriented specialist tier, competing on technical-grade purity specifications for African and Southeast Asian markets. These three entities represent the dominant competitive anchors across the value chain's vertical tiers.
| Leading Market Players |
|---|
| Bayer CropScience AG |
| FMC Corporation |
| Nufarm Limited |
| Heranba Industries Ltd. |
| Tagros Chemicals India Ltd. |
| Rotam |
| Virbac |
| Jiangsu Yangnong Chemical |
| Gharda Chemicals |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Brazilian agricultural cooperatives and technical-grade manufacturers lock in both brominated intermediate supply access and eighteen-month price visibility for emulsifiable concentrate formulations. These contracts insulate Mato Grosso soybean protection programs from spot market volatility in Jiangsu province while compressing margins for non-integrated distributors.
Pricing Analysis
Price spreads between Gujarat technical-grade exports and Brazilian formulated products exceed transport and tariff differentials, reflecting captive manufacturing premiums. Three-tier pricing structure across microencapsulated premium, standard emulsifiable concentrate, and economy wettable powder levels segments buyer archetypes by application scale. Cost compression in standard concentrates is intensifying as biological insecticide alternatives capture organic-certified share. Smallholder cooperatives consolidating through digital procurement platforms exhibit highest price sensitivity, while peri-urban pest control operators in Jakarta and Ho Chi Minh City prioritize dosing accuracy over unit cost.
Supply Chain Analysis
Inventory buffers for brominated intermediates have compressed to six-week cycles as Jiangsu province manufacturers retrofit lines for MEE GB standard compliance. Technical-grade production draws from India, China, and Brazil, with formulation finishing concentrated in agricultural belt states and Southeast Asian contract facilities. Single-source vulnerability concentrates in specialty chemical feedstock markets for brominated inputs. Distribution runs through agricultural cooperative procurement platforms and peri-urban professional spray service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the deltamethrin value chain creates niche entry points as formulation chemist expertise retires from European and North American R&D facilities, opening specialized service gaps for new technical-grade entrants.
For Market Incumbents: Fortify captive brominated intermediate supply through backward integration into Jiangsu province chemical parks or long-term offtake partnerships with MEE-compliant facilities. Lock in formulation chemist talent through acquisition of retiring European expertise pools before biological insecticide substitution accelerates in organic-certified segments. For New Entrants and Emerging Players: CDSCO fast-track registration pathways for generic deltamethrin bioequivalence specifications offer the most penetrable entry point into Indian cotton protection programs. Target peri-urban vector control services in Indonesian and Vietnamese secondary cities where professional spray operators specify pre-formulated liquid ready-to-use products. Partner with digital procurement platforms serving smallholder cooperatives to bypass traditional agrochemical distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward export-oriented technical-grade specialists with MEE-compliant Jiangsu facilities and established African and Southeast Asian customer relationships. The five-to-ten year viability window favors manufacturers with backward integration into brominated intermediate production. Monitor CDSCO registration timeline compression as the inflection signal for generic formulation market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brominated Intermediates | Captive supply secures MEE-compliant technical-grade capacity in Jiangsu province chemical parks. |
| Microencapsulation Technology Licensing | Controlled-release polymer systems open premium tiers for Brazilian soybean rust vector suppression. |
| CDSCO Fast-Track Registration Investment | Accelerated bioequivalence pathways compress market access timelines for generic deltamethrin entrants. |
| Digital Procurement Platform Partnership | Direct smallholder cooperative relationships disintermediate traditional agrochemical distribution channels. |
| Peri-Urban Spray Service Network Expansion | Professional pest control operators in Jakarta and Ho Chi Minh City command premium margin capture. |
Methodological Framework
Desk research of customs trade databases, CDSCO registration filings, and MEE discharge compliance records preceded structured interviews with plant managers at Jiangsu province technical-grade facilities, procurement leads at Brazilian agricultural cooperatives, formulation R&D directors, and peri-urban pest control operators in Southeast Asian cities. Primary fieldwork with EPA-registered formulation facilities and Central Insecticides Board officials was cross-validated against secondary sources including SEC 10-K disclosures from listed agrochemical conglomerates and ANVISA pesticide registration databases. Bottom-up volume modeling triangulated with top-down value chain analysis.
Variance decomposition across product type, formulation chemistry, application method, and end-user archetype segments shaped the analytical framework throughout the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking regulatory compliance cost trajectories. Modeled inputs included MEE retrofit investment cycles, CDSCO registration queue lengths, and biological insecticide substitution rates in organic-certified agricultural segments.
Decision-makers should treat outputs as directional under assumptions of stable EPA residue tolerance schedules and continued MEE enforcement intensity; material deviation in regulatory stringency or biological substitute efficacy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Diquat Dibromide Market