
 US Surface Disinfectant Market | 2026-2036
US Surface Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
US Surface Disinfectant Market Intelligence
US Gulf Coast chemical manufacturing capacity is reconfiguring the domestic supply base for surface disinfectant active ingredients. The Clorox Company leverages its integrated bleach production network to anchor cost positions in sodium hypochlorite formulations. Ecolab competes through specialized healthcare channel relationships that sustain premium placement in hospital system contracts. 3M differentiates via technology leadership in quaternary ammonium compound delivery systems for institutional applications.
Surface disinfectants are antimicrobial chemical formulations designed to eliminate or inactivate pathogenic microorganisms on non-porous environmental surfaces, typically containing active concentrations between 0.5% and 5.0% by weight depending on the biocidal mechanism. These products serve primarily to interrupt nosocomial transmission chains in healthcare settings and maintain sanitary conditions in commercial foodservice and public accommodation environments. Quaternary ammonium compounds occupy the largest volume position due to their favorable safety profile and material compatibility, while hydrogen peroxide formulations represent the fastest-expanding category as facilities seek alternatives to chlorine-based chemistries amid respiratory irritation concerns. Aerosol and wipe formulations command margin premiums over liquid concentrates because of labor cost savings in high-frequency application settings.
EPA regulates surface disinfectants under FIFRA as pesticides, requiring extensive efficacy data and label claims verification before market entry, while OSHA bloodborne pathogen standards mandate disinfectant availability in workplace exposure control plans. FDA oversight intersects for disinfectants claiming compatibility with medical devices, creating dual jurisdictional compliance requirements that shape product development timelines. State-level health department adoption of CDC infection control guidelines further standardizes procurement specifications across hospital systems. Stakeholders must monitor evolving EPA guidance on per- and polyfluoroalkyl substance contamination in disinfectant supply chains and position formulation portfolios accordingly.
Market Dynamics
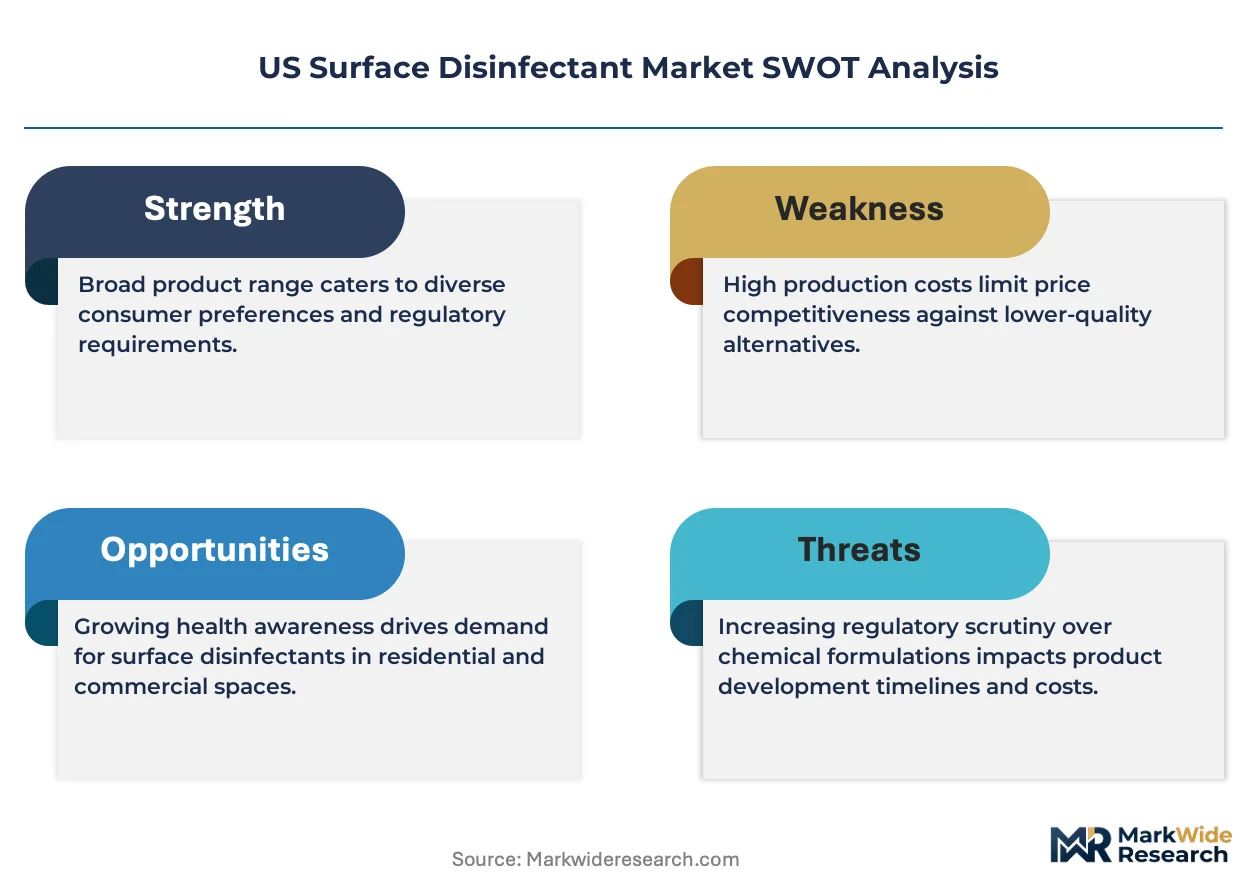
Permanent infection control protocols in US hospitals are institutionalizing higher disinfectant consumption baselines, while EPA registration timelines for emerging pathogen claims compress product development cycles and favor incumbents with established regulatory infrastructure.
Growth Catalysts
- OSHA bloodborne pathogen mandates:Workplace exposure control plans require disinfectant availability across healthcare and commercial settings, creating baseline demand floors that persist regardless of epidemic cycles.
- Quaternary ammonium compound material compatibility:Hospital facilities prioritize surface-safe chemistries that reduce equipment corrosion and extend asset life, driving preference for QAC-based formulations over chlorine alternatives.
- Midwest and Southeast hospital construction:New acute care facility development in these regions expands addressable institutional demand for bulk disinfectant supply contracts.
Market Restraints
- Sodium hypochlorite feedstock volatility:Gulf Coast chlorine production capacity constraints and energy input costs create margin pressure for bleach-based formulation manufacturers.
- EPA FIFRA registration timelines:Efficacy data requirements and label claims verification processes extend product commercialization cycles to 18-24 months, delaying revenue realization for novel active ingredients.
- Peracetic acid substitution threat:Food processing and pharmaceutical cleanroom applications increasingly specify peracetic acid systems for sporicidal efficacy, eroding hydrogen peroxide growth potential in these segments.
Strategic Opportunities
- Long-term care facility underpenetration:Nursing homes and assisted living operators lag hospitals in automated dispensing adoption, presenting white space for wipe and aerosol format expansion.
- EPA emerging pathogen protocol acceleration:Streamlined registration pathways for SARS-CoV-2 and future viral threats enable faster label expansion and premium positioning for prepared manufacturers.
- E-commerce channel consolidation:Direct procurement platforms serving mid-sized outpatient clinics and dental practices bypass traditional distribution markups, capturing margin pool previously allocated to regional distributors.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in biocidal stability and surface adhesion science commands premium compensation, constraining R&D throughput for mid-tier manufacturers.
- Legacy dispensing system integration:Hospital capital equipment refresh cycles for electrostatic sprayers and dilution control systems lag behind new chemistry introductions, creating adoption friction for novel delivery formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Surface Disinfectant Market |
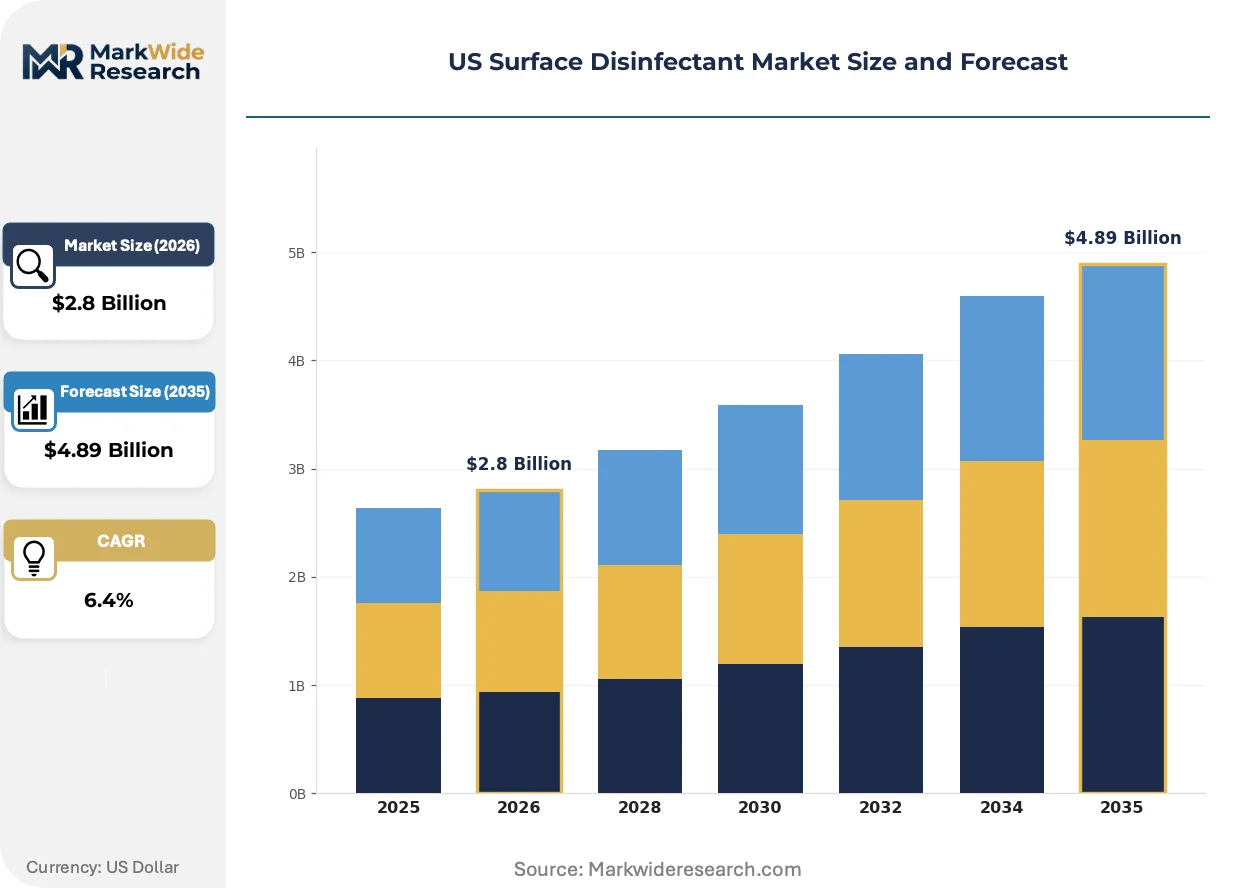
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Alcohol-Based, Hydrogen Peroxide, Sodium Hypochlorite Application: Healthcare Facilities, Commercial Spaces, Residential Use, Educational Institutions Formulation: Aerosol, Liquid Concentrate, Wipes, Foam End User: Hospitals, Restaurants, Office Buildings, Retail Outlets |
| Companies Covered | Procter & Gamble, The Clorox Company, 3M, Ecolab, Reckitt Benckiser Group PLC, GOJO Industries, STERIS, SC Johnson Professional, PDI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Surface Disinfectant Market Strategic Shifts & Innovations
Formulation science is converging with application technology to reduce labor burden and respiratory exposure in high-frequency disinfection environments, reshaping how facilities evaluate total cost of ownership.
Electrostatic spray technology is hybridizing liquid disinfectant application methods by imparting positive charge to droplets that wrap around complex surface geometries. Ambulatory surgical centers and school districts are adopting these systems at accelerating rates to reduce labor hours per square foot. The technology is compressing demand for manual wipe formats in large-area applications while expanding addressable use cases beyond traditional healthcare settings.
EPA guidance on per- and polyfluoroalkyl substance contamination is tightening raw material sourcing requirements for disinfectant supply chains. Manufacturers must now document PFAS absence in surfactants and stabilizers, extending qualification timelines for new suppliers. Formulation portfolios containing fluorinated compounds face reformulation pressure, particularly in institutional contracts with sustainability procurement criteria.
Hospital system buying cooperatives are consolidating purchasing volume through shared services organizations that negotiate multi-year supply agreements. Regional GPOs displace independent distributor relationships, extracting price concessions in exchange for sole-source or dual-source commitments. This concentration is most visible in the Southeast, where health system mergers have created super-regional entities controlling dozens of acute care facilities under unified procurement authority.
US Surface Disinfectant Market Segmentation
Surface disinfectant procurement decisions in the US diverge sharply across facility types, with hospitals prioritizing sporicidal efficacy while commercial buyers optimize for labor efficiency. Product chemistry and delivery format combinations determine contract eligibility for institutional buyers operating under EPA FIFRA and OSHA compliance frameworks.
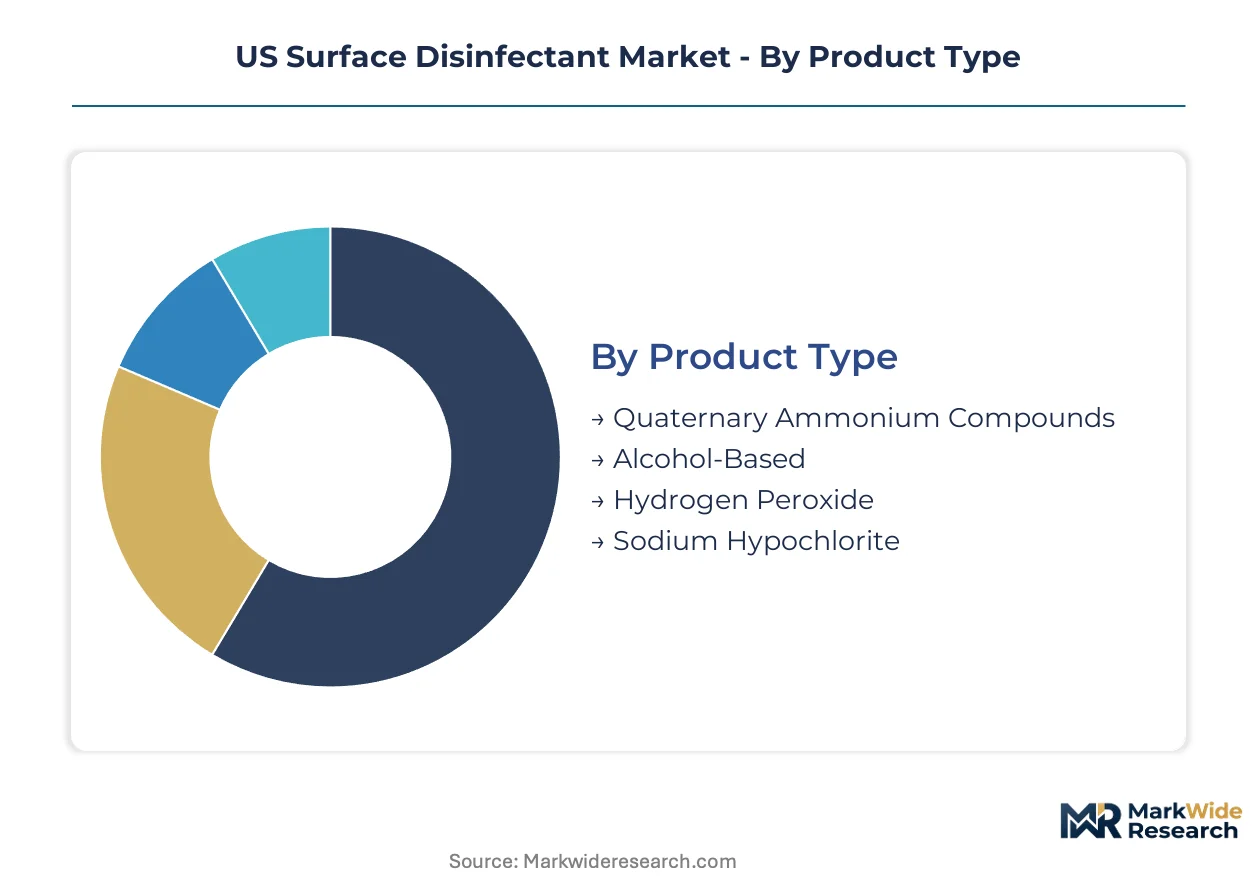
Product Type:
Cost tier stratification separates commodity chlorine chemistry from premium peroxide and QAC formulations competing on material compatibility.
- Quaternary Ammonium Compounds:Cationic surfactant formulations typically blended at 0.5% to 2.0% active concentration deliver broad-spectrum bactericidal action with minimal corrosion risk. Southeast hospital systems specify QAC chemistries for electronic medical equipment disinfection, prioritizing surface preservation over sporicidal speed.
- Hydrogen Peroxide:Oxidative formulations at 3% to 7.5% concentration decompose to water and oxygen, eliminating residual toxicity concerns. Midwest long-term care facilities are expanding hydrogen peroxide adoption amid respiratory sensitivity complaints from chlorine alternatives.
- Alcohol-Based:Ethanol and isopropanol blends at 60% to 80% concentration provide rapid evaporation for high-frequency touchpoint protocols.
- Sodium Hypochlorite:Bleach solutions at 0.5% to 5.0% available chlorine remain the lowest-cost option for environmental surface decontamination.
Quaternary Ammonium Compounds hold installed capacity. Hydrogen Peroxide is rotating up the share rankings.
Application:
End-use concentration maps directly to regulatory stringency, with healthcare settings commanding formulation sophistication beyond commercial or residential demand.
- Healthcare Facilities:Acute care hospitals, ambulatory surgery centers, and outpatient clinics require EPA-registered hospital-use disinfectants with documented efficacy against bloodborne pathogens. Midwest and Southeast states concentrate procurement volume through consolidated health system contracts.
- Commercial Spaces:Hospitality, transportation, and public venue operators balance disinfection frequency against labor cost, driving preference for fast-evaporation formats.
- Residential Use:Consumer households purchase lower-concentration formulations through retail channels with simplified label instructions.
- Educational Institutions:K-12 districts and university facilities specify products compatible with daily high-touch surface protocols in shared environments.
Healthcare Facilities anchor volume concentration. Commercial Spaces are gaining share fastest on post-pandemic protocol permanence.
Formulation:
Delivery format selection determines labor economics and respiratory exposure profiles in high-frequency application environments.
- Wipes:Pre-saturated nonwoven substrates eliminate dilution control errors and reduce worker chemical exposure. Hospital environmental services departments in the Southeast specify wipe formats for terminal cleaning of patient rooms.
- Liquid Concentrate:Dilution-control systems deliver cost efficiency for large-footprint facilities with dedicated housekeeping infrastructure.
- Aerosol:Pressurized spray formats enable rapid coverage of complex geometries in equipment-dense environments.
- Foam:Clinging formulations extend contact time on vertical surfaces and equipment with irregular contours.
Wipes command premium placement in acute care. Aerosol is climbing the fastest on electrostatic spray technology adoption.
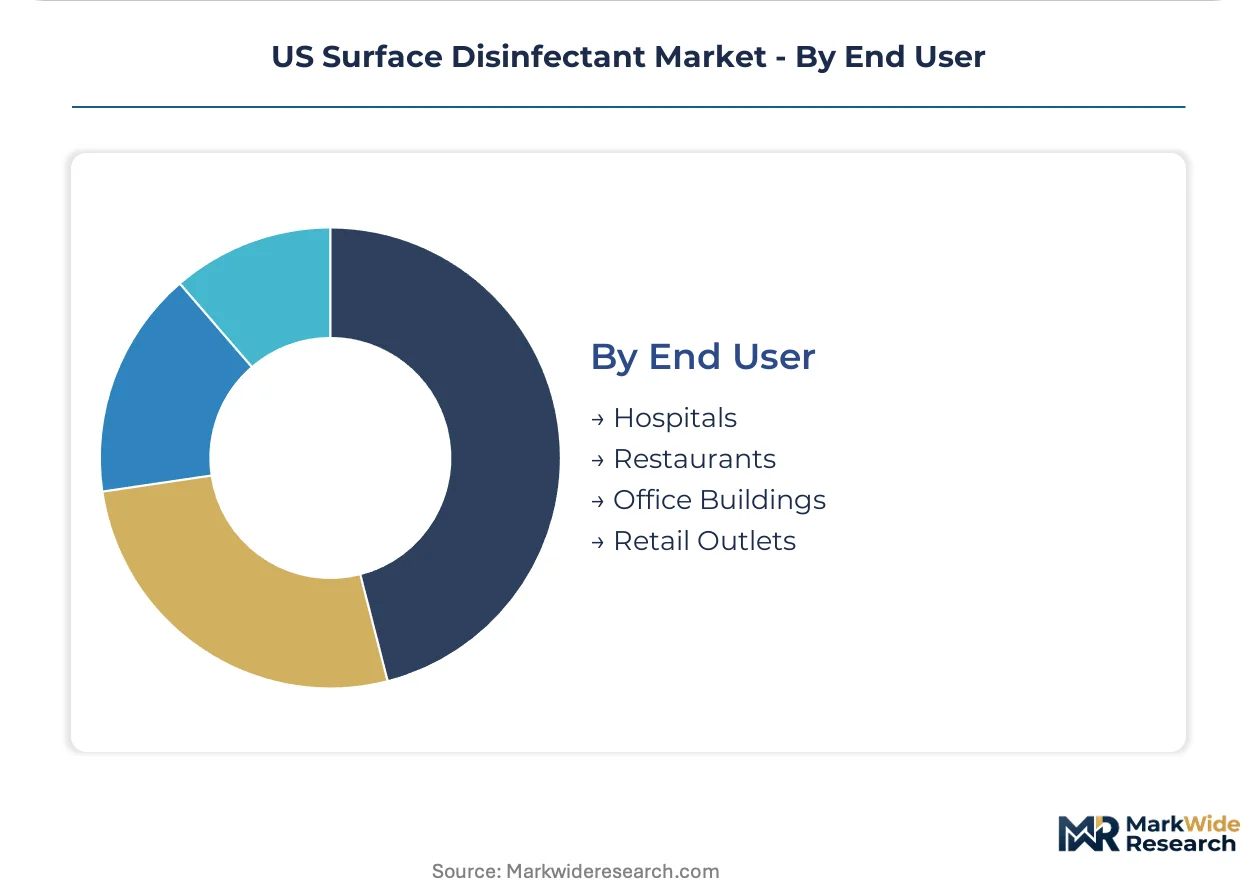
End User:
Customer type dictates contract structure, with hospitals negotiating multi-year supply agreements while fragmented commercial buyers purchase through distribution.
- Hospitals:Integrated delivery networks and academic medical centers procure through GPO-negotiated contracts with sole-source or dual-source commitments. EPA emerging pathogen label claims determine vendor qualification for federal preparedness stockpiles.
- Restaurants:Foodservice operators specify no-rinse formulations compliant with FDA food contact surface regulations.
- Office Buildings:Facility management companies prioritize bulk liquid concentrates for cost control across multi-site portfolios.
- Retail Outlets:Big-box and grocery chains balance visible sanitation protocols against per-square-foot supply cost targets.
Hospitals concentrate procurement authority. Restaurants are expanding specification sophistication on health department inspection alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns in the US vary sharply by sub-region, with the Southeast and Midwest driving institutional volume through health system consolidation while the Northeast and West Coast emphasize sustainability-certified formulations.
Southeast
Florida and Georgia health systems are consolidating procurement through shared services organizations covering dozens of acute care facilities. EPA FIFRA registration requirements for emerging pathogen claims determine vendor qualification for federal preparedness stockpiles. Atlanta anchors super-regional distribution networks serving consolidated hospital networks across the Carolinas and Tennessee.
Midwest
Illinois, Michigan, and Ohio are expanding acute care facility construction and environmental services staffing. OSHA bloodborne pathogen mandates enforce disinfectant availability across workplace exposure control plans. Chicago-based GPOs negotiate multi-year supply agreements controlling procurement for health systems spanning the Great Lakes region.
Southwest
Texas and Arizona long-term care facilities are accelerating adoption of hydrogen peroxide formulations amid respiratory sensitivity complaints. State health departments adopt CDC infection control guidelines standardizing procurement specifications. Houston Gulf Coast chemical manufacturing capacity is reconfiguring domestic supply bases for active ingredients.
Northeast
New York and Massachusetts hospital systems prioritize PFAS-free formulations in sustainability procurement criteria. EPA guidance on per- and polyfluoroalkyl substance contamination tightens raw material sourcing requirements. Boston academic medical centers specify quaternary ammonium compounds for electronic medical equipment disinfection.
Pacific Coast
California and Washington ambulatory surgical centers are adopting electrostatic spray technology at accelerating rates. FDA oversight intersects with EPA FIFRA for disinfectants claiming medical device compatibility. Los Angeles and Seattle distribution hubs serve outpatient clinic networks emphasizing labor-efficient application formats.
US Surface Disinfectant Market Key Industry Players
Capability concentration sits with integrated chemical manufacturers possessing captive bleach production networks; scale advantage sits with diversified hygiene companies leveraging cross-category distribution infrastructure. The market structure tiers between premium-positioned healthcare specialists and cost-anchored commodity suppliers. Three archetypes dominate: integrated chemical producers with upstream active ingredient control, healthcare channel specialists with GPO-negotiated contracts, and diversified consumer goods companies with retail scale. Competitive moves center on electrostatic spray technology partnerships and PFAS-free formulation pipelines.
Among integrated chemical manufacturers, The Clorox Company and Ecolab occupy positions representing opposing strategic vectors—one anchored in commodity bleach production scale, the other in healthcare channel premium placement. 3M exemplifies technology-led differentiation through delivery system innovation. These three entities illustrate how regulatory infrastructure and application technology respectively defend margin position in institutional contracting.
| Leading Market Players |
|---|
| Procter & Gamble |
| The Clorox Company |
| 3M |
| Ecolab |
| Reckitt Benckiser Group PLC |
| GOJO Industries |
| STERIS |
| SC Johnson Professional |
| PDI |
| Others |
Cost & Logistics Intelligence
Houston Ship Channel freight corridors anchor cost dynamics for Gulf Coast chlorine derivatives, concentrating supply-side leverage among integrated producers while downstream price differentiation widens between bulk institutional contracts and premium wipe formats.
Pricing Analysis
Midwest hospital systems pay 15-20% premiums over Southeast spot markets for EPA-registered hospital-use formulations with emerging pathogen claims. Three-tier pricing structure separates sporicidal peroxide blends from standard QAC formulations from commodity bleach concentrates, with differentiation resting on certification tier and after-sales technical support. Cost compression in sodium hypochlorite tiers is intensifying because Gulf Coast energy input volatility feeds directly into feedstock economics. Long-term care facilities exhibit highest price sensitivity; academic medical centers with GPO-negotiated sole-source commitments show least.
Supply Chain Analysis
Chlor-alkali feedstock production concentrates in Texas, Louisiana, and West Virginia, with Gulf Coast capacity reconfiguring domestic active ingredient supply. Hydrogen peroxide formulations draw from Ohio River Valley chemical manufacturing clusters and Canadian electrochemical imports. Single-source vulnerability sits with EPA FIFRA registration infrastructure—novel active ingredients face 18-24 month approval timelines that tether commercialization to incumbent regulatory teams. Distribution runs through consolidated health system GPOs in the Southeast and Midwest, displacing independent regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in automated dispensing system maintenance and EPA compliance consulting expand faster than base chemical volumes, creating recurring revenue layers that outperform commodity formulation sales.
For Market Incumbents: Build regulatory infrastructure moats by accelerating EPA emerging pathogen protocol submissions ahead of viral threat designation. Consolidate electrostatic spray technology partnerships to lock in hospital capital equipment refresh cycles. Peracetic acid substitution in food processing cleanrooms threatens hydrogen peroxide growth; defend through sporicidal speed claims in healthcare settings. Deepen backward integration into Gulf Coast chlorine production to capture feedstock margin. For New Entrants and Emerging Players: Pursue long-term care facility automation gaps where wipe and aerosol formats lag hospital adoption rates. Target nursing home chains in Texas and Arizona with respiratory-sensitive hydrogen peroxide formulations paired with simple dispensing hardware. E-commerce direct procurement platforms serving mid-sized dental practices offer the most penetrable channel, bypassing traditional distributor markups through subscription replenishment models. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming disinfectant divisions lacking healthcare channel specialization. Five-to-ten year viability hinges on PFAS-free formulation pipelines and electrostatic delivery system integration. Watch EPA guidance acceleration on per- and polyfluoroalkyl substance contamination as inflection indicator for reformulation capex cycles and stranded asset risk in fluorinated surfactant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Pipeline | EPA tightening on per- and polyfluoroalkyl substances forces surfactant replacement ahead of procurement specification changes. |
| Electrostatic Spray Partnership | Positive-charge droplet technology compresses labor hours per square foot in ambulatory surgical center contracts. |
| EPA Emerging Pathogen Registration | Streamlined SARS-CoV-2 protocol access enables faster label expansion for federal preparedness stockpile qualification. |
| GPO Contract Consolidation | Southeast health system mergers create super-regional entities demanding sole-source or dual-source supply commitments. |
| Long-Term Care Channel Expansion | Nursing home automated dispensing penetration lags acute care, presenting white space for wipe format volume. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with hospital procurement directors, GPO contracts managers, environmental services executives, and EPA regulatory affairs specialists; and secondary validation through EPA FIFRA registration databases, hospital supply chain disclosures, OSHA enforcement records, and customs import data for active ingredient feedstocks. Bottom-up facility-level demand modeling triangulated against top-down chemical production capacity estimates.
Forecast inputs incorporated product chemistry segmentation, delivery format adoption curves, and regional health system consolidation patterns across the projection horizon. CAGRs derived from facility construction pipelines, GPO contract renewal cycles, and EPA registration timeline assumptions. Hydrogen peroxide respiratory sensitivity substitution rates and electrostatic spray technology penetration served as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in Gulf Coast energy pricing, chlorine production capacity utilization, or federal hospital construction funding would shift the trajectory. Cross-checking against EPA emerging pathogen registration approval rates and health system merger completion timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Antibacterial Products Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Sodium Dichloroisocyanurate Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market