
 Bactericides Market | 2026-2036
Bactericides Market Size, Share, and Industry Trends Forecast 2026-2036
Bactericides Market Analysis
Chinese agrochemical manufacturers is rebalancing active ingredient output toward copper-based and antibiotic bactericide intermediates. BASF SE leverages integrated fermentation capacity to sustain cost positions in streptomycin-derived products. Syngenta Crop Protection AG anchors its portfolio in seed treatment bactericides for cereals and oilseeds. Nufarm Agriculture Inc. competes through regional formulation plants that reduce freight exposure in Australasia and Latin America.
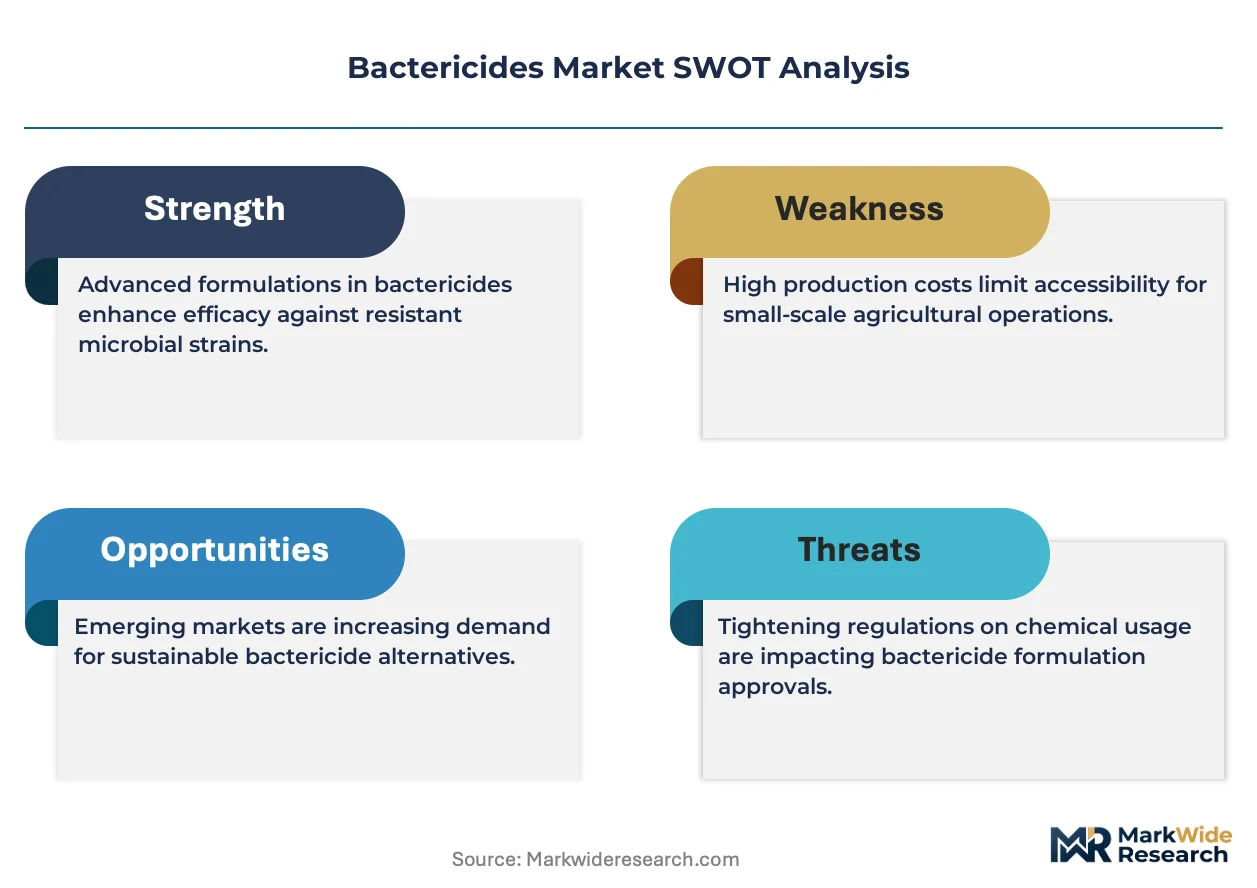
Bactericides are antimicrobial agents that disrupt bacterial cell walls, protein synthesis, or metabolic pathways through active ingredients such as copper sulfate, kasugamycin, or quaternary ammonium salts, formulated for agricultural, industrial, or consumer disinfection endpoints. Quaternary ammonium compounds dominate institutional and household chemical channels where surface disinfection protocols have tightened post-pandemic. Agricultural applications of antibiotic bactericides face margin compression as residue monitoring expands, while phenol-based formulations in oil and gas water treatment retain stable replacement demand.
EPA tolerance assessments and EU MRL regulations under EFSA oversight are extending product re-registration timelines and elevating toxicology study burdens for legacy active ingredients. China's MEE discharge standards for antibiotic manufacturing effluent are forcing capacity relocation or wastewater retrofit investments. India's CEA water quality mandates for utilities are expanding quaternary ammonium procurement specifications. Stakeholders must weigh biological bactericide pipeline maturity against the regulatory depreciation risk confronting conventional chemistries.
Market Dynamics
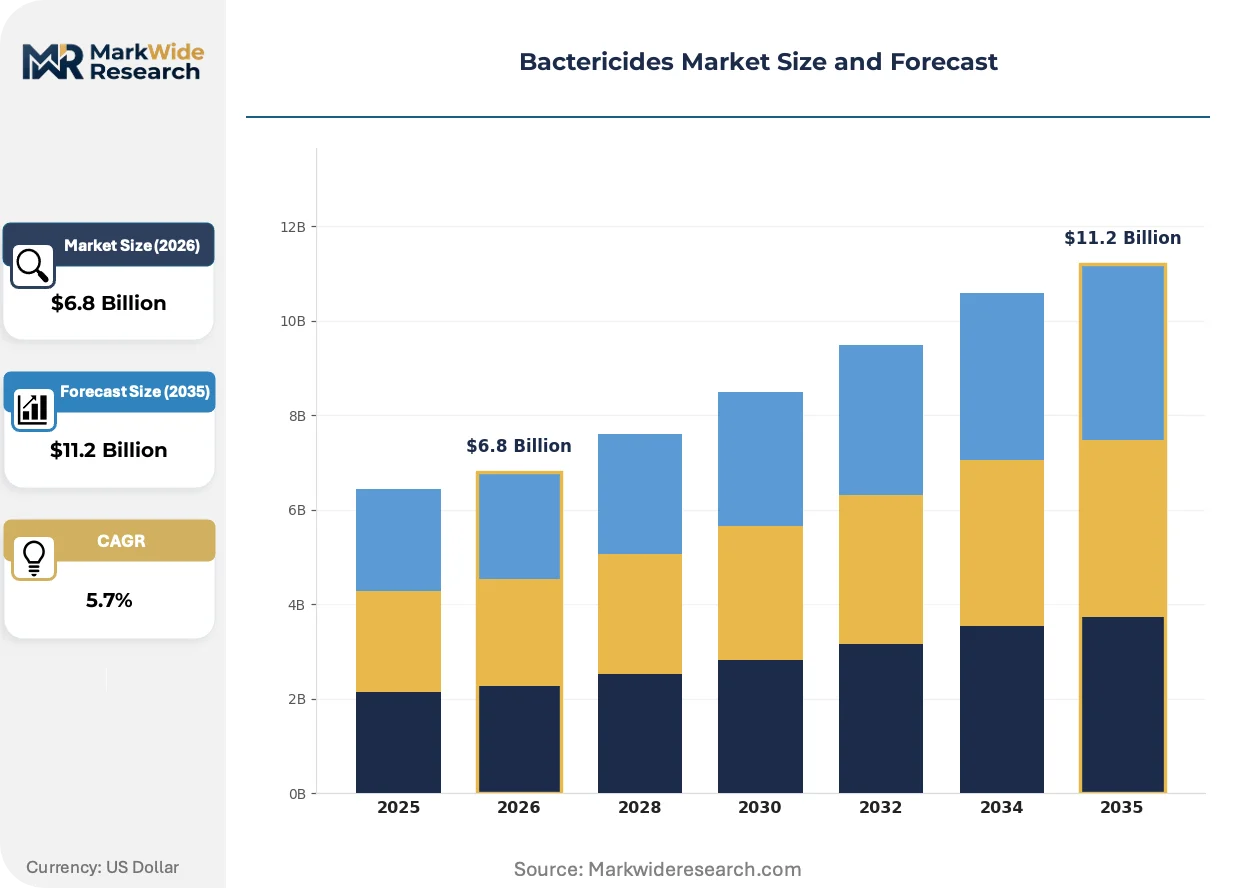
Copper sulfate and kasugamycin active ingredient shortages are compressing formulation margins while EU MRL tightening accelerates biological bactericide pipeline investments. The structural tension between legacy chemistry depreciation and biological registration acceleration defines competitive positioning across agricultural and industrial end-uses.
Growth Catalysts
- EU Farm to Fork Strategy:The EU Green Deal's pesticide reduction targets are compressing synthetic bactericide windows while fast-tracking microbial product approvals, redirecting R&D budgets toward fermentation-derived alternatives.
- Horticulture Intensification:Maharashtra and Telangana state governments in India are expanding protected cultivation acreage for pomegranates and tomatoes, concentrating procurement of antibiotic and copper-based bactericide formulations.
- Post-Pandemic Disinfection Protocols:Institutional buyers in healthcare and food processing are mandating quaternary ammonium surface treatment frequencies that sustain industrial chemical demand above pre-2020 baselines.
Market Restraints
- Copper Sulfate Supply Concentration:Chilean and Peruvian mining output volatility feeds into Chinese intermediate production, exposing formulated product margins to concentrate price swings.
- EFSA Re-Registration Burden:Legacy streptomycin and oxytetracycline products face extended toxicology study requirements that freeze label expansions and elevate compliance costs for generic manufacturers.
- Biological Efficacy Gap:Microbial bactericides demonstrate inconsistent field performance against Xanthomonas and Pseudomonas pathogens in humid tropical conditions, limiting grower switching from antibiotic standards.
Strategic Opportunities
- Seed Treatment Expansion:Cereal and oilseed coating applications represent underpenetrated bactericide endpoints where integrated pest management bundling with fungicides reduces per-acre application costs.
- China MEE Discharge Compliance:Antibiotic manufacturing effluent standards are forcing capacity consolidation, creating acquisition targets for fermentation specialists with compliant wastewater infrastructure.
- Biostimulant Convergence:Combining Bacillus subtilis bactericides with biostimulant formulations addresses both disease suppression and plant vigor, opening premium positioning in organic horticulture channels.
Industry Challenges
- Microbial Formulation Expertise Scarcity:Fermentation scale-up and shelf-life stabilization for biological actives requires process engineers with pharmaceutical biologics experience, a talent pool concentrated in Basel and Boston hubs.
- Multi-Jurisdiction Registration Synchronization:Divergent data requirements between EPA tolerance assessments, EU zonal authorizations, and Brazil's ANVISA timelines fragment launch sequencing and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bactericides Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenols, Quaternary Ammonium Compounds, Halides, Antibiotics Application: Agriculture, Water Treatment, Oil & Gas, Household Chemicals Delivery Mode: Liquid Formulations, Powder Formulations, Granules, Emulsions End User: Farms, Water Utilities, Chemical Manufacturers, Households |
| Companies Covered | Corteva Agriscience, Sumitomo Chemical Company Ltd., BASF SE, UPL Limited, Adama Agricultural Solutions Ltd., Syngenta Crop Protection AG, FMC Corporation, Nufarm Agriculture Inc., Bayer Crop Science AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bactericides Market Emerging Trajectories
Biological fermentation platforms and nanoscale copper delivery systems are displacing conventional formulation chemistries. Regulatory stringency and residue monitoring expansion are compressing legacy product lifecycles while opening white space for precision application technologies.
RNA interference bactericides targeting bacterial virulence genes are electrifying pre-commercial development pipelines. Bayer CropScience and Syngenta field trials in California strawberry and Florida citrus demonstrate 60-90 day residual control comparable to antibiotic standards. This platform is electrifying the competitive landscape by enabling trait-specific mode-of-action patents that circumvent generic streptomycin competition.
REACH authorization timelines for copper-based actives are extending substance evaluation phases to 48-60 months. ECHA's revised environmental risk assessment endpoints for soil macroorganisms are forcing reformulation of fixed-copper products across vine and tree fruit applications. Spanish and Italian cooperatives are responding by trialing reduced-rate copper programs integrated with biocontrol agents to maintain protective coverage within cumulative loading limits.
Direct procurement relationships between Maharashtra tomato processing cooperatives and formulation plants are disintermediating traditional distributor networks. Bulk tanker deliveries of copper hydroxide suspensions replace packaged goods, cutting per-liter logistics costs by eliminating drum handling and warehousing markups. This channel compression is most advanced in Nashik and Pune districts where contract farming consolidation enables volume commitments sufficient for dedicated production runs.
Bactericides Market Segmentation
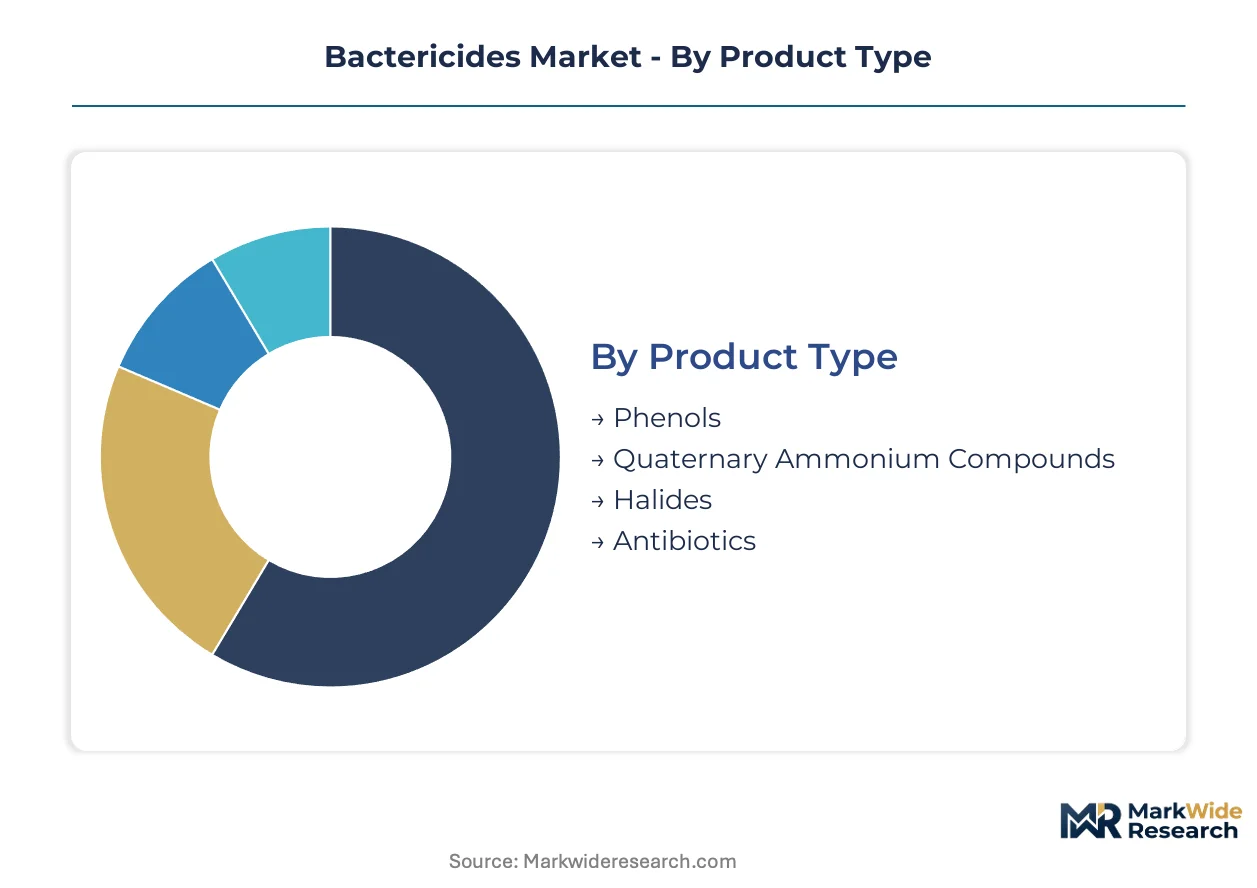
Bactericide procurement patterns diverge sharply across end-use contexts, with agricultural buyers prioritizing residue-compliant actives while industrial purchasers emphasize bulk volume economics. Segmentation clarity enables suppliers to align formulation investments with distinct regulatory and performance requirements.
Product Type:
Quaternary ammonium compounds face EPA tolerance assessments for agricultural residues, while phenols navigate REACH authorization timelines and antibiotics confront China's MEE discharge compliance mandates.
- Phenols:Coal-tar derivatives and synthetic phenolics deliver broad-spectrum bacterial control through membrane disruption. Oil and gas water treatment operators in Texas and Alberta specify phenol-based formulations for produced water biocide programs where replacement cycles sustain steady procurement.
- Quaternary Ammonium Compounds:Cationic surfactants adsorb to bacterial cell walls causing leakage and lysis. Hospital systems and food processing plants in São Paulo and Mumbai mandate quaternary ammonium surface protocols that institutionalize above-baseline consumption patterns.
- Halides:Chlorine and bromine-releasing compounds serve municipal water disinfection with straightforward oxidation chemistry.
- Antibiotics:Streptomycin and kasugamycin face tightening EFSA MRL surveillance that compresses label expansion opportunities.
Quaternary ammonium compounds sit at the top of the volume ranking, with antibiotics climbing the fastest as biological alternatives erode their agricultural dominance.
Application:
Cost tier differentiation separates commodity-scale industrial treatments from precision agricultural applications where per-acre economics dominate procurement decisions.
- Agriculture:Foliar sprays and seed treatments protect high-value horticulture through copper sulfate, kasugamycin, and emerging RNA interference platforms. Maharashtra pomegranate growers and California strawberry producers drive antibiotic and biological bactericide procurement with residue-sensitive export requirements.
- Water Treatment:Municipal utilities and industrial cooling systems deploy halides and quaternary ammonium compounds for biofilm prevention. India's CEA water quality mandates for urban utilities expand quaternary ammonium specification volumes in Delhi and Bangalore treatment facilities.
- Oil & Gas:Downhole and produced water applications favor phenol biocides with proven efficacy against sulfate-reducing bacteria.
- Household Chemicals:Surface disinfectants and sanitizers concentrate quaternary ammonium actives for consumer channel distribution.
Agriculture generates the steepest expansion trajectory, with water treatment gaining share fastest as India's utility upgrades accelerate.
Delivery Mode:
Supply concentration in Chinese intermediate production shapes formulation economics, with liquid suspensions dominating bulk agricultural channels and powders serving distant markets where freight optimization matters.
- Liquid Formulations:Ready-to-use suspensions and solutions eliminate dissolution steps for spray equipment. Brazilian citrus cooperatives and Spanish olive growers procure copper hydroxide and kasugamycin liquids through direct tanker deliveries that bypass packaged goods distribution.
- Powder Formulations:Dry concentrates reduce shipping weights and enable extended shelf stability. Australian broadacre wheat producers and Canadian prairie oilseed growers favor powder antibiotics and copper products where on-farm mixing integrates with existing spray routines.
- Granules:Controlled-release formats serve specialty turf and ornamental applications with reduced application frequency.
- Emulsions:Oil-in-water systems enhance adhesion for tree fruit and vine crops requiring rainfast protection.
Liquid formulations command the highest volume position, with emulsions expanding most quickly as rainfast requirements intensify in humid growing regions.
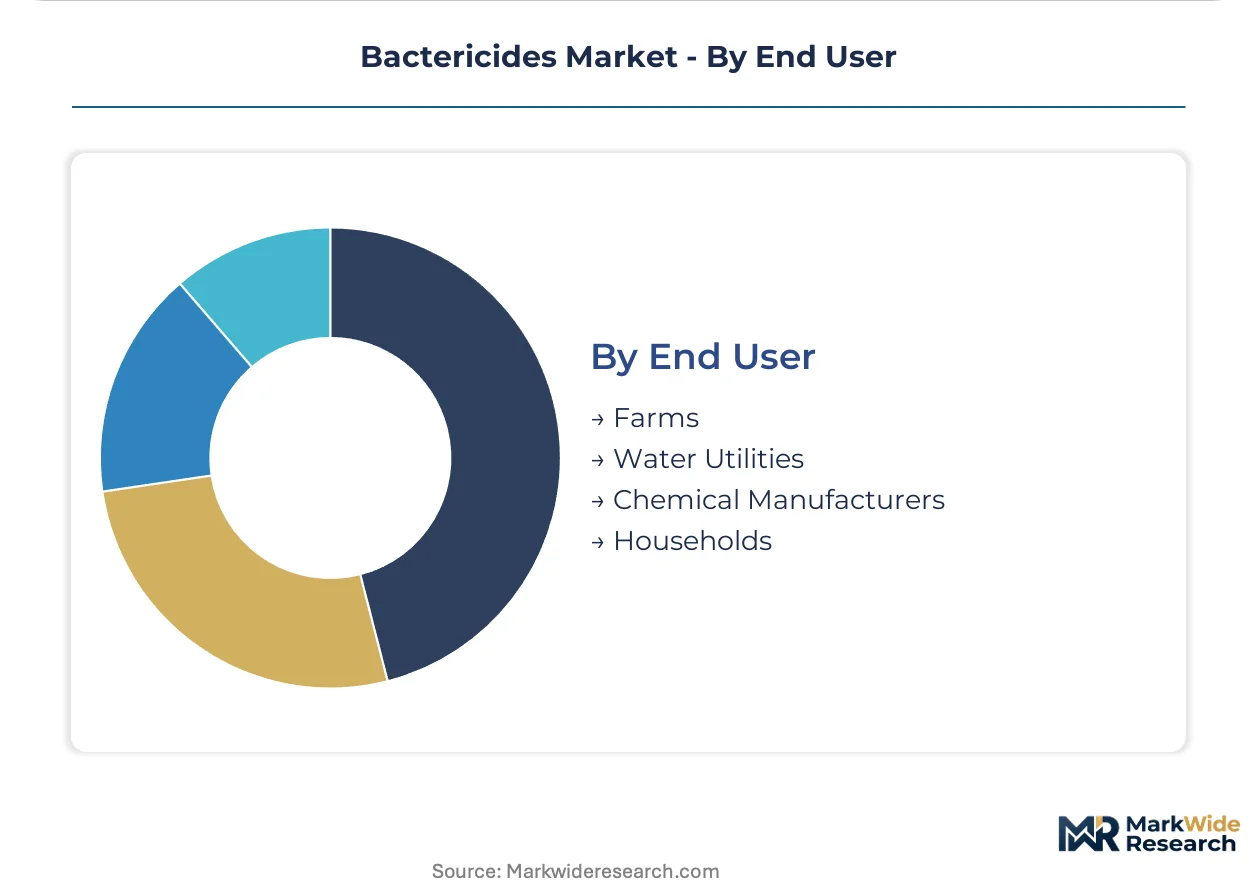
End User:
Customer type determines contract structure, with farms negotiating seasonal procurement and water utilities locking multi-year supply agreements.
- Farms:Individual growers and cooperative associations purchase through distributor networks or direct formulation plant relationships. Telangana tomato processing cooperatives and Nashik grape growers consolidate volumes for dedicated production runs with logistics cost elimination.
- Water Utilities:Municipal and industrial treatment operators specify bactericide programs through tender processes. Indian urban water authorities under CEA mandates and Brazilian sanitation companies drive quaternary ammonium and halide procurement with regulatory compliance deadlines.
- Chemical Manufacturers:Formulation plants source active ingredients for downstream blending and packaging.
- Households:Retail consumers purchase ready-to-use disinfectants through grocery and pharmacy channels.
Farms represent the largest consumption base, with water utilities expanding most rapidly as infrastructure investment accelerates across emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese antibiotic intermediate manufacturers are relocating fermentation capacity to Southeast Asia as MEE discharge compliance costs escalate, while Indian formulation plants capture margin from direct-to-farm channel compression in horticulture belts.
China
Copper sulfate concentrate imports from Chile and Peru feed Jiangsu and Shandong province formulation plants serving domestic fruit growers. MEE wastewater standards are forcing capacity consolidation among streptomycin intermediate producers. Zhejiang fermentation specialists are acquiring compliant facilities in Vietnam to preserve cost positions.
India
Maharashtra pomegranate processors and Telangana tomato cooperatives are consolidating procurement volumes for dedicated bactericide production runs. CEA water quality mandates for urban utilities are expanding quaternary ammonium specifications in Delhi and Bangalore treatment plants. Nashik district grape growers now receive bulk copper hydroxide tanker deliveries bypassing distributor markups.
Brazil
São Paulo citrus cooperatives and Minas Gerais coffee federations are driving antibiotic bactericide demand for export-compliant residue management. ANVISA registration timelines for biological alternatives are accelerating as Farm to Fork-aligned import protocols tighten. Santa Catarina apple growers are trialing reduced-rate copper programs integrated with biocontrol agents.
United States
California strawberry producers and Florida citrus growers field-test RNA interference bactericides against Xanthomonas and Pseudomonas pathogens. EPA tolerance assessments for legacy antibiotic actives are extending re-registration study burdens. Texas Panhandle feedlot operators specify phenol biocides for water treatment replacement cycles.
Germany
Baden-Württemberg vineyard cooperatives and Bavarian hop growers navigate ECHA soil macroorganism risk assessments for fixed-copper products. REACH authorization timelines now stretch 48-60 months for copper-based actives. Rhineland-Palatinate wine producers are integrating reduced-rate copper with microbial biocontrol to stay within cumulative loading limits.
Bactericides Market Vendor Landscape
European integrated agrochemical conglomerates anchor one tier; Asian fermentation specialists and regional formulation plants hold distinct positions in cost-sensitive geographies. The market structure reflects a bifurcation between R&D-intensive patent platforms and procurement-optimized blending operations. Three archetypes dominate: diversified life-science conglomerates with seed-to-shelf integration, fermentation-centric antibiotic specialists, and geography-focused formulation plants with freight-advantaged distribution. Competitive positioning hinges on backward integration into active ingredient supply and direct channel relationships with processing cooperatives.
Within the diversified conglomerate tier, BASF SE and Syngenta Crop Protection AG exemplify integrated fermentation and seed treatment capabilities. Bayer CropScience AG occupies a position in RNA interference development pipelines. Among regional specialists, Nufarm Agriculture Inc. represents freight-optimized formulation architecture across Australasia and Latin America. These three anchors illustrate divergent bets on biological registration acceleration versus legacy chemistry cost defense.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Sumitomo Chemical Company Ltd. |
| BASF SE |
| UPL Limited |
| Adama Agricultural Solutions Ltd. |
| Syngenta Crop Protection AG |
| FMC Corporation |
| Nufarm Agriculture Inc. |
| Bayer Crop Science AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fermentation specialists in Jiangsu and Zhejiang provinces anchor Chinese antibiotic intermediate supply, translating concentrated ownership into disciplined capacity management that buffers copper sulfate concentrate volatility while sustaining formulation margin structures across agricultural and industrial channels.
Pricing Analysis
Distributor margin compression in Maharashtra and Telangana horticulture belts is accelerating direct-to-cooperative procurement models that eliminate warehousing markups. Three-tier pricing structure across residue-compliant premium actives, standard copper-based formulations, and economy generic antibiotics reflects EFSA MRL surveillance intensity and buyer export certification requirements. Cost compression in legacy streptomycin formulations is intensifying because EFSA re-registration study burdens freeze label expansions. Export-oriented processing cooperatives exhibit lowest price sensitivity; domestic spot buyers in fragmented vegetable belts demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification mandates from São Paulo hospital systems and Mumbai food processing plants are fragmenting procurement across multiple quaternary ammonium compound suppliers to mitigate Chilean mining output volatility. Active ingredient production concentrates in China, India, and Germany. Formulated products draw from copper sulfate concentrates, kasugamycin fermentation broths, and quaternary ammonium intermediates. Single-source vulnerability pervades Chinese streptomycin intermediate capacity facing MEE discharge compliance deadlines. Distribution runs through regional formulation plants with freight-optimized coverage of Australasia and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biological bactericide premium-tier positioning and MEE-compliant wastewater infrastructure capturing stranded antibiotic capacity at distressed acquisition multiples.
For Market Incumbents: Anchor seed treatment bactericide portfolios in cereal and oilseed coating applications where integrated pest management bundling with fungicides defends against RNA interference platform displacement. Prioritize backward integration into fermentation capacity in Vietnam and Indonesia to preserve cost positions as Chinese MEE standards escalate. Certification investment in EU Farm to Fork-aligned microbial product registrations offers label expansion leverage unavailable to generic manufacturers facing EFSA toxicology study freezes. For New Entrants and Emerging Players: Launch via direct tanker delivery relationships with Nashik grape cooperatives and Telangana tomato processing associations, bypassing distributor networks that incumbent generics dominate. Target seed treatment expansion in Brazilian citrus and Minas Gerais coffee belts where ANVISA biological registration acceleration creates first-mover windows against legacy antibiotic standards. White-space concentration sits in Bacillus subtilis biostimulant convergence formulations for organic horticulture premiums. For Investors and Strategic Acquirers: Valuations sit cheapest among fermentation specialists with compliant wastewater infrastructure stranded by Chinese MEE consolidation. Long-term viability favors acquisition targets with pharmaceutical biologics process engineering talent concentrated in Basel and Boston hubs, positioned to scale RNA interference platforms. Signal to watch as inflection indicator: EPA tolerance assessment acceleration for microbial alternatives that would depreciate legacy antibiotic re-registration asset values.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures stranded Chinese antibiotic intermediate assets as MEE discharge standards force consolidation. |
| Biological Product Registration Acceleration | EU Farm to Fork fast-track timelines redirect R&D budgets toward microbial alternatives ahead of synthetic chemistry depreciation. |
| Direct-to-Cooperative Channel Establishment | Maharashtra and Telangana horticulture belt procurement consolidation eliminates distributor margins through bulk tanker deliveries. |
| RNA Interference Platform Development | Bayer CropScience and Syngenta field trials demonstrate residual control parity with antibiotic standards in California strawberry applications. |
| Biostimulant Convergence Formulation | Bacillus subtilis bactericide integration with plant vigor actives opens premium positioning in organic export channels. |
Methodological Framework
Coverage spans Asia-Pacific agricultural clusters, European regulatory jurisdictions, and Latin American horticulture belts, with primary inputs from each combining interviews with fermentation plant managers, formulation procurement leads at cooperatives, regulatory affairs directors navigating EFSA and EPA timelines, and distribution channel partners in São Paulo and Mumbai with secondary validation through customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed agrochemical conglomerates, and ANVISA registration databases. Bottom-up volume triangulation across product type, application, and delivery mode segments reconciles against top-down value estimates.
Granularity-level modeling disaggregates projections across antibiotic, copper-based, quaternary ammonium, and biological active ingredient categories; agricultural, water treatment, oil and gas, and household chemical end-uses; liquid, powder, granule, and emulsion delivery formats; and farm, utility, chemical manufacturer, and household customer types throughout the projection horizon. CAGRs derive from segment-level growth rate synthesis anchored in regulatory timeline acceleration, horticulture intensification patterns, and residue monitoring expansion. Industry-specific forecast inputs include EFSA MRL tightening schedules, MEE discharge standard implementation phases, and CEA water quality mandate rollout across Indian urban utilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EFSA re-registration moratoriums or Chinese MEE enforcement surges that would strand antibiotic intermediate capacity faster than biological pipeline maturation permits. Deviation in EPA tolerance assessment acceleration for RNA interference platforms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Warehouse Fumigants Market