
 Mobile Virtual Network Operator (MVNO) Market | 2026-2036
Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Virtual Network Operator (MVNO) Market Analysis
Enterprise IoT connectivity is consolidating as the fastest-expanding end-use vertical within the MVNO landscape. Virgin Mobile leverages its brand strength to sustain consumer loyalty across prepaid segments. Mint Mobile competes aggressively on price-transparent digital distribution. TracFone Wireless anchors rural and budget-conscious demographics through extensive retail partnerships.
A Mobile Virtual Network Operator leases bulk network capacity from host mobile network operators and resells services under its own brand, typically operating through software-defined provisioning platforms that enable real-time subscriber management and flexible tariff structures. The primary commercial purpose is delivering branded mobile services without owning spectrum or physical radio infrastructure. Reseller business models dominate volume but carry thin margins, while wholesale arrangements capture deeper value pools through network slicing and API-driven service orchestration. IoT connectivity represents the fastest-growing service type as industrial asset tracking and connected vehicle platforms require specialized, low-latency data tiers.
The FCC governs wholesale access agreements and interconnection rates in the United States, directly influencing MVNO market entry economics. Ofcom in the United Kingdom enforces retail pricing transparency and net neutrality provisions that constrain tariff design flexibility. The EU Roaming Regulation and associated wholesale caps reshape cross-border service economics for European operators. Stakeholders must monitor evolving spectrum auction conditions and host-operator consolidation trends that could tighten wholesale capacity availability.
Market Dynamics
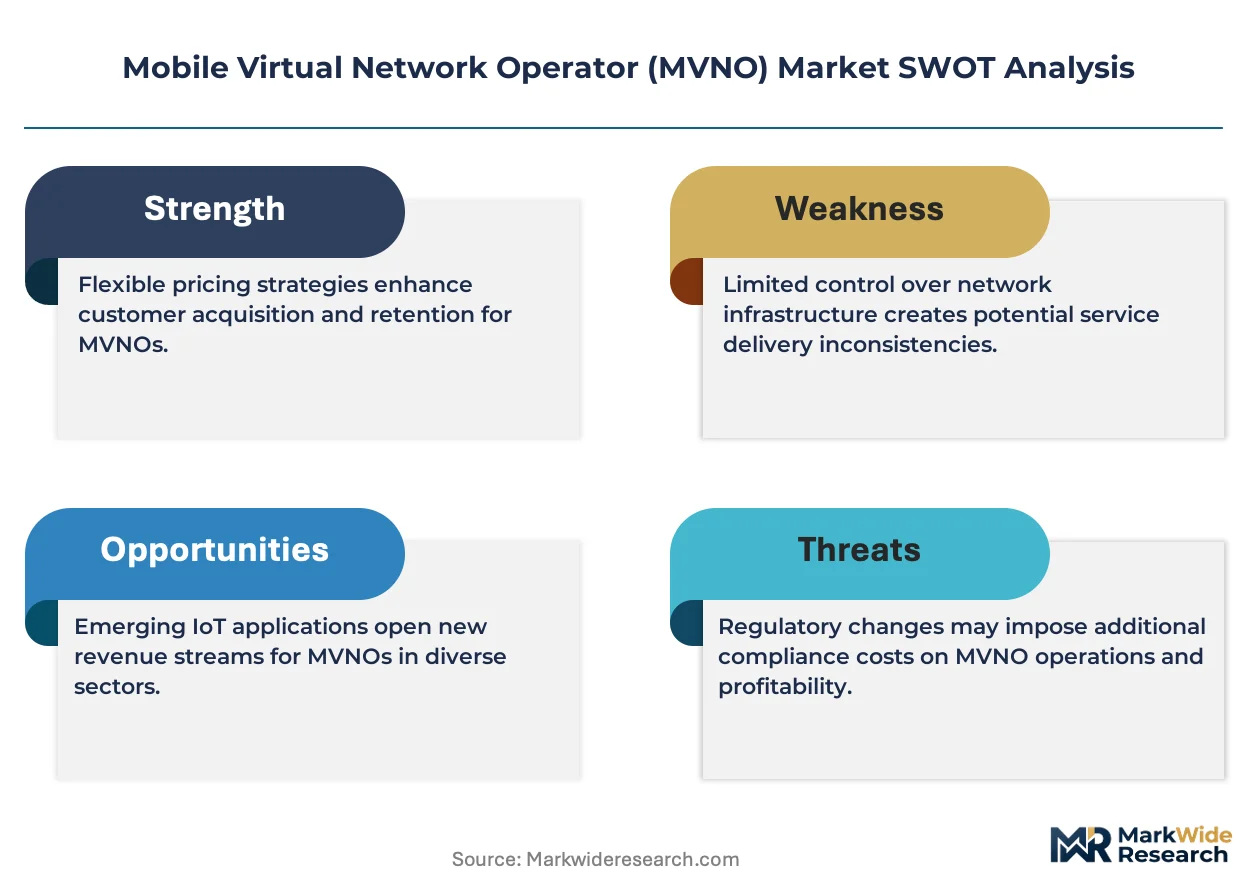
Enterprise IoT connectivity consolidation is compressing traditional consumer MVNO margins while forcing wholesale contract renegotiation. Host-operator network slicing capabilities now determine which resellers can access industrial-grade service tiers.
Growth Catalysts
- EU Roaming Regulation:Wholesale rate caps reduce cross-border service costs for European MVNOs serving multinational fleet operators. German automotive logistics contracts expand accordingly.
- Industrial IoT deployments:Asset tracking platforms in manufacturing require specialized low-latency data tiers that wholesale MVNO arrangements uniquely deliver.
- FCC interoperability mandates:Standardized network access interfaces lower host-operator switching costs for US-based digital-first entrants.
Market Restraints
- Host-operator consolidation:Reduced wholesale capacity availability in concentrated US and German markets squeezes reseller margin structures.
- Spectrum auction tightness:Limited mid-band release schedules constrain network slicing granularity for latency-sensitive IoT applications.
- Regulatory fragmentation:Divergent net neutrality interpretations between Ofcom and FCC jurisdictions complicate cross-border tariff harmonization.
Strategic Opportunities
- Connected vehicle platforms:Automotive OEMs seek captive MVNO partnerships for over-the-air software update delivery and telematics aggregation.
- API-driven service orchestration:Wholesale arrangements enabling real-time provisioning through software-defined platforms unlock enterprise self-service models.
- India's TRAI framework:Liberalized MVNO licensing guidelines create entry pathways for digital distribution specialists targeting price-transparent prepaid segments.
Industry Challenges
- Legacy billing system integration:Enterprise IoT contracts require real-time usage mediation that conflicts with prepaid-centric subscriber management platforms.
- Network slicing certification timelines:Host-operator technical validation delays extend enterprise sales cycles beyond standard consumer onboarding periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Virtual Network Operator (MVNO) Market |
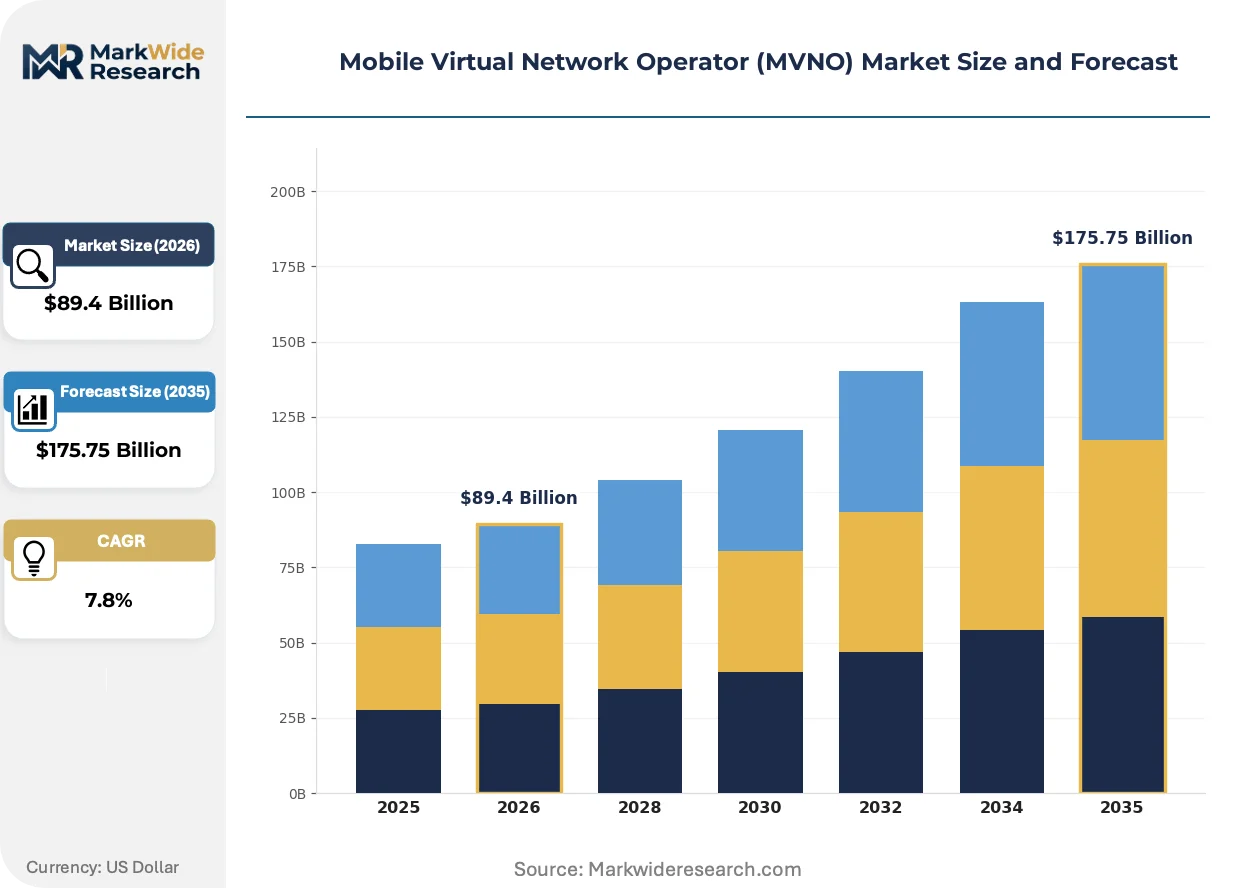
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $175.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Reseller, Wholesale, Retailer, Niche Provider Service Type: Voice, Data, SMS, IoT Connectivity End User: Consumer, Business, Government, Enterprise Distribution Channel: Online, Retail, Direct, Third-Party |
| Companies Covered | Virgin Mobile, Boost Mobile, Lycamobile, Mint Mobile, Giffgaff, TracFone Wireless, Tesco Mobile, Spectrum Mobile, Lebara Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Virtual Network Operator (MVNO) Market Emerging Trajectories
Software-defined network orchestration is dissolving traditional boundaries between wholesale and retail service layers. This shift compresses time-to-market for specialized connectivity offerings while elevating API maturity as a competitive differentiator.
Network function virtualization is unifying core network elements across multiple host infrastructures. Industrial asset tracking providers in Germany adopt these architectures within eighteen-month procurement cycles. The technology is unifying previously siloed connectivity management platforms into single-pane subscriber orchestration.
CSRD sustainability disclosure requirements are mandating granular carbon footprint reporting from European connectivity providers. MVNOs must now document scope-three emissions from host-operator data center energy consumption. German industrial IoT contracts increasingly specify renewable energy sourcing as a mandatory evaluation criterion.
Enterprise procurement teams now consolidate connectivity spend through managed service aggregators rather than direct MVNO relationships. Automotive fleet operators in the United States favor platform-agnostic brokers who normalize pricing across multiple host networks. This pattern concentrates contract value with intermediaries possessing real-time tariff optimization engines.
Mobile Virtual Network Operator (MVNO) Market Segmentation
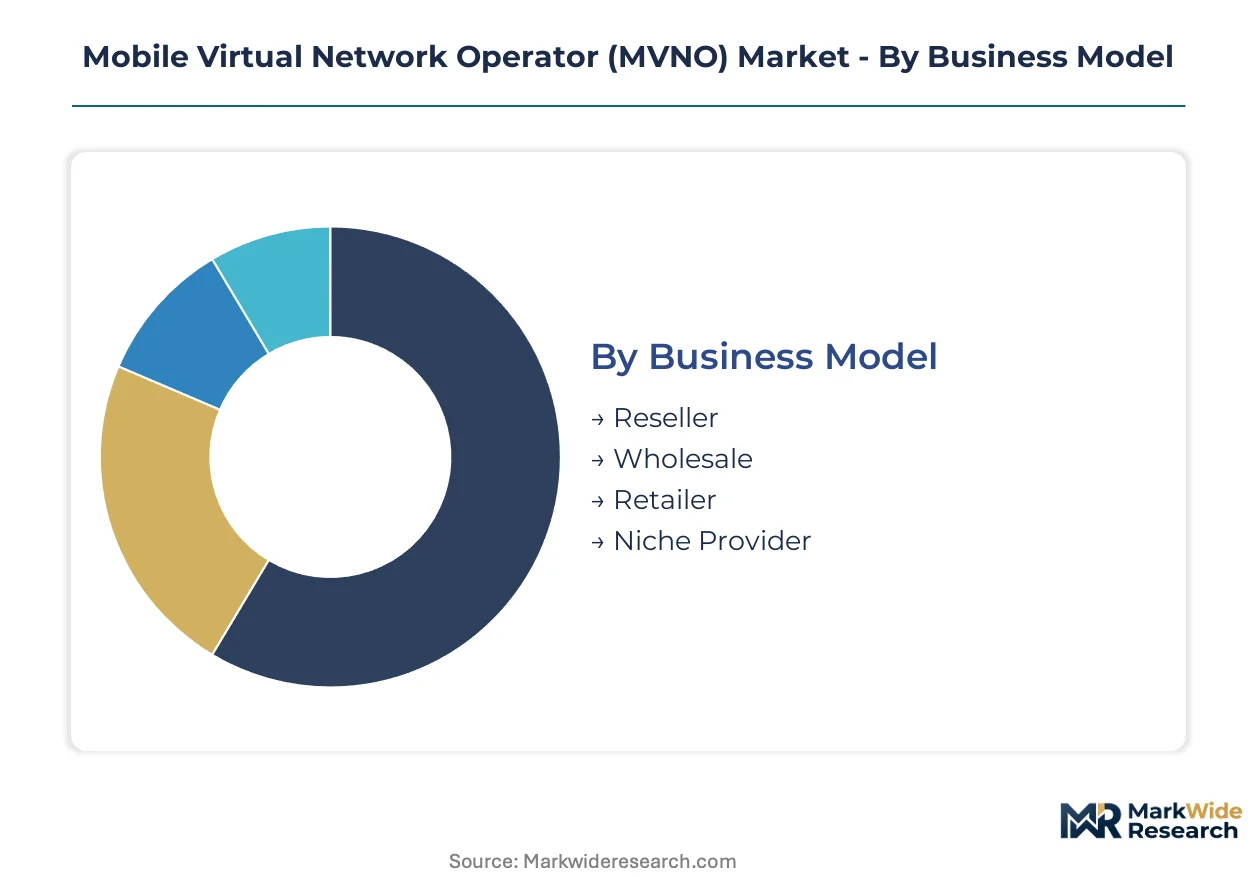
MVNO segmentation reveals divergent margin structures across business models and service tiers. Wholesale arrangements capture industrial-grade value pools while reseller models compete on volume throughput. Understanding these segment boundaries clarifies where host-operator negotiations concentrate and which distribution investments yield sustainable returns.
Business Model:
Integration depth varies sharply — wholesale operators embed directly into enterprise IT stacks while resellers maintain arm's-length subscriber relationships.
- Reseller:Thin-margin volume play leasing bulk capacity from host operators with minimal service differentiation. German automotive logistics contracts rarely engage this tier due to lack of network slicing access. Margin compression from host-operator consolidation forces cost discipline.
- Wholesale:Deep API integration enabling real-time provisioning and custom service orchestration for industrial IoT platforms. German manufacturing asset tracking providers prioritize this tier for guaranteed latency tiers. Captive relationships with automotive OEMs drive contract value concentration here.
- Retailer:Branded consumer services with proprietary customer acquisition and loyalty programs. Mint Mobile's digital-first distribution exemplifies this segment's cost structure optimization.
- Niche Provider:Specialized offerings targeting demographic or use-case segments such as rural connectivity or senior-focused simplified tariffs. TracFone Wireless anchors this tier through retail partnerships.
Volume placements concentrate in Reseller; the faster expansion belongs to Wholesale.
Service Type:
Cost tier stratification separates commodity connectivity from premium-engineered service levels.
- Voice:Mature revenue stream with declining per-user economics across prepaid consumer segments. Regulatory rate floors in some jurisdictions preserve minimal margin.
- Data:Primary revenue engine with tiered pricing reflecting throughput guarantees and fair-use thresholds. Enterprise procurement teams negotiate volume commitments against sliding rate scales.
- SMS:Legacy messaging infrastructure supporting two-factor authentication and machine-to-machine alerts. Flat-rate bundles increasingly subsume standalone pricing.
- IoT Connectivity:Specialized low-latency tiers with device-level authentication and usage mediation. Industrial deployments in Germany specify this service type in procurement mandates. Connected vehicle platforms require guaranteed bandwidth for over-the-air software delivery.
Revenue gravity centers on Data; IoT Connectivity climbs the fastest.
End User:
Customer type determines contract structure complexity and sales cycle duration.
- Consumer:Prepaid and postpaid individual subscribers acquired through brand marketing and retail presence. Virgin Mobile sustains loyalty through lifestyle positioning.
- Business:Small and medium enterprises purchasing standardized mobility packages with pooled usage allowances. Procurement lacks technical sophistication for custom negotiations.
- Government:Security-cleared contracts with domestic data residency requirements and audit compliance. Tender processes extend sales cycles significantly.
- Enterprise:Multinational fleet operators and industrial platforms demanding API-driven provisioning and granular usage analytics. German automotive logistics contracts exemplify this segment's technical requirements.
Subscriber counts peak in Consumer; contract value expansion concentrates in Enterprise.
Distribution Channel:
Channel maturity shapes customer acquisition economics and brand control intensity.
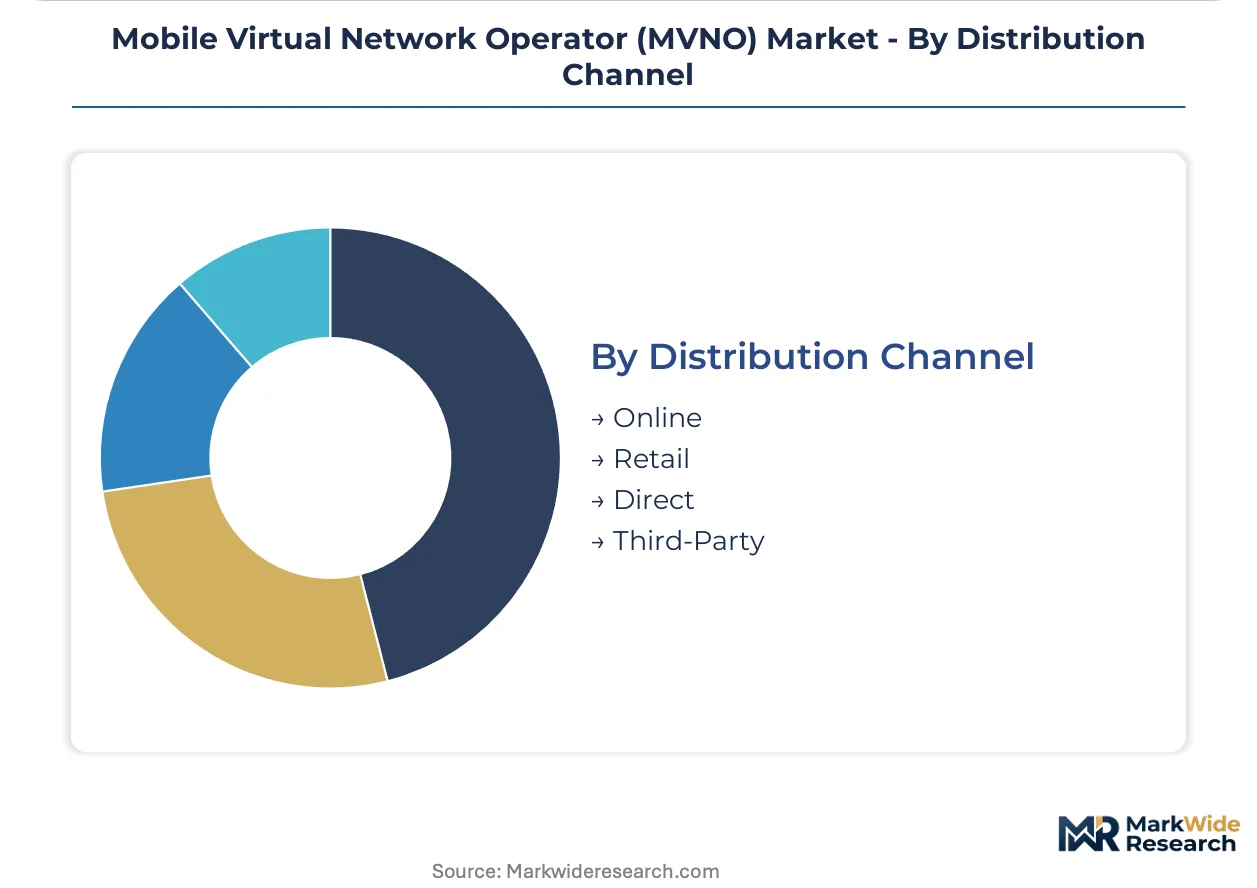
- Online:Digital-first acquisition with transparent pricing and self-service provisioning. Mint Mobile's direct-to-consumer model minimizes subscriber acquisition costs.
- Retail:Physical presence through carrier stores, electronics retailers, and convenience partnerships. TracFone Wireless leverages this channel for rural demographic reach.
- Direct:Branded stores and enterprise sales teams managing complex contract negotiations. High touch for government and enterprise segments.
- Third-Party:Aggregators and brokers normalizing pricing across multiple host networks. US automotive fleet operators favor platform-agnostic intermediaries with real-time tariff optimization.
Subscriber volumes flow through Retail; margin efficiency gains concentrate in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dubai Internet City concentrate MVNO back-office operations and API development centers. These zones attract wholesale operators seeking low-latency connectivity infrastructure. Tax incentives for digital service exports accelerate platform investments.
United States
Enterprise fleet management and connected vehicle platforms drive B2B contract growth. FCC interoperability mandates standardize host-operator access interfaces. Detroit automotive clusters source captive MVNO partnerships for over-the-air software delivery.
Germany
Industrial IoT asset tracking and automotive logistics contracts dominate enterprise procurement. EU Roaming Regulation wholesale caps reduce cross-border service costs. Munich manufacturing corridors specify low-latency data tiers in connectivity tenders.
United Kingdom
Digital-first consumer brands compete through transparent pricing and self-service provisioning. Ofcom net neutrality provisions constrain tariff design flexibility. London fintech clusters demand API-driven connectivity orchestration for payment platforms.
India
Price-transparent prepaid segments attract digital distribution specialists. TRAI liberalized MVNO licensing guidelines reduce entry barriers. Bangalore technology corridors host software-defined provisioning platform development.
United Arab Emirates
Smart city infrastructure and logistics hubs require specialized IoT connectivity tiers. Dubai Internet City free zone incentives concentrate regional MVNO headquarters operations. Abu Dhabi industrial zones specify guaranteed bandwidth for critical asset monitoring.
Mobile Virtual Network Operator (MVNO) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with digital-first entrants capturing consumer volume while wholesale operators lock in enterprise value pools. The vendor base organizes around three strategic archetypes: price-transparent digital distributors, host-operator captive brands, and API-driven wholesale orchestrators. Consolidation pressures intensify as host-operator mergers reduce available wholesale capacity. Strategic partnerships with automotive OEMs and industrial platform providers now determine contract access.
Within the digital-first tier, Mint Mobile and Giffgaff exemplify cost-optimized customer acquisition models. Virgin Mobile occupies a position anchoring lifestyle-branded consumer loyalty. TracFone Wireless sits within the rural and budget-conscious demographic segment through extensive retail partnership networks.
| Leading Market Players |
|---|
| Virgin Mobile |
| Boost Mobile |
| Lycamobile |
| Mint Mobile |
| Giffgaff |
| TracFone Wireless |
| Tesco Mobile |
| Spectrum Mobile |
| Lebara Group |
| Others |
Supply Flow & Price Mechanics
API-orchestrated wholesale tiers diverge sharply from thin-margin reseller slots, with the former commanding premium positioning through guaranteed latency SLAs while the latter compete on subscriber acquisition velocity. This bifurcation concentrates pricing power with host operators possessing network slicing certification, compressing reseller margins in concentrated markets like the United States and Germany.
Pricing Analysis
Short lead-time provisioning commands premium rates in enterprise IoT contracts, while spot capacity leases trade at discounts to long-term wholesale commitments. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed latency tiers from best-effort data pools and basic voice bundles. Cost compression in consumer prepaid segments is intensifying because digital-first distributors automate subscriber acquisition. Small and medium enterprises exhibit highest price sensitivity; multinational fleet operators prioritize technical specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with host-operator consolidation in the United States and Germany, where reduced wholesale capacity availability constrains reseller economics. Network infrastructure draws from Taiwan for semiconductor components, Finland for core network software, and domestic data centers for edge computing deployment. Tariff exposure runs through cross-border data routing agreements. Distribution runs through software-defined provisioning platforms enabling real-time subscriber orchestration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Host-operator wholesale capacity constraints prop pricing across enterprise IoT tiers, creating durable margin pools for certified orchestrators while squeezing undifferentiated resellers.
For Market Incumbents: Extend API integration depth into automotive OEM IT stacks before captive MVNO partnerships solidify. Consolidate position in German manufacturing corridors through dedicated network slicing certification. Vertical integration into proprietary provisioning platforms preserves margin against host-operator rate renegotiation. For New Entrants and Emerging Players: Rural fleet operators in the United States represent an underserved buyer archetype with limited platform-agnostic broker coverage. India's TRAI liberalized framework offers entry pathways for digital distribution specialists targeting price-transparent prepaid segments. Lead with self-service provisioning interfaces to minimize subscriber acquisition costs. For Investors and Strategic Acquirers: Re-rating potential sits with wholesale orchestrators possessing automotive OEM captive relationships given connected vehicle platform expansion. Long-term viability favors operators with software-defined network orchestration capabilities and host-operator diversification. Monitor FCC spectrum auction schedules as inflection indicator for wholesale capacity availability tightening.| Strategic Initiative | Industry Significance |
|---|---|
| API-Driven Service Orchestration | Unlocks enterprise self-service models through real-time provisioning platforms. |
| Network Slicing Certification | Grants access to German automotive logistics contracts specifying guaranteed latency tiers. |
| Automotive OEM Partnership | Captures over-the-air software update delivery and telematics aggregation contracts. |
| Digital-First Distribution Launch | Mint Mobile's model demonstrates subscriber acquisition cost optimization potential. |
| CSRD Sustainability Compliance | Mandates scope-three emissions documentation for European connectivity procurement. |
Methodological Framework
Regulatory filings, host-operator wholesale rate disclosures, and enterprise procurement databases formed the secondary backbone for this analysis. Primary interviews with MVNO platform engineers, host-operator wholesale contract managers, automotive fleet procurement leads, and enterprise IoT solution architects validated demand assumptions. FCC docket records, EU Roaming Regulation implementation reports, and TRAI licensing guidelines anchored supply-side characterization. Bottom-up subscriber volume estimates triangulated against top-down wholesale capacity assessments.
Historical trendline analysis of MVNO subscriber economics and wholesale rate evolution informed projection frameworks across the analysis window. Segmentation dimensions modeled include business model tier, service type, end-user category, and distribution channel maturity. CAGRs derived from slope analysis of normalized subscriber value trajectories. Forecast inputs incorporated host-operator consolidation timelines and spectrum release schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation between Ofcom and FCC jurisdictions and host-operator merger clearance decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Vietnam ICT Market
Telecommunications
5G Technology Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Ghana Telecom Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Video Door Phones Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Germany ICT Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Russia Telecom Market
Telecommunications
Poland Telecom Market