
 GCC Adult Diaper Market | 2026-2036
GCC Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Adult Diaper Market Intelligence
Market Context
Saudi FDA medical device classification rules is repositioning the cost-of-entry calculus for absorbent hygiene manufacturers seeking Gulf market access. Kimberly-Clark Corporation leverages its regional distribution infrastructure to sustain shelf presence across Saudi and UAE pharmacy networks. Essity AB anchors its competitive stance through specialized incontinence brands tailored to institutional buyers. Hayat Kimya San AS competes on manufacturing scale from its Turkish production base, extending cost-efficient supply into Bahrain and Oman.
Technical Definition and Segment Structure
GCC adult diapers are multi-layer absorbent garments engineered with superabsorbent polymer cores, breathable polyethylene back-sheets, and elastic leg gathers, manufactured through continuous web-forming and ultrasonic bonding processes to manage moderate-to-heavy urinary incontinence in non-ambulatory or mobility-limited adults. Disposable product types dominate volume due to infection-control protocols in hospitals and nursing homes, while biodegradable variants attract premium positioning among environmentally conscious institutional purchasers in the UAE. Senior citizens represent the deepest end-user pool, though caregiver-directed home care channels are expanding fastest as family-based eldercare shifts toward supervised community models.
Regulatory Frame and Outlook
Saudi FDA, UAE Ministry of Health and Prevention, and Gulf Standardization Organization (GSO) hygiene product standards collectively govern absorbency claims, skin-contact safety, and packaging disclosures across the six-member economic bloc. These frameworks elevate compliance burdens for new entrants while reinforcing incumbent brand loyalty among risk-averse hospital procurement committees. Stakeholders must monitor evolving medical device reclassification proposals and local-content incentives that could reroute supply chain investments toward domestic manufacturing zones.
Market Dynamics
Saudi FDA medical device reclassification is compressing product development cycles for absorbent hygiene manufacturers while simultaneously elevating capital requirements for Gulf market entry. This regulatory pressure is redrawing competitive boundaries across the six-member economic bloc.
Growth Catalysts
- Aging Demographics:Saudi Arabia's Riyadh-Jeddah corridor hosts the Gulf's fastest-growing senior population cohort, generating sustained institutional demand for heavy-absorbency products in long-term care settings.
- Superabsorbent Polymer Innovation:Next-generation SAP cores with 30% higher fluid retention capacity are extending wear-time intervals and reducing caregiver labor costs in hospital wards.
- GSO Harmonization:Gulf Standardization Organization hygiene product standards are eliminating duplicative testing requirements across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE, accelerating cross-border product registration.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices, tied to regional crude differentials, transmit directly to back-sheet and nonwoven fabric production costs.
- Import Dependency:Domestic manufacturing capacity for fluff pulp and SAP remains concentrated in Turkey and Southeast Asia, exposing GCC buyers to shipping rate fluctuations and customs clearance delays.
- Biodegradability Trade-offs:Plant-based absorbent materials currently sacrifice 15-20% fluid retention performance versus petroleum-derived alternatives, limiting their penetration in heavy-incontinence segments.
Strategic Opportunities
- Oman and Bahrain Underpenetration:These smaller Gulf states maintain lower per-capita institutional procurement rates, creating first-mover advantages for suppliers establishing direct distribution.
- Home Care Channel Expansion:E-commerce platforms and pharmacy delivery networks are displacing traditional wholesale medical supply distributors for caregiver-directed purchases.
- MOHAP Green Procurement Incentives:UAE Ministry of Health and Prevention preferential purchasing guidelines for environmentally certified products reward manufacturers with biodegradable SKU development.
Industry Challenges
- Regulatory Compliance Timeline Compression:Saudi FDA medical device classification transitions are shortening product registration windows from 18 months to 9 months, straining documentation and clinical testing resources.
- Ultrasonic Bonding Equipment Scarcity:Specialized converting machinery for elastic leg gather attachment faces 12-14 month delivery lead times from European and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Adult Diaper Market |
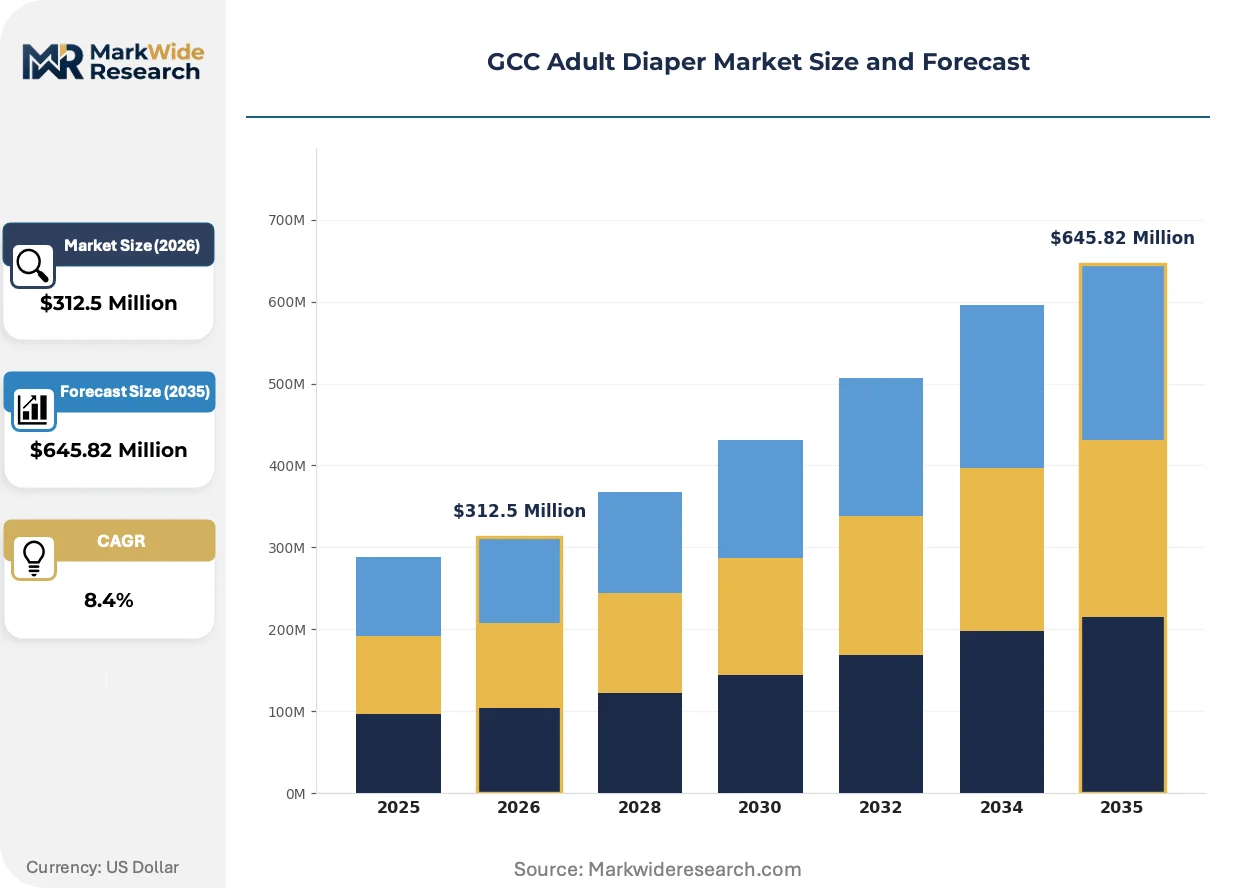
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Biodegradable, Underpads End User: Senior Citizens, Patients, Caregivers, Institutions Gender: Male, Female, Unisex, Others Distribution Channel: Retail, Online, Pharmacies, Supermarkets |
| Companies Covered | Unicharm Corporation, Paul Hartmann AG, Kimberly-Clark Corporation, Hayat Kimya San AS, Domtar Corporation, Essity AB, Ontex, Abena Group, Procter & Gamble, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Adult Diaper Market Strategic Shifts & Innovations
Product architecture and distribution pathways across the GCC are undergoing simultaneous transformation, with regulatory stringency and caregiver workflow optimization serving as the twin forcing functions reshaping competitive positioning.
Smart moisture-sensing indicators integrated into diaper back-sheets are electrifying the shift from scheduled-change protocols to condition-based care in Saudi nursing homes. These printed electronic sensors alert staff via handheld receivers when saturation thresholds breach optimal levels. Hospital procurement committees in Riyadh and Jeddah are electrifying their technical specifications to mandate this capability for new vendor qualifications.
Saudi FDA absorbency claim verification requirements are tightening labeling disclosures for all incontinence products marketed as medical devices. Manufacturers must now submit third-party laboratory testing for fluid retention capacity, rewet performance, and skin-contact biocompatibility. Heavy-absorbency product lines destined for long-term care facilities face the steepest documentation burdens, with several regional distributors expanding in-house regulatory affairs teams to manage submission volumes.
Caregiver-directed subscription models are displacing institutional bulk purchasing for home-based eldercare across the UAE's expatriate communities. Adult children managing parental incontinence remotely favor auto-replenishment deliveries with discrete packaging over pharmacy visits. Dubai and Abu Dhabi last-mile logistics providers are capturing this demand by integrating absorbent hygiene products into existing medication delivery infrastructure.
GCC Adult Diaper Market Segmentation
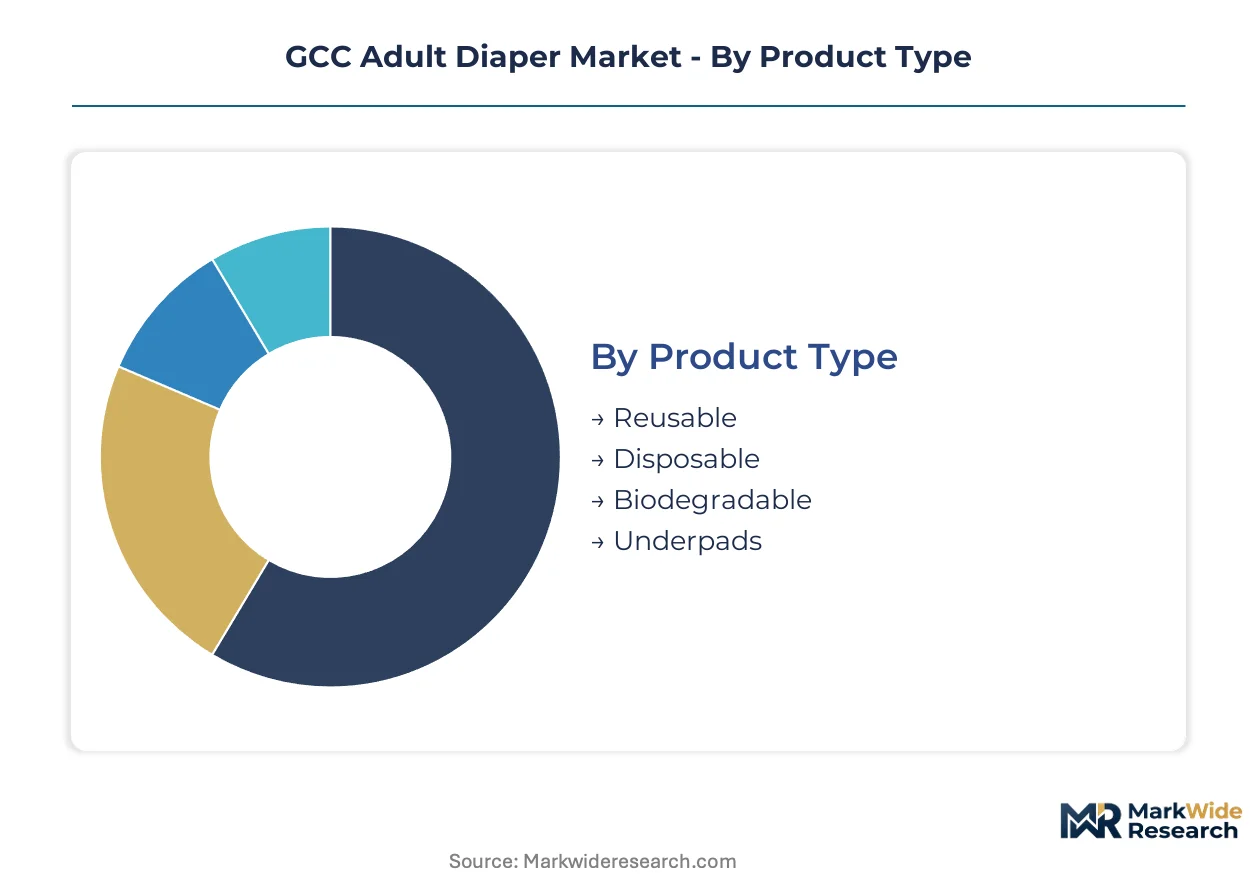
Adult diaper procurement across the GCC varies sharply by care setting and user mobility, with product specifications and channel preferences diverging between institutional buyers and family caregivers. Understanding these segment boundaries illuminates where manufacturers must adapt absorbency ratings, packaging formats, and regulatory documentation to capture volume.
Product Type:
Replacement cycles accelerate where infection-control protocols dominate purchasing decisions, compressing the upgrade window for manufacturers introducing higher-retention cores.
- Disposable:Multi-layer constructions with SAP cores and polyethylene back-sheets dominate hospital and nursing home procurement across Saudi Arabia's Riyadh-Jeddah corridor, driven by single-use mandates in MOHAP-licensed facilities.
- Biodegradable:Plant-based absorbent materials with reduced environmental footprint attract UAE institutional buyers responding to MOHAP green procurement incentives, though fluid retention trade-offs limit deployment in heavy-incontinence wards.
- Reusable:Washable cotton-polyester blends with waterproof PUL layers serve cost-conscious home caregivers in Bahrain and Oman where laundry infrastructure supports circular use models.
- Underpads:Disposable or washable sheet protectors with non-slip backing layer onto mattresses and furniture for bedridden patients, purchased in bulk by Saudi long-term care facilities.
Disposable products sit at the top of the volume ranking, with Biodegradable variants climbing the fastest as UAE sustainability mandates harden.
End User:
Cost tier differentiation separates institutional procurement committees seeking bulk absorbency certifications from individual buyers prioritizing discretion and delivery convenience.
- Senior Citizens:Non-ambulatory and mobility-limited elders across Saudi Arabia's aging demographic cohort generate sustained demand for heavy-absorbency overnight products with elastic leg gathers and wetness indicators.
- Patients:Hospital inpatients and post-surgical recovery cases require medical-grade products meeting Saudi FDA device classification standards for fluid retention and skin-contact biocompatibility.
- Caregivers:Family members managing home-based eldercare favor subscription-based auto-replenishment with discrete packaging, driving e-commerce penetration in Dubai and Abu Dhabi.
- Institutions:Long-term care facilities and rehabilitation centers in Riyadh and Jeddah negotiate annual supply contracts specifying SAP core performance thresholds and ultrasonic bonding quality.
Institutions command the highest absolute volume, with Caregiver-directed purchases expanding most quickly as family-based eldercare models shift toward supervised community support.
Gender:
Application-specific anatomical requirements shape product architecture, with unisex designs sacrificing fit precision for manufacturing scale advantages.
- Unisex:Standardized absorbent cores with symmetrical leg gathers serve institutional buyers seeking procurement simplicity across mixed-gender patient populations in Kuwait and Qatar.
- Female:Contoured designs with targeted absorbency zones address postpartum and age-related stress incontinence, concentrated in Saudi Arabia's female senior population.
- Male:Front-focused absorbent panels with secure fit systems serve prostate surgery recovery and mobility-limited male patients in UAE hospital wards.
- Others:Gender-neutral sizing and neutral packaging accommodate diverse user identities, primarily distributed through UAE and Saudi online channels with privacy-focused logistics.
Unisex products hold the volume lead, with Female-specific designs gaining share fastest as Saudi Arabia's female senior demographic expands.
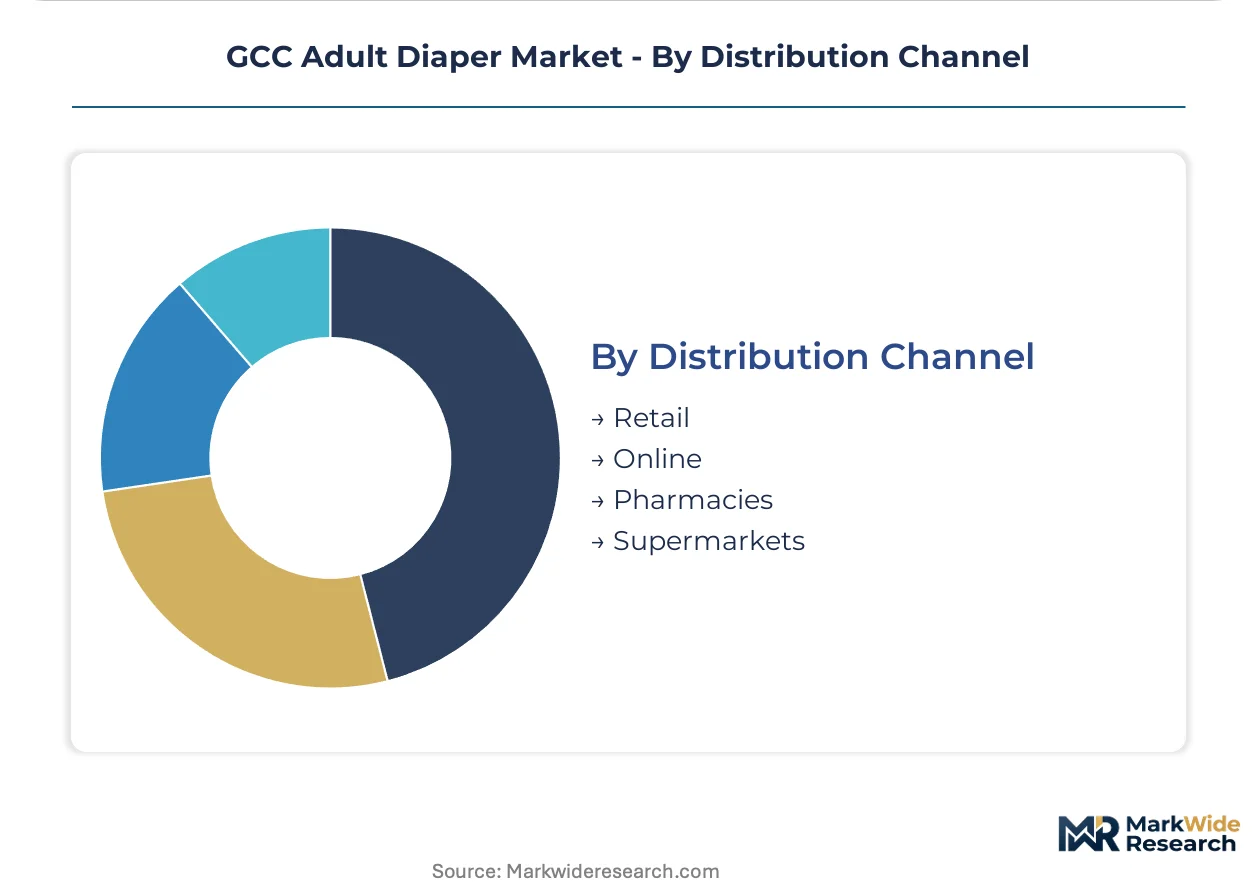
Distribution Channel:
Customer type fragmentation splits procurement between risk-averse institutional committees and convenience-seeking individual buyers, with channel investments diverging accordingly.
- Pharmacies:Licensed pharmacy networks across Saudi Arabia and UAE maintain shelf presence for caregiver-directed purchases, with pharmacists influencing brand selection through absorbency guidance.
- Online:E-commerce platforms and dedicated medical supply websites capture auto-replenishment subscriptions from expatriate caregivers in Dubai managing parental care remotely.
- Retail:Supermarket and hypermarket chains stock economy-tier products for price-sensitive consumers in Bahrain and Oman with lower institutional procurement penetration.
- Supermarkets:Mass-market retail formats in UAE and Saudi Arabia carry standard-absorbency SKUs targeting working-age stress incontinence and light leakage management.
Pharmacies anchor current volume, with Online channels showing the steepest expansion trajectory as last-mile logistics providers integrate absorbent hygiene into medication delivery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled nursing workforce concentrations across the Gulf Cooperation Council anchor absorbent hygiene procurement networks. Saudi Arabia's Riyadh-Jeddah corridor employs the region's largest cohort of certified eldercare professionals. UAE's Dubai Health Authority and MOHAP-licensed facilities attract Filipino and Indian nursing talent through structured recruitment pipelines.
Saudi Arabia
Aging demographics and hospital infrastructure investments generate institutional demand for heavy-absorbency products. Saudi FDA medical device classification requirements tighten absorbency verification and labeling standards for incontinence products marketed to long-term care facilities. Riyadh and Jeddah host the densest concentrations of MOH-licensed nursing homes and rehabilitation centers.
United Arab Emirates
Expatriate caregiver communities and green procurement mandates reshape distribution channels. MOHAP preferential purchasing guidelines reward manufacturers with biodegradable SKU development and environmental certifications. Dubai and Abu Dhabi logistics providers integrate absorbent hygiene into medication delivery infrastructure serving remote family caregivers.
Kuwait
Public health ministry procurement centralization standardizes absorbent hygiene specifications across government-subsidized eldercare facilities. The country's national pharmaceutical regulator enforces GSO hygiene product standards for cross-border registered medical devices. Kuwait City medical supply distributors maintain regional warehousing for re-export to Bahrain and Qatar.
Oman
Lower per-capita institutional procurement rates create first-mover advantages for suppliers establishing direct distribution. Ministry of Health licensing requirements for imported medical devices follow Saudi FDA alignment timelines with abbreviated documentation windows. Muscat and Salalah port infrastructure supports Turkish and Southeast Asian supply chain entry points.
Qatar
Hamad Medical Corporation standardization drives bulk purchasing consolidation for hospital and long-term care absorbent hygiene. The Supreme Council of Health mandates GSO-compliant absorbency testing for all incontinence products procured through central tender processes. Doha's healthcare city cluster concentrates procurement decision-making for specialized rehabilitation and eldercare services.
GCC Adult Diaper Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the GCC absorbent hygiene sector. Consumer goods multinationals leverage existing retail pharmacy relationships to secure institutional contracts, while regional manufacturers exploit geographic proximity to minimize shipping cost exposure. Three archetypes dominate: Turkish-scale producers with Gulf export specialization, European premium-brand houses with regulatory documentation depth, and Asian conglomerates with polymer science integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with ultrasonic bonding equipment scarcity forcing collaborative manufacturing arrangements.
Among diversified consumer health conglomerates, Kimberly-Clark Corporation and Procter & Gamble occupy positions shaped by decades of Gulf retail pharmacy network presence. Turkish manufacturer Hayat Kimya San AS exemplifies the scale-driven export archetype, leveraging proximity to Bahrain and Oman for cost-efficient supply extension. Essity AB and Paul Hartmann AG represent European pure-play specialists with institutional buyer certification depth. These named entities anchor competitive tiering without exhaustively mapping market share distribution.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Paul Hartmann AG |
| Kimberly-Clark Corporation |
| Hayat Kimya San AS |
| Domtar Corporation |
| Essity AB |
| Ontex |
| Abena Group |
| Procter & Gamble |
| Others |
Cost & Logistics Intelligence
Institutional procurement committees at Saudi long-term care facilities dominate volume absorption and enforce contract-based annual offtake agreements that compress margin elasticity for absorbent hygiene manufacturers. This buyer concentration amplifies pricing power asymmetry toward heavy-absorbency product tiers while squeezing standard-grade margins through specification standardization.
Pricing Analysis
Product-plus-service bundling separates premium-tier suppliers offering regulatory documentation support and caregiver training from unbundled transactional sellers in economy segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by Saudi FDA certification depth and SAP core performance thresholds. Cost compression in standard-grade tiers intensifies because Turkish manufacturers exploit proximity advantages to undercut European incumbents on freight-adjusted unit economics. Home care caregivers exhibit highest price sensitivity due to out-of-pocket payment structures, while hospital procurement committees prioritize absorbency certification over per-unit cost.
Supply Chain Analysis
Direct-to-institution channels handle hyperscale demand from Riyadh-Jeddah corridor nursing homes, while pharmacy wholesale networks serve caregiver-directed purchases across smaller Gulf states. Manufacturing concentration rests on Turkey, Southeast Asia, and Western Europe for fluff pulp and superabsorbent polymer feedstocks. Polypropylene and polyethylene resin dependencies draw from regional petrochemical complexes in Saudi Arabia and UAE. Single-source vulnerability in ultrasonic bonding equipment from European and Japanese suppliers creates 12-14 month capacity expansion bottlenecks. Distribution runs through Dubai and Jeddah as regional re-export hubs for Bahrain, Oman, and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC adult diaper procurement offers geographic-arbitrage potential where Saudi FDA regulatory stringency creates compliance cost premiums that Turkish manufacturers bypass through Gulf proximity. UAE green procurement mandates generate parallel arbitrage windows for biodegradable SKU development against petroleum-derived competitors.
For Market Incumbents: Cement institutional contract renewals by embedding smart moisture-sensing indicators as standard features before Saudi FDA mandates electrify technical specifications. Expand in-house regulatory affairs teams to compress 9-month registration windows into competitive moats. Vertical integration into SAP core production insulates margin positions against Southeast Asian shipping rate volatility.
For New Entrants and Emerging Players: The premium-economy price-point gap in Oman's underpenetrated institutional market offers white-space entry without incumbent contract lock-in. Target caregiver-directed subscription channels in Dubai's expatriate communities through discrete-packaging auto-replenishment partnerships with last-mile logistics providers. Pursue MOHAP green certification as differentiation lever for UAE hospital procurement committees.
For Investors and Strategic Acquirers: Turkish-scale manufacturers with Gulf export specialization are the most active acquirer targets in this space as equipment scarcity forces collaborative manufacturing arrangements. Long-term viability centers on backward integration into petrochemical feedstocks or captive SAP production capacity. Monitor Saudi FDA medical device reclassification timelines as inflection signal for compliance cost restructuring across the competitive tier.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable SKU Development | MOHAP green procurement incentives reward environmental certification with preferential tender access. |
| Smart Sensor Integration | Saudi nursing home electrification of technical specifications mandates moisture-alert capability for vendor qualification. |
| Regulatory Affairs Expansion | In-house documentation teams compress 9-month Saudi FDA registration windows into competitive differentiation. |
| Direct Distribution Buildout | Oman and Bahrain first-mover advantages accrue to suppliers bypassing Kuwaiti re-export intermediaries. |
| Backward Integration into SAP | Captive superabsorbent polymer production insulates margins against Southeast Asian shipping volatility. |
Research Approach
Bottom-up institutional procurement modeling reconciled against top-down absorbent hygiene production tracking forms the analytical core of this study. Primary interviews with long-term care facility procurement managers, Saudi FDA regulatory consultants, Turkish manufacturer export directors, UAE pharmacy chain category buyers, and Dubai logistics platform operators combined with secondary validation from GSO hygiene product standards, Saudi FDA medical device filings, MOHAP green procurement guidelines, customs trade records, and hospital supply contract databases. Triangulation across these sources ensures volume estimates align with actual institutional absorption patterns.
Input-output matrices map SAP core performance tiers against end-user mobility segments and distribution channel economics across the projection horizon. Segmentation dimensions modeled include product type, care setting, gender specification, and procurement channel. CAGRs derive from institution-level replacement cycle analysis and caregiver-directed purchase expansion rates. Forecast inputs incorporate Saudi aging demographic trajectories, MOHAP sustainability mandate progression, and petrochemical feedstock price sensitivity.
Caveats apply where Saudi FDA reclassification acceleration, biodegradable material performance trade-offs, or ultrasonic equipment delivery delays could materially shift the outlook. Forecasts reflect base-case assumptions around regulatory timeline adherence and supply chain continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Shoe Cover Market