
 Global Incontinence and Ostomy Care Product Market | 2026-2036
Global Incontinence and Ostomy Care Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Incontinence and Ostomy Care Product Market Foresight
The EU Medical Device Regulation is repositioning the cost-of-entry calculus for manufacturers seeking CE-marked ostomy pouch and skin barrier approvals in Europe. Coloplast Corp leverages its vertically integrated silicone adhesive manufacturing to sustain premium positioning across hospital and home care channels. Essity anchors its volume position through broad retail distribution of absorbent pads and elastic underwear in European pharmacies and supermarkets. Hollister Incorporated differentiates via specialized stoma care portfolios that compete on clinician training depth and direct-to-patient support infrastructure.
Incontinence and ostomy care products encompass absorbent hygiene articles, drainable and closed ostomy collection systems, and peristomal skin management devices engineered with hydrocolloid and acrylic adhesive layers to maintain wear time and moisture balance under physiological stress. These products serve the clinical management of urinary and fecal diversion, post-surgical recovery, and chronic mobility impairment by containing effluent and protecting peristomal integument. Ostomy pouches command durable margin pools due to recurring replenishment cycles and patient lock-in from custom-fit barrier systems, while online retailers represent the fastest-growing distribution channel as home care providers and individual users shift procurement away from brick-and-mortar medical supply stores. Elastic underwear and absorbent pads remain mature segments with price-competitive manufacturing concentrated among large-scale hygiene producers.
The FDA regulates these products as Class I and Class II medical devices under 21 CFR 876, enforcing biocompatibility and sterility standards that shape domestic market access timelines and clinical validation burdens. Japan's PMDA and METI coordinate on QMS certification and post-market surveillance for ostomy appliances, creating parallel compliance tracks for multinational manufacturers. Stakeholders must monitor how reimbursement coding reforms in Medicare and Japan's long-term care insurance system redirect demand between institutional procurement and direct patient purchasing models.
Market Dynamics
Home care providers are consolidating procurement authority while the EU Medical Device Regulation raises conformity costs for adhesive skin barrier manufacturers, compressing margin pools for non-integrated suppliers and accelerating channel consolidation toward direct-to-patient models.
Growth Catalysts
- Aging Demographics in Developed Economies:Japan's long-term care insurance system and Germany's Pflegeversicherung expand reimbursement for intermittent catheterization and stoma appliances, pulling demand from institutional settings into domestic environments.
- Silicone Adhesive Chemistry:Advanced hydrocolloid and silicone adhesive layers extend wear time for ostomy barriers, reducing peristomal skin complications and lowering total cost-of-care for home nursing programs.
- EU MDR Implementation:Stricter biocompatibility documentation requirements for pouch materials are filtering out marginal competitors and concentrating CE-marked supply among manufacturers with captive testing infrastructure.
Market Restraints
- Petrochemical Input Volatility:Acrylic and hydrocolloid adhesive production depends on propylene and natural rubber latex derivatives, exposing margin structures to energy feedstock fluctuations without pricing power to pass through.
- Supply Concentration in Southeast Asia:Elastic nonwoven fabric and superabsorbent polymer manufacturing clusters in Thailand and Malaysia create single-source vulnerability for European and North American hygiene converters.
- Reimbursement Compression:Medicare's competitive bidding program for urological supplies caps allowable charges for intermittent catheters, squeezing distributor markups and forcing volume commitments.
Strategic Opportunities
- Brazil and Mexico Underpenetration:Direct-to-consumer e-commerce channels for ostomy pouches remain nascent in Latin America, offering first-mover positioning before local distributors consolidate.
- Smart Wearable Integration:Sensor-enabled ostomy appliances that monitor effluent volume and skin pH are converging with telehealth platforms, opening recurring SaaS revenue streams alongside hardware replenishment.
- Japan's Community-Based Care Reform:METI incentives for preventive stoma management are redirecting procurement toward specialized home care agencies with training certification requirements.
Industry Challenges
- Clinical Specialist Shortage:Enterostomal therapy certification programs in the United States and United Kingdom are producing insufficient wound care nurses to support expanding home care populations.
- CE Marking Timeline Compression:EU MDR notified body backlogs are extending technical file review periods for barrier adhesive innovations, delaying product launches by 18-24 months against commercial plans.
- Legacy ERP Integration:Hospital procurement systems using GS1 standards struggle to synchronize with direct-to-patient subscription platforms, creating order fulfillment friction and inventory mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Incontinence and Ostomy Care Product Market |
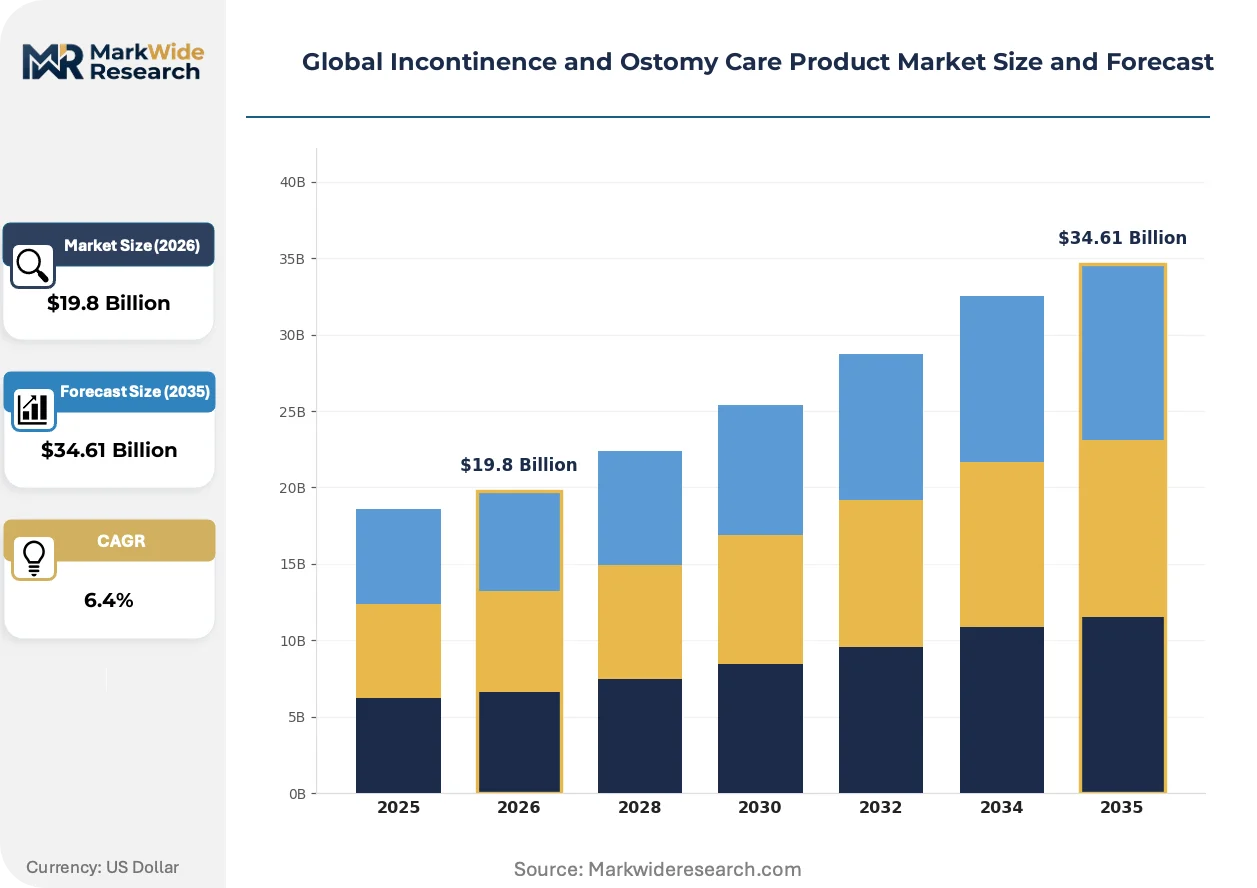
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Diapers, Ostomy Pouches, Absorbent Pads, Skin Barriers, Elastic Underwear Application: Urinary Incontinence, Fecal Incontinence, Post-Surgical Care, Elderly Care, Mobility Impairment End User: Hospitals, Nursing Facilities, Home Care Providers, Rehabilitation Centers, Specialty Clinics Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales, Supermarkets |
| Companies Covered | Coloplast Corp, ConvaTec Group Plc, Kimberly-Clark Corporation, Hollister Incorporated, B. Braun Melsungen AG, Unicharm Corporation, Essity, Domtar Corporation, Welland Medical Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Incontinence and Ostomy Care Product Market Shifts & Advancements
Material science advances and regulatory documentation burdens are simultaneously elevating product performance thresholds and raising competitive barriers, while channel migration toward specialized e-commerce platforms is rewiring traditional distributor relationships.
Silicone-based skin barriers with integrated moisture management layers are consolidating market share among home care providers seeking extended wear times. Hospital discharge planners are specifying these systems for post-surgical stoma patients to reduce readmission risk. The technology is consolidating procurement decisions around manufacturers with captive silicone polymer production and clinical training infrastructure.
The EU Medical Device Regulation's enhanced clinical evidence requirements for adhesive contact layers are extending approval timelines for pouch system modifications. Manufacturers must now submit biocompatibility testing under ISO 10993 protocols that were previously accepted as supplier declarations. German notified bodies are processing these submissions with 14-18 month queues, forcing portfolio prioritization toward high-margin barrier systems over commodity drainable pouches.
Home care agencies are aggregating purchasing authority through group purchasing organizations and direct manufacturer contracts, bypassing traditional medical supply distributors. Specialized ostomy product subscriptions with auto-replenishment algorithms are displacing periodic retail pharmacy purchases in the United States and United Kingdom. This channel compression is most visible in Medicare Advantage plans where care coordinators manage stoma supply benefits as part of bundled post-acute care programs.
Global Incontinence and Ostomy Care Product Market Segmentation
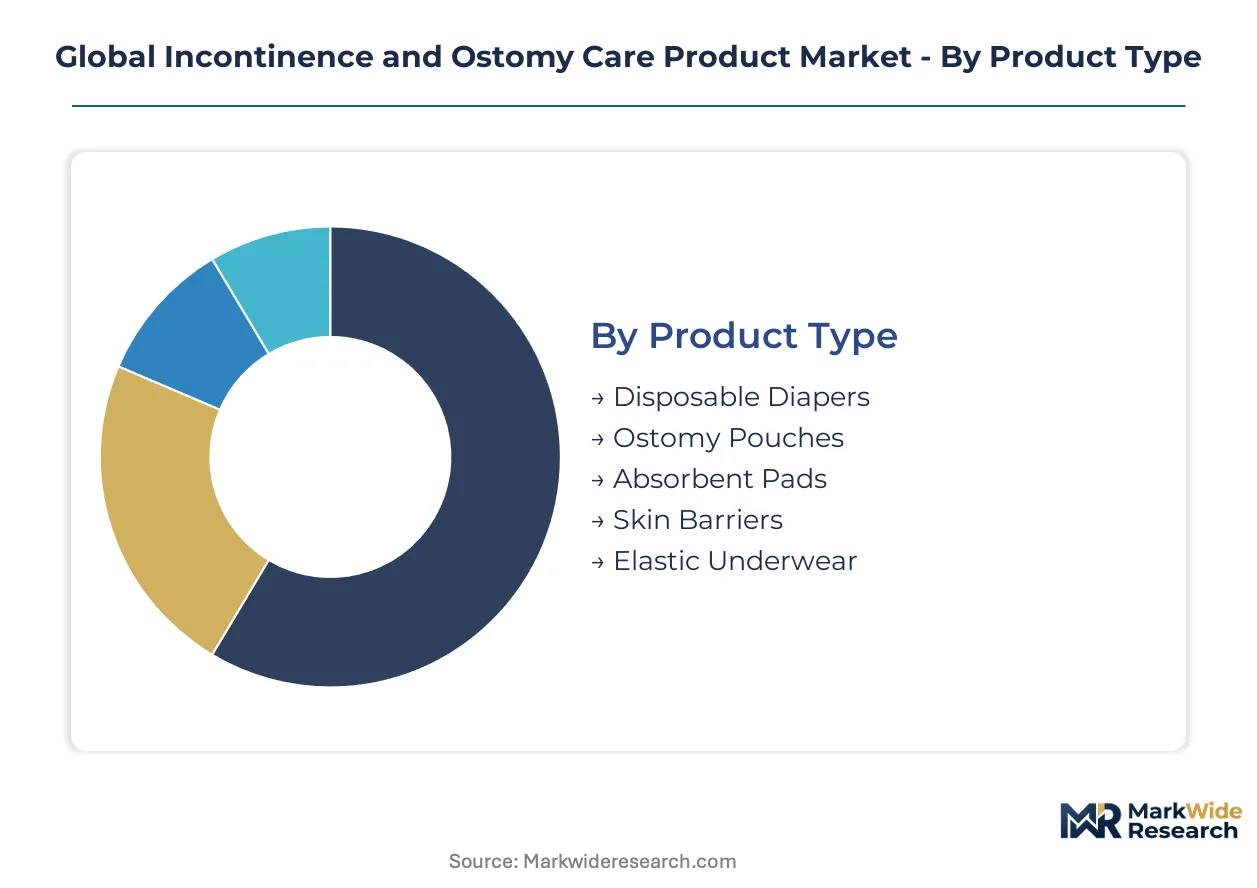
Product differentiation in incontinence and ostomy care hinges on wear time, skin compatibility, and reimbursement coding. Segmentation reveals where margin pools concentrate and which channels are consolidating procurement authority.
Product Type:
Replacement cycles vary dramatically across product categories, with some systems requiring daily replenishment while others lock patients into multi-week wear schedules.
- Ostomy Pouches:Drainable and closed systems utilize hydrocolloid or silicone adhesive flanges to secure stoma interfaces. Demand clusters in Germany and Japan where long-term care insurance covers specialized appliances, though EU MDR biocompatibility documentation is extending approval timelines for new barrier chemistries.
- Skin Barriers:Hydrocolloid and acrylic adhesive rings protect peristomal skin from enzymatic effluent damage. Home care providers in the United States are consolidating procurement around extended-wear silicone formulations that reduce nursing visit frequency.
- Disposable Diapers:Superabsorbent polymer cores with elastic nonwoven chassis serve acute and community settings. Retail pharmacy chains in France and Italy dominate volume distribution.
- Absorbent Pads:Anatomically shaped inserts with acquisition layers target light-to-moderate urinary loss. Supermarket and pharmacy channels in Germany and the United Kingdom drive replenishment velocity.
- Elastic Underwear:Pull-up designs with breathable waistbands serve mobile elderly populations. Manufacturing concentrates among large-scale hygiene converters with captive nonwoven production.
Ostomy pouches sit at the top of the volume ranking, with skin barriers climbing the fastest as home care programs prioritize extended-wear systems.
Application:
Clinical severity and reimbursement tier determine product specification, with post-surgical pathways commanding premium pricing compared to chronic management.
- Post-Surgical Care:Temporary and permanent stoma management following colorectal or urological procedures requires specialized pouch systems with cut-to-fit barriers. Hospital discharge planners in the United States and Germany increasingly specify silicone-adhesive platforms to reduce readmission risk.
- Elderly Care:Age-related sphincter weakness and cognitive decline drive demand for absorbent hygiene with odor control. Japan's long-term care insurance system and Germany's Pflegeversicherung expand reimbursement for intermittent catheterization and pad replenishment.
- Urinary Incontinence:Stress, urge, and mixed incontinence patterns require differentiated absorbency and fit. Medicare competitive bidding in the United States caps allowable charges for intermittent catheters.
- Fecal Incontinence:Passive leakage and urgency management demands higher-capacity systems with secure containment. Specialist stoma nurses in the United Kingdom prescribe custom-fit appliances.
- Mobility Impairment:Spinal cord injury and neurological conditions necessitate catheterization and pouch systems compatible with wheelchair positioning. Rehabilitation centers in the United States coordinate discharge supply planning.
Elderly care captures the largest addressable population, with post-surgical applications expanding most quickly as enhanced recovery protocols shorten hospital stays.
End User:
Procurement authority is migrating from institutional purchasing departments toward specialized home care agencies with direct manufacturer contracts.
- Home Care Providers:Specialized agencies manage stoma and continence supply benefits under bundled post-acute care programs. Medicare Advantage plans in the United States are consolidating purchasing through group purchasing organizations.
- Hospitals:Acute care settings drive initial stoma appliance selection during post-surgical discharge planning. German hospital procurement systems specify CE-marked barrier systems with ISO 10993 biocompatibility documentation.
- Nursing Facilities:Long-term residential care requires high-volume absorbent hygiene with staff-efficient change protocols. Medicaid reimbursement variations across United States states shape product tier selection.
- Specialty Clinics:Enterostomal therapy and wound care centers provide custom fitting and patient education. Certification requirements in the United Kingdom limit qualified clinician availability.
- Rehabilitation Centers:Neurogenic bladder and bowel management programs coordinate transition to community-based care. METI incentives in Japan redirect procurement toward certified home care agencies.
Home care providers now lead procurement volume, with specialty clinics gaining share fastest as stoma nurse certification programs expand.
Distribution Channel:
Channel economics are compressing as direct-to-patient subscriptions displace traditional distributor markups.
- Online Retailers:Specialized ostomy product platforms with auto-replenishment algorithms are displacing periodic pharmacy purchases. Amazon and dedicated medical supply sites dominate in the United States and United Kingdom.
- Direct Sales:Manufacturer-to-patient subscription models bypass distributor margins and capture patient data for adherence programs. Coloplast and Hollister maintain dedicated direct channels in Europe and North America.
- Pharmacies:Community and hospital pharmacies retain pad and diaper volume through prescription fulfillment and retail foot traffic. Boots and CVS maintain significant shelf space.
- Medical Supply Stores:Traditional durable medical equipment dealers face margin pressure from home care consolidation and competitive bidding. Independent stores in rural United States markets struggle against national chains.
- Supermarkets:Mass retail channels drive elastic underwear and light incontinence pad volume through price-competitive positioning. Tesco and Carrefour maintain private-label offerings.
Pharmacies retain the largest transaction volume, with online retailers expanding most quickly as auto-replenishment algorithms capture patient loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stoma care nurses and enterostomal therapy certification programs concentrate in Germany, Japan, and the United States, anchoring regional demand clusters for advanced ostomy systems and home care coordination.
United States
Medicare Advantage plans and bundled post-acute care programs are consolidating procurement authority among specialized home care agencies. FDA Class II device regulations under 21 CFR 876 enforce biocompatibility standards that shape domestic market access timelines. Cleveland Clinic and Mayo Clinic stoma care centers in Ohio and Minnesota drive clinical protocol standardization for silicone-adhesive barrier systems.
Germany
Pflegeversicherung reimbursement expansion pulls demand from institutional settings into domestic environments for intermittent catheterization and stoma appliances. EU MDR notified bodies in Berlin and Munich are processing biocompatibility submissions with 14-18 month queues, filtering out marginal competitors. The Rhine-Ruhr industrial corridor hosts concentrated medical device manufacturing for hydrocolloid adhesive production.
Japan
METI incentives for preventive stoma management redirect procurement toward certified home care agencies with training requirements. PMDA and METI coordinate on QMS certification and post-market surveillance for ostomy appliances, creating parallel compliance tracks. Tokyo and Osaka metropolitan areas concentrate aging populations with mature long-term care insurance pathways.
United Kingdom
NHS stoma care services and enterostomal therapy certification programs in London and Manchester support expanding home care populations. MHRA post-Brexit regulatory alignment with EU MDR documentation requirements extends approval timelines for barrier innovations. The Oxford-Cambridge arc hosts specialized wound care research clusters advancing peristomal skin management protocols.
Brazil
Direct-to-consumer e-commerce channels for ostomy pouches remain nascent, offering first-mover positioning before local distributors consolidate. ANVISA medical device registration requirements create compliance barriers for imported barrier systems. São Paulo's healthcare infrastructure anchors specialized stoma nurse training programs serving Southeast regional demand.
Global Incontinence and Ostomy Care Product Market Competitive Landscape
The competitive structure tilts toward vertically integrated manufacturers with captive adhesive production and clinical training infrastructure. Tiered positioning separates premium silicone-barrier specialists from volume-scale hygiene converters and regional distributors. Three archetypes dominate: integrated medical device manufacturers with in-house polymer production, large-scale hygiene conglomerates leveraging retail distribution breadth, and specialized ostomy care providers competing on clinician education depth. Consolidation pressures favor backward integration into adhesive raw materials and direct-to-patient subscription platforms bypassing traditional distributor markups.
Among integrated specialists, Coloplast Corp, Hollister Incorporated, and ConvaTec Group Plc occupy positions defined by clinical support infrastructure and barrier chemistry capabilities. Coloplast represents the vertically integrated archetype with silicone adhesive manufacturing control. Hollister exemplifies specialized stoma care portfolio depth. ConvaTec sits within the advanced wound care convergence space. These three anchors demonstrate how procurement consolidation toward home care providers rewards manufacturers combining product performance with patient education programs.
| Leading Market Players |
|---|
| Coloplast Corp |
| ConvaTec Group Plc |
| Kimberly-Clark Corporation |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| Unicharm Corporation |
| Essity |
| Domtar Corporation |
| Welland Medical Ltd |
| Others |
Supply & Pricing Matrix
Silicone-adhesive premium tier divergence from commodity hydrocolloid systems manifests in both pricing power and supply chain configuration, with German and Japanese reimbursement pathways rewarding extended-wear performance while Southeast Asian manufacturing clusters feed price-competitive pad and diaper segments.
Pricing Analysis
Bundled post-acute care contracts against unbundled retail pharmacy purchases split pricing models across the market. Subscription-based auto-replenishment for ostomy systems commands premium positioning through patient lock-in, while spot purchasing of absorbent pads in European supermarkets operates on volume-scale commodity economics. Price differentiation rests on CE marking tier and clinical training bundling, with FDA Class II certification adding validation costs that filter marginal competitors. Cost compression in the retail absorbent segment intensifies as Thai and Malaysian hygiene converters expand capacity, though Medicare competitive bidding caps create pricing floors for intermittent catheter reimbursement. Home care providers exhibit lowest price sensitivity due to bundled benefit structures, while individual cash-pay patients in Brazil and Mexico drive hard bargains on drainable pouch systems.
Supply Chain Analysis
Workforce availability constraints in Thailand and Malaysia shape elastic nonwoven and superabsorbent polymer manufacturing, where skilled technician pools for polymerization chemistry remain thinner than in German or Japanese adhesive production corridors. Raw material flows draw from Saudi petrochemical feedstocks for propylene derivatives, Malaysian natural rubber latex for hydrocolloid bases, and Japanese silicone monomer production for premium barrier systems. Single-source vulnerability concentrates in Southeast Asian SAP manufacturing, where flooding or energy rationing could disrupt European and North American hygiene converter supply. Distribution runs through specialized medical supply distributors in institutional channels, direct-to-patient subscription platforms in Medicare Advantage markets, and mass retail chains for light incontinence products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU MDR compliance costs and Latin American regulatory lag creates margin expansion opportunities for manufacturers willing to front-load Berlin or Munich notified body investments while capturing Brazilian direct-to-consumer growth ahead of ANVISA harmonization.
For Market Incumbents: Acquire captive silicone polymer production capabilities to defend margin pools against commodity hydrocolloid competitors and secure supply continuity through propylene derivative volatility. Consolidate procurement relationships with Medicare Advantage care coordinators before group purchasing organizations complete vendor rationalization. Backward integration into adhesive raw materials hedges against petrochemical input swings while CE marking investment filters second-tier challengers from German hospital procurement lists. For New Entrants and Emerging Players: EU MDR implementation in Germany opens a window for specialized stoma care platforms that combine silicone barrier innovation with clinical education infrastructure, bypassing saturated retail absorbent segments. Brazil's nascent direct-to-consumer e-commerce channels offer first-mover positioning before São Paulo distributors consolidate around incumbent brands. Target certified home care agencies in Japan's community-based care reform zones with METI-aligned training programs and localized inventory staging. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale manufacturers possessing ISO 10993 testing infrastructure and pending CE marking submissions that will clear 14-18 month notified body queues ahead of competitor filings. Long-term viability over the next decade favors archetypes combining captive adhesive production with direct-to-patient subscription platforms, as channel compression eliminates traditional distributor markups. Watch EU MDR technical file approval velocity as the inflection signal—accelerating clearance rates indicate regulatory capacity expansion that would erode first-mover compliance advantages.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility documentation under ISO 10993 protocols secures German hospital procurement access. |
| Direct-to-Patient Subscription Platform | Auto-replenishment algorithms capture Medicare Advantage stoma benefit loyalty ahead of GPO consolidation. |
| Silicone Adhesive Manufacturing Scale-Up | Captive polymer production insulates margin structures from propylene derivative volatility in feedstock markets. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic protocol standardization drives silicone-barrier specification at discharge planning. |
| Reimbursement Strategy | Pflegeversicherung and Japan LTCI pathway alignment pulls demand from institutional into domestic care settings. |
Research Methodology
Direct dialogue with enterostomal therapy nurses, hospital procurement committee members, biomedical engineers specializing in adhesive biocompatibility, and group purchasing organization contract managers grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) filings for Class II urological devices, EUDAMED CE marking registration databases, CMS Medicare competitive bidding program announcements, and Japanese METI long-term care insurance policy circulars. Bottom-up demand modeling across product segments triangulated against top-down macroeconomic indicators and demographic aging trajectories.
Top-down regional economic projections anchored the analytical lens, with bottom-up segment builds across ostomy pouches, skin barriers, absorbent pads, and elastic underwear categories. Modeled dimensions included adhesive chemistry tier, wear time performance, reimbursement coding eligibility, and distribution channel structure throughout the forecast period. CAGRs derived from historical replenishment velocity patterns, insurance coverage expansion schedules, and technology substitution curves for silicone versus hydrocolloid systems. Forecast inputs incorporated EU MDR approval timeline distributions and Medicare Advantage enrollment shifts toward bundled post-acute care.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EU MDR notified body backlogs or abrupt petrochemical feedstock disruptions. Projections reflect assumptions regarding reimbursement stability, regulatory harmonization pace, and patient adherence to prescribed replacement cycles. Material deviation in CE marking queue lengths, silicone monomer supply disruptions, or Medicare competitive bidding program expansions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Abdominal Pads Market