
 Sales Coaching Software Market | 2026-2036
Sales Coaching Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Coaching Software Market Outlook
Enterprise-grade certification standards is reorganizing competitive dynamics across the Sales Coaching Software landscape. Gong leverages proprietary conversation intelligence to anchor its position in revenue intelligence workflows. Highspot sustains differentiation through unified enablement platforms that span content management and coaching analytics. Mindtickle competes by extending its readiness methodology into structured certification programs for field sales organizations.
Sales coaching software denotes platforms that apply machine learning to recorded sales conversations, delivering real-time behavioral feedback, skill gap analysis, and personalized training curricula to improve rep performance. Cloud-based deployment dominates structural investment, with hybrid architectures gaining traction among regulated industries requiring local data residency. Performance tracking modules capture disproportionate margin pools as enterprises prioritize measurable quota attainment over generic training content. API support integration levels are accelerating fastest, reflecting buyer demand for seamless connectivity with existing CRM and revenue operations stacks.
FDA oversight applies where coaching platforms interface with regulated medical device sales training, while FCC frameworks govern voice data capture and storage protocols across telephony-integrated systems. GDPR and emerging US state privacy laws are forcing vendors to rearchitect data processing pipelines, elevating compliance costs but also creating barriers for non-compliant entrants. Stakeholders must monitor evolving AI disclosure requirements that could mandate explicit notification when automated systems analyze human sales conversations.
Market Dynamics
AI-powered conversation intelligence is compressing sales coaching cycles from quarterly reviews to real-time behavioral interventions, forcing vendors to rearchitect data pipelines for sub-second latency.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face mandatory algorithmic transparency requirements for workforce analytics tools, accelerating replacement of legacy coaching platforms with auditable AI systems.
- Pharmaceutical field sales digitization:Medical device and therapeutic sales teams require FDA-validated training records, driving demand for certified coaching platforms with immutable audit trails.
- API-first integration architectures:Revenue operations teams prioritize coaching tools that embed directly into Salesforce and HubSpot workflows rather than standalone applications.
Market Restraints
- Cloud compute cost volatility:Real-time transcription and sentiment analysis consume substantial GPU resources, compressing margins for vendors without negotiated hyperscaler contracts.
- Data residency fragmentation:Germany's Bundesdatenschutzgesetz and France's CNIL guidance impose conflicting localization requirements, forcing redundant infrastructure deployment.
- Telephony integration technical debt:Legacy PBX systems lack modern webhook architectures, requiring expensive middleware development for established enterprise accounts.
Strategic Opportunities
- India's PLI scheme for SaaS:Production-linked incentives for software exports create cost advantages for vendors establishing development centers in Bangalore and Hyderabad.
- Conversational AI and emotion recognition convergence:Multimodal analysis combining voice stress detection with linguistic patterns enables predictive coaching interventions before deal deterioration.
- Outcome-based pricing models:Vendors can capture value through quota attainment-linked contracts rather than per-seat subscriptions, aligning incentives with customer success metrics.
Industry Challenges
- Sales methodology certification bottlenecks:MEDDIC, Challenger, and Sandler-trained coaches command premium salaries, constraining vendor ability to staff implementation teams.
- HIPAA-aligned security architecture complexity:Healthcare-focused coaching platforms require Business Associate Agreements with every downstream transcription provider, extending procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Coaching Software Market |
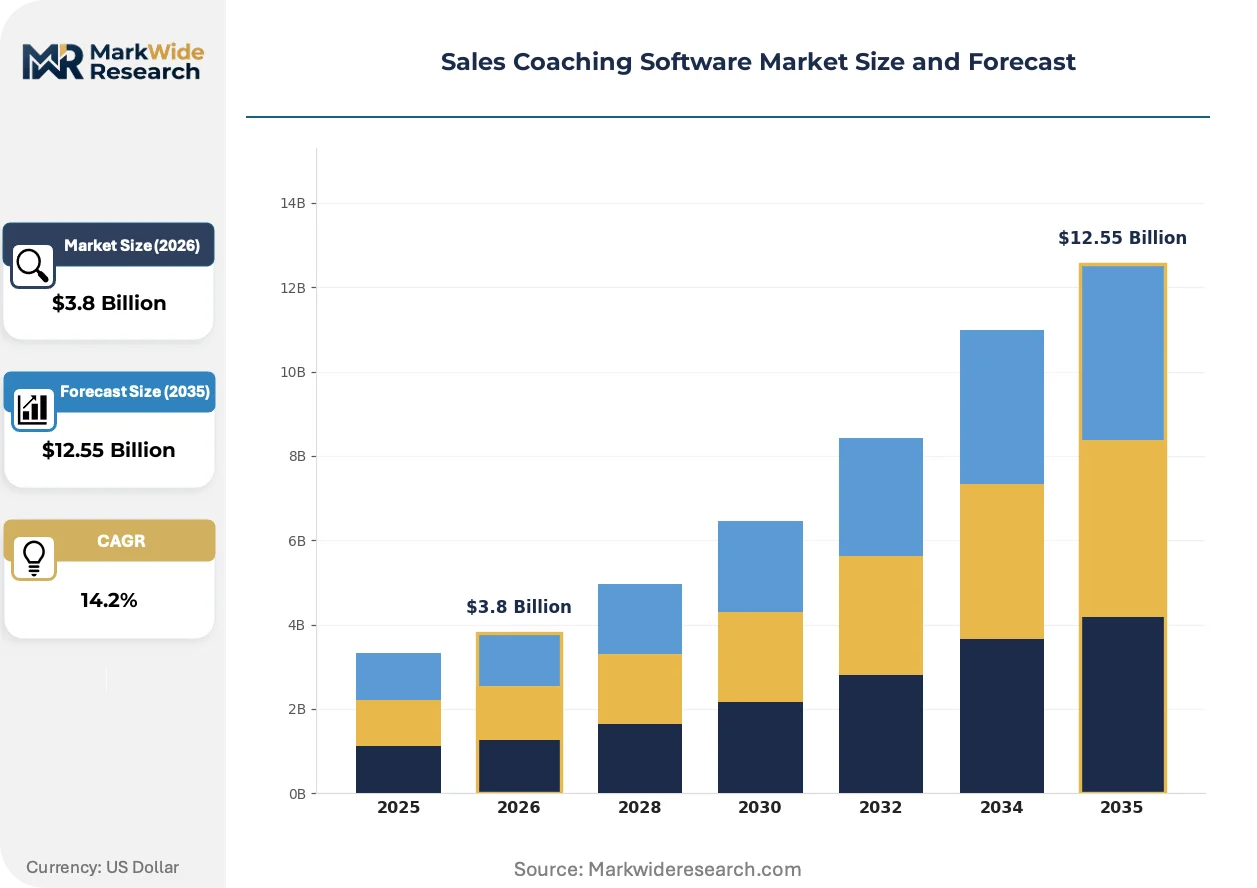
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboarding Tools, Performance Tracking, Feedback Systems, Simulation Software Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions End User: SMBs, Enterprises, Sales Teams, Coaches Integration Level: CRM Integration, API Support, Single Sign-On, Reporting Tools |
| Companies Covered | Mindtickle, Allego, Spekit, Nooks, Zime.ai, Highspot, Salesloft, Second Nature, Gong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Coaching Software Market Strategic Shifts
Generative AI is compressing content creation cycles for personalized coaching curricula while simultaneously raising the bar for platform differentiation beyond basic transcription accuracy.
Large language model fine-tuning for sales-specific domains is bifurcating vendor strategies between general-purpose GPT wrappers and proprietary models trained on curated conversation datasets. Enterprise buyers with stringent data governance requirements favor the latter approach despite higher implementation costs. This technical divergence is concentrating margin capture among vendors with sufficient training data scale to justify dedicated model development.
The EU AI Act's risk classification framework is forcing conversation analytics vendors to implement explicit human-in-the-loop review mechanisms for high-stakes employment decisions. Systems flagging reps for performance improvement plans now require documented human validation before disciplinary action. German and French deployments are experiencing the steepest compliance cost increases due to existing national labor protection precedents.
Buyer procurement patterns are compressing vendor evaluation cycles from twelve-month pilots to ninety-day proof-of-concept mandates. Revenue operations leaders now demand measurable quota impact within one sales quarter before enterprise-wide rollout authorization. This acceleration is most pronounced in United States technology sector deployments where CFO scrutiny of SaaS spend intensifies.
Sales Coaching Software Market Segmentation
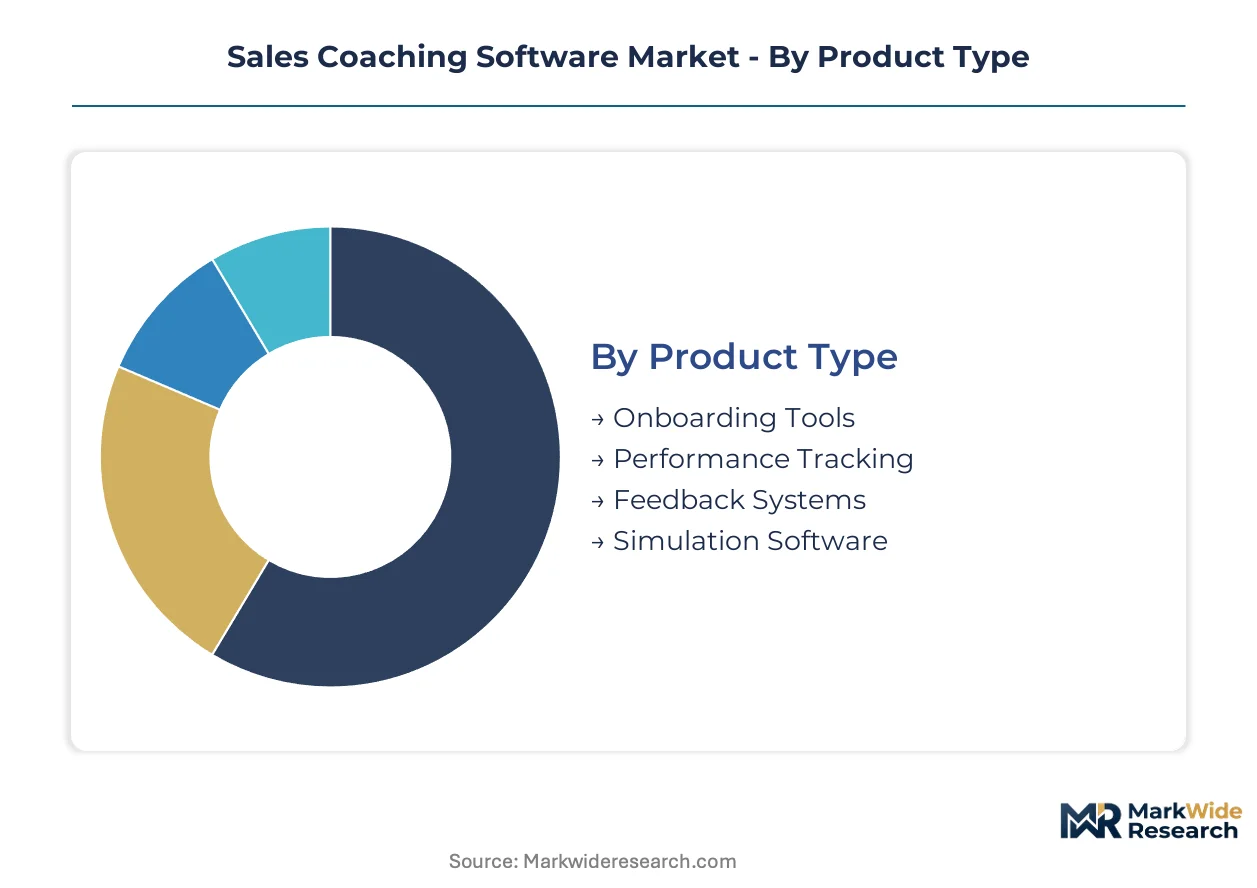
Sales coaching software segmentation reveals how regulatory pressure and integration architecture reshape vendor priorities. Product type and deployment choices determine compliance burden, while end-user scale dictates pricing model viability.
Product Type:
GDPR and the EU AI Act impose divergent audit requirements across functional modules, with workforce analytics facing stricter algorithmic transparency mandates than training content delivery.
- Onboarding Tools:Structured curriculum platforms automate rep certification workflows with embedded competency assessments. Demand concentrates in pharmaceutical field sales requiring FDA-validated training records, constrained by HIPAA-aligned security architecture complexity that extends procurement timelines through Business Associate Agreement negotiations.
- Performance Tracking:Real-time quota attainment dashboards capture disproportionate margin pools as CFO scrutiny intensifies. United States technology sector deployments prioritize measurable revenue impact within ninety-day proof-of-concept windows over generic training metrics.
- Feedback Systems:Behavioral coaching interfaces delivering post-call analysis.
- Simulation Software:Role-play environments with AI-generated buyer personas for skill rehearsal.
Established volume favors Performance Tracking; emerging adoption favors Simulation Software.
Deployment:
Cost tier differentiation separates hyperscaler-negotiated cloud contracts from capital-intensive on-premises infrastructure requiring dedicated security operations centers.
- Cloud-Based:Dominant architecture leveraging AWS, Azure, and GCP for elastic transcription compute. Germany's Bundesdatenschutzgesetz and France's CNIL guidance impose conflicting data localization requirements, forcing redundant regional infrastructure deployment that compresses margins for vendors without scale.
- Hybrid:Split processing architectures retaining sensitive conversation data on local servers while pushing analytics to cloud pipelines. Regulated industries in Switzerland and Saudi Arabia favor this model for voice data residency compliance, climbing the fastest as GDPR enforcement tightens.
- On-Premises:Fully air-gapped installations for defense and intelligence contractor sales teams.
- Mobile Solutions:Native iOS and Android applications for field sales accessibility.
Cloud-Based maintains share leadership; Hybrid gains preference among compliance-sensitive buyers.
End User:
Customer maturity determines feature complexity tolerance, with enterprise procurement teams demanding API-first architectures that SMBs rarely staff to implement.
- Enterprises:Multi-division rollouts requiring Salesforce and HubSpot native embedding. Revenue operations teams mandate sub-second latency for real-time coaching interventions, driving vendor rearchitecture of transcription pipelines from batch to streaming architectures.
- SMBs:Price-sensitive adopters prioritizing out-of-box functionality over customization. India's PLI scheme for SaaS exports creates cost advantages for vendors serving this tier through Bangalore and Hyderabad development centers.
- Sales Teams:Frontline rep-facing tools for individual skill development.
- Coaches:Manager workstations for curriculum design and intervention planning.
Enterprise contracts anchor vendor revenue; SMB subscriptions expand addressable market breadth.
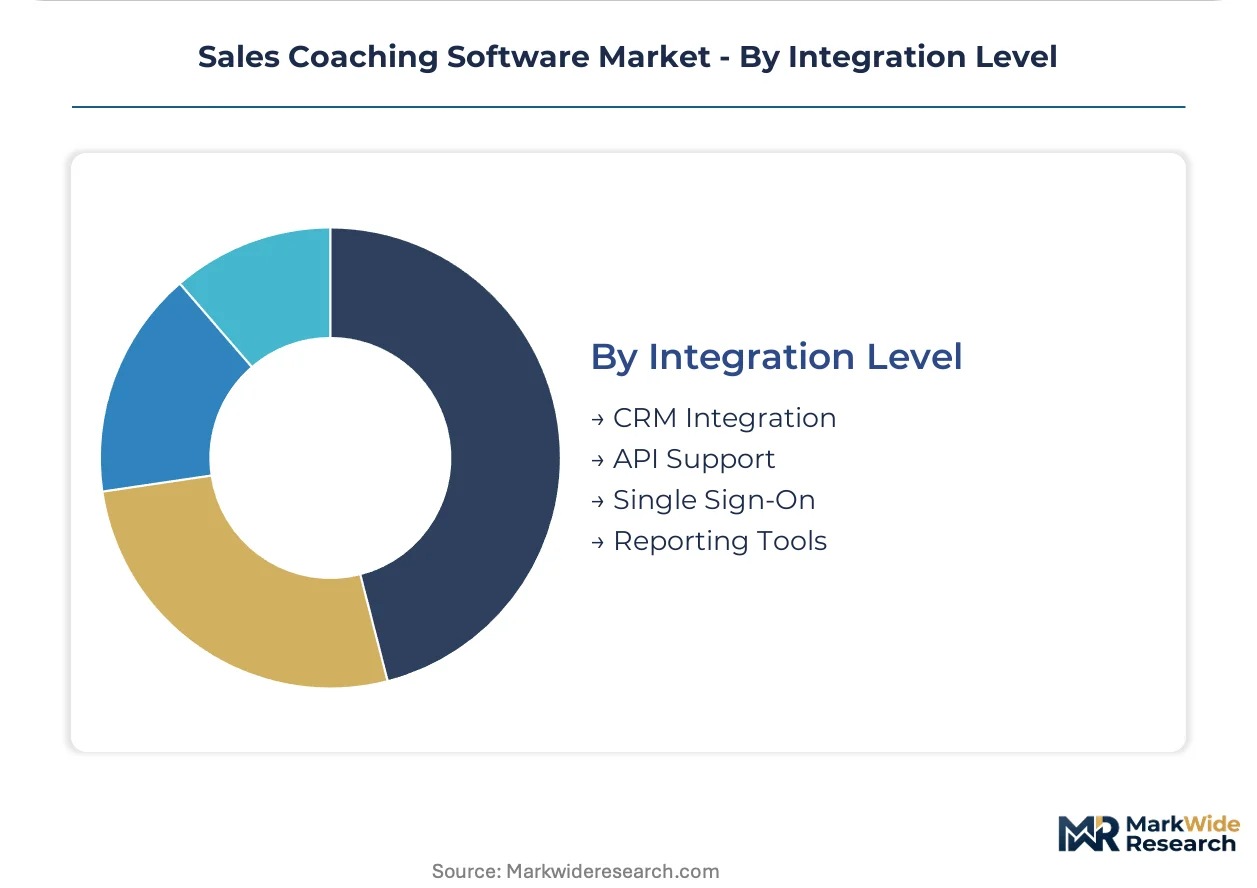
Integration Level:
Margin concentration follows connectivity depth, with API support commanding premium pricing over basic single sign-on functionality.
- API Support:Webhook and REST architectures enabling custom workflow embedding. FCC frameworks govern voice data capture protocols across telephony-integrated systems, requiring vendors to maintain middleware compatibility with legacy PBX infrastructure.
- CRM Integration:Native Salesforce, HubSpot, and Microsoft Dynamics connectors. United States deployments prioritize seamless revenue operations stack connectivity over standalone application value, steepest expansion trajectory as procurement cycles compress.
- Single Sign-On:SAML and OAuth implementations for identity provider federation.
- Reporting Tools:Pre-built dashboards for executive consumption without technical configuration.
CRM Integration dominates current procurement; API Support determines competitive defensibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers prioritize measurable quota impact within compressed ninety-day evaluation windows, while Indian SMBs gravitate toward cost-optimized deployments. European procurement teams balance algorithmic transparency mandates against integration complexity premiums.
United States
Revenue operations teams in San Francisco and New York Metro demand sub-second latency for real-time coaching interventions. FCC frameworks govern voice data capture protocols across telephony-integrated systems, requiring middleware compatibility with legacy PBX infrastructure. Austin and Seattle technology sector deployments anchor North American demand for API-first architectures.
Germany
Industrial manufacturing sales teams in Munich and Stuttgart require Bundesdatenschutzgesetz-compliant conversation analytics with local data residency. EU AI Act algorithmic transparency mandates force human-in-the-loop validation for performance improvement plan flagging. Frankfurt financial services clusters drive hybrid deployment adoption for sensitive client interaction records.
India
Bangalore and Hyderabad development centers serve cost-sensitive SMB segments through PLI scheme-enabled SaaS exports. CDSCO alignment pressures emerge where pharmaceutical field sales require immutable training audit trails. Mumbai enterprise headquarters increasingly mandate native Salesforce embedding over standalone application procurement.
United Kingdom
London fintech sales teams prioritize GDPR-aligned conversation intelligence with explicit consent management workflows. Financial Conduct Authority scrutiny of algorithmic decision-making elevates demand for auditable coaching platform selection. Manchester and Edinburgh emerging technology clusters favor ninety-day proof-of-concept structures mirroring US procurement patterns.
Japan
Tokyo enterprise sales organizations emphasize structured certification methodologies with longitudinal skill progression tracking. METI guidelines on workforce AI deployment influence vendor selection toward transparent model architectures. Osaka manufacturing sales teams drive demand for simulation software with culturally localized buyer persona libraries.
Sales Coaching Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Sales Coaching Software landscape. The vendor base concentrates around three strategic tiers: conversation intelligence specialists, unified enablement platforms, and AI-native challengers. Consolidation pressure intensifies as enterprise procurement teams demand full-stack solutions over point products. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and vertical integration into proprietary model training infrastructure.
Within the conversation intelligence tier, Gong and Nooks exemplify archetypes prioritizing real-time behavioral analytics over generic training content. Highspot occupies a position bridging content management and coaching analytics for unified enablement seekers. Among AI-native entrants, Zime.ai and Second Nature represent the simulation software specialization vector, anchoring emerging demand for role-play environments with synthetic buyer personas.
| Leading Market Players |
|---|
| Mindtickle |
| Allego |
| Spekit |
| Nooks |
| Zime.ai |
| Highspot |
| Salesloft |
| Second Nature |
| Gong |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with hyperscaler cloud providers anchor vendor pricing power by locking in GPU compute access at fixed rates while insulating margins from spot market volatility. These multi-year commitments simultaneously constrain supply flexibility, forcing vendors to forecast transcription demand accurately or face stranded capacity penalties.
Pricing Analysis
After-sales revenue from API access tiers and premium integration support drives lifetime value beyond base subscriptions. Pricing stratifies across enterprise, mid-market, and SMB tiers with differentiation anchored in conversation volume limits, compliance certification levels, and real-time latency guarantees. Cost compression in the mid-market tier is intensifying because India's PLI scheme enables offshore development centers to undercut domestic pricing. Enterprise buyers exhibit the least price sensitivity due to CFO-mandated quota attainment accountability, while SMBs prioritize out-of-box functionality over customization depth.
Supply Chain Analysis
Just-in-time provisioning of GPU compute resources dominates vendor infrastructure strategy, with strategic stockpiling limited to reserved capacity blocks negotiated during hyperscaler fiscal year-ends. Supply concentration centers on United States, Ireland, and Singapore for primary cloud regions, with conversation data processing drawing from NVIDIA GPU clusters, proprietary transcription models, and regional data residency infrastructure. Single-source vulnerability in NVIDIA's AI chip supply chain represents the dominant structural risk. Distribution runs through direct enterprise sales teams and cloud marketplace listings with revenue operations platform partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from API consumption and outcome-based coaching contracts expands faster than standalone seat licenses, repositioning vendor valuation toward recurring platform economics.
For Market Incumbents: Secure exclusive integration partnerships with Salesforce and HubSpot to lock out challenger embedding opportunities. Invest in proprietary model training infrastructure to differentiate from GPT-wrapper entrants facing EU AI Act algorithmic transparency scrutiny. Defensive consolidation through acquisition of simulation software specialists addresses the fastest-growing product segment while filling capability gaps in AI-generated buyer persona libraries. For New Entrants and Emerging Players: Differentiate on pharmaceutical field sales compliance by securing FDA-validated training record capabilities that incumbent generalists lack. Target India's cost-sensitive SMB segment through PLI scheme-enabled development economics. Pursue white-label deployment through regional system integrators serving Bundesdatenschutzgesetz-constrained German manufacturing accounts. For Investors and Strategic Acquirers: Capital is best deployed toward vendors with proprietary conversation datasets sufficient for dedicated model development rather than API-dependent architectures. Long-term viability favors platforms with hybrid deployment capabilities addressing tightening GDPR enforcement. Monitor EU AI Act enforcement patterns in Germany and France as the inflection indicator for compliance cost escalation across European enterprise accounts.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Development | Reduces dependency on OpenAI APIs while satisfying EU AI Act audit requirements. |
| Hybrid Deployment Architecture | Captures regulated industry demand in Switzerland and Saudi Arabia requiring voice data residency. |
| API-First Platform Integration | Embeds coaching workflows directly into Salesforce revenue operations stacks. |
| Outcome-Based Pricing Transition | Aligns vendor incentives with customer quota attainment metrics. |
| Pharmaceutical Compliance Certification | Unlocks FDA-validated training record requirements in medical device sales. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with revenue operations leaders, sales enablement directors, and pharmaceutical training compliance officers; and secondary validation through SEC SaaS company filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up triangulation against top-down market sizing anchored volume estimates.
Across the projection horizon, the analytical framework modeled deployment architecture, end-user scale, integration complexity, and regional regulatory cluster. CAGRs derived from historical adoption curves in conversation intelligence and projected AI Act compliance replacement cycles. Forecast inputs included GPU compute cost trajectories and pharmaceutical field sales digitization mandates.
The analysis sits within stated boundaries; outcomes outside sustained enterprise SaaS spend levels or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect assumptions about transcription accuracy improvement rates and hyperscaler pricing stability. Revision becomes warranted when cloud compute cost volatility crosses thresholds that compress vendor margins below sustainable levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gym Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Translation Software Market
Software & Services
Global Ipad POS Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Video Converter Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Channel Management Software Market
Software & Services
Global MSP Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Subscription Management Software Market