
 Global Stand Up Paddle (SUP) Boards Market | 2026-2036
Global Stand Up Paddle (SUP) Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stand Up Paddle (SUP) Boards Market Outlook
Board rental subscription services and software-connected paddle tracking features are hardening into core revenue streams alongside hardware sales. Red Paddle Co leverages its inflatable expertise to dominate the rental channel. Starboard anchors its position through R&D intensity in sustainable composite materials. Naish International specializes in high-performance racing and touring designs that command premium positioning.
Stand Up Paddle (SUP) Boards are buoyant watercraft typically measuring 2.7 to 4.3 meters in length, constructed from epoxy resin, PVC, carbon fiber, or wood laminates, designed for propulsion by a single-bladed paddle while standing. The inflatable product type leads volume through portability and storage advantages, while carbon fiber racing boards concentrate margin pools among professional users. Specialty stores sustain the highest per-unit economics, though online retail extends reach into inland markets where physical showrooms remain sparse.
EPA guidelines on marine coating emissions and REACH chemical restrictions in Europe constrain epoxy and PVC formulations, pushing manufacturers toward bio-based resins and recycled core materials. The EU's F-Gas Regulation and California's coastal water quality standards further tighten production compliance. Stakeholders must monitor how regulatory divergence between North American and European chemical standards reshapes supply chain sourcing decisions.
Market Dynamics
Material compliance costs from ECHA's REACH restrictions on epoxy resin formulations are compressing margin structures and forcing rapid supplier transitions toward bio-based alternatives across European manufacturing footprints.
Growth Catalysts
- Waterfront Tourism Infrastructure:Municipal investment in coastal access points and rental kiosks across Australia, France, and the United States expands addressable user bases for recreational paddlers.
- REACH Chemical Phase-Outs:Regulatory deadlines for PVC and epoxy resin restrictions accelerate R&D spending on sustainable composite materials that command premium positioning.
- Inflatable Board Technology:Drop-stitch construction advances improve rigidity-to-weight ratios, enabling storage-constrained urban consumers to participate without dedicated transport equipment.
Market Restraints
- Petrochemical Input Volatility:Epoxy resin and PVC feedstock prices fluctuate with crude oil benchmarks, compressing gross margins for manufacturers lacking long-term supply contracts.
- Asian Supply Concentration:Drop-stitch fabric and air valve subassembly production clusters in Chinese manufacturing zones, creating single-source vulnerability for Western brands.
- Hardboard Substitution Limits:Carbon fiber racing boards retain performance advantages in competitive applications that inflatable constructions cannot replicate at equivalent stiffness-to-weight ratios.
Strategic Opportunities
- Inland Waterway Expansion:Germany and Austria exhibit underpenetrated lake and river recreation markets where paddleboarding adoption lags coastal benchmarks by substantial margins.
- Subscription Rental Platforms:Software-enabled monthly membership models for equipment access reduce consumer capital barriers while generating recurring revenue streams.
- EU Green Deal Alignment:Bio-based resin certification and recycled core material sourcing qualify manufacturers for public procurement preferences and sustainability-linked financing.
Industry Challenges
- Composite Engineering Talent Scarcity:Specialized expertise in sustainable laminate formulation and drop-stitch structural optimization commands premium compensation in tight labor markets.
- Multi-Jurisdiction Certification Timelines:Separate EPA marine coating approvals, CE marking processes, and state-level watercraft registrations extend product launch cycles by 8-14 months.
- Supply Chain Reconfiguration Friction:Relocating epoxy resin sourcing from REACH-restricted European suppliers to compliant bio-based alternatives requires qualification testing and vendor revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stand Up Paddle (SUP) Boards Market |
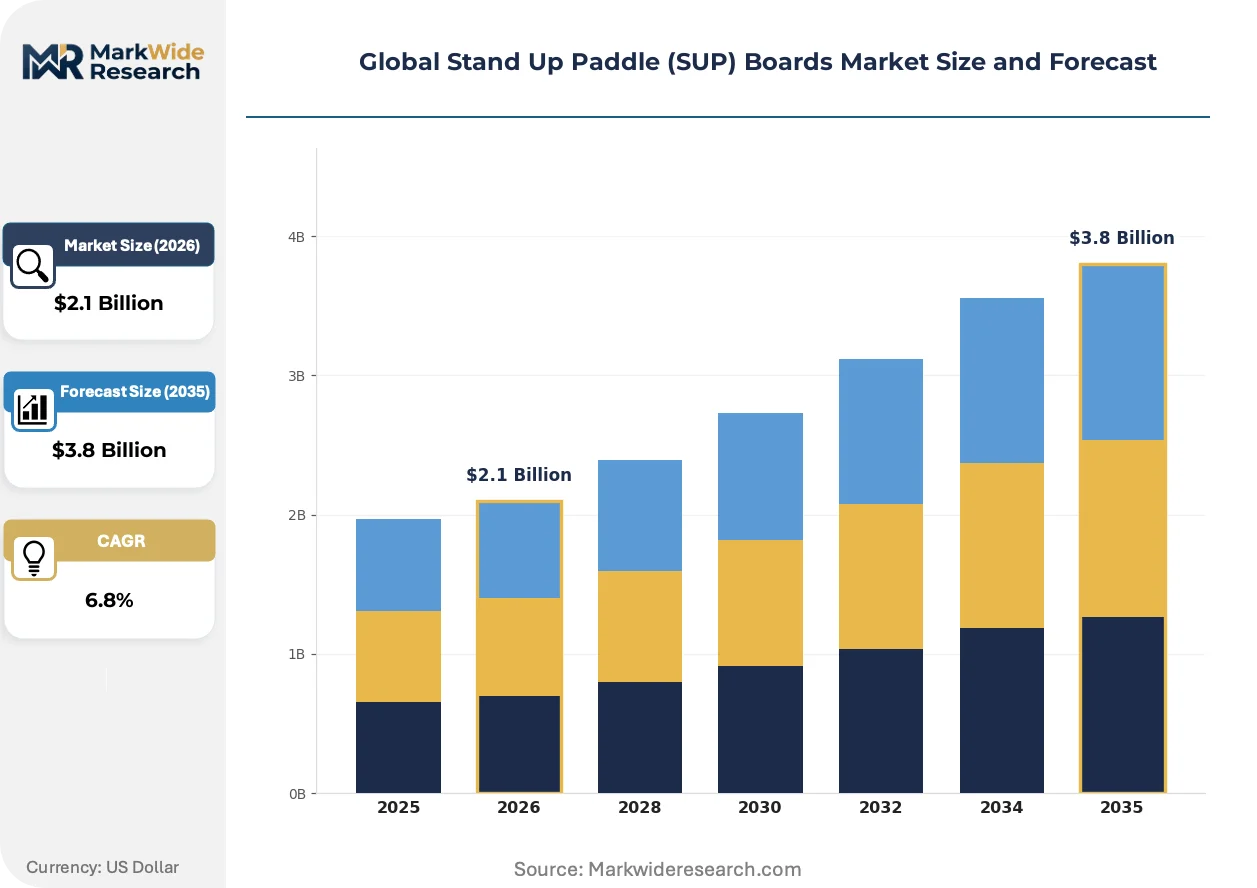
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allround, Touring, Racing, Inflatable Material: Epoxy, PVC, Carbon Fiber, Wood End User: Recreational Paddlers, Professionals, Fitness Enthusiasts, Rentals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Red Paddle Co, Starboard, Naish International, Tahe Outdoors, BOTE, SUP ATX, Boardworks Surf and Sup, Hobie Cat Company, Surftech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stand Up Paddle (SUP) Boards Market Strategic Shifts
Connected hardware integration and material sustainability are redefining product architecture and revenue architecture simultaneously across the SUP board value chain.
Modular fin systems and removable component architectures are modularizing board design standards. Touring and all-around segments adopt interchangeable fin boxes and detachable bungee rigging that enable single-platform configuration across flatwater, light surf, and downwind conditions. This architecture compresses SKU proliferation for manufacturers while expanding utility per unit for rental fleet operators seeking maximum deployment flexibility.
California's coastal water quality standards and the EPA's marine coating emission guidelines are tightening permissible VOC thresholds for hull finishes and deck grip applications. Manufacturers serving North American markets reformulate polyurethane and acrylic coatings to comply with state-level air quality management district rules. The racing and expedition segments absorb compliance costs most acutely given their reliance on high-performance surface treatments.
Direct-to-consumer digital channels are displacing specialty retail for entry-level inflatable purchases. Urban buyers without proximity to surf shops rely on video-guided assembly tutorials and virtual fitting tools to select board dimensions. This pattern concentrates most visibly in inland United States markets where waterfront recreation infrastructure exists but dedicated paddle sports retail remains sparse.
Global Stand Up Paddle (SUP) Boards Market Segmentation
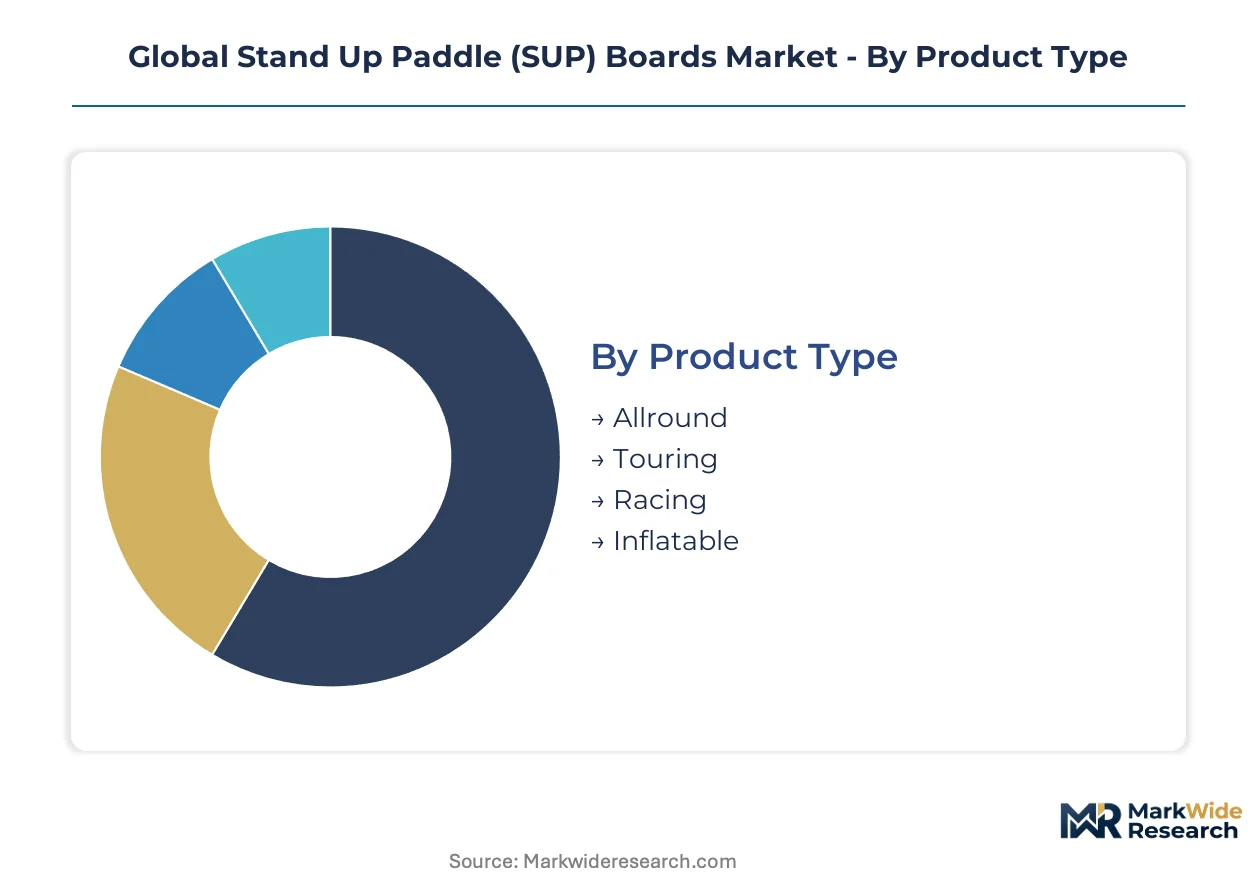
Segmentation in the SUP board market tracks divergent performance requirements across paddling disciplines, material compliance pressures under REACH and EPA frameworks, and channel economics that separate premium specialty retail from mass-market online fulfillment.
Product Type:
Drop-stitch construction advances and hydrodynamic design specialization differentiate performance envelopes across paddling disciplines.
- Inflatable:Drop-stitch PVC construction with reinforced rail taping delivers packable portability for urban consumers lacking vehicle transport. Demand concentrates in Germany and Austria's lake recreation markets where storage constraints dominate purchase decisions. REACH-compliant bio-resin alternatives are compressing margin structures for European manufacturers.
- Allround:Hybrid rocker profiles and moderate width dimensions accommodate flatwater stability and light surf maneuverability in single-platform designs. Rental fleet operators in France and Australia's coastal tourism zones favor this segment for maximum deployment flexibility across user skill levels.
- Touring:Displacement hull geometries and extended waterline lengths optimize glide efficiency for expedition paddling. Fitness enthusiasts in the United States' Great Lakes region drive adoption where distance paddling infrastructure exceeds surf access.
- Racing:Carbon fiber sandwich construction achieves stiffness-to-weight ratios that inflatable technologies cannot replicate at competitive performance thresholds. Professional circuits in Australia and France anchor demand despite concentrated production complexity and premium pricing tiers.
Mature deployment sits with Allround configurations. Newer deployment is concentrated in Inflatable constructions.
Material:
Regulatory phase-outs of conventional chemistries are forcing rapid qualification of bio-based alternatives across laminate supply chains.
- Epoxy:Thermoset resin systems dominate fiberglass and carbon fiber layup applications for rigid hull construction. ECHA's REACH restrictions on bisphenol-A derivatives are accelerating supplier transitions toward bio-epoxy formulations in European manufacturing footprints.
- PVC:Thermoplastic polymer forms the air-tight bladder and outer skin layers for inflatable drop-stitch assemblies. Chinese manufacturing zones concentrate drop-stitch fabric production, creating single-source vulnerability for Western brands dependent on air valve subassemblies.
- Carbon Fiber:Pre-preg composite layups deliver maximum stiffness-to-weight ratios for racing and expedition segments. California's coastal water quality standards and EPA marine coating guidelines tighten VOC thresholds for hull finishes applied to these high-performance platforms.
- Wood:Sustainable timber laminates and bamboo veneers serve aesthetic-driven recreational segments with lower performance requirements. EU Green Deal procurement preferences favor manufacturers sourcing FSC-certified core materials for public tender qualification.
Volume concentration favors PVC for inflatable portability. Margin concentration favors Carbon Fiber for technical performance applications.
End User:
Capital barriers and skill progression curves segment participation intensity across casual, committed, and professional paddling populations.
- Recreational Paddlers:Casual participants seeking flatwater stability and minimal learning curves dominate unit volume. Australia's municipal waterfront infrastructure investments and France's coastal access point expansions broaden addressable user bases in established tourism corridors.
- Rentals:Fleet operators prioritize durability, rapid inflation protocols, and interchangeable fin systems for maximum asset utilization. Software-enabled subscription platforms in the United States reduce consumer capital barriers while generating recurring revenue streams for equipment access providers.
- Fitness Enthusiasts:Core strength and balance training applications drive dedicated purchase behavior beyond casual trial. Inland United States markets with waterfront recreation infrastructure but sparse specialty retail rely on direct-to-consumer channels for board acquisition.
- Professionals:Competitive athletes and certified instructors demand specification-grade equipment with warranty terms supporting intensive use cycles. Racing circuits in Australia maintain performance standards that exclude inflatable constructions from sanctioned competition.
Established participation sits with Recreational Paddlers. Expanding most quickly are Fitness Enthusiasts converting from gym-based training modalities.
Distribution Channel:
Physical showroom requirements for inflatable assembly demonstration compete against digital convenience for entry-level purchase decisions.
- Specialty Stores:Surf shops and paddle sports retailers provide on-water demo programs and technical fitting consultation. Australia's coastal population clusters and France's surf culture regions sustain highest per-unit economics through premium positioning and accessory attachment.
- Online Retail:Video-guided assembly tutorials and virtual dimension selectors displace physical inspection for storage-constrained urban buyers. Inland United States markets with waterfront access but absent dedicated retail infrastructure concentrate this channel's expansion trajectory.
- Supermarkets:Mass-market retailers stock entry-level inflatable packages for seasonal impulse purchase occasions. Price-sensitive positioning limits product range to allround configurations with minimal accessory bundling.
- Others:Direct-to-consumer brand websites and rental fleet procurement channels capture residual volume outside conventional retail structures. Subscription membership models bypass traditional ownership economics entirely.
Margin protection sits with Specialty Stores. Channel expansion is climbing the fastest through Online Retail penetration of inland geographic whitespace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Chinese manufacturing zones for drop-stitch fabric and air valve assemblies, while consumption anchors in waterfront recreation corridors across the United States, Australia, and France where municipal infrastructure investments expand access points.
United States
Fitness enthusiasts in the Great Lakes region and coastal California drive demand for touring and allround configurations. EPA marine coating emission guidelines and California coastal water quality standards tighten VOC thresholds for hull finishes. Austin-based subscription rental platforms scale software-enabled membership models that reduce consumer capital barriers.
Australia
Municipal waterfront infrastructure investments across New South Wales and Queensland broaden recreational paddler participation in established surf culture regions. TGA-equivalent state-level watercraft registration requirements govern product compliance timelines. Sydney and Gold Coast clusters anchor racing circuit standards that exclude inflatable constructions from sanctioned competition.
France
Coastal tourism zones in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine sustain rental fleet operator demand for durable allround configurations. ECHA REACH restrictions on epoxy resin formulations accelerate manufacturer transitions toward bio-based alternatives. Biarritz and Hossegor surf clusters concentrate specialty retail infrastructure with premium per-unit economics.
Germany
Lake recreation markets in Bavaria and Baden-Württemberg exhibit underpenetrated adoption relative to coastal benchmarks, creating whitespace for inflatable board penetration. EU F-Gas Regulation and EU Green Deal procurement preferences favor manufacturers sourcing FSC-certified core materials. Munich and Stuttgart urban centers concentrate storage-constrained consumers prioritizing packable portability.
China
Drop-stitch fabric production clusters in Guangdong and Zhejiang provinces supply air valve subassemblies to Western brands with single-source dependency exposure. MEE environmental standards and dual carbon goals reshape petrochemical input sourcing for PVC formulations. Shenzhen and Ningbo manufacturing zones dominate global inflatable board component output.
Global Stand Up Paddle (SUP) Boards Market Competitive Environment
Top-tier vendors anchor premium positioning through sustainable material R&D and racing circuit certification, while mid-tier specialists compete on inflatable construction expertise and rental channel penetration. The vendor base stratifies across three archetypes: composite innovators pursuing bio-resin formulations, inflatable specialists leveraging drop-stitch scale, and lifestyle brands building direct-to-consumer digital infrastructure. Consolidation pressure intensifies as REACH compliance costs squeeze margin structures and force supplier requalification. Geographic expansion into underpenetrated lake markets and backward integration into core material sourcing represent dominant competitive vectors.
Specialists in inflatable construction and sustainable composite engineering occupy differentiated positions across the value chain. Red Paddle Co and Starboard exemplify archetype divergence—one anchoring rental channel scalability through drop-stitch expertise, the other representing R&D-intensive positioning in bio-based laminate development. Naish International occupies a position within the premium performance tier, its nomenclature signaling long-standing water sports lineage. These three entities collectively illustrate how technical specialization and channel focus separate sustainable margin pools from commoditized volume segments.
| Leading Market Players |
|---|
| Red Paddle Co |
| Starboard |
| Naish International |
| Tahe Outdoors |
| BOTE |
| SUP ATX |
| Boardworks Surf and Sup |
| Hobie Cat Company |
| Surftech |
| Others |
Value Chain & Pricing Dynamics
REACH-mandated epoxy resin phase-outs in Europe are forcing procurement teams to requalify bio-based laminate suppliers, compressing gross margins and triggering tiered pricing adjustments across carbon fiber and inflatable product lines. Manufacturers absorb compliance premiums or pass them downstream, widening spreads between REACH-certified and conventional material tiers.
Pricing Analysis
Margin tightening in inflatable boards reflects PVC feedstock volatility tied to crude oil benchmarks and Chinese manufacturing zone labor cost adjustments. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber racing platforms from drop-stitch recreational models and mass-market supermarket SKUs. Pricing pressure stems from REACH compliance premiums and EPA marine coating reformulation costs. Rental fleet operators exhibit highest price sensitivity due to volume procurement and asset utilization metrics, while professional racers absorb premium tiers for stiffness-to-weight performance.
Supply Chain Analysis
Refurbishment flows for rental fleet operators and warranty return programs are creating secondary material recovery channels that reshape upstream resin procurement. Manufacturing concentrates in China for drop-stitch fabric and air valve subassemblies, with epoxy resin formulation anchored in Germany and carbon fiber pre-preg sourcing centered in Japan. Supply chains draw from petrochemical feedstocks, FSC-certified timber laminates, and bio-based resin alternatives. Single-source vulnerability in Guangdong and Zhejiang manufacturing zones poses structural risk. Distribution runs through specialty surf shops in Australia and France, online retail for inland United States markets, and direct-to-consumer brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SUP board market is becoming a vertical-integration race as manufacturers pursue captive supply of REACH-compliant bio-resins and backward control over drop-stitch fabric production to defend margin structures.
For Market Incumbents: To counter REACH compliance cost compression and Asian supply concentration, secure long-term offtake agreements with bio-epoxy formulators in European manufacturing footprints and acquire minority stakes in Guangdong drop-stitch fabric producers to de-risk valve subassembly sourcing. For New Entrants and Emerging Players: Begin with Germany and Austria's underpenetrated lake recreation markets where storage-constrained urban consumers prioritize inflatable portability over coastal surf culture infrastructure. Target fitness enthusiast segments converting from gym-based training through direct-to-consumer digital channels with video-guided assembly support. For Investors and Strategic Acquirers: The window for entry favors specialists in sustainable composite engineering with demonstrated bio-resin certification and FSC-certified core material sourcing. Monitor ECHA regulatory expansion timelines and EU Green Deal procurement preference rollouts as inflection indicators for premium positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Resin Sourcing | REACH compliance premiums favor manufacturers with captive bio-epoxy supply chains in European footprints. |
| Drop-Stitch Fabric Production Acquisition | Control over Guangdong and Zhejiang manufacturing zones reduces single-source vulnerability for Western brands. |
| Subscription Rental Platform Launch | Software-enabled membership models in the United States reduce consumer capital barriers and generate recurring revenue. |
| FSC-Certified Core Material Sourcing | EU Green Deal procurement preferences qualify manufacturers for public tender access and sustainability-linked financing. |
| Racing Circuit Certification Investment | Australia's sanctioned competition standards exclude inflatable constructions, anchoring premium carbon fiber demand. |
Study Parameters
Document review covered customs and trade data, ECHA REACH regulatory filings, EPA marine coating guidelines, and industry association reports, complemented by interviews with brand product development directors, rental fleet procurement managers, composite engineering specialists, and specialty retail buyers. Primary fieldwork across the United States, Australia, France, and Germany validated secondary estimates through bottom-up unit demand modeling and top-down market sizing triangulation.
Cross-referencing historical shipment data against expert panel inputs anchored volume projections across the analysis window. Segmentation modeling tracked product type, material compliance tier, end-user participation intensity, and distribution channel economics. CAGRs were derived from regression analysis of waterfront infrastructure investment cycles, regulatory phase-out timelines, and adoption curve penetration in inland versus coastal markets.
REACH enforcement acceleration, crude oil benchmark volatility, and Chinese environmental standard tightening are the dominant revision risks to material cost assumptions and supply availability. Forecasts reflect documented assumptions about regulatory implementation schedules and feedstock price stability. Practitioners should monitor ECHA substance restriction proposals, MEE dual carbon policy enforcement, and municipal infrastructure appropriations for early signals of demand and cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Skating Shoes Market
Sports Equipment
Running Gear Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Kneeboard Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Padel Balls Market
Sports Equipment
Surfing Equipment Market