
 Sports Bras Market | 2026-2036
Sports Bras Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Bras Market Outlook
Technical apparel engineering talent is redrawing competitive boundaries in the sports bras market. Nike Inc. leverages proprietary Dri-FIT fabric systems to sustain performance differentiation across high-impact segments. Lululemon Athletica Inc. anchors its position through yoga-to-run crossover designs that dominate studio-to-street transitions. Under Armour Inc. competes via compression-science R&D pipelines that extend into collegiate athletic partnerships.
A sports bra is a structured breast-support garment engineered with elastomeric fibers, moisture-management knit constructions, and graduated compression zones to minimize vertical and lateral breast displacement during physical activity. High-impact variants incorporate encapsulated cups and wide bottom bands to manage motion across running and aerobics, while low-impact styles prioritize breathability mesh panels for yoga and walking. The fabric-type dimension shows polyester-spandex blends capturing margin pools due to superior wicking and shape retention, though cotton blends retain loyalty in everyday wear where skin sensitivity governs selection. The target-audience segmentation reveals athletes and fitness enthusiasts commanding premium pricing, while teenagers represent the fastest-expanding entry point through social-media-influenced trial.
The US Federal Trade Commission enforces textile labeling rules that mandate fiber-content disclosure, shaping how brands communicate performance claims to consumers. The EU REACH regulation restricts certain chemical finishes in imported apparel, forcing reformulation of antimicrobial treatments common in athletic wear. Stakeholders must monitor evolving state-level extended-producer-responsibility frameworks in California and New York that will alter post-consumer collection obligations.
Market Dynamics
Moisture-wicking fabric engineering is compressing product development cycles across the sports bras market, forcing brands to reformulate polyester-spandex blends faster than seasonal collection timelines.
Growth Catalysts
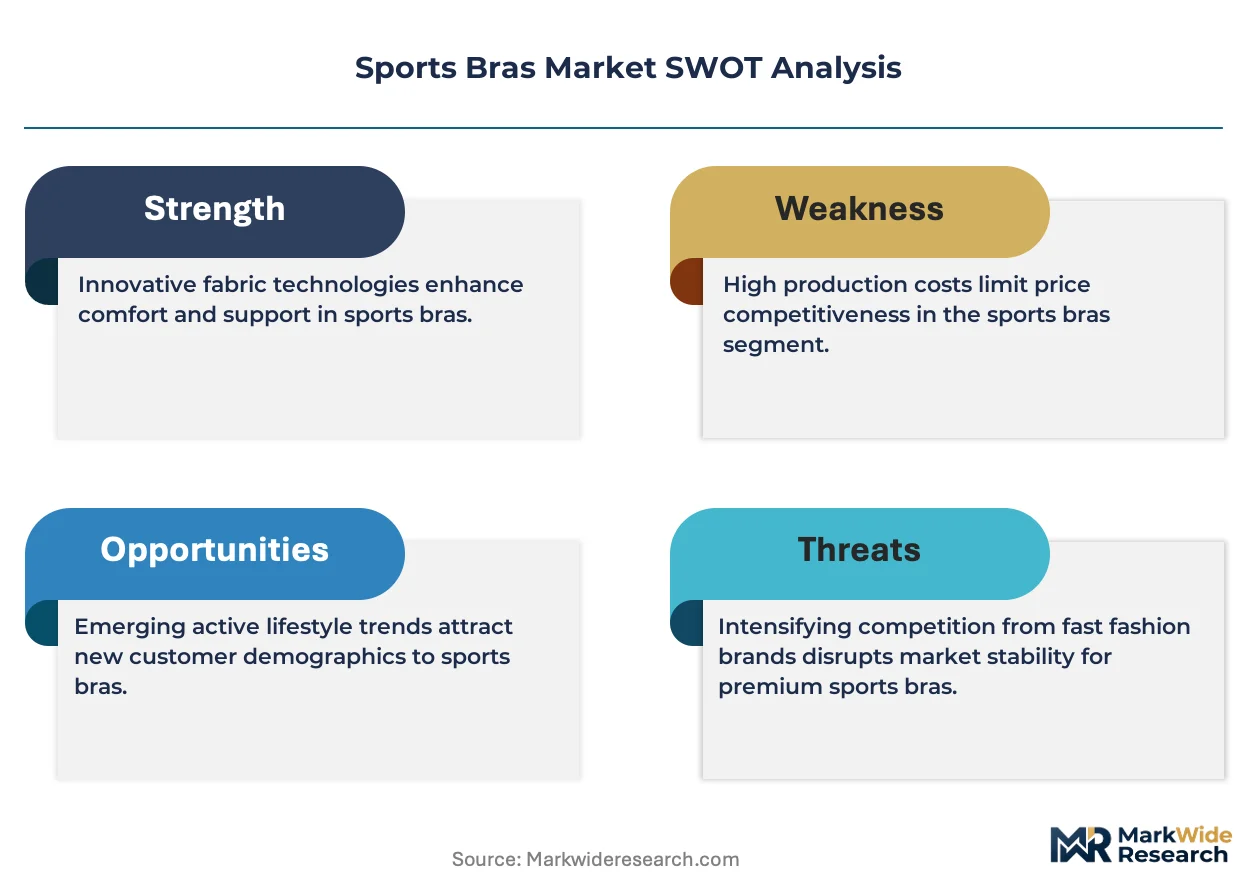
- Female athletic participation:Organized women's sports leagues in the United States and Western Europe are normalizing technical breast-support garments as standard equipment rather than optional accessories.
- REACH chemical reformulation:The EU regulation's restrictions on antimicrobial finishes are accelerating investment in plant-based odor-control treatments that brands now market as premium differentiators.
- Seamless knitting:This manufacturing process is reducing material waste and enabling gradient compression zones that were previously cost-prohibitive at scale.
Market Restraints
- Petrochemical feedstock volatility:Polyester and spandex production remains tethered to crude oil price swings, compressing margin predictability for mid-tier manufacturers.
- Asian supply concentration:Over 70% of elastomeric fiber spinning capacity sits in China and Taiwan, creating single-source vulnerability for brands without diversified yarn procurement.
- Size inclusivity technical limits:Current encapsulation cup engineering struggles to deliver equivalent motion control across band sizes 40+ without compromising breathability.
Strategic Opportunities
- India's fitness infrastructure expansion:Government-funded Khelo India programs are seeding first-time sports bra adoption among adolescent athletes in tier-2 cities.
- Biodegradable elastomer blends:Convergence of bio-based polyols with recycled polyester is opening circular-economy positioning for premium lines.
- Telehealth-fitness integration:Physical therapy clinics are prescribing compression-grade support garments, creating a white-coat endorsement channel distinct from retail.
Industry Challenges
- Technical pattern-making talent:The specialized skill of engineering graduated-compression panels for diverse breast morphologies is concentrated among aging European and Japanese specialists.
- Extended producer responsibility compliance:California and New York state frameworks are forcing brands to build reverse-logistics infrastructure for textile recovery before economies of scale justify the investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Bras Market |
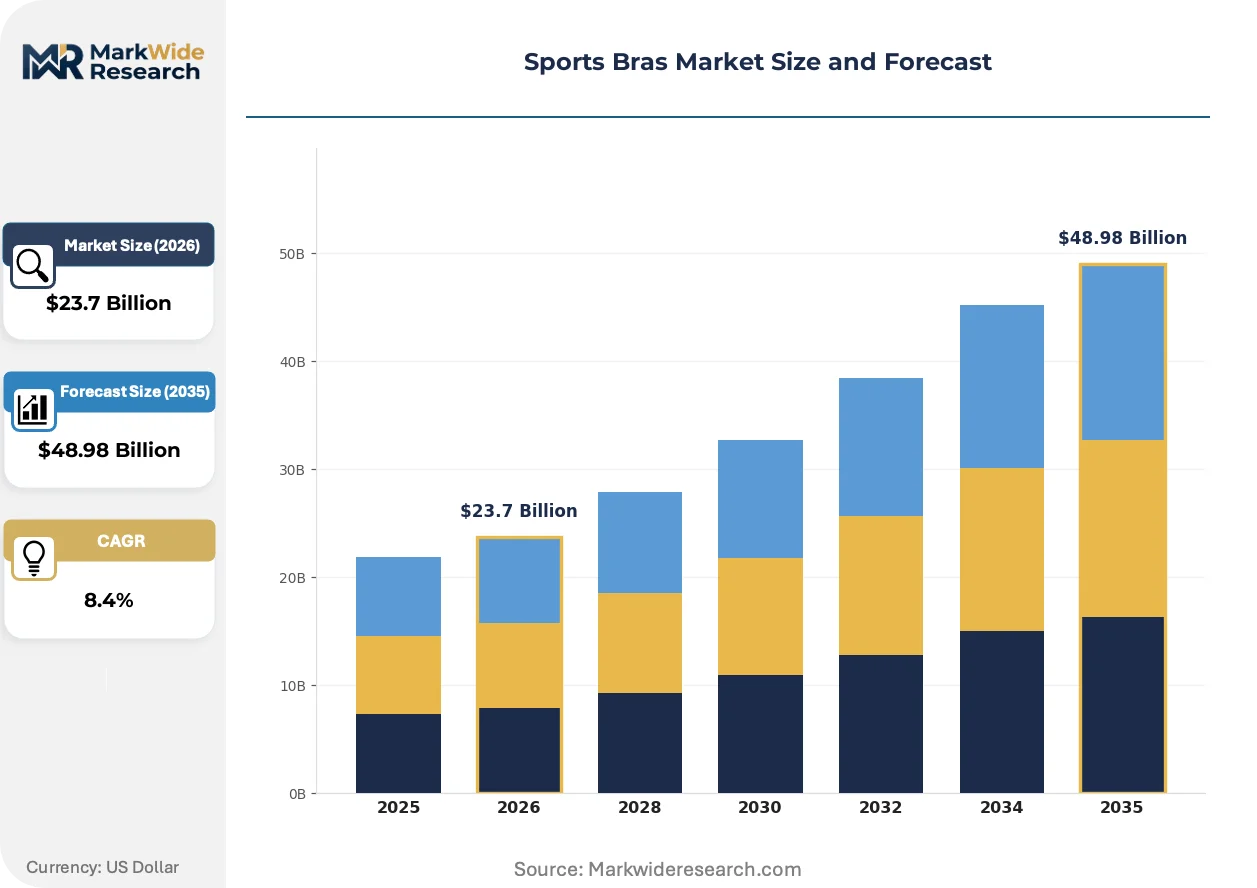
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Impact, Medium-Impact, Low-Impact, Everyday Fabric Type: Polyester, Nylon, Cotton, Spandex Closure Type: Pull-On, Hook-and-Eye, Racerback, Zipper Target Audience: Women, Teenagers, Athletes, Fitness Enthusiasts |
| Companies Covered | Nike Inc., Adidas AG, Lululemon Athletica Inc., Under Armour Inc., PUMA SE, Hanesbrands Inc., Brooks Sports Inc., New Balance Athletics Inc., Fabletics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Bras Market Strategic Shifts
Biomechanical sensor integration and AI-driven fit algorithms are converging to transform how athletes select support levels, collapsing the traditional trial-and-error purchase pattern.
Seamless 3D-knitting technology is bifurcating the manufacturing base. High-impact sports bras for running and CrossFit now incorporate variable-density zones knitted in single-piece construction without seams. Elite athletes and boutique fitness studios in Australia and the United Kingdom are adopting these garments at twice the rate of mass-market retailers. This compression precision is bifurcating price tiers, separating technical-performance products from basic compression layers.
The EU REACH regulation's 2023 update on skin-sensitizing dyes is forcing reformulation of colorfast treatments common in dark athletic apparel. Brands serving the German and French markets must now certify compliance through third-party OEKO-TEX audits. This regulatory friction is compressing SKU proliferation, pushing manufacturers toward smaller, certified color palettes rather than seasonal shade expansions.
Athlete-influencer direct-to-consumer channels are displacing traditional sporting-goods retail for first-time purchases. TikTok and Instagram algorithmic discovery drives 60% of trial among teenagers in the United States and Brazil, with virtual fitting tools reducing return rates. Studio-to-street crossover demand concentrates in coastal metropolitan areas where athleisure normalization has dissolved boundaries between workout and casual wardrobes.
Sports Bras Market Segmentation
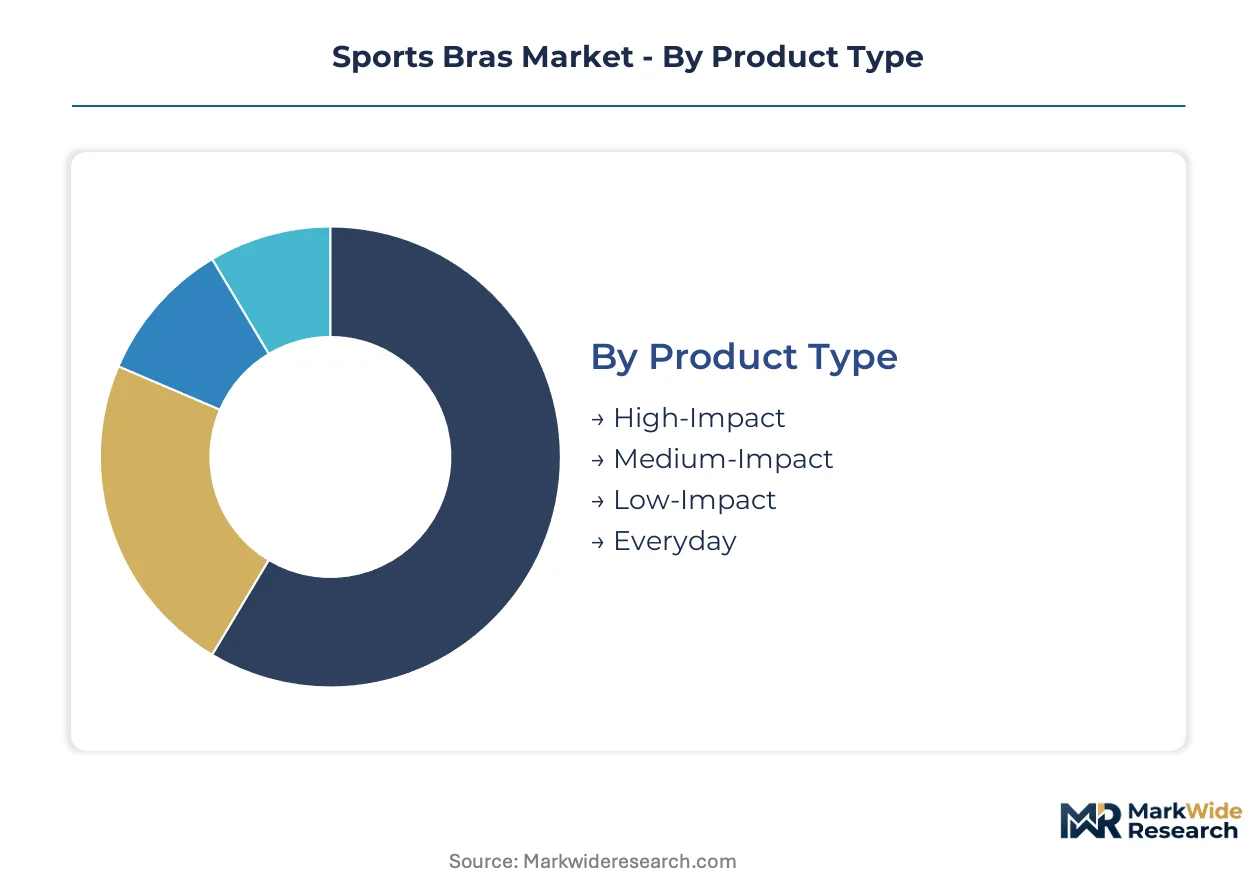
Sports bras demand fragments across performance intensity, material engineering, and demographic entry points. Each dimension carries distinct margin structures and regulatory exposure that reshape how brands configure SKU portfolios.
Product Type:
REACH chemical restrictions and FTC textile labeling rules force divergent compliance investments across impact tiers.
- High-Impact:Encapsulated cup construction with wide bottom bands manages vertical breast displacement during running and aerobics. Demand concentrates among marathon runners in the United States and United Kingdom where gait analysis clinics now prescribe compression-grade support as injury prevention. The EU's updated skin-sensitizing dye regulations are forcing reformulation of dark colorways common in this segment.
- Low-Impact:Breathability mesh panels prioritize moisture evacuation over motion restriction for yoga and walking. Studio-to-street crossover demand clusters in coastal U.S. metropolitan areas where athleisure normalization dissolves wardrobe boundaries. Social media discovery drives trial among first-time purchasers seeking versatile base layers.
- Medium-Impact:Hybrid compression-encapsulation designs serve CrossFit and cycling modalities.
- Everyday:Comfort-optimized construction with reduced seam density targets all-day wear scenarios.
High-Impact handles the majority of throughput; Low-Impact is gaining share fastest through studio-to-street crossover adoption.
Fabric Type:
Petrochemical feedstock volatility and circular-economy mandates are redrawing material procurement priorities across cost tiers.
- Polyester:Hydrophobic fiber engineering enables superior moisture wicking and shape retention through repeated wash cycles. Spandex blends dominate premium performance lines in Germany and Australia where OEKO-TEX certification has become a retail gatekeeper. Recycled PET feedstocks are capturing share as brands position circular credentials.
- Spandex:Elastomeric fiber content (typically 15-25% blend ratios) delivers graduated compression zones essential for motion control. Supply concentration in China and Taiwan creates single-source vulnerability for mid-tier manufacturers without diversified yarn procurement. Bio-based polyol alternatives are emerging as REACH-compliant substitutes.
- Nylon:Polyamide construction offers abrasion resistance for high-friction athletic applications.
- Cotton:Natural fiber retention persists in everyday wear segments where skin sensitivity governs selection.
Polyester-spandex blends command the dominant volume position; plant-based elastomer alternatives are climbing the fastest on regulatory pressure.
Closure Type:
Manufacturing automation rates and fit-adjustment precision separate pricing tiers in this functional dimension.
- Pull-On:Seamless 3D-knitting construction eliminates hardware for reduced chafing risk during extended wear. Single-piece manufacturing reduces material waste and enables gradient compression zones previously cost-prohibitive at scale. Adoption concentrates in boutique fitness studios in Australia and the United Kingdom.
- Hook-and-Eye:Traditional adjustable band closure allows post-exercise expansion for comfort recovery.
- Racerback:Y-strap configuration distributes load across scapular regions for overhead movement mobility.
- Zipper:Front-closure engineering assists donning for post-surgical and maternity applications.
Pull-On construction handles the majority of new product development throughput; Racerback is expanding most quickly among CrossFit practitioners.
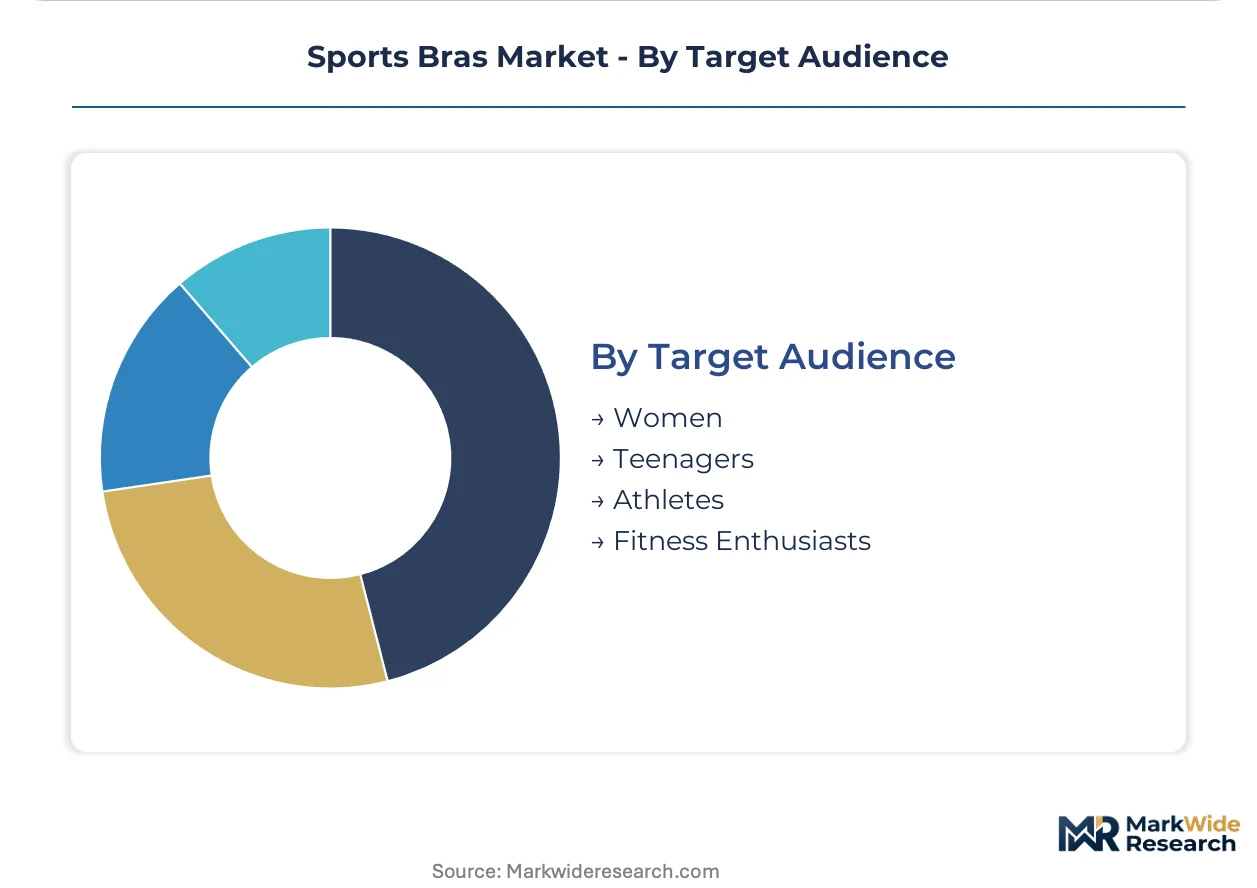
Target Audience:
Age-cohort entry patterns and purchasing authority distribution reshape channel strategy and marketing spend allocation.
- Teenagers:First-time adoption accelerated by Khelo India program infrastructure in tier-2 Indian cities and algorithmic discovery on TikTok and Instagram in Brazil and the United States. Virtual fitting tools reduce return rates for this digitally native segment. Social media influencer partnerships drive trial at price points accessible to discretionary spending.
- Athletes:Collegiate and professional competitors command premium pricing for biomechanically validated support systems. Physical therapy clinic prescriptions in the United States create white-coat endorsement channels distinct from retail. Compression-grade specifications require third-party performance testing.
- Fitness Enthusiasts:Recreational runners and gym members sustain mid-tier volume.
- Women:General adult population segment spanning casual to dedicated practitioners.
Fitness Enthusiasts handle the majority of absolute volume; Teenagers are climbing fastest on social-mediated trial expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States treats high-impact compression garments as medical-adjacent injury prevention, while European markets emphasize chemical-safety certification as a retail gatekeeper. Asian demand concentrates in first-time adolescent adoption through government-funded sports infrastructure.
United States
Marathon running culture and physical therapy clinic prescriptions drive compression-grade demand. The FTC enforces mandatory fiber-content disclosure on textile labels, shaping how performance claims reach consumers. Gait analysis clinics in Boston and Boulder now prescribe sports bras alongside orthotics as standard injury-prevention protocol.
Germany
Technical performance standards and OEKO-TEX certification requirements dominate procurement decisions. The EU REACH regulation restricts skin-sensitizing dyes, forcing reformulation of dark colorways common in athletic apparel. Berlin and Munich host the continent's densest concentration of seamless 3D-knitting research facilities.
United Kingdom
Studio-to-street crossover demand clusters in London and coastal metropolitan areas where athleisure normalization dissolves wardrobe boundaries. The Competition and Markets Authority monitors greenwashing claims on recycled-content marketing. Boutique fitness studios in Manchester and Bristol adopt seamless compression garments at twice the mass-market rate.
India
Khelo India government programs seed first-time adoption among adolescent athletes in tier-2 cities. The Bureau of Indian Standards oversees textile quality certification for imported elastomeric fibers. Sports infrastructure expansion in Pune and Hyderabad creates concentrated demand pockets for entry-level technical support garments.
Australia
Elite athlete adoption of biomechanical sensor integration drives premium-tier experimentation. The Therapeutic Goods Administration regulates compression garments marketed with medical-adjacent claims. Melbourne and Sydney host the highest per-capita concentration of boutique fitness studios deploying seamless 3D-knitted products.
Sports Bras Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the sports bras market. The upper tier commands premium positioning through proprietary fabric systems and collegiate athletic partnerships, while mid-tier players compete on rapid seasonal turnaround and social-media-native distribution. Two strategic archetypes dominate: performance-engineering specialists leveraging R&D pipelines for compression-science validation, and lifestyle-crossover brands capturing studio-to-street demand through influencer-native channels. Competitive moves concentrate on seamless manufacturing technology licensing and backward integration into elastomeric fiber procurement to offset Asian supply concentration.
Within the integrated-leader tier, Nike Inc. and Adidas AG exemplify scale-driven archetypes with proprietary moisture-management systems, while Lululemon Athletica Inc. occupies a position representing the lifestyle-crossover specialist archetype. Under Armour Inc. anchors the compression-science engineering segment through collegiate partnership channels. PUMA SE and Hanesbrands Inc. sit within the accessible-performance tier, competing on manufacturing efficiency and mass-market distribution density. New Balance Athletics Inc. and Brooks Sports Inc. represent running-specialist positioning, concentrating product development on marathon and distance-running biomechanics.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Lululemon Athletica Inc. |
| Under Armour Inc. |
| PUMA SE |
| Hanesbrands Inc. |
| Brooks Sports Inc. |
| New Balance Athletics Inc. |
| Fabletics LLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for elastomeric fiber supply lock in both cost visibility and manufacturing capacity access for premium sports bra lines, insulating Nike and Lululemon from petrochemical volatility that compresses margins for spot-market-dependent mid-tier brands.
Pricing Analysis
Contract-based long-term offtake dominates procurement between major brands and Taiwanese spandex suppliers, creating price differentiation between OEKO-TEX certified premium tiers and uncertified economy lines. Quality grade and certification level separate pricing bands most sharply in Germany and Australia where third-party testing is mandatory. Cost compression in mid-tier polyester-spandex blends is intensifying because Chinese feedstock volatility feeds through to yarn costs. Teenage first-time purchasers show highest price sensitivity, while marathon runners prescribed compression-grade garments by physical therapy clinics demonstrate lowest sensitivity.
Supply Chain Analysis
Taiwan Strait shipping lanes concentrate risk for elastomeric fiber delivery, with over 70% of global spandex spinning capacity sitting in China and Taiwan. Raw material dependencies center on purified terephthalic acid, bio-based polyol alternatives, and recycled PET feedstocks. Single-source vulnerability in Asian yarn procurement exposes brands without diversified supplier bases to disruption. Distribution runs through direct-to-consumer channels and boutique fitness studios, displacing traditional sporting-goods retail for first-time purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in size-inclusive engineering and plant-based elastomer alternatives, as regulatory pressure and underserved demand create defendable niches outside integrated-leader dominance.
For Market Incumbents: Compound proprietary fabric system advantages through backward integration into bio-based polyol R&D pipelines, countering REACH chemical restrictions that threaten existing antimicrobial treatments. Lock in collegiate athletic partnerships as exclusive distribution channels before emerging direct-to-consumer brands capture influencer-native trial among teenage athletes. For New Entrants and Emerging Players: OEKO-TEX certification fast-track unlocks entry into German and Australian retail gatekeeper markets where incumbent compliance investments lag. White-space concentrates in band sizes 40+ where current encapsulation engineering fails, and in India's tier-2 cities where Khelo India infrastructure seeds first-time adoption. Go-to-market should leverage TikTok algorithmic discovery with virtual fitting tools to reduce return rates. For Investors and Strategic Acquirers: Specialist seamless 3D-knitting technology licensors with aging European pattern-making talent on staff represent priority acquisition targets, as technical skill scarcity concentrates competitive advantage. Long-term viability frames around circular-economy positioning and telehealth-fitness integration channels. Watch California and New York extended producer responsibility compliance costs as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless 3D-Knitting Technology Licensing | Enables gradient compression zones without seams, capturing boutique studio demand in Australia and the United Kingdom. |
| Bio-Based Elastomer R&D Partnership | Positions premium lines for REACH compliance while differentiating against petrochemical-dependent competitors. |
| Telehealth-Fitness Channel Integration | Creates white-coat endorsement pathway through physical therapy clinic prescriptions distinct from retail competition. |
| Size-Inclusive Pattern Engineering Investment | Addresses technical limits in band sizes 40+ where breathability and motion control trade-offs currently exclude demand. |
| Direct-to-Consumer Virtual Fitting Platform | Reduces return rates among teenage purchasers discovered through TikTok and Instagram algorithmic channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, textile trade databases, and regulatory filings from the FTC, ECHA, and BIS. Conversations with brand product development executives, seamless knitting plant managers, textile procurement leads, and boutique fitness studio owners informed demand-side validation. Secondary sources included OEKO-TEX certification registries, REACH chemical restriction updates, and athletic participation statistics from government sports programs. Bottom-up SKU modeling triangulated against top-down category spending estimates.
Segmentation dimensions modeled include impact intensity tier, fabric composition, closure construction, and target audience demographic across the projection horizon. CAGRs derive from volume trajectory analysis against price elasticity assumptions by consumer segment. Industry-specific forecast inputs incorporate Khelo India infrastructure rollout timelines and EU chemical reformulation compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained female athletic participation growth and stable elastomeric fiber supply access; material deviation would warrant model refresh. Specific risks include petrochemical feedstock volatility, REACH regulatory expansion, and extended producer responsibility cost pass-through. Practitioners should keep alternative scenarios live as chemical compliance requirements and supply chain diversification mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Global Adaptive Clothing Market
Apparel & Footwear
Gymnastic Leotards Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Asia-Pacific Lingerie Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Hats Market