
 US Fanny Packs Market | 2026-2036
US Fanny Packs Market Size, Share, and Industry Trends Forecast 2026-2036
US Fanny Packs Market Analytics
California's SB 707 textile recycling mandate is restructuring material sourcing priorities for domestic fanny pack producers. Bearse Manufacturing Co. leverages its Midwest production footprint to sustain contract manufacturing relationships with major outdoor labels. Sasco, Inc. anchors its position through specialized military and tactical waist pack fabrication. Flowfold differentiates via ultralight composite materials derived from recycled sailcloth and racing fabrics.
A fanny pack constitutes a waist-worn carrying device typically constructed from woven synthetic textiles or tanned hides, featuring a primary zippered compartment with dimensions ranging from 0.5 to 5 liters internal volume, designed for hands-free transport of personal effects during locomotion or recreational activity. Classic Fanny Packs dominate unit volume through heritage outdoor retail placement, while Mini Fanny Packs capture expanding fashion-oriented demand among urban consumers seeking reduced-carry alternatives. Belt Bags sustain premium positioning through leather construction and artisanal stitching protocols that command higher per-unit margins in specialty store channels.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1610 for textile waist-worn products, while California's Proposition 65 mandates disclosure of chemical constituents in synthetic materials contacting skin. The Federal Trade Commission's Green Guides constrain environmental marketing claims regarding recycled content percentages and biodegradability assertions. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that will reshape material certification requirements and supplier qualification protocols.
Market Dynamics
California's SB 707 textile recycling mandate is forcing domestic fanny pack producers to restructure material sourcing priorities, accelerating the shift from virgin petroleum-based synthetics toward certified recycled nylon and polyester inputs.
Growth Catalysts
- SB 707 Compliance Deadlines:California's phased textile recycling mandates are pulling recycled nylon and polyester into mainstream supply chains ahead of other states.
- Athletic End-Use Expansion:Runners, cyclists, and trail athletes are driving functional waist-worn storage adoption as hands-free mobility becomes non-negotiable.
- Pacific Northwest Manufacturing Clusters:Portland and Seattle anchor artisanal production networks that shorten lead times for direct-to-consumer brands.
Market Restraints
- Recycled Input Cost Volatility:Post-consumer nylon flake pricing fluctuates with collection infrastructure gaps, compressing margin buffers for mid-tier producers.
- Single-Region Concentration Risk:California regulatory stringency diverges sharply from Texas and Florida enforcement patterns, fragmenting compliance economics.
- Performance Limitations:Recycled polyester tensile strength degrades across mechanical reprocessing cycles, restricting load-bearing applications in tactical segments.
Strategic Opportunities
- Mountain West Outdoor Retail Expansion:Colorado and Utah specialty retailers remain underpenetrated relative to coastal markets, offering whitespace for regional brand building.
- Modular Attachment Systems:MOLLE-compatible waist packs are converging with technical apparel, opening adjacent revenue in hunting and emergency responder verticals.
- State EPR Framework Pre-Positioning:Early alignment with emerging extended producer responsibility schemes in Oregon and Washington secures supplier qualification advantages.
Industry Challenges
- Certification Timeline Compression:Global Recycled Standard and OEKO-TEX audits require 8-14 month lead times, misaligning with seasonal product development cycles.
- Technical Talent Scarcity:Domestic expertise in thermoformed composite panel bonding remains concentrated in aerospace suppliers, limiting ultralight construction scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fanny Packs Market |
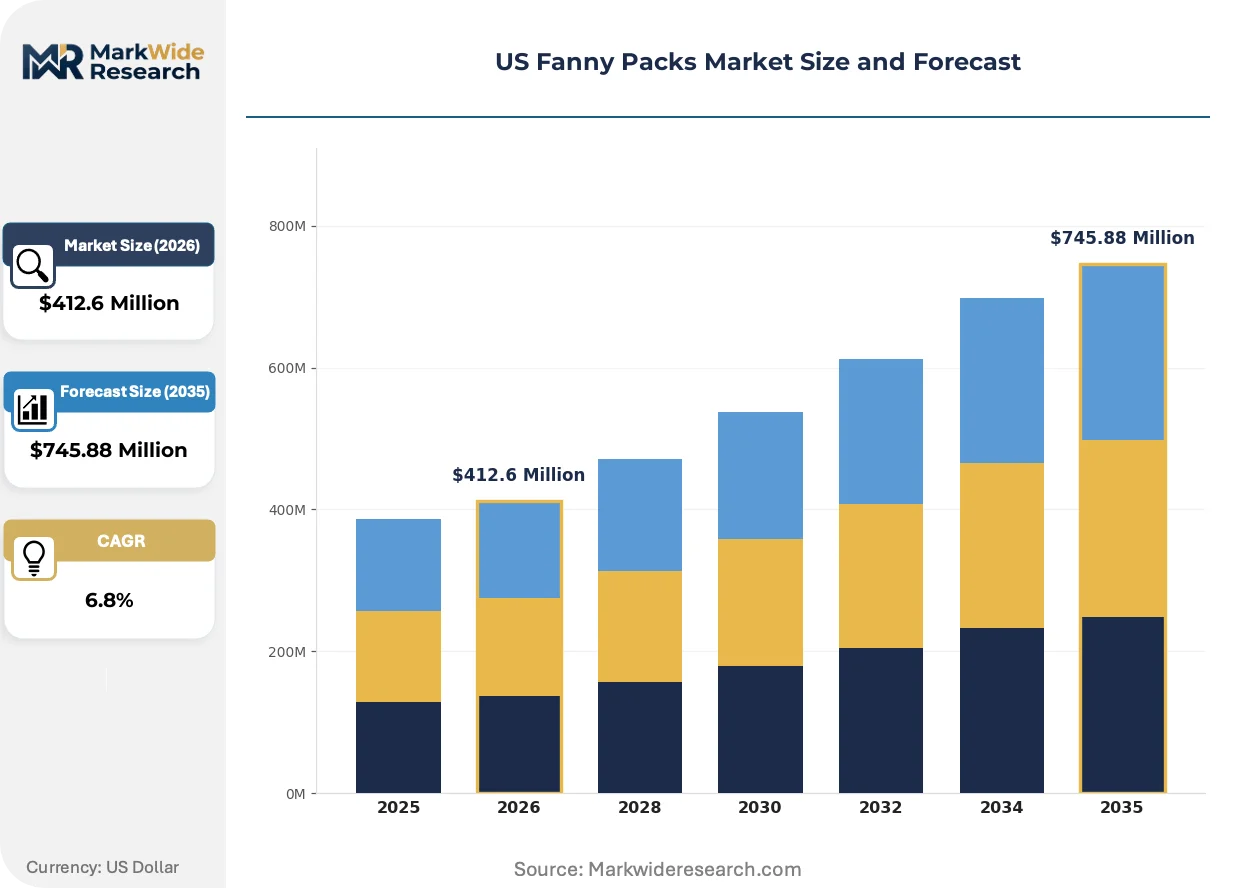
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Fanny Packs, Mini Fanny Packs, Belt Bags, Hydration Packs Material: Nylon, Polyester, Leather, Canvas End User: Adults, Children, Athletes, Travelers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Outlets |
| Companies Covered | Bearse Manufacturing Co., Sasco, Inc., LBU, Inc., Tough Traveler, Flowfold, Fieldtex Products, Inc., Landes Inc., Rickshaw Bagworks, AdCapitol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fanny Packs Market Evolving Landscape
Material science convergence and regulatory pressure are restructuring how fanny pack producers design, source, and certify products for an increasingly segmented buyer base.
Laser-cut composite laminates derived from recycled sailcloth and racing fabrics are unifying durability and weight reduction in a single material stack. Ultralight outdoor enthusiasts are adopting these constructions at accelerating rates, compressing the performance gap between heritage nylon weaves and technical composites.
The Federal Trade Commission's Green Guides are tightening enforcement against unsubstantiated recycled content claims. Producers must now maintain chain-of-custody documentation from polymer reclamation through finished goods, elevating compliance costs most acutely for brands lacking captive recycling partnerships.
Direct-to-consumer channel migration is fragmenting traditional wholesale relationships. Specialty outdoor retailers in the Pacific Northwest are losing volume share to brand-owned e-commerce and subscription-based gear services, with this shift most visible among urban millennials seeking customization options unavailable through brick-and-mortar assortments.
US Fanny Packs Market Segmentation
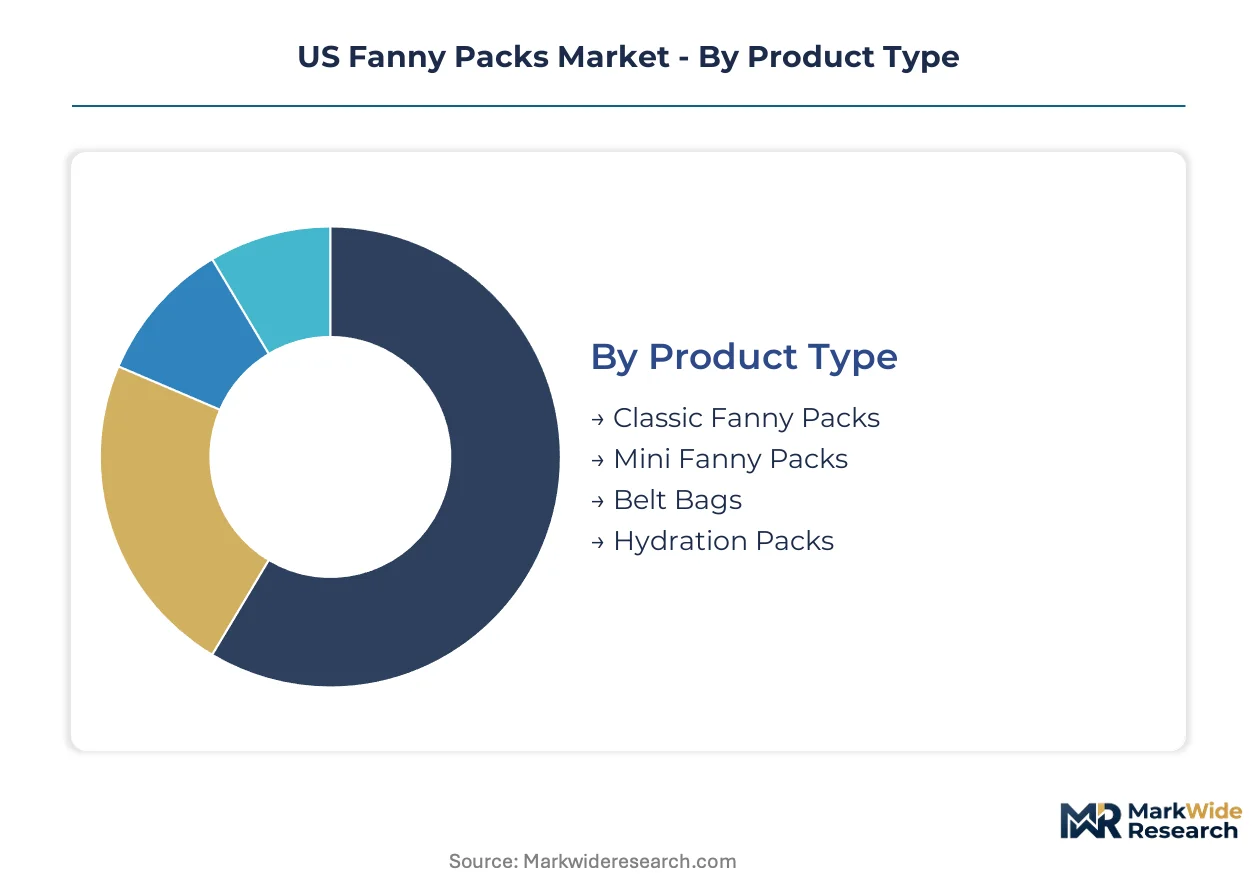
US fanny pack producers face divergent technical requirements across buyer cohorts, from the flammability compliance demands of children's products to the load-bearing specifications of athletic waist-worn storage. Segmentation clarity determines which material certifications and channel investments yield margin protection.
Product Type:
Buyer priorities split between heritage functionality and fashion-forward minimalism, with volume concentration in established outdoor retail placement versus DTC acceleration in reduced-carry formats.
- Classic Fanny Packs:Constructed from woven nylon or polyester with 1-5 liter capacity and multiple zippered compartments. Demand concentrates in Pacific Northwest specialty retailers serving hikers and casual outdoor users, with heritage brand placement sustaining baseline volume despite DTC erosion.
- Mini Fanny Packs:Compact constructions under 1 liter targeting urban fashion consumers. Expansion tilts toward direct-to-consumer channels among millennials seeking customization unavailable through brick-and-mortar assortments, compressing wholesale margins.
- Belt Bags:Premium leather constructions with artisanal stitching protocols.
- Hydration Packs:Integrated reservoir systems for endurance athletes.
Volume sits with Classic Fanny Packs; growth tilts toward Mini Fanny Packs.
Material:
Cost tier stratification aligns with performance requirements and regulatory exposure, from SB 707-mandated recycled synthetics to exempt natural hides.
- Nylon:Dominant synthetic for abrasion resistance and water repellency, now transitioning to post-consumer recycled flake under California textile mandates. Supply volatility in collection infrastructure compresses margin buffers for mid-tier producers lacking captive recycling partnerships.
- Polyester:Lower-cost alternative with tensile strength degradation across mechanical reprocessing cycles. Tactical segment producers face performance limitations restricting load-bearing applications despite regulatory pull toward recycled inputs.
- Leather:Tanned hide constructions exempt from synthetic material regulations.
- Canvas:Cotton duck weaves appealing to heritage aesthetic buyers.
Procurement is shifting toward certified recycled nylon; leather sustains premium positioning unaffected by EPR frameworks.
End User:
Application intensity determines durability specifications and price elasticity, from occasional travel use to daily athletic wear.
- Athletes:Runners, cyclists, and trail users driving functional waist-worn storage adoption. Demand concentrates in Colorado and Utah specialty retailers where hands-free mobility is non-negotiable for technical end-use.
- Travelers:Security-focused buyers prioritizing RFID-blocking compartments and anti-theft features.
- Adults:General-purpose casual use spanning commuting and recreation.
- Children:Smaller-scale constructions subject to CPSC flammability standards under 16 CFR Part 1610.
Athletes represent the steepest expansion trajectory; adults anchor current volume concentration.
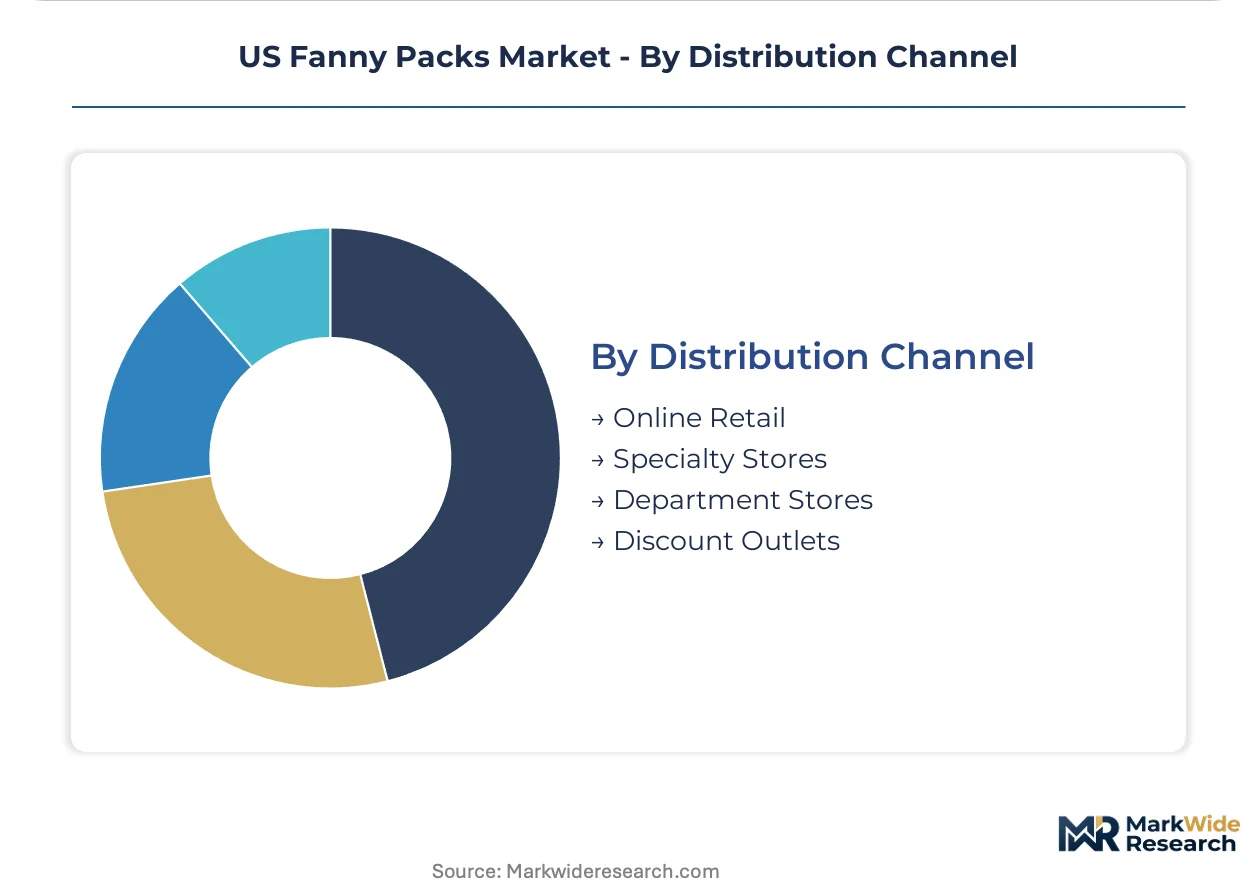
Distribution Channel:
Channel economics fragment as brand-owned e-commerce captures margin previously allocated to wholesale partners, with geographic concentration in underpenetrated Mountain West markets.
- Online Retail:Brand-direct and marketplace sales enabling customization and subscription-based gear services. Urban millennial buyers migrate here fastest, shortening cash conversion cycles for digitally native labels.
- Specialty Stores:Pacific Northwest outdoor retailers in Portland and Seattle clusters losing volume share despite anchoring artisanal manufacturing relationships.
- Department Stores:Mid-tier assortment breadth with compressed margins.
- Discount Outlets:Inventory liquidation and entry-price positioning.
Revenue is concentrating in online retail; specialty stores retain strategic value for brand credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland and Seattle anchor the Pacific Northwest manufacturing corridor where artisanal fanny pack production concentrates. California's regulatory stringency is reshaping material sourcing priorities across domestic supply chains.
Pacific Northwest
Portland and Seattle clusters host the densest concentration of direct-to-consumer brand origination and small-batch manufacturing. Oregon's emerging extended producer responsibility frameworks are pressuring early alignment with certification requirements. Seattle-based producers leverage shortened lead times for digitally native labels seeking rapid product iteration cycles.
California
SB 707 textile recycling mandates are accelerating shifts from virgin petroleum-based synthetics toward certified recycled nylon and polyester inputs. The state's Proposition 65 disclosure requirements for skin-contacting synthetic materials add compliance layering for brands distributing through California retail channels. Los Angeles and San Francisco Bay Area clusters concentrate fashion-forward mini fanny pack demand among urban millennial buyers.
Mountain West
Colorado and Utah specialty retailers remain underpenetrated relative to coastal markets, offering whitespace for regional brand building. Athletes and outdoor enthusiasts in Denver and Salt Lake City metro areas drive functional waist-worn storage adoption for trail running and cycling applications. Local producers face lower regulatory compliance burdens compared to California-based competitors.
Midwest
Contract manufacturing relationships with major outdoor labels concentrate in Midwest production footprints leveraging lower operational costs. Illinois and Ohio-based fabricators supply heritage brands with classic fanny pack constructions. The region's industrial base supports tooling and thermoformed composite panel bonding capabilities for ultralight segment production.
Southeast
Florida and Georgia distribution hubs serve discount outlet and mass retail channels with entry-price positioning. The region's logistics infrastructure supports inventory liquidation flows from coastal manufacturing centers. Lower labor costs attract assembly operations for synthetic textile constructions exempt from California's stringent material mandates.
US Fanny Packs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and channel positioning dimensions. The vendor base stratifies between heritage outdoor manufacturers, ultralight composite specialists, and contract fabricators serving private label programs. Three archetypes dominate: artisanal direct-to-consumer brands leveraging Pacific Northwest manufacturing clusters; tactical and military-focused producers with specialized load-bearing constructions; and scaled contract manufacturers sustaining relationships with major outdoor labels. Competitive moves concentrate on early alignment with state-level extended producer responsibility frameworks and backward integration into recycled material supply chains.
Within the heritage manufacturing tier, Bearse Manufacturing Co. and Sasco, Inc. occupy positions representing distinct strategic archetypes. Bearse exemplifies the Midwest contract manufacturing model, leveraging regional production footprints to sustain relationships with established outdoor labels. Sasco anchors the tactical specialization vector, with its corporate structure suggesting military and load-bearing application focus. Flowfold represents the ultralight composite differentiation path, with its name indicating technical material innovation derived from recycled sailcloth and racing fabrics.
| Leading Market Players |
|---|
| Bearse Manufacturing Co. |
| Sasco, Inc. |
| LBU, Inc. |
| Tough Traveler |
| Flowfold |
| Fieldtex Products, Inc. |
| Landes Inc. |
| Rickshaw Bagworks |
| AdCapitol |
| Others |
Value Network & Pricing Analysis
Captive recycling partnerships anchor supply positions for mid-tier producers while insulating premium brands from post-consumer nylon flake volatility. This backward integration into reclaimed polymer streams simultaneously secures SB 707 compliance and sustains margin buffers against virgin petroleum-based synthetic price swings.
Pricing Analysis
Outcome-based pricing tied to durability certification separates premium leather belt bags from synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects Global Recycled Standard tier differentiation and artisanal stitching protocols. Cost compression in recycled polyester constructions is intensifying because mechanical reprocessing cycles degrade tensile strength, forcing tactical segment producers toward virgin nylon despite regulatory pull. Fashion-forward urban millennials demonstrate lowest price sensitivity; discount outlet buyers in Florida and Georgia distribution hubs exhibit highest elasticity.
Supply Chain Analysis
Freight cost differentials between Pacific Northwest artisanal clusters and Midwest contract manufacturing footprints favor regional production placement for direct-to-consumer brands. Domestic supply draws from California recycled nylon reclamation facilities, Midwest thermoformed composite panel fabricators, and Southeast assembly operations. Single-source vulnerability concentrates in post-consumer nylon flake collection infrastructure gaps. Distribution runs through brand-owned e-commerce channels, specialty outdoor retailers in Portland and Seattle, and mass retail liquidation flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over certified recycled material streams determines compliance economics and supplier qualification advantages.
For Market Incumbents: Anchor Pacific Northwest manufacturing relationships through early OEKO-TEX and Global Recycled Standard certification investment ahead of Oregon and Washington extended producer responsibility frameworks. Defend against direct-to-consumer erosion by acquiring digitally native labels with established urban millennial subscription bases. Prioritize captive recycling partnerships to isolate margin buffers from post-consumer nylon flake price volatility. For New Entrants and Emerging Players: Specialty outdoor retailers in Colorado and Utah represent the most penetrable channel white space, with underpenetrated Mountain West markets offering regional brand building runway absent coastal saturation. Target trail running and cycling athletes through MOLLE-compatible modular attachment systems converging with technical apparel. Launch through subscription-based gear services to bypass wholesale margin compression. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by heritage outdoor labels seeking Pacific Northwest manufacturing footprint and direct-to-consumer capability. Long-term viability favors ultralight composite specialists with aerospace-derived thermoformed panel bonding expertise. Watch for inflection in state-level extended producer responsibility adoption rates beyond California, Oregon, and Washington.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Supply | Captive recycling partnerships insulate margin buffers from SB 707 compliance cost escalation. |
| Pacific Northwest Manufacturing Footprint Expansion | Portland and Seattle clusters shorten lead times for direct-to-consumer brand iteration cycles. |
| Global Recycled Standard Certification Investment | Early OEKO-TEX alignment secures supplier qualification under emerging Oregon EPR frameworks. |
| Direct-to-Consumer Channel Migration | Brand-owned e-commerce captures margin previously allocated to wholesale specialty retailers. |
| Ultralight Composite Material Differentiation | Laser-cut sailcloth laminates unify durability and weight reduction for technical outdoor enthusiasts. |
Research Methodology
Document review covered SEC filings from publicly traded outdoor apparel companies, California SB 707 regulatory text, and FTC Green Guides enforcement actions, complemented by interviews with brand managers at direct-to-consumer fanny pack labels, category buyers at Pacific Northwest specialty retailers, supply planners at Midwest contract manufacturers, and technical R&D directors in ultralight composite materials. Secondary validation drew from CPSC flammability standard documentation, Global Recycled Standard audit protocols, and U.S. customs records for synthetic textile imports. Bottom-up unit volume estimates triangulated against top-down market sizing from channel revenue aggregation.
Cross-referencing historical pricing data from recycled nylon flake markets against panel input from composite material suppliers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, end-use intensity, and distribution channel concentration. CAGRs derived from regression analysis of volume trajectories, with industry-specific inputs incorporating SB 707 phase-in schedules and Pacific Northwest manufacturing cluster capacity utilization.
Caveats apply where California regulatory stringency divergence from Texas and Florida enforcement patterns, or breakthroughs in mechanical reprocessing tensile strength retention, could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Intimate Lingerie Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Insulated Jacket Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market