
 Asia-Pacific Lingerie Market | 2026-2036
Asia-Pacific Lingerie Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lingerie Market Outlook
Direct-to-consumer subscription revenue is rewriting margin allocation across the Asia-Pacific lingerie value chain. Wacoal Holdings Corp leverages its Japanese heritage and technical fit expertise to sustain premium positioning across East Asian markets. Aimer Group anchors its growth on domestic Chinese manufacturing scale and vertical retail penetration. Zivame competes through digital-first inventory models and localized sizing databases for South Asian body profiles.
Lingerie encompasses structured and unstructured intimate apparel engineered with specific compression ratios, seam-free bonding techniques, and moisture-wicking fiber blends to provide support, shaping, and comfort beneath outer garments. Bras command the largest product-type share due to recurring replacement cycles and technical innovation in wire-free construction, while shapewear records the fastest expansion as consumers prioritize seamless silhouettes under fitted clothing. Online retail channels are capturing disproportionate growth velocity, though specialty stores retain margin dominance through personalized fitting services and private-label exclusivity.
China's SAMR enforces GB standards for textile safety and fiber labeling, while India's BIS mandates quality certification for intimate apparel sold domestically; both frameworks elevate compliance costs for imported brands and incentivize local production partnerships. Japan's METI promotes technical textile innovation through JIS standards that influence regional performance benchmarks for stretch recovery and colorfastness. Stakeholders must weigh regulatory divergence against the cost of maintaining multiple product specifications across national markets.
Market Dynamics
Direct-to-consumer digital channels are compressing traditional wholesale margins across the Asia-Pacific lingerie sector while India's PLI scheme for textiles redraws manufacturing investment flows toward domestic production bases.
Growth Catalysts
- India's PLI Scheme for Textiles:Production-linked incentives for apparel manufacturing are attracting multinational brands to establish captive facilities in Gujarat and Tamil Nadu, reducing import dependency.
- Wire-Free Bra Innovation:Technical advances in bonded seam construction and stretch recovery fabrics are shortening replacement cycles and expanding addressable occasions beyond traditional categories.
- Gen Z Metropolitan Demand:Young consumers in Shanghai, Mumbai, and Jakarta are normalizing lingerie-as-outerwear styling, creating incremental purchase occasions across day and evening segments.
Market Restraints
- Petrochemical Feedstock Volatility:Nylon and elastane prices fluctuate with crude oil benchmarks, compressing gross margins for mid-market brands unable to pass through cost swings.
- China SAMR Compliance Burden:GB standards for textile safety and fiber labeling require separate testing protocols, elevating fixed costs for brands distributing across multiple national markets.
- Cotton Substitution Pressure:Sustainable alternatives including Tencel and bamboo viscose are gaining shelf space in premium channels, threatening conventional fiber demand.
Strategic Opportunities
- Western India Urban Corridors:Maharashtra and Gujarat present underpenetrated demand pools where organized retail infrastructure is expanding faster than national averages.
- Subscription Replenishment Models:Automated sizing algorithms and predictive inventory systems are enabling direct relationships that bypass department store intermediaries.
- Japan METI Technical Textile Funding:JIS standard development programs subsidize R&D in moisture-wicking and antimicrobial finishes, creating exportable intellectual property.
Industry Challenges
- Technical Pattern-Making Talent Scarcity:Specialized skills in 3D bra engineering and computational fit modeling concentrate in Osaka and Hong Kong, constraining scaling capacity elsewhere.
- Multi-Jurisdiction Certification Timelines:Brands must sequence BIS, GB, and JIS testing sequentially rather than in parallel, extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lingerie Market |
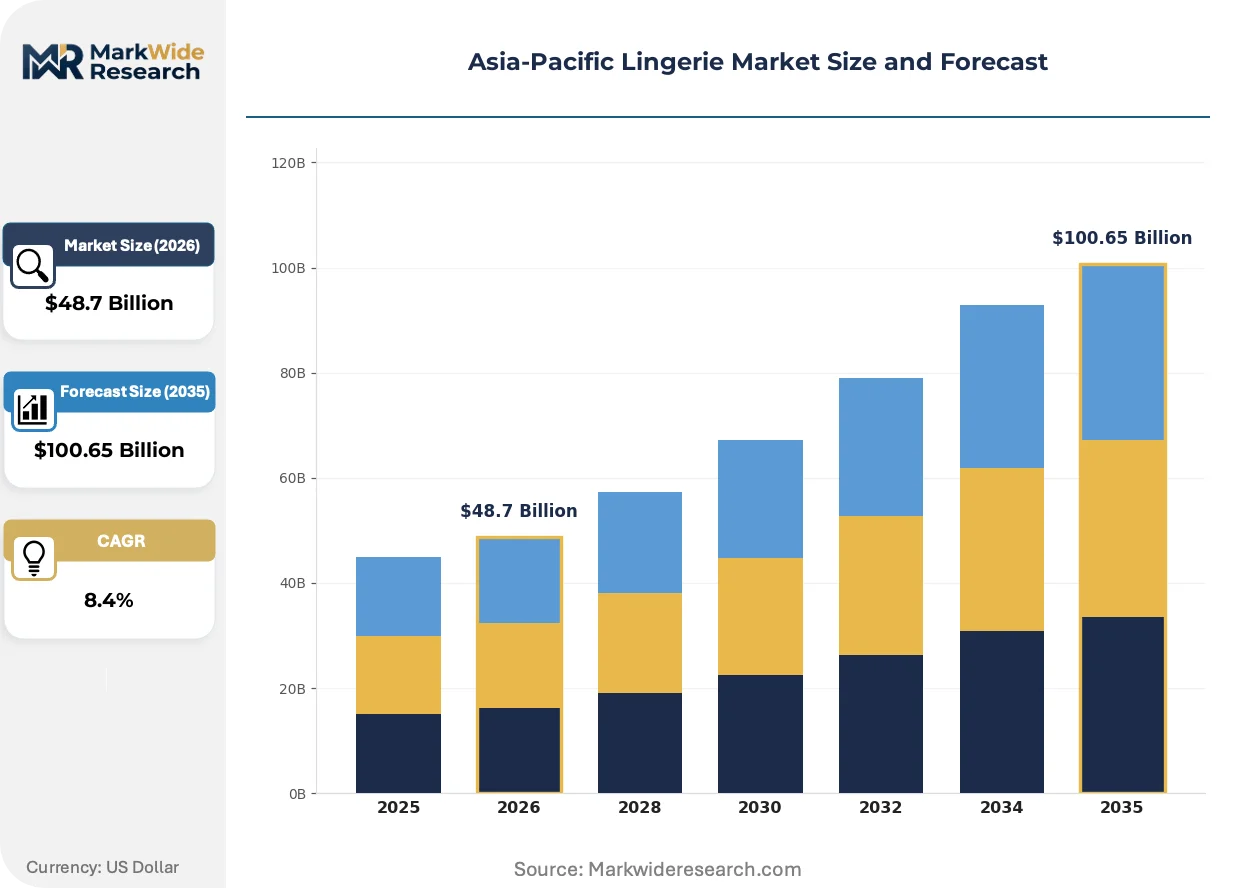
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Sleepwear, Shapewear Distribution Channel: Online Retail, Specialty Stores, Department Stores, Multi-brand Outlets End User: Women, Men, Teens, Plus-size Material: Cotton, Lace, Silk, Nylon |
| Companies Covered | Hop Lun, Wacoal Holdings Corp, Aimer Group, Regina Miracle, Zivame, Triumph International, Hanesbrands Inc., Victoria's Secret & Co., MAS Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lingerie Market Strategic Shifts
Technical textile convergence and regulatory fragmentation are simultaneously elevating product performance thresholds and compliance complexity across the Asia-Pacific lingerie value chain.
Seam-free bonding technology is migrating from premium positioning toward mass-market adoption. Japanese manufacturers pioneered ultrasonic welding and adhesive tape applications for wire-free construction. Mid-market brands in South Korea and Thailand are now licensing these processes, collapsing the traditional three-tier quality hierarchy into two distinct performance bands.
China's SAMR enforcement of GB 18401 textile safety standards is intensifying documentation requirements for imported intimate apparel. Foreign brands must submit fiber composition certificates and colorfastness testing from accredited laboratories before customs clearance. European and American labels are responding by shifting final assembly to domestic Chinese partners to streamline compliance.
Size-inclusive digital fitting tools are displacing in-person measurement services in metropolitan markets. Mobile applications using smartphone camera depth sensing now capture 14 body points with tolerances matching professional fitters. Adoption concentrates among millennial buyers in Singapore and Sydney, where retail space costs exceed the amortization of software development.
Asia-Pacific Lingerie Market Segmentation
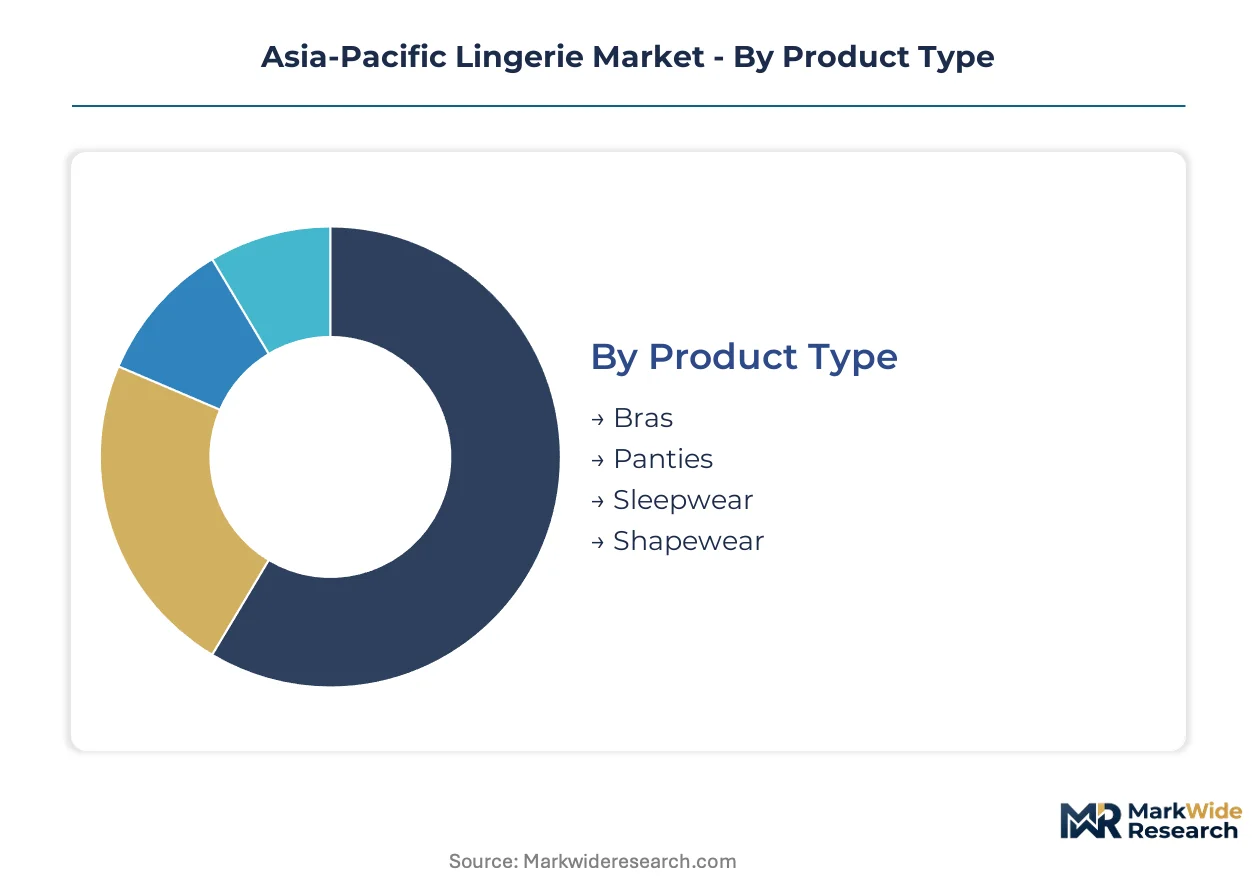
Technical specifications and channel economics fragment the Asia-Pacific lingerie market into distinct competitive arenas. Each segmentation dimension carries unique margin structures and regulatory exposure across the region's heterogeneous consumer base.
Product Type:
Cost tiers separate functional essentials from discretionary fashion purchases across the category.
- Bras:Structured garments engineered with specific compression ratios and seam-free bonding techniques serve daily support functions. Replacement cycles concentrate in China's tier-one cities where professional dress codes sustain premium wire-free innovation.
- Shapewear:Compression panels and targeted contouring address silhouette smoothing under fitted clothing. Demand accelerates fastest among millennial professionals in Mumbai and Jakarta normalizing seamless layering for workplace attire.
- Panties:Basic and fashion-forward styles in cotton blends and microfiber command volume sales through replenishment purchasing.
- Sleepwear:Loungewear hybrids and traditional nightgowns capture occasion-based spending in seasonal gifting windows.
Bras command the established base. The steepest expansion runs through shapewear.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for brand operators.
- Online Retail:Direct-to-consumer platforms leverage automated sizing algorithms and predictive inventory to bypass wholesale intermediaries. Subscription replenishment models gain traction among digital-native consumers in Singapore and Sydney where retail space costs exceed software amortization.
- Specialty Stores:Personalized fitting services and private-label exclusivity sustain margin dominance despite higher fixed costs. Technical expertise concentrates in Osaka and Hong Kong where pattern-making talent supports premium positioning.
- Department Stores:Multi-brand aggregation offers discovery for emerging labels but compresses margins through concession fee structures.
- Multi-brand Outlets:Discount positioning and inventory clearance functions serve price-sensitive segments in secondary cities.
Specialty stores anchor the revenue base. The sharpest volume gains emerge through online retail.
End User:
Body profile diversity and sizing requirements create distinct product development priorities.
- Women:Core demographic spanning structured support to unstructured comfort categories drives category-defining innovation cycles.
- Plus-size:Extended size ranges with specialized engineering for lift and support address historically underserved demand pools in India's western urban corridors.
- Men:Boxer briefs and thermal base layers represent emerging category expansion with lower penetration than womenswear.
- Teens:Entry-level pricing and age-appropriate styling capture first-lingerie purchases through school-adjacent retail locations.
Women represent the foundational revenue stream. Plus-size shows the most rapid addressable market expansion.
Material:
Fiber selection determines compliance pathways and sustainability positioning across price tiers.
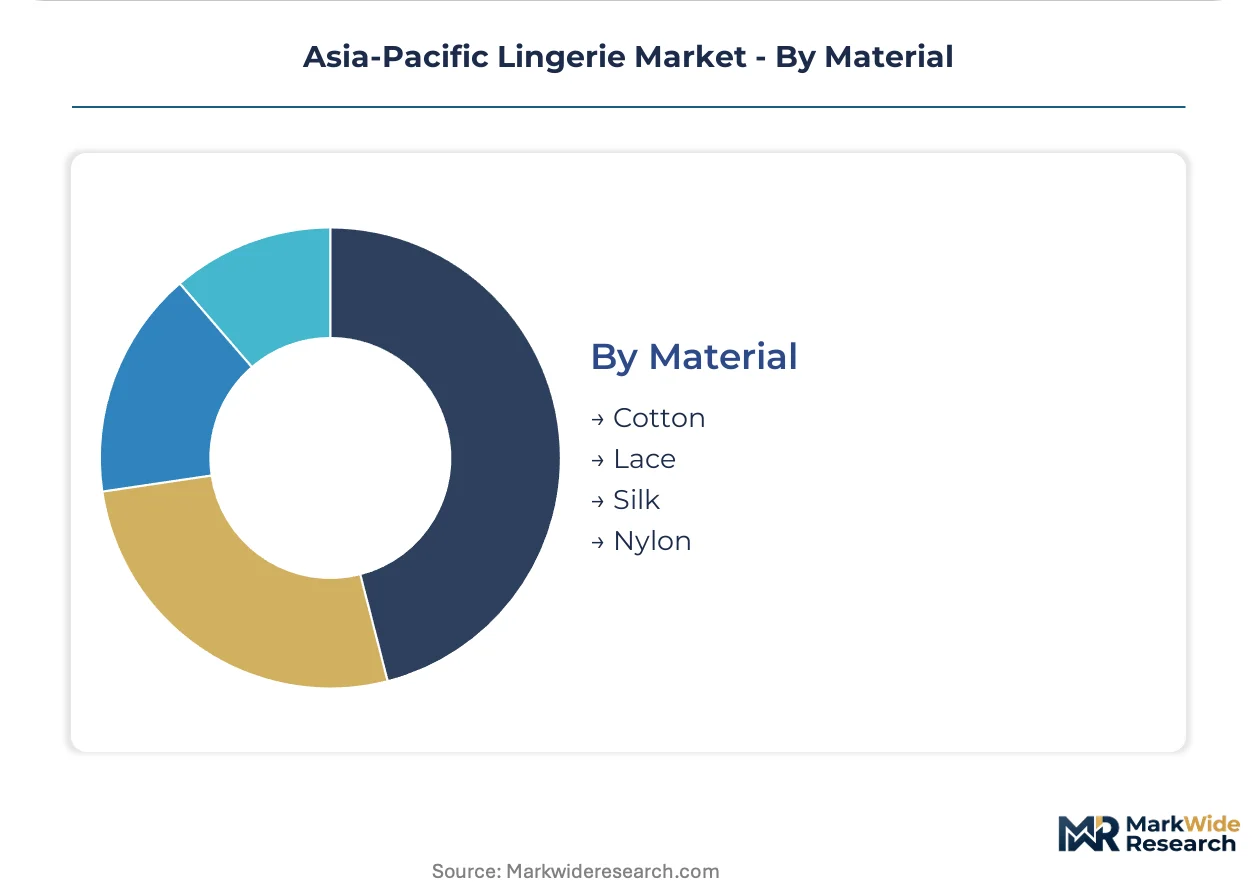
- Nylon:Petrochemical-derived synthetic with superior stretch recovery dominates mass-market construction but faces feedstock price volatility tied to crude benchmarks.
- Cotton:Natural fiber with established BIS and GB certification protocols serves sensitive-skin segments and regulatory-preferred domestic production.
- Lace:Decorative openwork construction commands premium positioning in bridal and occasion segments through artisanal production associations.
- Silk:Protein-based luxury fiber with moisture-wicking properties targets gift purchasing and temperature-regulating sleepwear applications.
Nylon underpins current volume leadership. Cotton gains share fastest on sustainability and regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific lingerie market. Japanese and Australian buyers absorb premium positioning with minimal volume sacrifice. Indian and Indonesian consumers trade down aggressively when unit costs rise.
China
Shanghai and Beijing sustain wire-free bra innovation through professional dress code requirements. SAMR enforces GB 18401 textile safety standards with fiber certification mandates before customs clearance. The Yangtze River Delta manufacturing cluster near Suzhou attracts European brands shifting final assembly to streamline compliance.
Japan
Tokyo and Osaka concentrate demand for technical fit precision and moisture-wicking performance. METI subsidizes JIS standard development for stretch recovery and antimicrobial finishes. The Kansai industrial corridor around Osaka hosts specialized 3D bra engineering talent pools that constrain scaling elsewhere.
India
Mumbai and Gujarat's urban corridors drive shapewear adoption among millennial professionals normalizing seamless workplace layering. BIS mandates quality certification for domestic intimate apparel sales. The PLI scheme for textiles attracts captive manufacturing facilities to Tamil Nadu and Gujarat.
South Korea
Seoul's metropolitan consumers license Japanese seam-free bonding processes for mid-market wire-free construction. MFDS regulates textile safety with import testing protocols. The Seoul Capital Area retail infrastructure supports rapid digital-native brand penetration with subscription replenishment models.
Australia
Sydney and Melbourne absorb premium pricing despite retail space costs exceeding software amortization thresholds. TGA oversees textile safety with accredited laboratory requirements. The Pacific coast urban corridor concentrates mobile fitting application adoption matching professional fitter tolerances.
Asia-Pacific Lingerie Market Competitive Environment
Capability concentration sits with technical pattern-making specialists; scale advantage sits with vertically integrated manufacturing groups. The market structures around three tiers: heritage Japanese fit engineers, Chinese domestic manufacturing giants, and digital-first South Asian platforms. Two strategic archetypes dominate competitive behavior: technical textile licensors extracting value from process IP, and direct-to-consumer operators bypassing wholesale intermediaries through automated sizing algorithms. M&A activity concentrates on captive production acquisition and subscription technology licensing.
Within the heritage technical tier, Wacoal Holdings Corp occupies a position exemplifying Japanese fit expertise exportable across East Asian markets. Among Chinese domestic operators, Aimer Group anchors manufacturing scale and vertical retail penetration archetypes. At the digital-native vector, Zivame represents inventory-light models leveraging localized sizing databases for South Asian body profiles. These three occupy distinct competitive spaces rather than direct confrontation.
| Leading Market Players |
|---|
| Hop Lun |
| Wacoal Holdings Corp |
| Aimer Group |
| Regina Miracle |
| Zivame |
| Triumph International |
| Hanesbrands Inc. |
| Victoria's Secret & Co. |
| MAS Holdings |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta manufacturing cluster concentrates elastic fiber and lace production, anchoring margin pools with Japanese heritage brands and domestic Chinese operators who command premium positioning through technical fit expertise. This upstream concentration forces mid-market competitors into price-sensitive volume tiers while captive production investments under India's PLI scheme redraw cost structures for South Asian supply.
Pricing Analysis
Subscription replenishment revenue drives lifetime value as automated sizing algorithms enable direct-to-consumer bypass of department store concession fees. Three-tier pricing structure across premium, standard, and economy levels separates heritage Japanese engineers from Chinese manufacturing giants and digital-native South Asian platforms. Pricing pressure stems from petrochemical feedstock volatility compressing nylon and elastane margins. Price-sensitive Indonesian and Indian consumers trade down aggressively when unit costs rise, while Japanese and Australian buyers absorb premium positioning with minimal volume sacrifice.
Supply Chain Analysis
Supplier-financing facilities extended by Tamil Nadu and Gujarat textile parks under India's PLI scheme accelerate working capital cycles for captive manufacturing investments. Raw material dependencies center on nylon, elastane, and cotton fiber inputs drawn from China, India, and Vietnam production bases. Single-source vulnerability concentrates in Japanese 3D bra engineering talent pools around Osaka. Distribution runs through direct-to-consumer platforms, specialty stores with personalized fitting services, and department store concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Gen Z metropolitan demand normalizes lingerie-as-outerwear styling, creating niche purchase occasions across day and evening segments that reward specialized positioning over mass-market coverage.
For Market Incumbents: Harden technical pattern-making capabilities through METI-subsidized JIS standard development programs in moisture-wicking and antimicrobial finishes. Acquire captive production facilities in Gujarat and Tamil Nadu to offset BIS certification burdens and petrochemical feedstock volatility. Defend against digital-native inventory-light models by embedding automated sizing algorithms into existing retail footprints.
For New Entrants and Emerging Players: Build out subscription replenishment models targeting Mumbai and Jakarta millennial professionals normalizing seamless workplace layering. Western India urban corridors present underpenetrated demand pools where organized retail infrastructure expands faster than national averages. Launch through mobile fitting applications using smartphone camera depth sensing to capture 14 body points with professional-grade tolerances.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with digital-first South Asian platforms leveraging localized sizing databases for regional body profiles. Long-term viability hinges on subscription technology licensing and captive production acquisition across the analysis window. Watch wire-free bra innovation adoption rates as inflection indicator for technical textile convergence maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Acquisition | PLI scheme incentives in Tamil Nadu reduce import dependency and streamline BIS compliance pathways. |
| Subscription Technology Licensing | Automated sizing algorithms bypass department store intermediaries and capture direct customer relationships. |
| Technical Textile R&D Investment | METI funding for JIS standard development creates exportable intellectual property in stretch recovery. |
| Direct-to-Consumer Platform Launch | Digital-native penetration concentrates in Singapore and Sydney where retail space costs exceed software amortization. |
| Size-Inclusive Digital Fitting Expansion | Mobile applications with depth sensing capture 14 body points matching professional fitter tolerances in metropolitan markets. |
Study Parameters
Operator-level perspectives from brand managers, category buyers at specialty retailers, supply planners, and technical textile R&D directors anchored the qualitative base. Secondary validation drew from customs records, SEC filings of listed lingerie manufacturers, BIS certification databases, and METI subsidy disclosure documents. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the Asia-Pacific region.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user demographic, and material composition. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention timing and technology adoption S-curves. Forecast inputs incorporated PLI scheme investment flows and GB standard enforcement intensity.
Stress conditions across petrochemical price volatility, BIS certification timeline extensions, and wire-free technology adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and consumer preference evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Press-To-Close Zippers Market
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Compression and Shapewear Market
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Shapewear Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Men's Underwear Market