

Ballet Pointe Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Ballet Pointe Shoes Market Insights
CE marking under the EU's Personal Protective Equipment framework is bifurcating the competitive landscape between certified European manufacturers and uncertified imports. Bloch leverages its Australian heritage and global distribution network to sustain premium positioning across multiple continents. Freed of London anchors its reputation on handmade construction at its London factory, while Gaynor Minden differentiates through engineered polymer technology that extends product lifespan.
Ballet pointe shoes are specialized footwear constructed with rigid shanks, layered toe boxes, and satin exteriors designed to support a dancer's full body weight on the tips of the toes during classical ballet performance. Traditional manufacturing involves hand-laminated layers of burlap, paper, and paste around a last, though contemporary variants incorporate thermoplastic polymers and elastomeric materials for customizable flex and durability. The product type dimension shows professional-grade classic models commanding the deepest margin pools due to artisan labor intensity, while contemporary designs with synthetic components attract recreational dancers through lower price points and reduced break-in periods. Material segmentation reveals satin maintaining dominance in formal performance settings, though canvas variants gain traction in training environments where breathability and washability matter.
REACH regulation through ECHA restricts certain chemical treatments in European-sourced leathers and adhesives, compelling reformulation of traditional paste components. The US Consumer Product Safety Commission monitors children's footwear for phthalate content, affecting beginner segment offerings. ISO standards for footwear safety and performance provide voluntary benchmarking that major distributors increasingly require for shelf placement. Stakeholders must monitor evolving biomaterial certifications and regional chemical restrictions as thermoplastic alternatives challenge century-old construction methods.
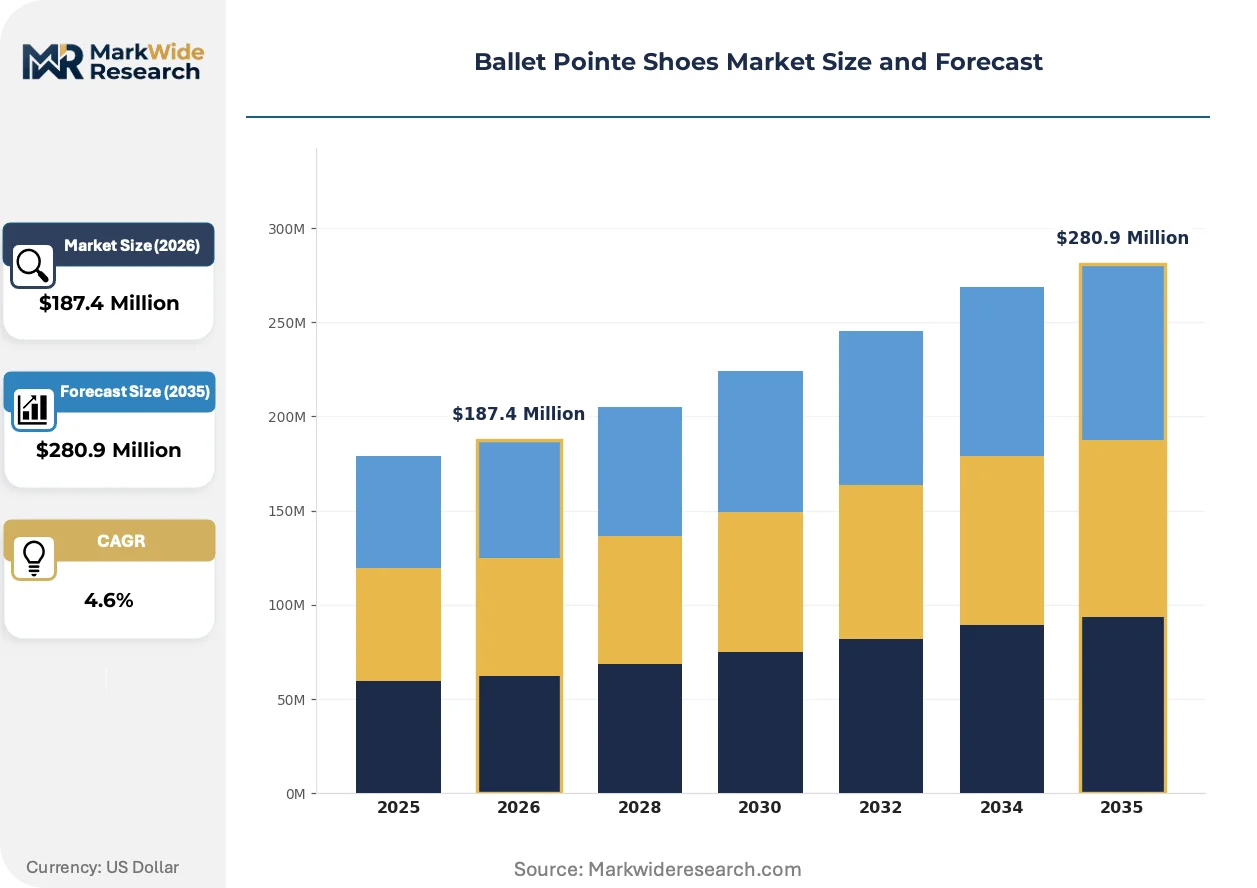
Market Dynamics
The ballet pointe shoes market faces structural pressure from thermoplastic polymer substitution, which threatens century-old handmade construction methods while promising extended product lifespan and reduced break-in time for recreational dancers.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on chemical treatments in European-sourced leathers are accelerating reformulation of traditional paste components, creating competitive advantage for manufacturers with advanced material science capabilities.
- Professional company procurement:North American and European ballet companies sustain premium demand for handcrafted models, insulating artisan producers from price erosion in recreational segments.
- Historic training cluster density:Paris, London, and New York concentrate elite academy enrollment, generating localized high-volume replacement cycles that support dedicated retail infrastructure.
Market Restraints
- Artisan labor scarcity:Hand-lamination of burlap, paper, and paste around lasts requires trained craftspeople whose numbers are shrinking across traditional manufacturing regions.
- Raw material concentration:High-grade satin and specialized leather suppliers cluster in specific European and Asian locations, exposing producers to input cost volatility and logistics disruption.
- Performance standard rigidity:Professional dancers reject synthetic alternatives for formal performance, capping addressable market expansion for engineered polymer variants regardless of durability advantages.
Strategic Opportunities
- Recreational segment expansion:Canvas variants with reduced break-in periods attract adult beginners in Australia and Canada, where dance studio enrollment grows outside traditional conservatory pipelines.
- Biomaterial certification pathways:Emerging standards for sustainable material sourcing create first-mover positioning for manufacturers investing in biodegradable thermoplastic alternatives.
- Direct-to-academy distribution:Bypassing traditional retail through institutional procurement contracts with conservatory networks captures volume commitments and reduces customer acquisition costs.
Industry Challenges
- CE marking compliance timeline:EU Personal Protective Equipment certification requires extensive testing documentation, delaying product launches and favoring incumbents with established regulatory affairs functions.
- Legacy craft preservation:Transferring hand-lamination expertise from aging master craftspeople to new workers demands multi-year apprenticeship investment that conflicts with compressed product development cycles.
- Cross-border phthalate monitoring:US Consumer Product Safety Commission scrutiny of children's footwear creates documentation burden for beginner segment offerings distributed through multi-channel retail.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballet Pointe Shoes Market Trends and Innovations
Material science advancement and regulatory chemistry restrictions are converging to transform pointe shoe construction, compressing the traditional trade-off between artisan authenticity and functional durability.
Thermoplastic polymer shank technology is miniaturizing the performance gap between engineered and traditional construction. Recreational dancers and adult beginners adopt these variants for training use, where washability and immediate wearability outweigh aesthetic tradition. The technology is miniaturizing the market share protected by handmade orthodoxy, forcing heritage manufacturers to develop hybrid product lines that preserve brand prestige while capturing synthetic-adjacent revenue.
REACH regulation through ECHA restricts specific chemical treatments in European-sourced leathers and adhesives, compelling wholesale reformulation of paste components that have defined construction for decades. Manufacturers serving EU distribution channels must requalify material suppliers and redesign lamination protocols. Professional-grade product lines face the steepest compliance burden, as these segments historically relied on traditional material treatments now flagged for restriction.
Academy procurement officers increasingly specify ISO performance benchmarks as mandatory qualification criteria, unbundling reputation-based supplier relationships in favor of documented safety verification. Conservatory networks in France and the United Kingdom lead this specification shift, requiring distributors to maintain certified testing records for shelf placement. This behavioral change elevates compliance infrastructure from cost center to competitive discriminator, particularly affecting smaller artisan producers without dedicated quality systems.
Ballet Pointe Shoes Market Segmentation
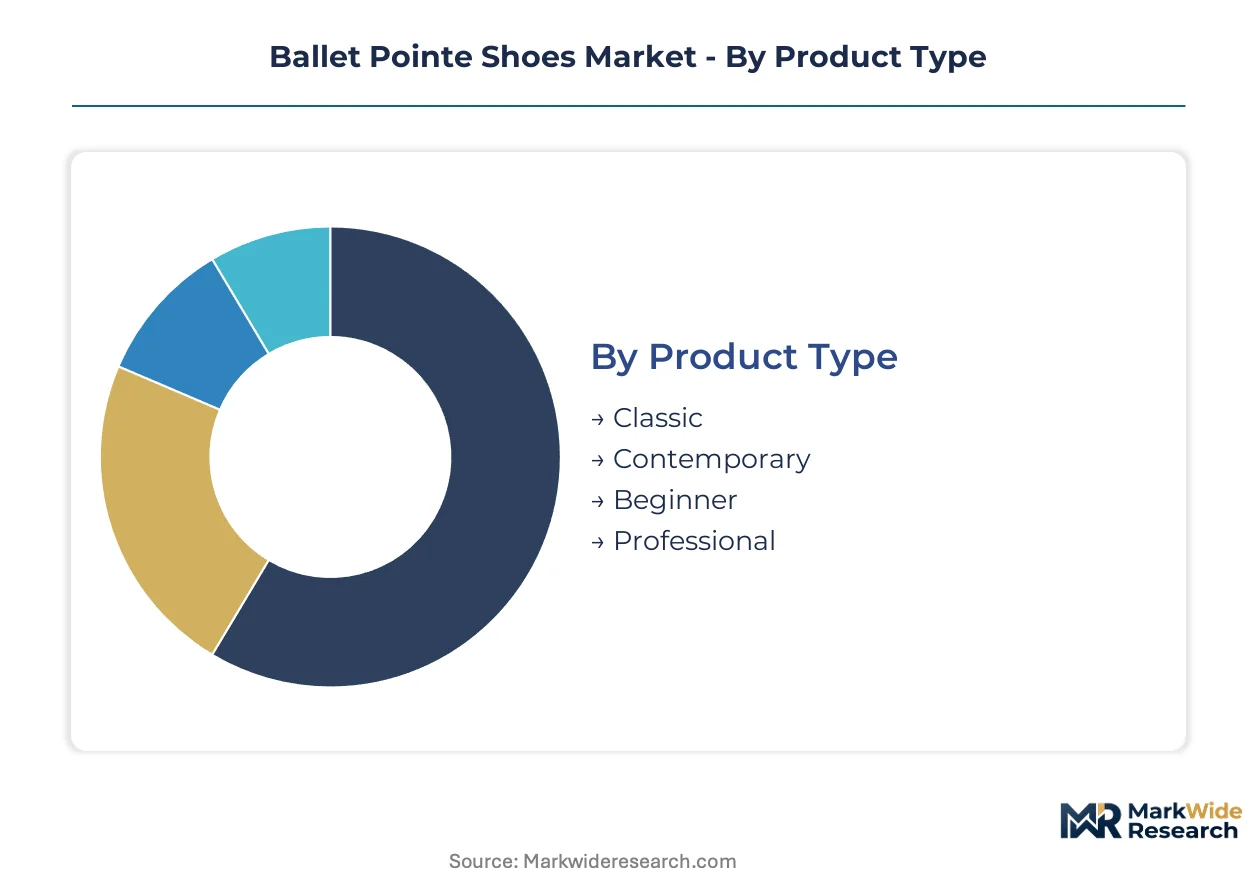
Pointe shoe segmentation reveals divergent margin structures across construction methods and user sophistication tiers. Professional-grade handmade models command premium pricing through scarcity of trained craftspeople, while synthetic alternatives capture volume through reduced break-in requirements and extended durability cycles.
Product Type:
Professional and classic variants concentrate the deepest margin pools due to artisan labor intensity and institutional procurement loyalty.
- Professional:Hand-laminated construction using burlap, paper, and paste around wooden lasts demands multi-year apprenticeship training. North American and European ballet companies sustain dedicated procurement contracts, insulating this tier from recreational price erosion.
- Classic:Traditional silhouette with rigid shank and tapered toe box maintains dominance in formal examination and competition settings. Paris and London conservatory networks specify these models for certification requirements, generating predictable replacement cycles.
- Contemporary:Engineered polymer shanks and elastomeric toe boxes reduce break-in periods for adult recreational dancers. Thermoplastic variants attract studio enrollment growth in Australia and Canada outside traditional conservatory pipelines.
- Beginner:Softer shanks and broader toe platforms accommodate pre-pointe training and skeletal immaturity. US Consumer Product Safety Commission phthalate monitoring creates documentation burden for children's footwear distributed through multi-channel retail.
Professional holds installed capacity. Contemporary is rotating up the share rankings.
Material:
Formal performance settings enforce material orthodoxy while training environments accept functional substitutes that prioritize breathability and maintenance convenience.
- Satin:Woven silk or synthetic fiber exterior maintains ceremonial aesthetic dominance in stage performance. REACH-regulated dye treatments and finish coatings in EU-sourced materials compel supplier requalification for European distribution channels.
- Canvas:Breathable woven cotton or cotton-blend upper gains traction in daily training where washability matters. Adult beginner enrollment in Australian and Canadian studios drives adoption outside traditional conservatory supply chains.
- Leather:Full-grain or corrected-grain hide construction offers durability for intensive rehearsal schedules. ECHA restrictions on chromium tanning and chemical treatments reshape European leather sourcing and adhesive compatibility testing.
- Polyester:Synthetic textile and polymer composite variants enable machine-washable pointe shoes for recreational use. Emerging biomaterial certification standards create positioning opportunities for biodegradable thermoplastic alternatives.
Satin retains ceremonial lock-in. Canvas is expanding most quickly through studio channel penetration.
End User:
Institutional procurement concentrates volume commitments while individual purchases fragment across skill levels and geographic access.
- Dance Academies:Conservatory and pre-professional programs generate predictable bulk replacement cycles tied to academic calendars. Academy procurement officers increasingly mandate ISO performance benchmarks as qualification criteria, elevating compliance infrastructure to competitive discriminator status.
- Performance Companies:Professional troupes in Paris, London, and New York anchor demand for premium handcrafted models through dedicated supplier relationships. Company shoe mistresses specify customized fittings and modification protocols unavailable through retail channels.
- Individual Dancers:Solo practitioners and recreational adult learners purchase through specialty retail or direct-to-consumer channels. Geographic distance from fitting specialists drives online consultation and remote sizing tool adoption.
- Dance Studios:Independent training facilities intermediate between institutional and individual procurement, offering branded retail partnerships or group ordering programs. Studio owners balance inventory carrying costs against student convenience expectations.
Performance Companies anchor premium tier stability. Dance Academies are climbing the fastest through specification standardization.
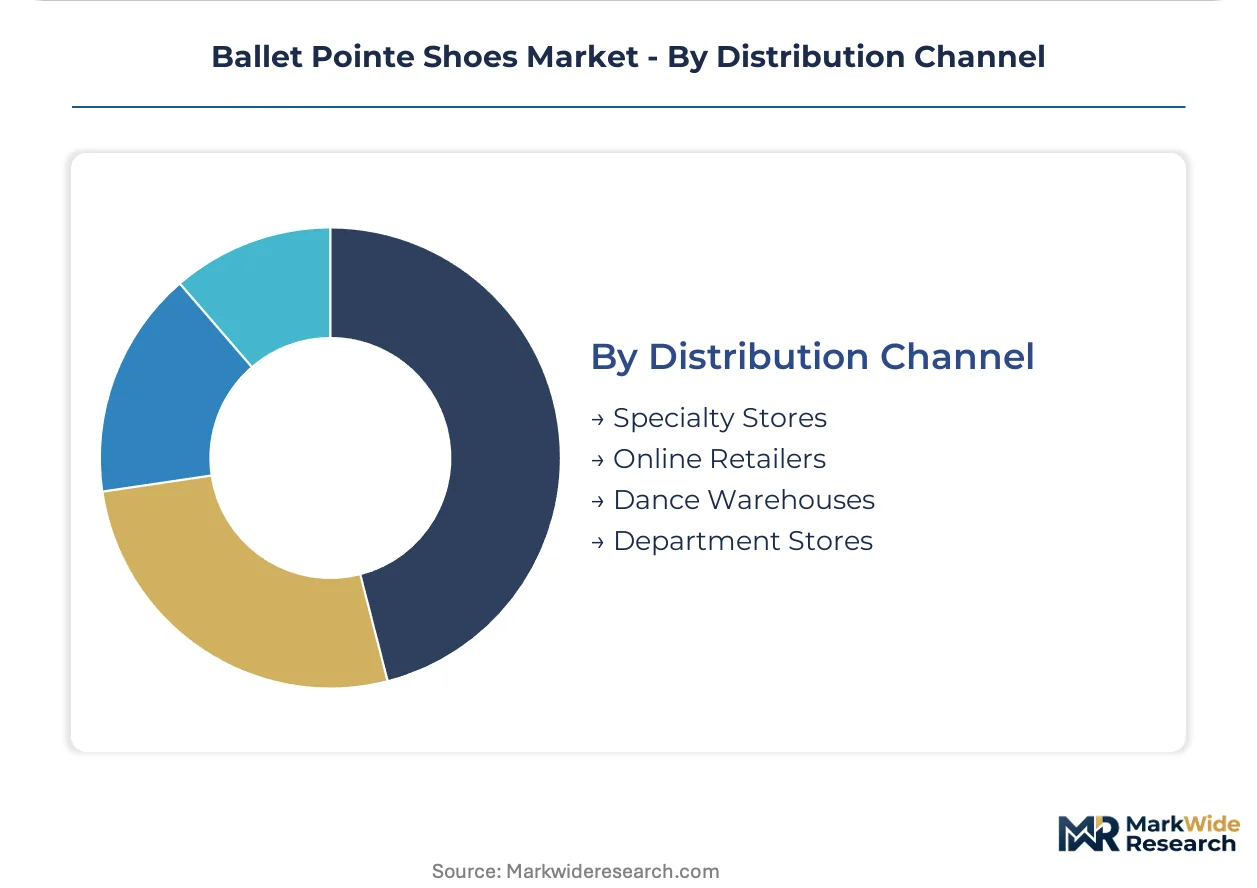
Distribution Channel:
Channel selection determines fitting service intensity and margin capture, with specialty intermediaries defending position against direct-to-academy disintermediation.
- Specialty Stores:Dedicated dance retailers provide professional fitting services, shank modification, and toe box customization. Staff expertise in foot anatomy and pointe readiness assessment justifies premium positioning against mass retail alternatives.
- Online Retailers:E-commerce platforms capture recreational and replacement purchases where sizing confidence exists. Virtual fitting tools and return policies address distance barriers for dancers outside major metropolitan clusters.
- Dance Warehouses:Institutional procurement specialists service academy and company accounts through volume contracts and seasonal delivery scheduling. Direct-to-academy distribution bypasses retail markup while capturing committed volume.
- Department Stores:General merchandise retailers carry beginner and recreational lines with limited fitting support. Shelf placement depends on distributor compliance with voluntary safety benchmarking increasingly required by major retail chains.
Specialty Stores defend fitting-service differentiation. Dance Warehouses are gaining share fastest through institutional contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite ballet academies and professional companies concentrate procurement power in historic training clusters across five countries, each shaping distinct regulatory and supply chain dynamics for pointe shoe manufacturers.
United States
New York City anchors North American demand through American Ballet Theatre and School of American Ballet procurement contracts. The US Consumer Product Safety Commission monitors phthalate content in children's footwear, creating documentation requirements for beginner segment distributors. Boston and San Francisco maintain secondary clusters of pre-professional programs with dedicated shoe mistresses.
France
Paris Opera Ballet and École de Danse de l'Opéra de Paris sustain institutional volume for premium handcrafted models. ANSM and REACH-aligned ECHA restrictions on chemical treatments in leather sourcing compel reformulation of traditional paste adhesives. Lyon and Marseille conservatory networks generate predictable replacement cycles tied to examination calendars.
United Kingdom
The Royal Ballet and Royal Ballet School in London anchor European demand for handmade construction at heritage manufacturers. CE marking under the EU's Personal Protective Equipment framework bifurcates certified domestic producers from uncertified imports. Birmingham and Glasgow maintain significant pre-professional enrollment outside the capital.
Russia
The Vaganova Academy in Saint Petersburg and Bolshoi Ballet in Moscow sustain dedicated supply relationships with domestic and regional manufacturers. National standards for theatrical footwear provide voluntary benchmarking that state-affiliated academies increasingly mandate. Novosibirsk and Perm host secondary company and training infrastructure with localized procurement.
Australia
The Australian Ballet and Queensland Ballet drive Pacific demand for both professional and contemporary synthetic variants. TGA-aligned product safety monitoring affects import documentation for children's beginner lines. Sydney and Melbourne studio enrollment growth outside conservatory pipelines expands recreational segment addressable market.
Ballet Pointe Shoes Market Competitive Landscape
Player mix skews toward heritage artisans and engineered-material specialists competing across divergent performance-versus-convenience value propositions. Market structure concentrates around London, New York, and Moscow heritage manufacturers with century-old brand equity, while polymer-engineering entrants capture recreational volume through durability advantages. Two strategic archetypes dominate: handmade traditionalists preserving artisan construction methods, and synthetic innovators commercializing thermoplastic shank technology. Competitive moves center on direct-to-academy distribution contracts and biomaterial certification investments.
Within the heritage artisan tier, Freed of London and Bloch exemplify geographic-brand positioning anchored in London and Sydney respectively, while Gaynor Minden occupies a position representing the engineered-material alternative with polymer-based construction. These three entities collectively illustrate the market's bifurcation between ceremonial authenticity and functional durability, with each archetype defending distinct customer segments through incompatible technical specifications.
| Leading Market Players |
|---|
| Bloch |
| Sansha |
| Vaganova |
| Freed of London |
| Gaynor Minden |
| Capezio |
| Nikolay |
| Grishko |
| Suffolk |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for European-sourced satin and specialized leathers concentrate pricing power with heritage manufacturers holding long-term supplier contracts, while artisan labor scarcity in London and Paris inflates cost-plus premiums for professional-grade construction.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement between heritage manufacturers and European tanneries. Three-tier pricing structure across professional, classic, and recreational levels separates handcrafted models from polymer-engineered variants, with certification grade and customization intensity driving spreads. Pricing pressure stems from thermoplastic substitution in the beginner segment, where adult recreational dancers prioritize immediate wearability over artisan authenticity. Dance academies exhibit lowest price sensitivity through institutional volume commitments, while individual recreational purchasers face highest elasticity to break-in period and durability claims.
Supply Chain Analysis
Italy and France anchor high-grade satin weaving and specialized leather finishing for formal performance tiers, while China and Vietnam machine-mold polymer shanks and canvas uppers for recreational lines. Raw material dependencies center on silk fiber suppliers in Como, chromium-tanned hides from Tuscan tanneries, and thermoplastic resins from East Asian petrochemical complexes. Single-source vulnerability concentrates in master craftsperson availability across London and Paris manufacturing ateliers. Distribution runs through specialty retailers with fitting services for professional tiers, and direct-to-academy contracts for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market approaches a platform-economics inflection as academy procurement officers unbundle reputation-based supplier relationships in favor of interoperable ISO-certified product lines, creating winner-take-most dynamics for compliance infrastructure investments.
For Market Incumbents: Compound certification advantages by accelerating CE marking documentation for thermoplastic hybrid lines before regulatory deadlines harden competitive moats. Backward integration into European tannery networks secures REACH-compliant leather supply against reformulation disruptions. Channel control through exclusive academy procurement contracts defends margin position against direct-to-consumer polymer entrants targeting recreational volume.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations opens institutional access faster than heritage competitors can adapt legacy product lines. White-space concentrates in Australian and Canadian studio markets where adult beginner enrollment grows outside conservatory supply chains. Go-to-market leverage through washable canvas variants with virtual fitting tools bypasses specialty retail infrastructure gaps in secondary cities.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because academy specification standardization and regulatory compliance burdens favor scaled players with dedicated quality systems over fragmented artisan workshops. Target archetypes include mid-cap polymer-engineering specialists with existing ISO infrastructure and regional distribution density. The signal to watch is academy procurement officer migration from brand-loyal relationships to mandatory performance benchmarking.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track | Accelerates EU market access before ECHA restrictions tighten on traditional paste formulations. |
| Direct-to-Academy Distribution | Bypasses specialty retail markup while capturing institutional volume commitments from Paris and London conservatories. |
| Thermoplastic Hybrid Development | Preserves brand prestige in professional tiers while capturing recreational demand for reduced break-in periods. |
| Biomaterial Certification Investment | Positions first-mover advantage as emerging standards for biodegradable alternatives reshape material specifications. |
| Master Craftsman Apprenticeship Programs | Addresses artisan labor scarcity threatening hand-lamination capacity at heritage London and Paris manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from pointe shoe manufacturers, academy procurement officers, specialty retail buyers, and professional shoe mistresses, and refined through secondary validation against customs trade records, ballet company annual reports, conservatory supply contracts, and ECHA regulatory filings. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against regional training enrollment data anchored forecast integrity.
Variance decomposition across product type, material composition, end-user sophistication tier, and geographic training cluster density structured the analytical framework throughout the projection horizon. CAGRs derived from replacement cycle frequencies tied to academic calendars and performance seasonality, with thermoplastic adoption curves and REACH compliance timelines as industry-specific forecast inputs.
Underlying assumptions cover sustained elite academy enrollment in Paris, London, and New York, with deviation risk concentrated in artisan labor availability and ECHA chemical restriction scope expansion. Recalibration cycles align with material shifts in regulatory enforcement patterns and polymer technology performance gaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.