
 Hats Market | 2026-2036
Hats Market Size, Share, and Industry Trends Forecast 2026-2036
Hats Market Analysis
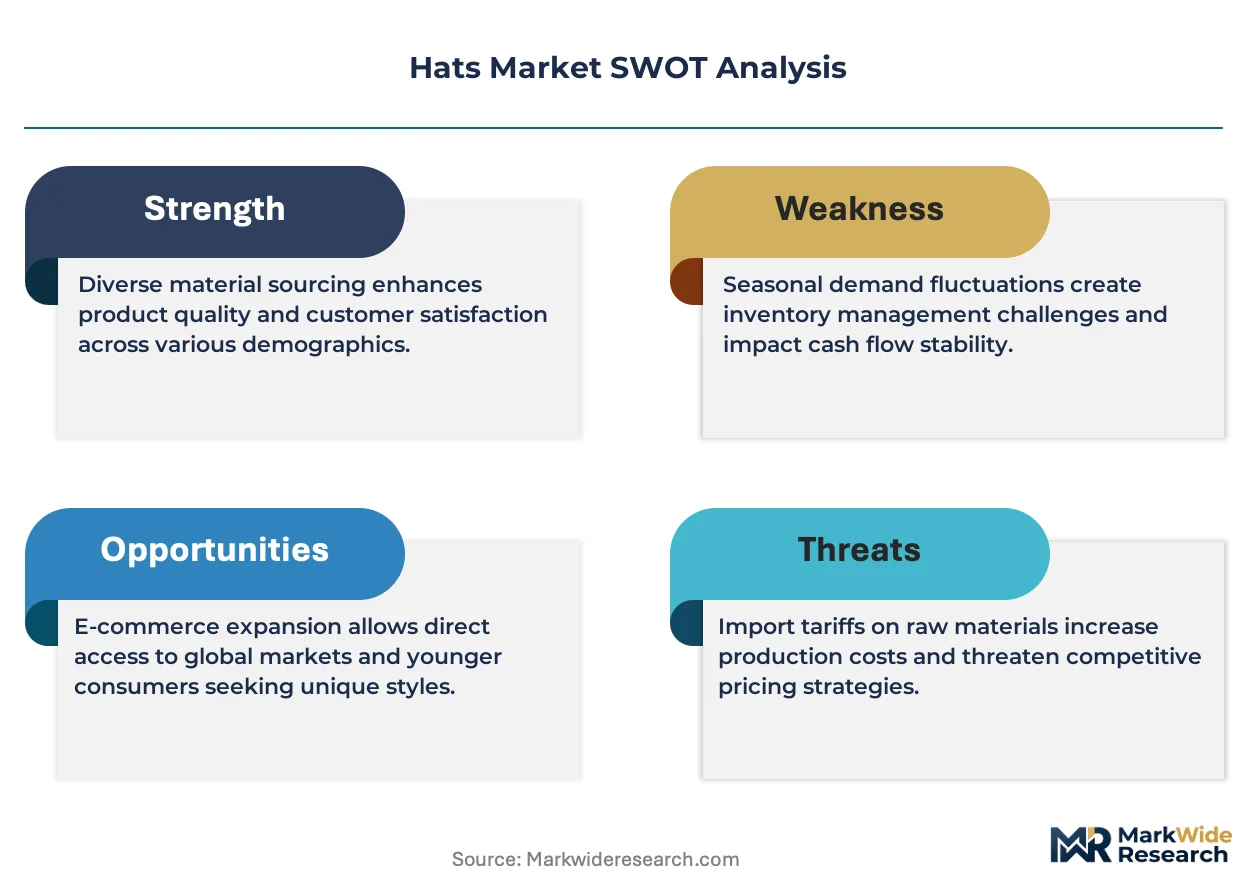
Athleisure and streetwear demand is shifting the balance of headwear consumption toward performance-oriented casual styles. Nike leverages its global sports licensing partnerships to dominate team-branded caps. Stetson anchors its position in premium Western heritage segments through controlled distribution. New Era Cap Company specializes in fitted and snapback silhouettes that occupy a defensible niche in licensed sports headwear.
Hats are wearable textile accessories constructed from woven, knitted, or molded materials with specified brim widths, crown heights, and UPF ratings, designed for sun protection, thermal insulation, fashion expression, or uniform identification. Baseball caps lead volume due to universal casual adoption and sports licensing, while beanies capture cold-weather demand in temperate climates. Straw materials command premium seasonal pricing in resort and formal segments where hand-finishing elevates margin pools above machine-woven alternatives.
The US Consumer Product Safety Commission governs flammability standards for textile headwear, while the EU REACH regulation restricts azo dyes and formaldehyde in imported accessories. China's GB standards for textile safety and labeling shape export compliance costs for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving chemical restriction schedules and traceability mandates to preserve market access across diverging regulatory frameworks.
Market Dynamics
Athleisure convergence is compressing the boundary between performance headwear and casual fashion, forcing manufacturers to engineer dual-purpose products that satisfy both technical specifications and aesthetic versatility.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA enforcement is elevating material traceability requirements, creating competitive advantage for suppliers with certified supply chains.
- Sports licensing expansion:Professional and collegiate league partnerships are extending headwear distribution into non-traditional retail channels including stadium e-commerce and streaming platform storefronts.
- Straw hand-finishing clusters:Artisan production networks in Ecuador and Madagascar are commanding premium positioning in resort and formal segments through scarcity-based positioning.
Market Restraints
- Cotton price volatility:Input cost swings for natural fibers compress margin predictability for mid-tier manufacturers lacking forward-contract coverage.
- Single-source dye suppliers:Concentration of azo-free pigment production in Zhejiang Province creates geographic vulnerability for REACH-compliant exporters.
- Synthetic microfiber shedding:Technical limitations in recycled polyester filtration are restricting adoption in premium outdoor performance lines.
Strategic Opportunities
- Domestic Chinese e-commerce:Tmall and Douyin marketplace infrastructure is opening direct-to-consumer pathways for heritage Western brands previously dependent on wholesale import partners.
- UV-protective wearable integration:Convergence of UPF-rated textiles with embedded biometric sensors is creating new product categories in golf and hiking applications.
- EU Green Deal textile strategy:Circular economy mandates for extended producer responsibility are incentivizing take-back programs and modular repair architectures.
Industry Challenges
- Digital pattern-making talent scarcity:Shortage of technicians proficient in 3D headform modeling software is extending sample development timelines.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with US FTC fiber content rules, EU textile labeling regulation, and China GB 5296.4 standards requires dedicated regulatory staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hats Market |
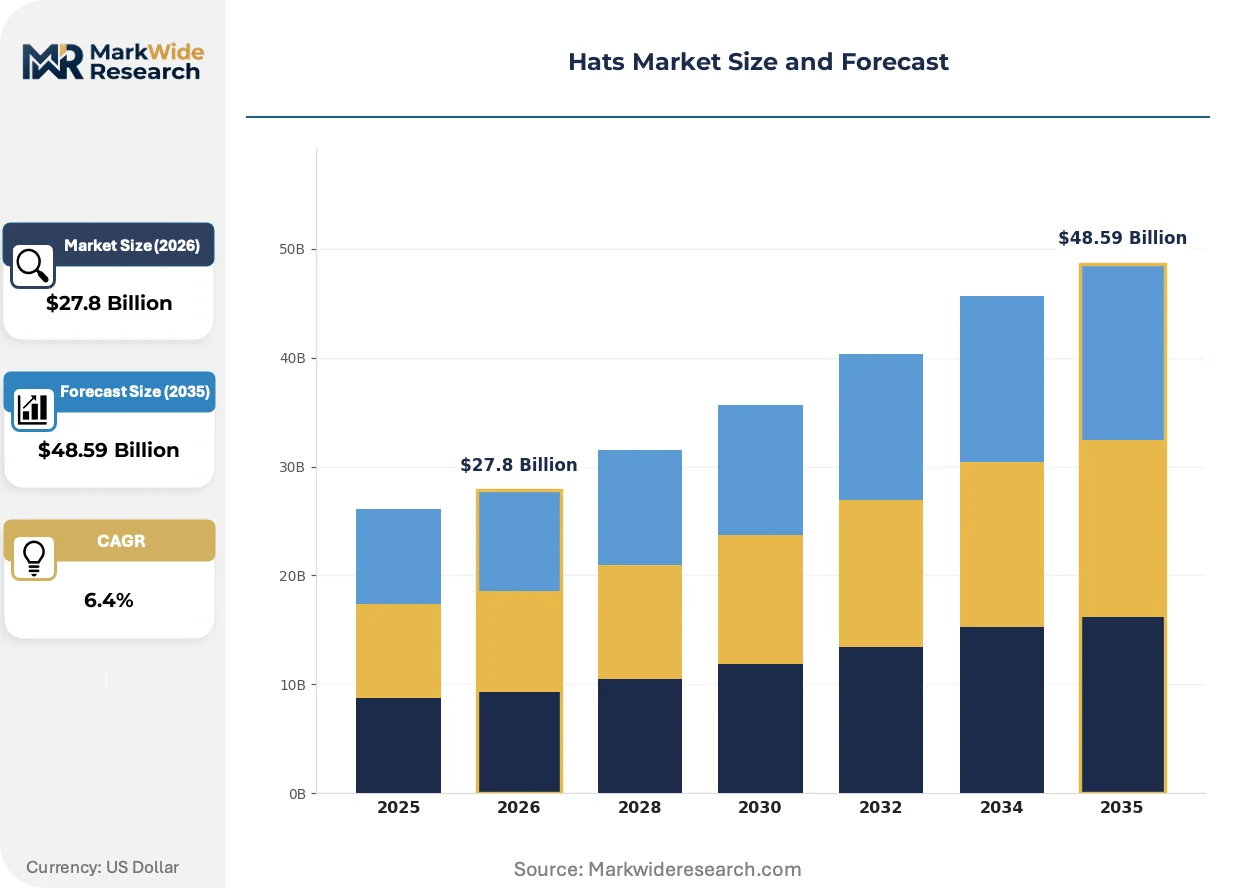
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball Caps, Beanies, Fedoras, Sun Hats Material: Cotton, Wool, Polyester, Straw Gender: Men, Women, Unisex, Kids Style: Casual, Formal, Sports, Fashion |
| Companies Covered | PUMA, Stetson, New Era Cap Company, Christys’ Hats, Lock & Co. Hatters, Nike, Under Armour, Bollman Hat Company, Adidas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hats Market Emerging Trajectories
Digital manufacturing and biomaterial science are converging to transform how headwear prototypes move from design to production, collapsing traditional sampling cycles while introducing novel performance attributes.
Laser-perforated synthetic panels are electrifying ventilation engineering in athletic caps by enabling zone-specific airflow mapping previously achievable only through manual stitching. Marathon and trail-running segments are adopting these structures at accelerating rates as heat-dissipation performance becomes a purchase determinant. The technology is compressing development timelines from six weeks to under ten days while reducing material waste.
EU REACH authorization list expansion is tightening restrictions on chromium VI in leather hat bands and formaldehyde in sizing agents used for straw stiffening. Manufacturers serving European distribution channels are reformulating chemical inputs and accelerating third-party OEKO-TEX certification to preserve shelf placement. Luxury and childrenswear categories face the most acute compliance pressure due to stricter skin-contact thresholds.
Direct-to-consumer customization platforms are fragmenting bulk order concentration as team and corporate buyers migrate from seasonal catalog purchases to on-demand embroidery and colorway selection. Traditional wholesale accounts are responding with private-label microsites and API-connected design tools. North American amateur sports leagues and hospitality uniform programs exhibit the most pronounced channel shift.
Hats Market Segmentation
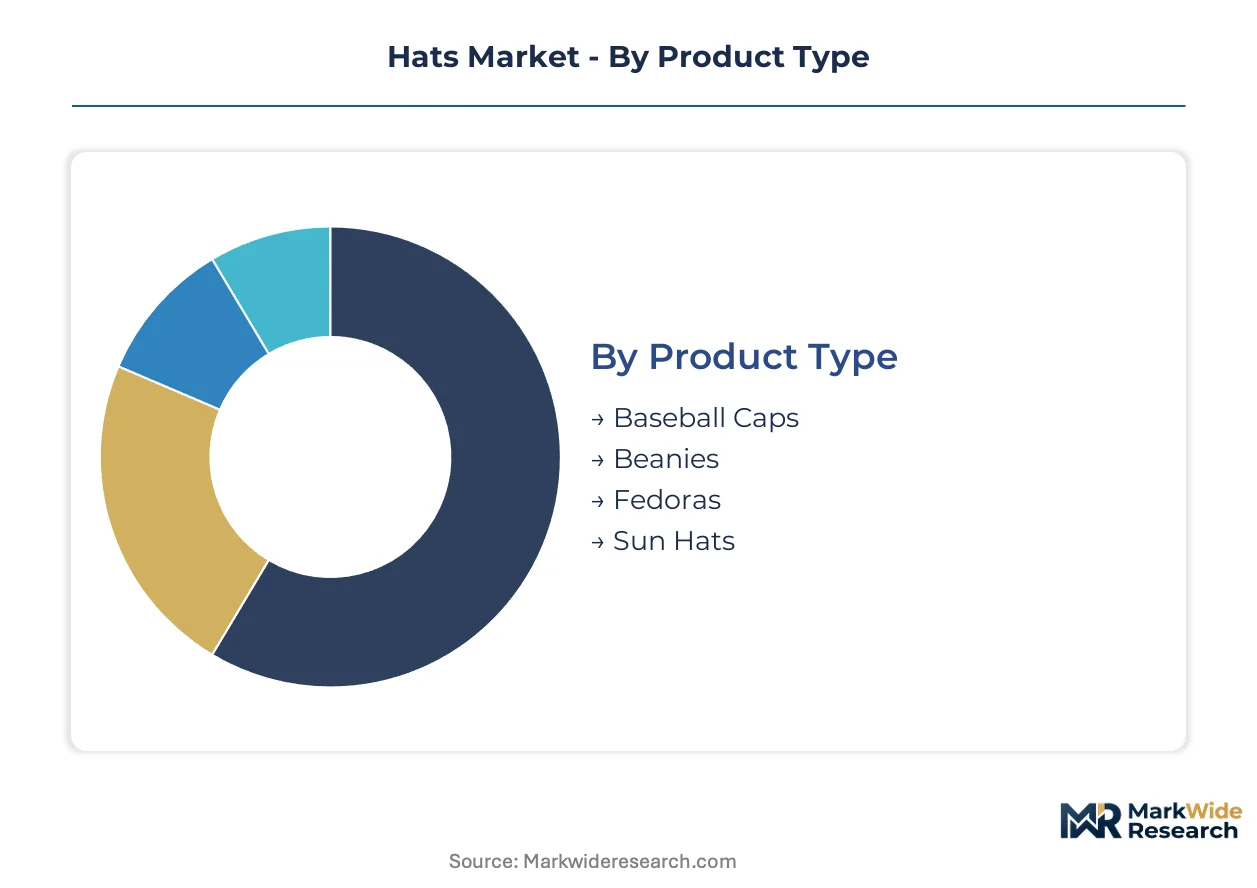
Headwear manufacturers engineer product architectures across four intersecting dimensions to capture divergent willingness-to-pay and functional requirements. Material chemistry, silhouette specifications, and end-use contexts determine margin structures and regulatory exposure. Segmentation discipline separates commodity volume plays from defensible premium positioning.
Product Type:
Six-panel crown construction and visor engineering specifications differentiate performance across athletic, casual, and protective applications.
- Baseball Caps:Structured or unstructured cotton-twill crowns with curved or flat visors dominate licensed sports and streetwear distribution. Nike and New Era Cap Company anchor team-branded volume through stadium retail and e-commerce partnerships.
- Beanies:Knitted wool-acrylic blends with ribbed or cuffed closures capture cold-weather demand in North American and European temperate climates. Thermal insulation ratings and slouch-fit silhouettes drive replacement cycles in outdoor retail channels.
- Fedoras:Felted wool or straw constructions with pinched crowns and grosgrain bands occupy formal and heritage Western segments. Hand-blocking craftsmanship in Ecuadorian and Italian production clusters commands premium positioning.
- Sun Hats:Wide-brim woven straw or UPF-rated synthetic constructions with chin cords serve resort and agricultural end-uses. Brim width specifications and packability features determine adoption in golf and hiking applications.
Baseball caps lead on scale; beanies lead on momentum in climate-adaptive casual wear.
Material:
Fiber selection governs thermal performance, chemical compliance burden, and circular economy integration pathways.
- Cotton:Natural fiber with established dye affinity and breathability dominates mid-tier casual headwear. Price volatility in ICE cotton futures compresses margin predictability for manufacturers lacking forward-contract coverage.
- Wool:Merino and lambswool variants provide moisture-wicking insulation in cold-weather beanies and formal felt hats. Mulesing-free sourcing certifications increasingly gate access to EU and North American premium distribution.
- Polyester:Recycled PET and virgin synthetic yarns enable laser-perforated ventilation panels in athletic caps. Technical limitations in microfiber filtration restrict adoption in EU Green Deal-aligned product lines.
- Straw:Toquilla palm and synthetic raffia weaves with hand-finishing elevate margin pools in resort and formal segments. Ecuadorian artisan networks exploit scarcity-based positioning against machine-woven alternatives.
Cotton leads on scale; straw leads on margin expansion in artisan-crafted segments.
Gender:
Fit engineering and aesthetic coding align product development with distinct purchasing behavior patterns.
- Men:Larger headform specifications and subdued color palettes dominate team-licensed and workwear-adjacent lines. Sports licensing partnerships concentrate volume in this segment through fitted and snapback silhouettes.
- Women:Expanded size runs, decorative embellishments, and seasonal color rotations drive fashion accessory turnover. Direct-to-consumer customization platforms accelerate micro-trend responsiveness.
- Unisex:Adjustable closure systems and neutral styling bridge casual and outdoor performance applications. Athleisure convergence amplifies demand for dual-purpose headwear in this classification.
- Kids:Scaled-down dimensions with breakaway chin straps and non-toxic material certifications address safety-sensitive parental purchasing. EU REACH and US CPSC flammability standards impose elevated compliance costs.
Unisex leads on momentum as athleisure dissolves traditional gender boundaries in casual headwear.
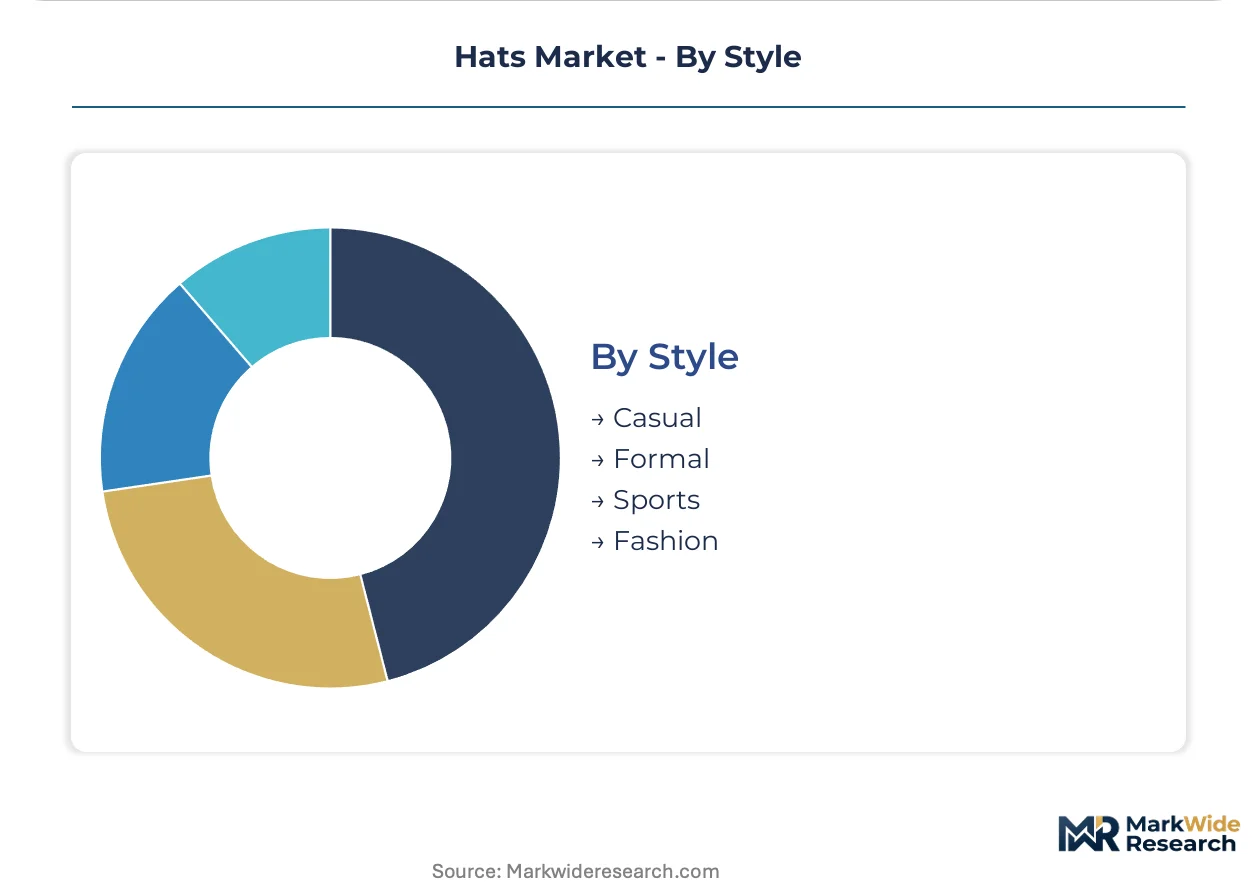
Style:
Occasion-based positioning determines distribution channel selection and price architecture.
- Casual:Universal adoption across age demographics with minimal styling constraints enables highest volume throughput. Baseball caps and unstructured bucket hats anchor this classification in mass retail.
- Formal:Structured felt and hand-finished straw constructions with precise crown proportions serve wedding, racing, and diplomatic dress codes. Controlled distribution through heritage houses preserves price integrity.
- Sports:Technical moisture-management, ventilation engineering, and league licensing define performance requirements. Heat-dissipation specifications increasingly determine purchase decisions in running and golf segments.
- Fashion:Rapid style cycling and designer collaborations drive editorial placement and limited-drop scarcity economics. Streetwear label partnerships command resale premiums in secondary markets.
Casual leads on scale; sports leads on technical innovation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors global headwear manufacturing through vertically integrated textile-to-finished-goods corridors serving export markets and domestic e-commerce channels.
United States
Sports licensing partnerships with MLB, NFL, and NBA franchises drive premium headwear consumption through stadium retail and team e-commerce portals. The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1610 for textile headwear imports. New York City and Los Angeles host design studios and flagship retail concepts that bridge streetwear and athletic performance segments.
China
Domestic brands scale manufacturing capacity to serve Tmall and Douyin marketplace demand while reducing import dependency. GB 5296.4 textile labeling standards and GB 18401 safety requirements shape export compliance costs for multi-jurisdiction suppliers. Guangdong and Zhejiang provinces concentrate dyeing, embroidery, and cut-and-sew operations in specialized industrial zones.
Germany
REACH chemical disclosure mandates and OEKO-TEX certification requirements elevate material traceability standards for imported accessories. EU Green Deal textile strategy incentives accelerate circular economy pilot programs among specialty retailers. Berlin and Munich anchor premium outdoor and heritage Western distribution networks.
United Kingdom
Heritage millinery traditions in formal and racing segments sustain artisan craft clusters against fast-fashion import pressure. UKCA marking requirements post-Brexit create parallel compliance pathways alongside retained EU regulations. London's Savile Row and Jermyn Street corridors preserve controlled distribution for luxury felt and straw constructions.
Japan
Precision manufacturing standards and seasonal fashion cycling drive demand for technical performance and limited-edition collaborations. METI guidelines on recycled content labeling influence sustainable material sourcing decisions. Tokyo's Shibuya and Harajuku districts function as trend incubation zones for streetwear silhouette evolution.
Hats Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek licensed sports distribution and direct-to-consumer platform access. The vendor base organizes across three tiers: global sports apparel conglomerates with headwear as portfolio extension, heritage specialists defending premium positioning through controlled distribution, and regional fabricators serving private-label mass retail. Licensing negotiations and e-commerce API integrations constitute the primary competitive battlegrounds, while artisan production networks exploit scarcity-based positioning in formal segments.
Within the heritage specialist tier, Stetson and Christys' Hats exemplify controlled distribution architectures that preserve price integrity against mass-market dilution. Nike and New Era Cap Company anchor licensed sports positioning through league partnerships and fitted silhouette specialization. PUMA and Adidas occupy the athletic performance vector with global supply chain scale.
| Leading Market Players |
|---|
| PUMA |
| Stetson |
| New Era Cap Company |
| Christys' Hats |
| Lock & Co. Hatters |
| Nike |
| Under Armour |
| Bollman Hat Company |
| Adidas |
| Others |
Supply Flow & Price Mechanics
Laser-perforated panel adoption is collapsing prototype development cycles from six weeks to under ten days while simultaneously concentrating production economics among manufacturers with digital manufacturing capabilities. This technological shift compresses cost structures for early adopters while fragmenting pricing power across tiers based on equipment access.
Pricing Analysis
Input-cost pass-through from cotton futures volatility and REACH-compliant dye premiums shapes pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels separates hand-finished straw artisans from machine-woven alternatives and licensed sports volume. Price differentiation rests on certification grade and brand licensing depth. Pricing pressure stems from cotton price swings compressing mid-tier margins. Amateur sports leagues exhibit highest price sensitivity; heritage Western collectors show lowest.
Supply Chain Analysis
Straw fiber supply rests on Ecuadorian toquilla palm and Madagascan raffia artisan networks, while synthetic yarn production centers on Zhejiang Province dyeing clusters. Raw material dependencies include azo-free pigments, laser-perforation equipment, and moisture-wicking synthetic blends. Single-source vulnerability in Zhejiang dye concentration creates geographic risk for REACH-compliant exporters. Distribution runs through Tmall and Douyin direct-to-consumer platforms alongside stadium retail and heritage house controlled channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hats market functions as a geographic-arbitrage play between EU REACH compliance costs and Chinese domestic manufacturing scale, with regulatory differential creating margin expansion for certified supply chains.
For Market Incumbents: Lock in OEKO-TEX certification investments to defend shelf placement against emerging private-label entrants. Secure forward cotton contracts to neutralize ICE futures volatility. Deepen backward integration into straw artisan networks in Ecuador to preserve scarcity-based premium positioning against machine-woven competitors.
For New Entrants and Emerging Players: Digital pattern-making software proficiency offers entry wedge against talent-scarce incumbents. Target UV-protective wearable integration in golf and hiking applications as most penetrable white-space. Pursue API-connected customization platforms for North American amateur sports leagues as primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking REACH certification or direct-to-consumer platform access. Long-term viability favors vertically integrated players with captive artisan networks and multi-jurisdiction compliance infrastructure. Watch EU Green Deal extended producer responsibility implementation as inflection signal for circular economy positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Artisan Networks | Captures Ecuadorian straw scarcity premium against machine-woven alternatives. |
| Direct-to-Consumer Platform Launch | Opens Tmall and Douyin pathways bypassing wholesale import dependencies. |
| REACH Certification Investment | Preserves EU market access as ECHA tightens chemical disclosure mandates. |
| Laser-Perforation Technology Adoption | Compresses development timelines while enabling zone-specific ventilation engineering. |
| Take-Back Program Implementation | Aligns with EU Green Deal circular economy incentives for modular repair architectures. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with brand managers at heritage houses, category buyers at sporting goods retailers, supply planners at licensed apparel manufacturers, and channel sales heads at e-commerce platforms. Secondary sources included customs and trade data, SEC filings from publicly traded apparel conglomerates, OEKO-TEX certification registries, and ECHA chemical restriction schedules. Bottom-up volume modeling triangulated against top-down market sizing.
Granularity-level framing applied product type, material chemistry, end-use occasion, and regional regulatory cluster dimensions at the segment level. CAGRs were derived from trend extrapolation adjusted for input cost trajectories and channel shift velocities across the analysis window. Forecast inputs incorporated cotton futures curve assumptions and sports licensing partnership renewal probabilities.
The model holds under stable REACH enforcement intensity and cotton price bands; deviation in tariff regimes or dye supplier concentration would shift volume and value trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Electric Heated Shoes Market
Apparel & Footwear
India Denim Jeans Market