
 School Shoes Market | 2026-2036
School Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
School Shoes Market Insights
Subscription-based replacement programs for outgrown school footwear is expanding how distributors monetize recurring family purchases. Wenling Wofeng Shoes Co., Ltd. leverages its manufacturing scale to serve bulk institutional contracts across East Asian markets. Quanzhou Qirun Trading Co., Ltd. anchors its position through specialized export logistics for leather school shoe lines. HYD Shoes differentiates by controlling in-house production of orthopedic-compliant designs for younger age brackets.
School shoes are closed-toe footwear engineered with reinforced toe caps, cushioned insoles, and abrasion-resistant outsoles to withstand daily wear during structured educational activities. Manufacturers typically employ cemented or direct-injection molding processes to bond rubber or thermoplastic polyurethane soles to leather, synthetic, or canvas uppers, achieving flex resistance above 100,000 cycles under standardized testing. Sneakers dominate volume within the product type split due to their versatility across physical education and casual uniform requirements, while leather commands premium positioning in private and parochial school segments. The preschool age group generates the fastest replacement velocity as foot growth outpaces shoe durability, creating concentrated margin pools in sizes spanning toddler through early elementary ranges.
China's SAMR enforces GB standards limiting harmful substances in children's footwear, directly constraining material sourcing for synthetic uppers and rubber soles. India's BIS certification mandate for domestically sold school shoes creates compliance barriers for unqualified imports while elevating quality benchmarks for institutional tenders. The EU REACH regulation governs chemical content for any European-bound exports, affecting dye formulations and adhesive selections across supplier factories. Stakeholders must monitor how evolving national safety standards reshape supplier qualification criteria and procurement contract terms across their target markets.
Market Dynamics
China's GB standards enforcement is compressing supplier qualification timelines while India's BIS certification mandate is elevating institutional tender barriers, creating a dual-track compliance environment that favors manufacturers with captive testing facilities.
Growth Catalysts
- GB Standards Convergence:China's SAMR enforcement of GB 30585-2014 limits phthalates and heavy metals in children's footwear, compelling manufacturers to reformulate synthetic uppers and rubber compounds. This regulatory pressure is accelerating material substitution toward water-based adhesives and bio-based thermoplastic polyurethanes.
- Institutional Procurement Scaling:India's Right to Education Act implementation drives bulk enrollment in government schools, generating concentrated demand for durable, low-cost school footwear through state-level tender systems. Manufacturers with regional distribution networks capture recurring replacement contracts.
- Orthopedic Design Integration:Podiatric research on juvenile foot development is reshaping product specifications for preschool and early elementary segments. Brands incorporating arch support, heel counters, and flexible forefoot zones command preference among parents with disposable income.
Market Restraints
- Petrochemical Input Volatility:Thermoplastic polyurethane and synthetic rubber prices fluctuate with crude oil derivatives, compressing margins on mid-tier product lines where price elasticity constrains pass-through capacity.
- Concentrated Manufacturing Geography:Wenling and Quanzhou industrial clusters in Zhejiang and Fujian provinces supply over 60% of global school shoe volume, exposing buyers to concentrated weather, labor, and logistics disruption risk.
- Leather Substitution Pressure:Vegan material alternatives and canvas constructions displace leather in uniform segments where schools relax formal dress codes, eroding premium positioning for traditional tannery-dependent suppliers.
Strategic Opportunities
- Subscription Replacement Models:Direct-to-family programs addressing rapid foot growth in ages 4-8 capture lifetime value through automated size progression and seasonal delivery, bypassing retail margin stacking.
- EU REACH-Compliant Export Positioning:Manufacturers certifying to ECHA chemical restrictions access premium private school segments across Germany, France, and the Netherlands where institutional buyers prioritize supply chain transparency.
- RFID-Enabled Inventory Tracking:Integration of embedded tags with school uniform management systems enables bulk procurement clients to monitor distribution, reduce loss, and automate reorder triggers.
Industry Challenges
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with China's GB standards, India's BIS mandates, and EU REACH requirements demands redundant testing protocols and extended product development cycles.
- Skilled Pattern Engineering Scarcity:Footwear last design and biomechanical fit optimization expertise concentrates in aging European and Japanese technical centers, constraining rapid product iteration for emerging market specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Shoes Market |
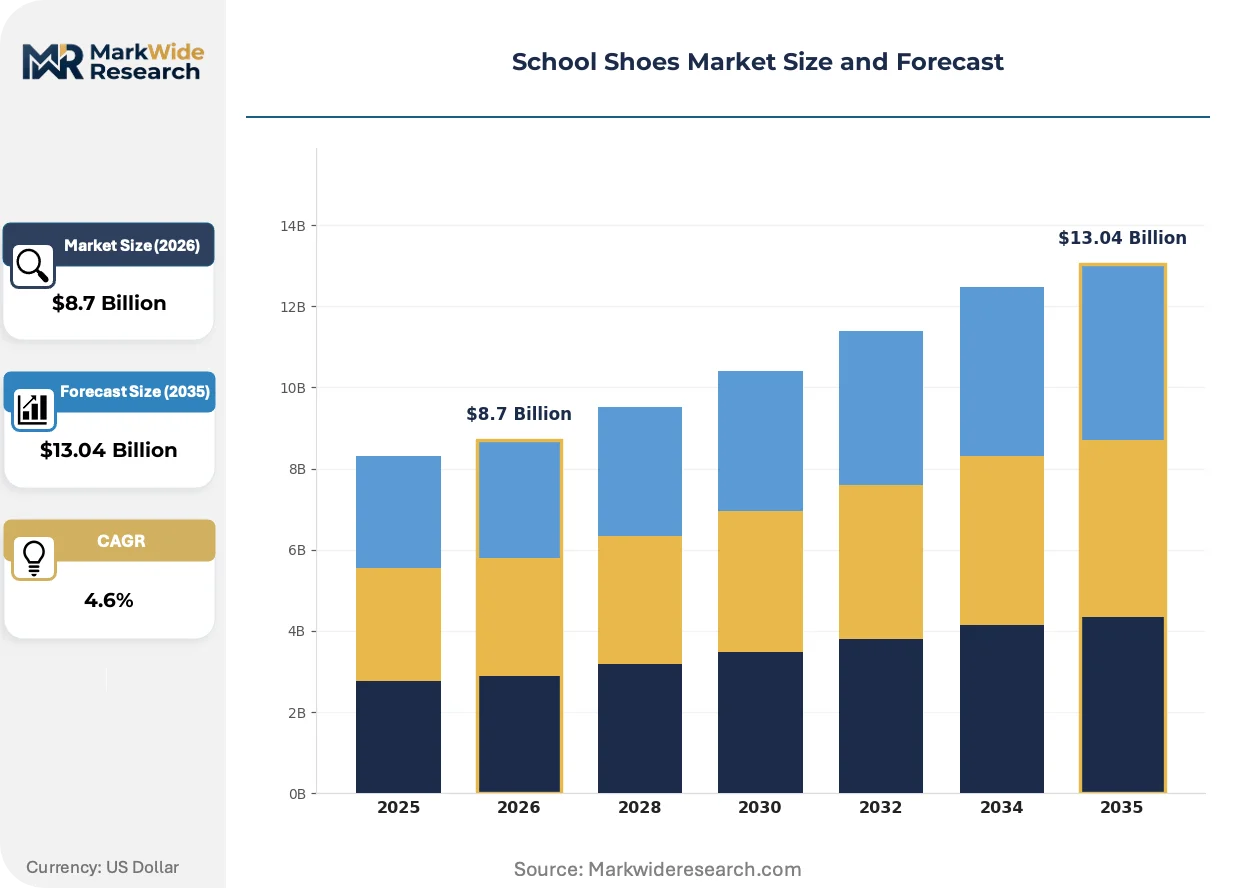
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ankle Boots, Sneakers, Loafers, Sandals Material: Leather, Synthetic, Canvas, Rubber Age Group: Preschool, Primary, Secondary, Tertiary End User: Boys, Girls, Unisex, Others |
| Companies Covered | Wenling Wofeng Shoes Co., Ltd., Quanzhou Qirun Trading Co., Ltd., HYD Shoes, Foshan Wise Import & Export Co., Ltd., Zhejiang Miyue Shoes Co., Ltd., Chengdu Cofida Leather Products Co., Ltd., Cangnan Hongtu Trading Co., Ltd., Quanzhou Bestway Import and Export Co., Ltd., Xiamen Elletop Import and Export Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Shoes Market Trends and Innovations
Material science advances and procurement digitization are compressing traditional manufacturing and distribution timelines, while regulatory fragmentation forces parallel compliance investments across multiple certification frameworks.
3D-printed midsole technology is modularizing production workflows for customized orthopedic school footwear. European specialist manufacturers and Asian contract producers are adopting selective laser sintering for localized cushioning geometries. This capability is modularizing the traditional mass-production model, enabling batch-size-one economics at previously unattainable cost points.
REACH Annex XVII restrictions on chromium VI in leather tanning are forcing tannery suppliers toward vegetable and synthetic tanning alternatives. German and Italian finishing houses are retooling wet-blue processing lines to meet ECHA substance limitations. Premium leather school shoe exporters to the EU are absorbing reformulation costs or pivoting to synthetic upper constructions.
Bulk institutional buyers are consolidating vendor relationships around multi-year framework agreements with performance guarantees. Indian state education departments and Middle Eastern private school chains are replacing spot purchasing with contracted volume commitments. This concentration is most visible in Gujarat, Maharashtra, and Karnataka where state procurement portals standardize technical specifications and reverse-auction pricing.
School Shoes Market Segmentation
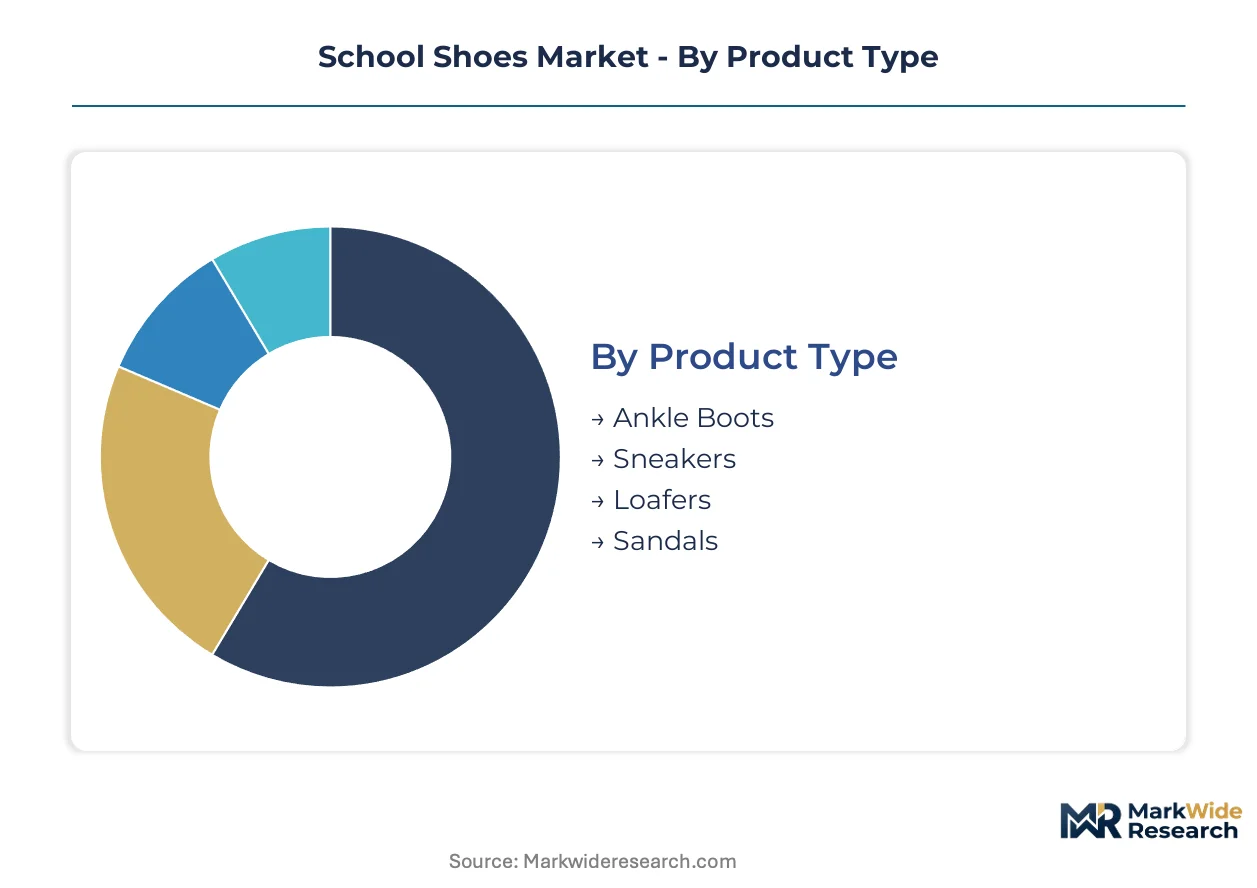
School shoe procurement patterns diverge sharply across institutional buyers versus family purchasers, with each segment demanding distinct performance specifications and price positioning. Manufacturers configure production lines around these structural differences, optimizing material selection and durability ratings for specific age brackets and institutional requirements.
Product Type:
Volume concentration in molded rubber outsole categories shapes factory equipment allocation across Wenling and Quanzhou manufacturing clusters.
- Sneakers:Engineered with cemented or direct-injection molded thermoplastic polyurethane soles bonded to synthetic mesh or canvas uppers, achieving flex resistance above 100,000 standardized test cycles. Demand concentrates in India's government school procurement systems where physical education mandates require versatile footwear for combined classroom and athletic use.
- Loafers:Slip-on constructions with moccasin stitching or apron toes, typically employing leather or synthetic uppers with low-profile rubber soles. China's private and international school segments drive preference here, where stricter uniform codes favor formal silhouettes over athletic designs.
- Ankle Boots:Reinforced quarter-height designs with padded collars and speed-lacing hardware, specified for colder climates and extended outdoor exposure.
- Sandals:Open-toe constructions with adjustable straps and contoured footbeds, restricted to specific institutional dress codes permitting seasonal flexibility.
Today's leader: Sneakers. Tomorrow's challenger: Loafers.
Material:
Cost tier differentiation separates premium positioning from institutional bulk procurement, with raw material selection directly determining margin structure and certification pathway complexity.
- Synthetic:Polyurethane and polyvinyl chloride formulations enabling color consistency and water resistance at scale production economics. India's BIS certification mandate for domestically sold footwear elevates quality benchmarks for synthetic upper constructions in state tender systems.
- Leather:Full-grain and corrected-grain bovine hides processed through chrome or vegetable tanning, commanding premium positioning in private and parochial school segments. EU REACH Annex XVII restrictions on chromium VI are forcing tannery suppliers toward alternative finishing processes for European-bound exports.
- Canvas:Cotton duck or twill weaves with rubber foxing tape, offering breathable constructions at economy price points.
- Rubber:Natural and synthetic compounds for outsole and upper applications in wet-weather specialized designs.
Synthetic materials dominate institutional volume. Leather retains premium-margins in private education segments.
Age Group:
Replacement velocity varies inversely with foot growth stabilization, creating concentrated margin pools where durability specifications intersect with rapid size progression.
- Preschool:Sizes spanning toddler through early elementary with orthopedic-compliant features including arch support and flexible forefoot zones. Podiatric research on juvenile foot development is reshaping specifications for this bracket, with brands incorporating heel counters commanding preference among parents with disposable income.
- Primary:Standardized sizing for structured educational environments with reinforced toe caps and abrasion-resistant outsoles.
- Secondary:Adult-size scaling with fashion-influenced styling permitted under relaxed uniform codes.
- Tertiary:Minimal institutional specification, functioning as general casual footwear with occasional formal requirements.
Preschool segments expand most quickly through subscription replacement models. Primary segments anchor institutional contract volumes.
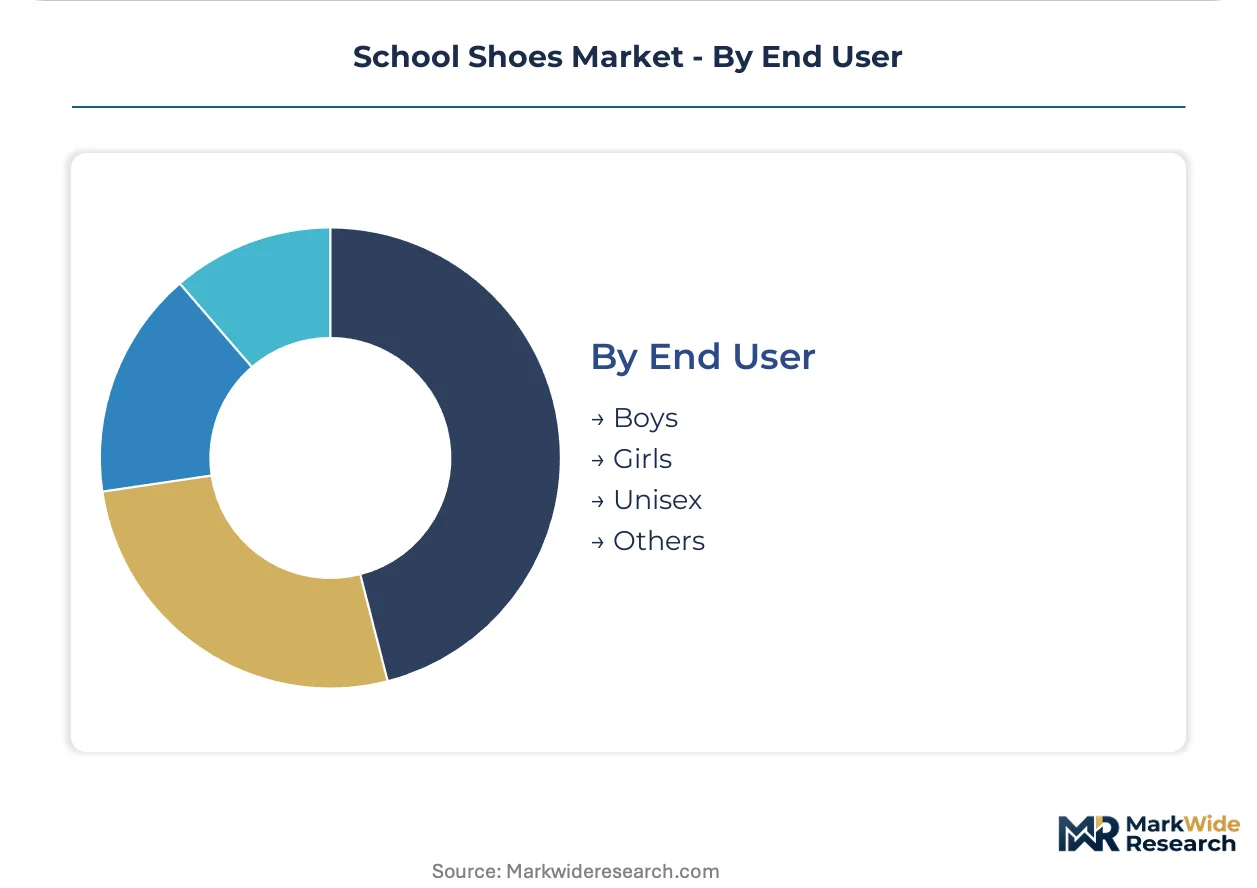
End User:
Gendered versus unisex positioning determines last design investment and inventory SKU proliferation across distribution channels.
- Unisex:Standardized lasts and neutral color palettes enabling bulk procurement efficiency for institutional buyers. India's state education departments consolidate vendor relationships around multi-year framework agreements specifying unisex constructions to simplify inventory management.
- Boys:Wider last dimensions with reinforced stress points in outsole flex zones.
- Girls:Narrower heel cups with alternative aesthetic detailing permitted under uniform code variations.
- Others:Specialized sizing and inclusive design parameters emerging in select private school segments.
Unisex constructions dominate tender-based procurement. Gendered differentiation persists in retail-family channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale contrasts with India's procurement-driven demand expansion, while European regulatory stringency and Middle Eastern institutional investment create divergent competitive environments across major markets.
China
Domestic consumption and export manufacturing dominate activity, with SAMR's GB 30585-2014 enforcement limiting phthalates and heavy metals in children's footwear. Wenling and Quanzhou industrial clusters in Zhejiang and Fujian provinces supply over sixty percent of global school shoe volume, concentrating production equipment and skilled labor in these coastal manufacturing hubs.
India
Government school enrollment under the Right to Education Act generates bulk tender demand for durable, low-cost footwear. BIS certification mandates for domestically sold products elevate quality barriers for imports while favoring manufacturers with regional distribution networks. Gujarat, Maharashtra, and Karnataka state procurement portals standardize technical specifications through reverse-auction systems.
Germany
Premium private and parochial school segments prioritize supply chain transparency and chemical compliance. ECHA REACH Annex XVII restrictions on chromium VI in leather tanning force tannery suppliers toward vegetable and synthetic alternatives. Bavarian and North Rhine-Westphalian finishing houses retool wet-blue processing lines to meet substance limitations for European-bound exports.
United States
Retail-family channels dominate procurement, with subscription-based replacement programs capturing lifetime value through automated size progression. Physical education mandates in public school systems sustain versatile sneaker demand across combined classroom and athletic use. Southeast and Southwest regions concentrate population growth driving replacement velocity in preschool through primary age brackets.
United Arab Emirates
Private school chains and institutional investors consolidate vendor relationships around multi-year framework agreements with performance guarantees. Dubai and Abu Dhabi education authorities standardize uniform specifications across expanding international school networks. Bulk procurement clients prioritize RFID-enabled inventory tracking for distribution monitoring and automated reorder triggers.
School Shoes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with volume concentration in Asian production clusters and premium positioning in European compliance-certified tiers. The vendor base organizes around three strategic archetypes: scale-driven OEM exporters serving institutional tenders, orthopedic-focused specialists capturing parent-paid premiums, and vertically integrated leather processors navigating REACH reformulation costs. Capacity expansion and certification portfolio diversification constitute the dominant competitive moves as multi-jurisdiction compliance demands redundant testing investments.
Among Chinese manufacturing specialists, Wenling Wofeng Shoes Co., Ltd. and Quanzhou Qirun Trading Co., Ltd. occupy positions exemplifying the scale-driven OEM archetype, while HYD Shoes represents orthopedic-compliant specialization for younger age brackets. These entities anchor the competitive structure without exhaustive market coverage, as regional trading companies and unlisted fabricators complete the supply base.
| Leading Market Players |
|---|
| Wenling Wofeng Shoes Co., Ltd. |
| Quanzhou Qirun Trading Co., Ltd. |
| HYD Shoes |
| Foshan Wise Import & Export Co., Ltd. |
| Zhejiang Miyue Shoes Co., Ltd. |
| Chengdu Cofida Leather Products Co., Ltd. |
| Cangnan Hongtu Trading Co., Ltd. |
| Quanzhou Bestway Import and Export Co., Ltd. |
| Xiamen Elletop Import and Export Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Thermoplastic polyurethane and synthetic rubber compound costs cascade from petrochemical feedstock volatility through three distinct pricing tiers for school footwear. India's BIS certification mandate elevates compliance expenses for economy-grade synthetic constructions, while EU REACH restrictions on chromium VI tanning push premium leather lines toward vegetable-based alternatives that absorb reformulation overhead.
Pricing Analysis
Capacity additions in Wenling and Quanzhou industrial clusters are reshaping price floors for economy-grade school footwear across Asian export markets. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European-bound exports from BIS-compliant Indian domestic tenders and unbranded bulk institutional contracts. Price differentiation hinges on certification grade and volume scale, with state-level tender systems in India commanding lowest unit economics. Pricing pressure stems from petrochemical input volatility, compressing margins on mid-tier synthetic constructions where pass-through capacity meets elastic demand. Family purchasers in preschool segments exhibit lowest price sensitivity, prioritizing orthopedic-compliant features, while government procurement officers in India's state education departments drive hardest bargain terms.
Supply Chain Analysis
Skilled pattern engineering labor availability constrains rapid product iteration in Zhejiang and Fujian manufacturing clusters, where aging technical workforces face limited replacement pipelines. Supply concentrates in China, India, and Vietnam, with over sixty percent of global volume originating from Wenling and Quanzhou industrial hubs. Raw material dependencies center on thermoplastic polyurethane pellets, natural rubber latex, and chrome-tanned leather hides from Australian and Brazilian tanneries. Single-source vulnerability runs through concentrated coastal manufacturing geography exposed to weather and logistics disruption. Distribution runs through regional trading companies serving institutional tenders, direct-to-family subscription platforms, and specialty orthopedic retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's SAMR enforcement of GB 30585-2014 and India's BIS certification mandate continuously elevate compliance barriers that filter supplier qualification pools.
For Market Incumbents: Anticipate synthetic material substitution acceleration by reformulating rubber compounds toward bio-based thermoplastic polyurethanes ahead of stricter GB standards evolution. Backward integration into captive testing facilities defends margin position against multi-jurisdiction certification overlap that extends rival product development cycles. Capacity consolidation around RFID-enabled inventory tracking systems captures multi-year framework agreement preference from Middle Eastern private school chains and Indian state education departments. For New Entrants and Emerging Players: Capture subscription replacement model white space in preschool through primary age brackets across Southeast Asian urban centers, where rapid foot growth outpaces traditional retail refresh cycles. Target EU REACH-compliant export positioning for German and Dutch private school segments where supply chain transparency commands measurable price premiums. Deploy 3D-printed midsole technology as differentiated go-to-market angle for customized orthopedic constructions at batch-size-one economics. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction compliance demands redundant testing investments that strain unlisted fabricator balance sheets. Five-to-ten year viability favors manufacturers with diversified certification portfolios spanning GB standards, BIS mandates, and REACH Annex XVII restrictions. Acquisition target archetype: regional trading companies with established state tender relationships in Gujarat, Maharashtra, and Karnataka. Signal to watch: Indian state procurement portal standardization accelerating vendor relationship concentration around framework agreements with performance guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Diversification | Multi-jurisdiction compliance with GB standards, BIS mandates, and REACH Annex XVII unlocks tender access across China, India, and EU markets. |
| Subscription Replacement Platform Launch | Direct-to-family automated size progression captures lifetime value in preschool segments with highest replacement velocity. |
| RFID-Enabled Inventory Integration | Embedded tracking tags align with Dubai and Abu Dhabi education authority uniform management system requirements. |
| Bio-Based Material Transition | Water-based adhesives and vegetable-tanned alternatives anticipate SAMR enforcement tightening on phthalates and chromium VI. |
| 3D-Printed Midsole Modularization | Selective laser sintering enables customized orthopedic geometries at previously unattainable cost points for European specialist segments. |
Research Methodology
Coverage spans China, India, Germany, the United States, and the United Arab Emirates, with primary inputs from each market informing demand-side validation. Factory managers in Wenling and Quanzhou industrial clusters, procurement officers at Indian state education departments, regulatory affairs specialists navigating SAMR and ECHA frameworks, brand managers at European private school uniform suppliers, and orthopedic podiatrists advising on juvenile foot development specifications contributed structured interviews. Secondary validation drew from customs and trade databases, BIS certification registries, ECHA substance restriction filings, and SEC disclosures from footwear manufacturing entities. Bottom-up unit economics triangulated against top-down market sizing across product type, material, age group, and end user segmentation dimensions.
Granularity-level modeling operated at country-regulation-product intersection points, with volume and value outputs reflecting segment-specific growth trajectory assumptions across the analysis window. Product type splits modeled sneakers, loafers, ankle boots, and sandals separately. Material tiers captured synthetic, leather, canvas, and rubber constructions with distinct certification pathway economics. Age group progression incorporated replacement velocity differentials between preschool, primary, secondary, and tertiary brackets. End user segmentation distinguished institutional tender dynamics from family retail purchasing patterns. CAGRs derived from historical enrollment data, uniform policy tightening trajectories, and regulatory implementation timelines without year-specific anchoring. Forecast inputs included government school enrollment projections under India's Right to Education Act and REACH Annex XVII restriction evolution patterns.
Underlying measurement precision varies by segment; preschool subscription replacement models and Indian state tender volumes carry tighter precision than fragmented unbranded fabricator supply in secondary age brackets. Forecasts reflect assumptions regarding regulatory enforcement consistency, petrochemical input price bands, and uniform policy adoption rates across private and parochial school networks. Material substitution velocity, multi-jurisdiction certification harmonization progress, and bulk procurement framework agreement penetration constitute specific risk factors that could revise trajectory assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Asia-Pacific Jeans Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Asia-Pacific Lingerie Market