
 Gymnastic Leotards Market | 2026-2036
Gymnastic Leotards Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastic Leotards Market Analytics
Southeast Asian manufacturing capacity is fragmenting as Vietnam and Indonesia add cut-and-sew facilities for stretch-performance apparel. GK Elite leverages vertical control over sublimation printing to sustain premium positioning in North American competitive circuits. Quatro Gymnastics anchors its European presence through specialized fits calibrated to British and Dutch national team specifications. Destira differentiates via direct-to-consumer customization platforms that bypass traditional wholesale gymnastics retail channels.
Gymnastic leotards are form-fitting, high-elongation garments engineered from nylon-spandex blends with 12-20% elastane content to permit unrestricted range of motion during aerial and floor routines, manufactured through flatlock seaming and dye-sublimation printing to eliminate surface friction against apparatus. Competitive leotards command the highest margin pool due to FIG compliance requirements and national federation procurement standards, while custom leotards represent the fastest-growing segment as club-level programs adopt individualized designs for team identity. Spandex-dominant material formulations lead volume production, though polyester blends are gaining share in training-day applications for enhanced moisture management.
Consumer Product Safety Commission guidelines govern flammability and small-part attachment standards for children's gymnastics apparel in the United States, while OEKO-TEX Standard 100 certification shapes European import acceptance for skin-contact textiles. China's GB 18401 national textile safety standard mandates formaldehyde and pH limits for domestic youth athletic wear distribution. Stakeholders must monitor evolving chemical restriction schedules across multiple jurisdictions to preempt compliance-driven reformulation costs.
Market Dynamics
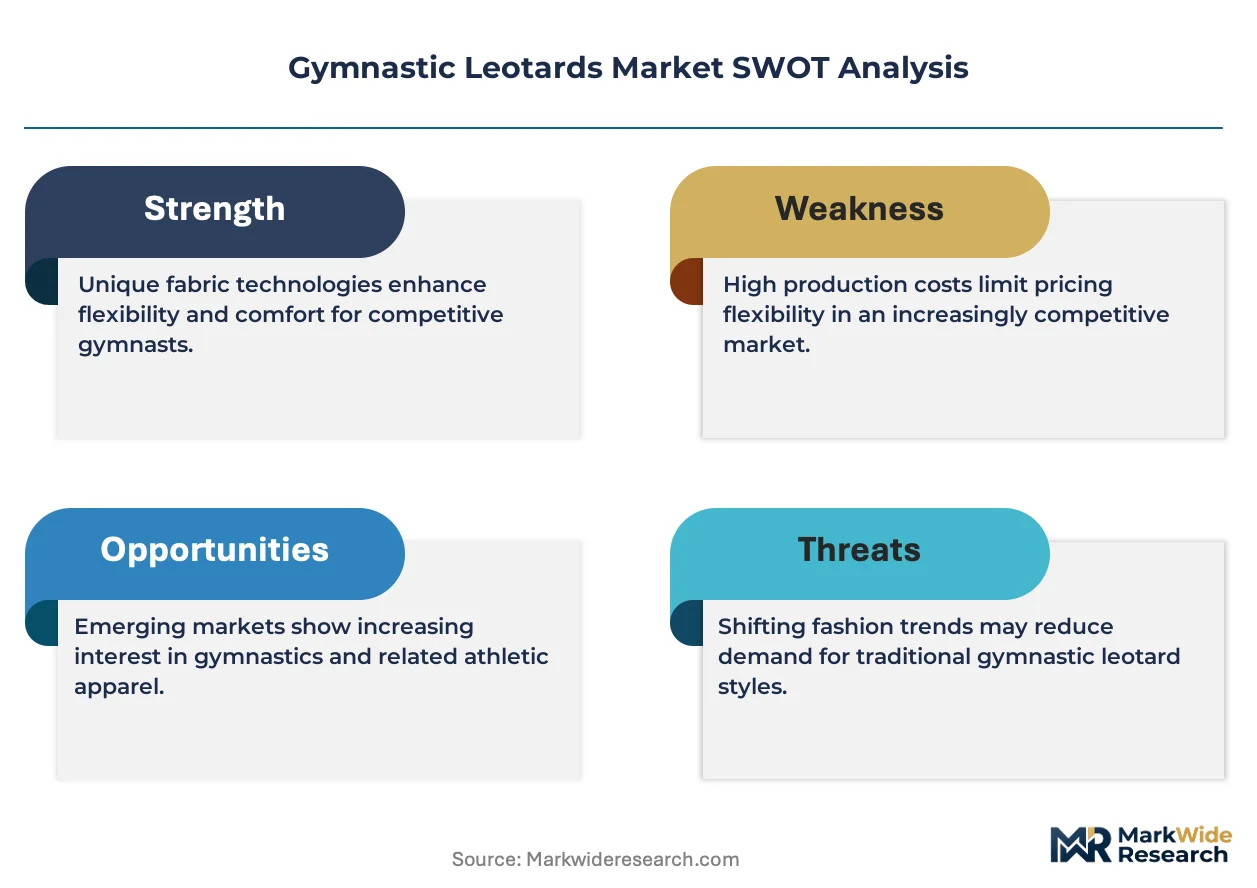
REACH compliance in the European Union is forcing elastane and dye reformulations across the entire supply base, compressing margins for mid-tier manufacturers while creating certification premiums for compliant suppliers.
Growth Catalysts
- Youth competitive pipelines:United States club gymnastics programs are expanding enrollment cohorts that require standardized performance apparel for sanctioned events.
- Provincial academy procurement:China's state-funded sports academies mandate bulk purchases of FIG-compliant uniforms for national team development tracks.
- Sublimation printing maturation:Digital dye-sublimation technology is reducing minimum order quantities for custom designs, enabling club-level personalization at scale.
Market Restraints
- Elastane cost volatility:Spandex feedstock prices fluctuate with crude oil derivatives, squeezing margin predictability for nylon-spandex blend manufacturers.
- Southeast Asian concentration risk:Cut-and-sew capacity fragmentation across Vietnam and Indonesia creates quality inconsistency and lead-time unpredictability.
- Formaldehyde restriction friction:China's GB 18401 standard mandates pH and chemical limits that require costly testing protocols for domestic distribution.
Strategic Opportunities
- Direct-to-consumer channels:Customization platforms bypass traditional wholesale gymnastics retail, capturing margin from club-level team orders.
- Moisture-management training segments:Polyester blend formulations for practice-day applications address unmet performance needs outside competition contexts.
- EU Green Deal alignment:Circular textile initiatives create first-mover advantage for recycled elastane sourcing in European competitive circuits.
Industry Challenges
- Flatlock seaming technician scarcity:Specialized stitch operators for high-elongation performance apparel command wage premiums and limit production scaling.
- Multi-jurisdiction certification timelines:Simultaneous OEKO-TEX, REACH, and CPSC compliance creates extended product development cycles.
- Legacy wholesale channel dependency:Traditional gymnastics specialty retailers resist inventory risk on custom-designed SKUs, constraining new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastic Leotards Market |
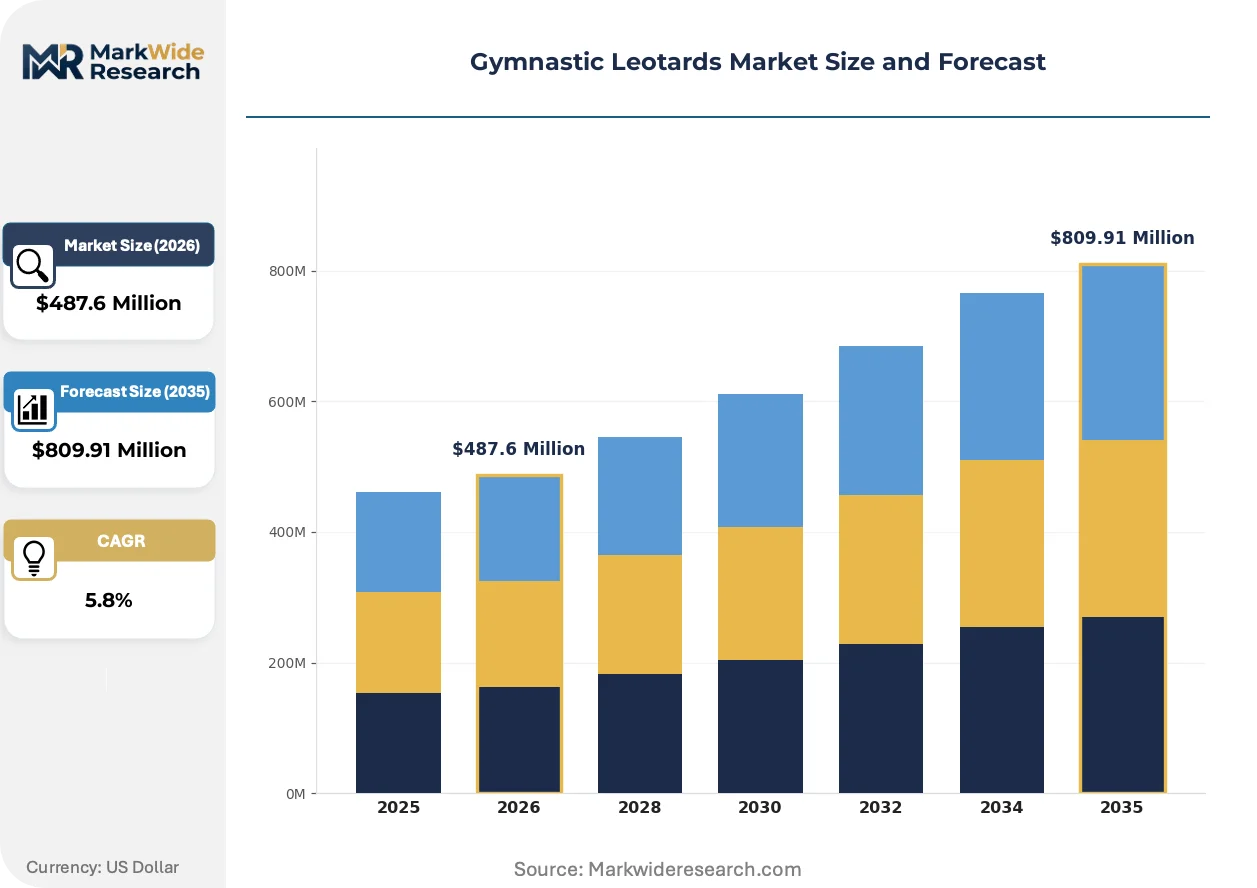
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Competitive Leotards, Training Leotards, Custom Leotards, Dance Leotards Material: Spandex, Nylon, Cotton, Polyester Age Group: Children, Teens, Adults, Professionals Design: Long Sleeve, Short Sleeve, Sleeveless, Open Back |
| Companies Covered | Goodworth Sports, Quatro Gymnastics, Snowflake Designs, Sylvia P, Destira, K-Bee Leotards, Joystream, Iron Cross Gymnastics Wear, GK Elite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastic Leotards Market Evolving Landscape
Digital workflows are compressing design-to-delivery cycles while regulatory chemistry restrictions and channel disintermediation reshape competitive positioning across price tiers.
3D body scanning and parametric pattern software is digitizing fit customization for elite competitive leotards. National federations and top-tier clubs are adopting these tools to reduce alteration cycles and minimize apparel-related deductions at FIG events. This compression of the specification process is digitizing traditional made-to-measure workflows that previously required multiple physical fittings.
REACH Annex XVII restrictions on azo dyes and nickel-releasing components are tightening chemical safety verification for skin-contact athletic textiles. European import authorities now require third-party testing documentation for elastane content and dye fastness, elevating compliance costs for non-vertically integrated suppliers. Competitive leotard segments bear the heaviest burden, as national federation procurement standards mandate full certification stacks.
Club-level programs are consolidating purchasing decisions through direct platform relationships rather than regional specialty retailers. This disintermediation shifts margin capture toward manufacturers with in-house design tools and short-run production capabilities. The United States exhibits the most pronounced channel migration, as youth competitive programs prioritize team identity differentiation over retail brand affiliation.
Gymnastic Leotards Market Segmentation
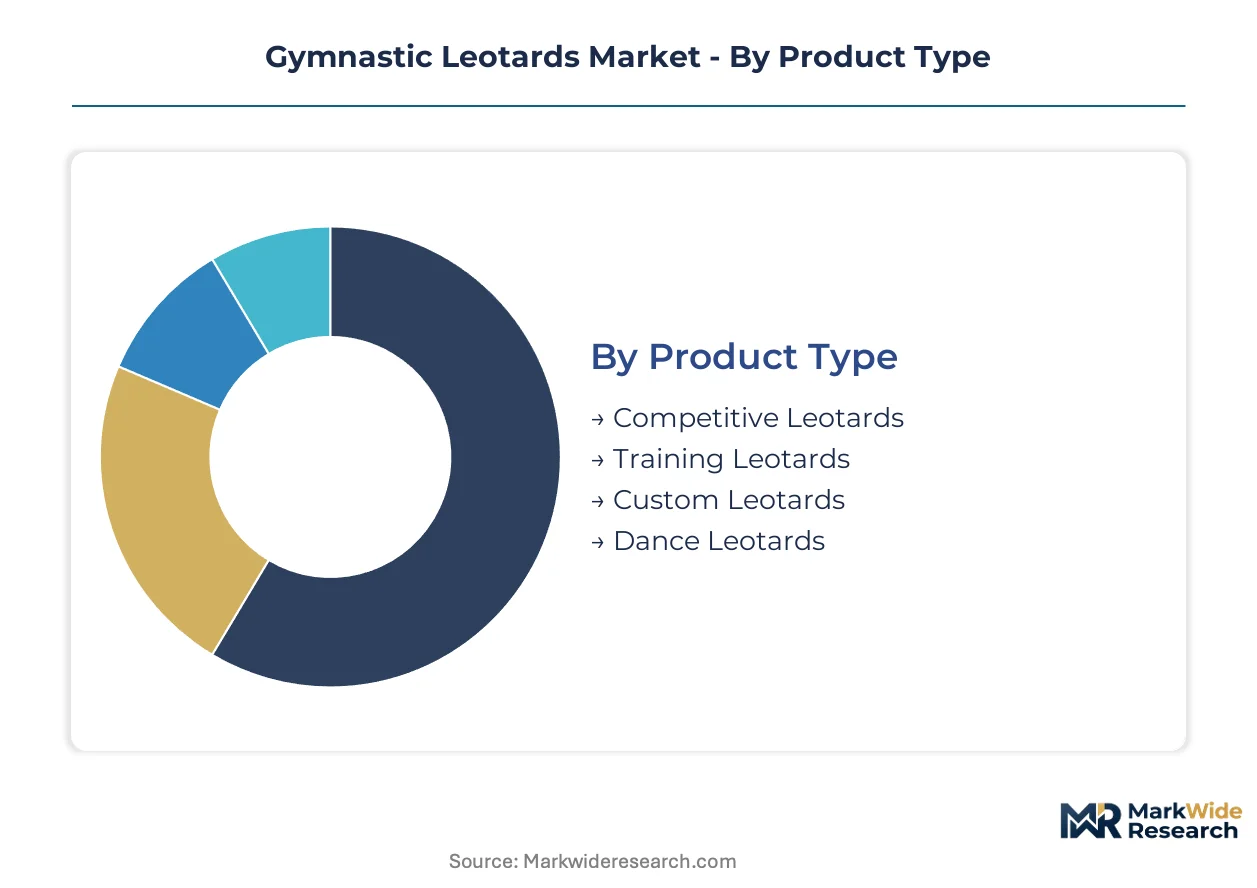
Gymnastic leotards segment across performance tier, material science, and demographic specification, with each dimension carrying distinct margin profiles and compliance burdens. Manufacturers calibrate production workflows to the technical demands of competition-grade apparel versus practice-day alternatives.
Product Type:
Mature competitive formats coexist with emerging customization platforms that compress design-to-delivery cycles.
- Competitive Leotards:FIG-compliant garments with 12-20% elastane content and dye-sublimation printing meet national federation procurement standards. China's provincial sports academies mandate bulk purchases for state-funded training centers, creating concentrated demand clusters.
- Custom Leotards:Digital sublimation workflows enable club-level personalization at reduced minimum order quantities. United States youth programs drive adoption through direct-to-consumer platforms that bypass traditional wholesale gymnastics retail channels.
- Training Leotards:Practice-day garments prioritize durability over aesthetic specification for daily academy use.
- Dance Leotards:Cross-over recreational apparel serves studio fitness segments with lower technical performance thresholds.
Competitive leotards retain volume leadership; custom leotards hold the steepest expansion curve.
Material:
Cost tier stratification separates premium elastane formulations from economy cotton alternatives.
- Spandex:Nylon-spandex blends with 12-20% elastane content dominate high-elongation performance applications. REACH compliance in the European Union forces costly reformulations of spandex feedstock derivatives, compressing margins for mid-tier suppliers.
- Polyester:Moisture-wicking blends gain share in training-day segments where perspiration management outweighs compression requirements. China's GB 18401 standard mandates pH and formaldehyde testing for domestic youth athletic wear distribution.
- Nylon:Base fiber for competitive-grade stretch construction with superior dye affinity.
- Cotton:Natural fiber relegated to beginner recreational segments with minimal technical specification.
Spandex retains volume leadership; polyester holds the steepest expansion curve.
Age Group:
Application intensity varies from recreational enrollment pipelines to elite professional procurement.
- Children:Entry-level competitive programs in the United States expand enrollment cohorts requiring CPSC-compliant flammability standards and small-part attachment verification.
- Teens:Club-level competitors drive custom design adoption for team identity differentiation at sanctioned events.
- Adults:Recreational fitness practitioners generate steady replacement demand with lower performance specifications.
- Professionals:National team athletes require made-to-measure calibration with 3D body scanning and parametric pattern software.
Children's segments retain volume leadership; teens hold the steepest expansion curve.
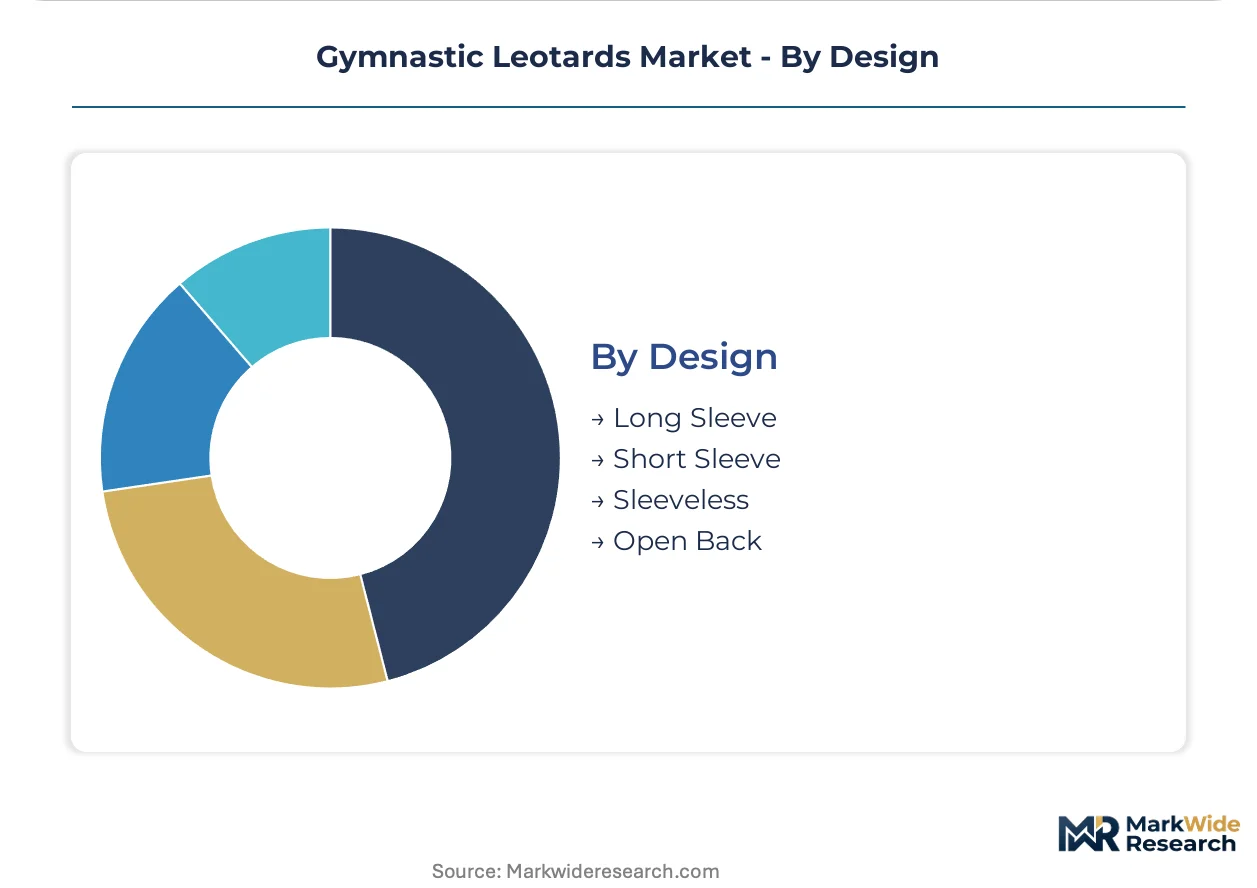
Design:
Customer type preferences split between federation-mandated coverage standards and club-level aesthetic differentiation.
- Long Sleeve:Full-coverage competitive formats preferred for apparatus events requiring maximum skin protection. FIG technical regulations govern sleeve length and torso coverage for international competition eligibility.
- Sleeveless:Streamlined cuts reduce fabric weight and eliminate shoulder seam friction during aerial rotations. Warm-weather training applications in Southeast Asian manufacturing regions favor this configuration for comfort.
- Short Sleeve:Intermediate coverage balancing mobility with modesty requirements for youth academy environments.
- Open Back:Aesthetic differentiation for exhibition and floor routines with specialized strap configurations.
Long sleeve retains volume leadership; sleeveless holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cut-and-sew capacity for stretch-performance apparel concentrates in Vietnam and Indonesia, though demand-side procurement patterns diverge sharply across regulatory jurisdictions. Each national market imposes distinct compliance burdens that reshape supplier economics and channel structures.
United States
Youth competitive gymnastics programs expand enrollment pipelines requiring CPSC-compliant flammability standards and small-part attachment verification. The Consumer Product Safety Commission governs children's athletic apparel safety through mandatory testing protocols. California and Texas host the densest clusters of club-level programs driving custom design adoption through direct-to-consumer platforms.
China
Provincial sports academies mandate bulk purchases of FIG-compliant uniforms for state-funded national team development tracks. GB 18401 national textile safety standards enforce formaldehyde and pH limits for domestic youth athletic wear distribution. Guangdong and Zhejiang manufacturing zones supply standardized competition garments to academy procurement officers under centralized purchasing agreements.
Germany
REACH Annex XVII restrictions on azo dyes and nickel-releasing components elevate compliance costs for elastane and dye formulations. ECHA enforcement requires third-party testing documentation for skin-contact athletic textiles entering European distribution. Bavaria and Baden-Württemberg host specialized technical textile suppliers serving federation procurement standards.
United Kingdom
British and Dutch national team specifications drive demand for specialized fit calibrations in competitive circuits. OEKO-TEX Standard 100 certification shapes import acceptance thresholds for performance apparel. Greater Manchester and West Midlands manufacturing bases maintain dye-sublimation capacity for club-level customization orders.
Australia
Recreational fitness practitioners generate steady replacement demand with lower performance specifications than competitive segments. TGA guidelines intersect with state-level consumer protection frameworks for children's athletic wear. Melbourne and Sydney metropolitan areas concentrate retail distribution for entry-level enrollment programs.
Gymnastic Leotards Market Competitive Landscape
Vertical specialists and direct-to-consumer platforms split the market into contrasting margin-capture models. Mid-tier manufacturers face compression from regulatory compliance costs while premium positioning sustains through captive production capabilities. Three archetypes dominate: federation-aligned suppliers, customization-platform operators, and training-day commodity producers. Capacity expansion and channel disintermediation represent the dominant competitive vectors reshaping supplier relationships.
Within the federation-aligned tier, GK Elite and Quatro Gymnastics exemplify positioning through technical specification adherence. Destira occupies a position representing the direct-to-consumer archetype, anchoring the platform-based customization segment. Sylvia P sits within the specialist tier serving national team procurement channels. These three entities collectively illustrate the strategic divergence between premium technical compliance and margin-capturing channel innovation.
| Leading Market Players |
|---|
| Goodworth Sports |
| Quatro Gymnastics |
| Snowflake Designs |
| Sylvia P |
| Destira |
| K-Bee Leotards |
| Joystream |
| Iron Cross Gymnastics Wear |
| GK Elite |
| Others |
Value Network & Pricing Analysis
Vietnam and Indonesia cut-and-sew capacity concentration for stretch-performance apparel feeds directly into margin capture at the customization-platform tier, where direct-to-consumer channels bypass wholesale gymnastics retail markups entirely.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European competitive circuits, separating OEKO-TEX-certified premium suppliers from uncertified mid-tier competitors facing reformulation cost compression. Three-tier pricing structure across premium, standard, and economy levels reflects certification stack depth, with national federation procurement standards anchoring the top tier. Pricing pressure stems from elastane feedstock volatility tied to crude oil derivatives, squeezing nylon-spandex blend manufacturers. Club-level youth programs in the United States exhibit highest price sensitivity, while FIG-compliant national team procurement shows lowest sensitivity due to compliance mandate rigidity.
Supply Chain Analysis
Extended payment terms from Southeast Asian cut-and-sew facilities to dye-sublimation equipment suppliers finance working capital cycles across the apparel value chain. Manufacturing capacity concentrates in Vietnam, Indonesia, and China's Guangdong province, drawing from elastane feedstock derivatives, nylon base fiber, and azo dye formulations. Single-source vulnerability runs through spandex feedstock suppliers exposed to petrochemical price swings. Distribution runs through direct-to-consumer platforms for custom orders and federation procurement channels for competitive-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with digital sublimation workflows compressing minimum order quantities and enabling club-level personalization at previously unattainable scale.
For Market Incumbents: Entrench certification premiums through captive OEKO-TEX and REACH compliance infrastructure, insulating margin pools from mid-tier reformulation cost compression. Add flatlock seaming technician training capacity in Vietnam and Indonesia manufacturing zones to preempt wage-premium scarcity. Defend against direct-to-consumer platform disintermediation by integrating in-house design tools for club-level team orders.
For New Entrants and Emerging Players: Australian recreational fitness practitioners represent underpenetrated white-space with lower performance specifications and reduced compliance burden than competitive segments. Target moisture-management polyester blend formulations for practice-day applications outside FIG-mandated procurement channels. Launch through digital customization platforms bypassing legacy wholesale gymnastics retail resistance to custom-designed SKU inventory risk.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer platform operators possessing short-run production capabilities and in-house design tool infrastructure. Five-to-ten year viability hinges on channel disintermediation acceleration and regulatory compliance stack consolidation. Watch for REACH Annex XVII restriction expansion beyond azo dyes and nickel-releasing components as inflection signal for compliance-cost barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye-Sublimation Equipment | GK Elite's vertical control over sublimation printing sustains premium positioning in North American competitive circuits. |
| Direct-to-Consumer Platform Launch | Destira's customization platform captures margin from club-level team orders bypassing traditional wholesale gymnastics retail. |
| REACH Compliance Certification Investment | Quatro Gymnastics anchors European presence through specialized fits calibrated to British and Dutch national team specifications. |
| Flatlock Seaming Technician Training Program | Specialized stitch operator scarcity in Vietnam and Indonesia commands wage premiums that limit production scaling. |
| Recycled Elastane Sourcing Partnership | EU Green Deal circular textile initiatives create first-mover advantage for sustainable material positioning in European competitive circuits. |
Research Methodology
Desk research of customs records, federation procurement databases, and textile safety standard filings preceded structured interviews with gymnastics club program directors, apparel manufacturing plant managers, dye-sublimation equipment suppliers, and national federation procurement officers. Primary fieldwork combined with secondary validation from OEKO-TEX certification registries, REACH Annex XVII restriction schedules, and CPSC flammability testing protocols. Bottom-up volume estimates from club-level enrollment pipelines and provincial academy procurement figures triangulated against top-down market sizing from trade flow analysis.
The forecast framework held crude oil derivative pricing within observed volatility bands while varying elastane content specifications and digital sublimation adoption rates across the projection horizon. Segmentation dimensions modeled include performance tier, material science formulation, age group specification, and design configuration. CAGRs derived from enrollment pipeline expansion in United States youth programs and state-funded procurement growth in China's provincial sports academies. Industry-specific inputs incorporated FIG compliance requirement evolution and flatlock seaming technician wage trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier manufacturers would shift outcomes through certification premium compression. Macroeconomic deviation in petrochemical feedstock markets, regulatory expansion of chemical restriction schedules, or technological displacement of dye-sublimation workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Women's Sports and Swimwear Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Luxury Fashion Market