
 Alpaca Apparel and Accessories Market | 2026-2036
Alpaca Apparel and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Alpaca Apparel and Accessories Market Analytics
The EU Green Deal's textile sustainability requirements is pivoting European fashion brands toward certified natural fibers. Alpaca Direct, LLC leverages its direct-to-consumer platform to control pricing and storytelling around Peruvian sourcing. Malabrigo Yarn specializes in hand-dyed, small-batch colorways that command premium positioning among knitters. Cascade Yarns dominates volume distribution through North American specialty retail channels with consistent, scalable production.
Alpaca apparel and accessories encompass garments and complementary items manufactured from the hollow-core fiber of Lama pacos, a camelid species native to the South American Andes. The fiber's thermal conductivity measures approximately 0.05 W/m·K, comparable to merino wool but with lower surface friction, making it suitable for next-to-skin applications without the prickle factor associated with coarser wools. Coats and sweaters represent the established revenue base where Baby Alpaca commands the highest price premiums due to its sub-22 micron fineness. Online retail channels are expanding fastest among distribution segments as direct-to-consumer brands bypass wholesale markups, though specialty stores retain margin concentration through experiential merchandising and hands-on fiber education.
REACH in Europe and the EU Green Deal's extended producer responsibility framework impose chemical disclosure and end-of-life accountability on textile imports. The USDA's organic certification and Peru's own National Institute of Natural Fibers standards create a dual-compliance environment for exporters serving multiple jurisdictions. Stakeholders must monitor how emerging digital product passport requirements will alter traceability investments and supplier qualification timelines.
Market Dynamics
EU Green Deal textile sustainability mandates are compressing supplier qualification timelines as brands scramble for certified fiber sources before extended producer responsibility rules take full effect. REACH chemical disclosure requirements and emerging digital product passport standards now determine which Peruvian cooperatives can access European luxury accounts.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandatory fiber traceability and end-of-life accountability push brands toward certified alpaca sourcing with verifiable chain-of-custody documentation.
- Peru's Puno Region Concentration:Artisan cooperatives and commercial processors in this high-altitude zone control premium Baby Alpaca fiber supply, creating scarcity value for international buyers.
- Hollow-Core Thermal Performance:The fiber's 0.05 W/m·K conductivity enables next-to-skin applications without merino wool's prickle factor, expanding addressable garment categories.
Market Restraints
- Input Cost Volatility:Shearing labor costs in the Peruvian Andes fluctuate with seasonal migration patterns and currency instability, compressing processor margins.
- Supply Concentration Risk:Over 80% of global alpaca fiber originates from Peru's southern highlands, exposing buyers to climate disruption and political instability in a single-source geography.
- REACH Compliance Friction:European chemical disclosure requirements for imported textiles create documentation burdens that exclude smaller cooperatives lacking laboratory testing capacity.
Strategic Opportunities
- Digital Product Passport Mandates:EU requirements for garment-level traceability create first-mover advantage for brands investing in blockchain-verified fiber provenance systems.
- Direct-to-Consumer Channel Expansion:Online retail bypasses wholesale markups and enables margin capture through controlled storytelling around Peruvian sourcing authenticity.
- Specialty Store Experiential Merchandising:Hands-on fiber education and tactile sampling in curated retail environments defend premium pricing against commodity wool alternatives.
Industry Challenges
- Artisan Skill Succession:Traditional hand-shearing and fiber-sorting expertise in Puno region cooperatives faces attrition as younger generations migrate to urban centers.
- Dual-Certification Complexity:Exporters must simultaneously satisfy USDA organic standards and Peru's National Institute of Natural Fibers requirements, extending qualification timelines.
- Legacy Dyehouse Integration:Small-batch hand-dyeing operations struggle to scale color consistency for commercial orders while maintaining artisan positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpaca Apparel and Accessories Market |
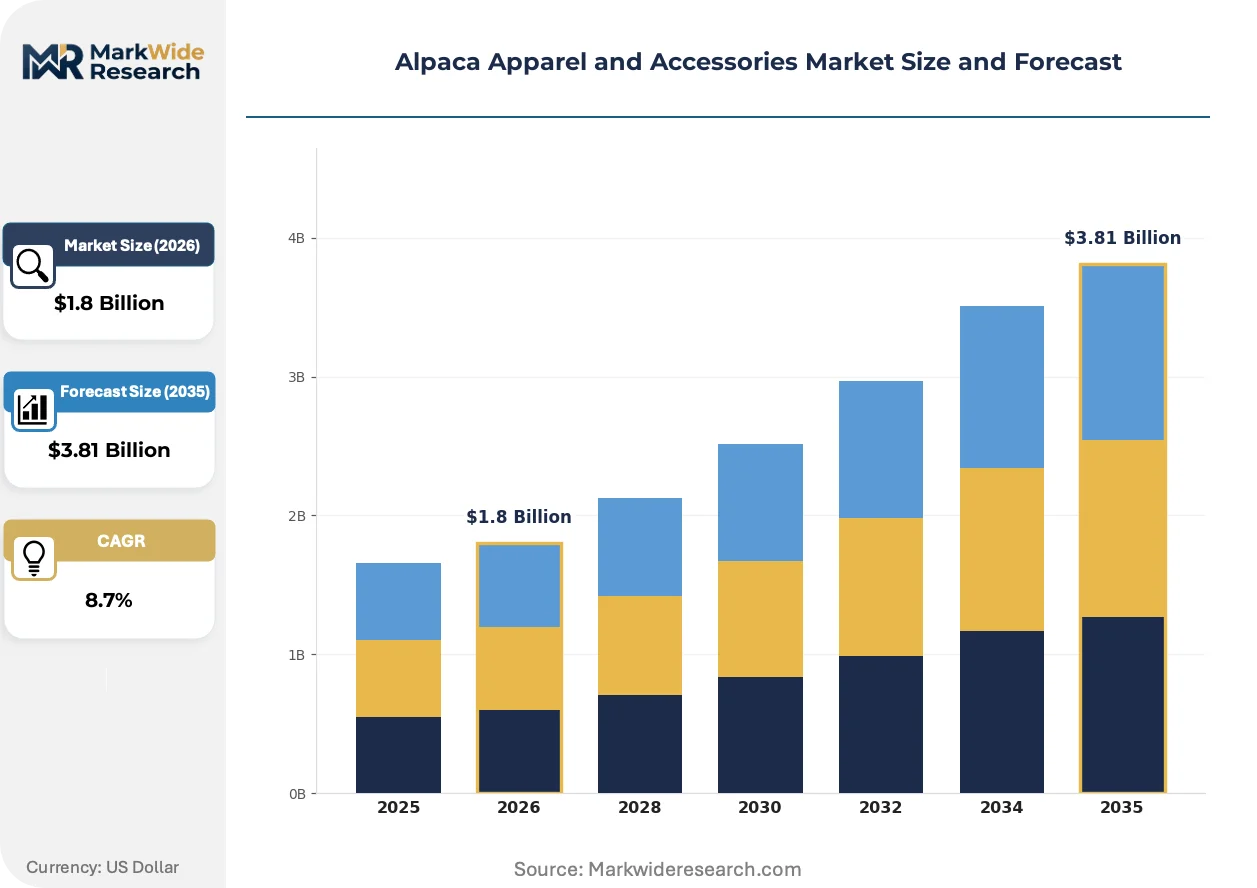
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Sweaters, Scarves, Socks End User: Retail Consumers, Wholesale Buyers, Designers, Fashion Brands Material Grade: Baby Alpaca, Suri, Huacaya, Mixed Fiber Distribution Channel: Online Retail, Specialty Stores, Marketplaces, Direct Sales |
| Companies Covered | The Natural Fibre Company, Alpaca Direct, LLC, Lion Brand Yarn, Plymouth Yarn Company, Inc., Mary Maxim Inc, Cascade Yarns, Malabrigo Yarn, Fil Katia, Berroco, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpaca Apparel and Accessories Market Evolving Landscape
Blockchain-enabled fiber traceability is compressing the information gap between Andean shearing floors and European retail floors. Three convergent forces are restructuring how value flows through the supply chain.
Blockchain-based provenance tracking is decentralizing fiber authentication away from centralized certifying bodies toward immutable, cooperative-level record-keeping. Luxury knitwear brands are piloting these systems fastest, embedding QR-linked shearing coordinates into garment labels. This compression of verification steps eliminates intermediary documentation costs while exposing supply chain weak points.
REACH chemical disclosure thresholds are tightening import requirements for all natural fiber textiles entering European customs territories. ECHA's expanded substance restriction lists now capture residual processing chemicals previously exempt for artisan-scale production. Peruvian export cooperatives with in-house laboratory partnerships are securing preferential supplier status with compliance-ready documentation packages.
Specialty retail buyers are consolidating purchase authority through direct mill relationships that bypass traditional wholesale distributors. North American yarn shops and boutique apparel buyers now negotiate fiber lots directly with Puno-based processors, compressing margin layers. This disintermediation is most visible in hand-dyeing segments where colorway exclusivity drives store-level traffic.
Alpaca Apparel and Accessories Market Segmentation
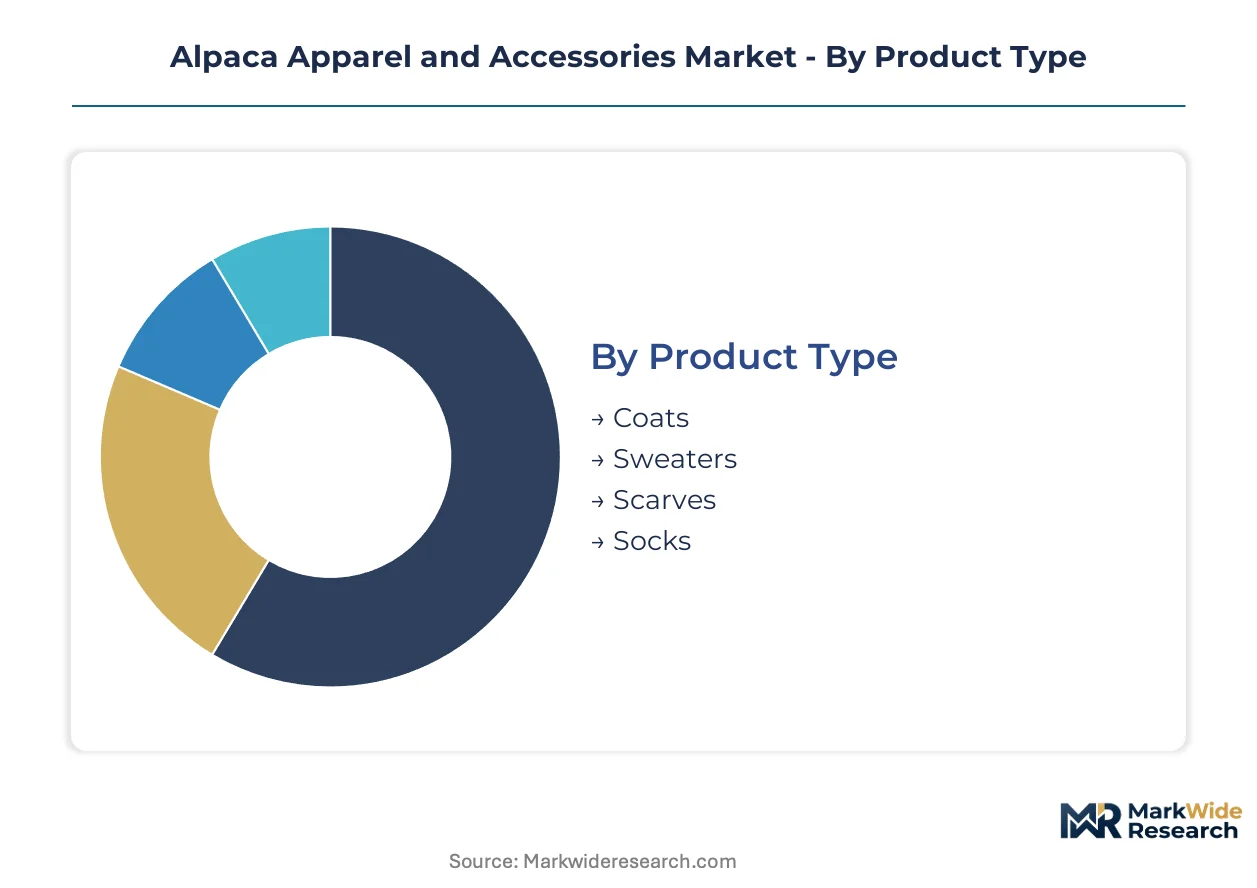
Alpaca fiber's hollow-core thermal properties and micron-grade fineness variations create natural tier boundaries that certification requirements amplify. Segmentation in this market tracks how processing standards, distribution economics, and end-use performance specifications reshape supplier qualification and margin capture across each category.
Product Type:
REACH chemical disclosure thresholds and EU Green Deal extended producer responsibility rules impose distinct documentation burdens on each garment category based on dye complexity and fiber blend ratios.
- Coats:Heavy-gauge outerwear construction utilizes Baby Alpaca's sub-22 micron fineness for thermal retention without bulk. European luxury houses concentrate procurement here, driven by digital product passport mandates requiring blockchain-verified fiber provenance for high-value garments.
- Sweaters:Mid-weight knitwear represents the volume anchor where Peruvian Puno cooperatives compete on fineness grading and color consistency. REACH compliance costs disproportionately squeeze smaller processors serving this segment, favoring cooperatives with in-house laboratory partnerships.
- Scarves:Accessory-grade items with lower dye complexity face reduced ECHA substance restriction documentation. Hand-dyeing specialists capture premium positioning through small-batch colorway exclusivity.
- Socks:Blended constructions with nylon or elastane trigger additional chemical disclosure requirements for synthetic components. Mass-market brands prioritize Huacaya fiber for cost-efficient durability in high-friction applications.
Leading the category by volume: Sweaters. Growing fastest: Coats.
End User:
Procurement authority concentrates differently across buyer types, with certification readiness and volume scale determining access to Peru's premium fiber lots.
- Retail Consumers:Direct-to-consumer platforms bypass wholesale markups while controlling Peruvian sourcing narratives. Online channels expand fastest as brands invest in traceability storytelling that justifies premium pricing.
- Wholesale Buyers:North American specialty yarn shops and boutique apparel buyers now negotiate fiber lots directly with Puno processors, compressing traditional distributor margins through disintermediation.
- Designers:Small-batch creators prioritize hand-dyed Suri fiber for luster-driven luxury positioning. Limited scale exempts many from full REACH documentation, though EU market access requires basic chemical disclosure.
- Fashion Brands:Extended producer responsibility frameworks force systematic chain-of-custody investments. Compliance-ready cooperatives with dual USDA-Peru National Institute of Natural Fibers certification secure preferential supplier status.
Procurement scale peaks with Fashion Brands. Margin capture improves fastest for Retail Consumers.
Material Grade:
Fiber diameter and crimp structure create performance tiers that processing standards and end-use specifications reinforce through pricing stratification.
- Baby Alpaca:Sub-22 micron fineness enables next-to-skin applications without prickle factor. Scarce supply from high-altitude Puno herds commands steepest premiums in European luxury accounts.
- Suri:Straight, lustrous fiber structure suits formal accessories and high-sheen outerwear. Limited population share—roughly 10% of Peruvian herds—creates natural supply constraint.
- Huacaya:Crimped, elastic fiber dominates commercial volume with scalable processing characteristics. Standard-grade applications in socks and base layers prioritize durability over fineness premiums.
- Mixed Fiber:Blends with merino or cashmere alter thermal conductivity and dye uptake profiles. REACH documentation complexity increases with synthetic or cross-species fiber content.
Premium positioning concentrates in Baby Alpaca. Volume leadership sits with Huacaya.
Distribution Channel:
Channel economics determine how traceability investments translate into margin capture and customer education opportunities.
- Online Retail:Direct-to-consumer platforms control pricing and fiber provenance storytelling without wholesale markup compression. Digital product passport integration enables QR-linked shearing coordinates that verify Peruvian authenticity.
- Specialty Stores:Hands-on fiber education and tactile sampling defend premium positioning against commodity wool alternatives. North American yarn shops consolidate purchase authority through direct mill relationships.
- Marketplaces:Aggregated demand platforms favor standardized Huacaya grades with consistent supply and reduced certification documentation. Price transparency intensifies margin pressure on undifferentiated listings.
- Direct Sales:Artisan cooperative networks and trunk-show models bypass retail overhead for maximum producer margin retention. Limited scale constrains growth despite favorable economics.
Volume flows through Online Retail. Margin defense succeeds best in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru produces over 80% of global alpaca fiber while Europe and North America absorb premium-grade output through luxury fashion channels. This production-consumption divide shapes trade flows, regulatory compliance burdens, and supplier qualification investments across three continents.
Peru
Puno region herders supply 95% of Baby Alpaca fiber through artisan cooperatives and commercial processors. Peru's National Institute of Natural Fibers certification mandates micron testing and chain-of-custody documentation for export eligibility. Arequipa houses the country's largest fiber processing cluster, where compliance-ready laboratories serve European luxury accounts.
United States
Direct-to-consumer brands and specialty yarn shops drive demand for traceable Peruvian fiber with verifiable sourcing stories. USDA organic certification creates dual-compliance requirements alongside Peruvian standards for importers serving premium segments. Colorado and Oregon host the densest concentrations of domestic alpaca ranches, though commercial scale remains limited.
Germany
ECHA's REACH chemical disclosure thresholds filter import access for Peruvian cooperatives lacking laboratory testing partnerships. Berlin and Munich-based sustainable fashion labels pioneer blockchain-verified fiber provenance systems ahead of EU digital product passport mandates. Extended producer responsibility frameworks under the EU Green Deal accelerate certified natural fiber procurement timelines.
United Kingdom
London luxury houses concentrate Baby Alpaca procurement for outerwear collections requiring sub-22 micron fineness. Post-Brexit regulatory divergence complicates REACH-aligned chemical disclosure for UK-bound Peruvian exports. Yorkshire's historic textile mills process smaller fiber lots for heritage knitwear brands emphasizing artisan provenance.
France
Paris-based couture houses command steepest premiums for Suri fiber in formal accessories and high-sheen garments. ANSM and CNIL oversight intersects with EU Green Deal textile sustainability requirements for import documentation. Lyon maintains specialized dyehouse capacity for small-batch luxury colorways with reduced synthetic chemical profiles.
Alpaca Apparel and Accessories Market Competitive Landscape
The competitive structure tilts toward vertically integrated Peruvian processors with dual-certification capacity and North American direct-to-consumer platforms controlling pricing and provenance storytelling. Three archetypes dominate: Puno-based cooperatives with in-house laboratory partnerships, specialty yarn distributors with direct mill relationships, and digital-native apparel brands bypassing wholesale markups. Capacity expansion and blockchain traceability investments constitute the dominant competitive moves as EU compliance deadlines compress supplier qualification timelines.
Among North American specialty distributors, Cascade Yarns and Malabrigo Yarn exemplify contrasting scale strategies—volume distribution through retail channels versus hand-dyed small-batch positioning. Alpaca Direct, LLC anchors the direct-to-consumer archetype with controlled Peruvian sourcing narratives. These three occupy positions spanning mass-market accessibility, artisan premium positioning, and digital-native margin capture.
| Leading Market Players |
|---|
| The Natural Fibre Company |
| Alpaca Direct, LLC |
| Lion Brand Yarn |
| Plymouth Yarn Company, Inc. |
| Mary Maxim Inc |
| Cascade Yarns |
| Malabrigo Yarn |
| Fil Katia |
| Berroco, Inc. |
| Others |
Value Network & Pricing Analysis
European luxury fashion houses concentrate procurement authority for Baby Alpaca fiber, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects fineness grading and certification status. Their compliance-ready documentation requirements compress margin capture for smaller Peruvian cooperatives while rewarding dual-certified processors with preferential supplier terms.
Pricing Analysis
Margin tightening in standard-grade Huacaya reflects mass-market brand consolidation around cost-efficient durability specifications. Pricing stratifies across premium, standard, and economy tiers based on micron fineness and REACH compliance readiness, with Baby Alpaca commanding steepest premiums for sub-22 micron certification. Cost-down pressure on undifferentiated fiber accelerates because marketplace aggregators intensify price transparency. Mass-market apparel brands exhibit highest price sensitivity, while Paris couture houses tolerate premium escalation for verified Suri fiber provenance.
Supply Chain Analysis
Seasonal migration patterns among Andean shearing crews in Peru, Bolivia, and Ecuador compress available labor pools during peak harvest windows. Raw material flows draw from high-altitude Puno herds, Arequipa processing clusters, and emerging Ecuadorian commercial ranches. Single-source vulnerability concentrates risk in Peru's southern highlands where climate disruption threatens fiber yield consistency. Distribution runs through direct-to-consumer platforms and specialty retail channels that bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Baby Alpaca fiber scarcity from high-altitude Puno herds props pricing across all tiers, creating a supply-constrained market where capacity expansion faces geographic and climatic barriers.
For Market Incumbents: To counter REACH documentation burdens that exclude smaller competitors, secure in-house laboratory partnerships in Arequipa and deepen backward integration into high-altitude herding cooperatives. Channel control through direct mill relationships with North American specialty retailers defends margin capture against marketplace disintermediation. For New Entrants and Emerging Players: The gap between premium Baby Alpaca and economy-grade Huacaya pricing opens white-space opportunity in mid-tier certified fiber for direct-to-consumer knitwear brands. Target online retail channels with blockchain-verified provenance storytelling that justifies margin premiums. Hand-dyed small-batch positioning among specialty yarn shops offers the most penetrable entry vector. For Investors and Strategic Acquirers: Distressed-cycle entries favor dual-certified Peruvian processors with existing EU laboratory partnerships and established luxury brand relationships. Long-term viability across the analysis window hinges on traceability infrastructure investments ahead of digital product passport mandates. Watch blockchain verification adoption rates among Berlin and Munich sustainable fashion labels as inflection indicators for compliance-ready supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Verified Provenance System | EU digital product passport mandates reward first-movers with preferential luxury brand access. |
| Direct-to-Consumer Channel Launch | Bypassing wholesale markups captures margin through controlled Peruvian sourcing narratives. |
| In-House Laboratory Partnership | REACH-ready documentation secures European customs clearance and luxury account eligibility. |
| Artisan Cooperative Backward Integration | Captive supply of Baby Alpaca fiber defends fineness grading consistency against climate yield volatility. |
| Specialty Retail Distribution Expansion | Hands-on fiber education in curated environments defends premium positioning against commodity wool alternatives. |
Research Methodology
Document review covered Peruvian National Institute of Natural Fibers certification records, ECHA REACH substance restriction updates, and EU Green Deal textile sustainability guidance, complemented by interviews with fiber processing executives, artisan cooperative managers, luxury brand procurement directors, and specialty retail buyers. Secondary validation drew from customs trade databases, SEC filings of North American apparel distributors, and USDA organic certification registries. Bottom-up fiber volume estimates from Puno region cooperatives were triangulated against top-down luxury brand procurement disclosures.
Cross-referencing historical price premiums for micron-grade fineness against panel input from European fashion house sourcing executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, distribution channel, and end-user procurement authority. CAGRs were derived from fiber volume trajectories and pricing elasticity assumptions. Forecast inputs incorporated shearing labor cost trends in the Peruvian Andes and blockchain traceability adoption curves among compliance-ready cooperatives.
Underlying measurement precision varies by segment; Baby Alpaca fiber volumes carry tighter precision than blended fiber estimates due to concentrated Puno region sourcing. Forecasts reflect documented assumptions about EU extended producer responsibility implementation timelines and digital product passport technical standards. Material deviation in Andean climate patterns, Peruvian political stability, or ECHA substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Men's Underwear Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Headwear Market