
 Global Adaptive Clothing Market | 2026-2036
Global Adaptive Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Clothing Market Analysis
Aftermarket service revenue for garment modification and repair is fragmenting across specialized providers and in-house care operations. Silvert's Adaptive Clothing & Footwear leverages its direct-to-consumer platform to sustain recurring orders from institutional buyers. Tommy Hilfiger anchors its position through fashion-forward adaptive lines that compete with mainstream apparel aesthetics. Nike differentiates via performance-oriented adaptive sportswear that dominates athletic rehabilitation channels.
Adaptive clothing denotes garments engineered with modified closures, adjusted seam placements, and alternative fastening systems to accommodate limited dexterity, mobility restrictions, or sensory sensitivities. Manufacturers employ magnetic fasteners, side-opening constructions, and seated-wear pattern grading to enable independent dressing or assisted caregiver protocols. Shirts and pants lead volume throughput due to universal daily wear necessity, while outerwear commands premium positioning through weatherproof fabric integration and thermal regulation engineering. The seniors demographic anchors current revenue pools, though children with disabilities represents the fastest-expanding segment as early-intervention programs expand coverage.
The FDA oversees textile biocompatibility for medical-adjacent garments, while ISO 10993 standards govern skin-contact material safety across export markets. The EU Green Deal's textile sustainability mandates are forcing fiber sourcing disclosures and circular design requirements. REACH chemical restrictions limit certain dye and finish applications, elevating compliance costs for low-volume producers. Stakeholders must monitor evolving reimbursement classifications that could shift adaptive clothing from discretionary retail toward prescription-funded channels.
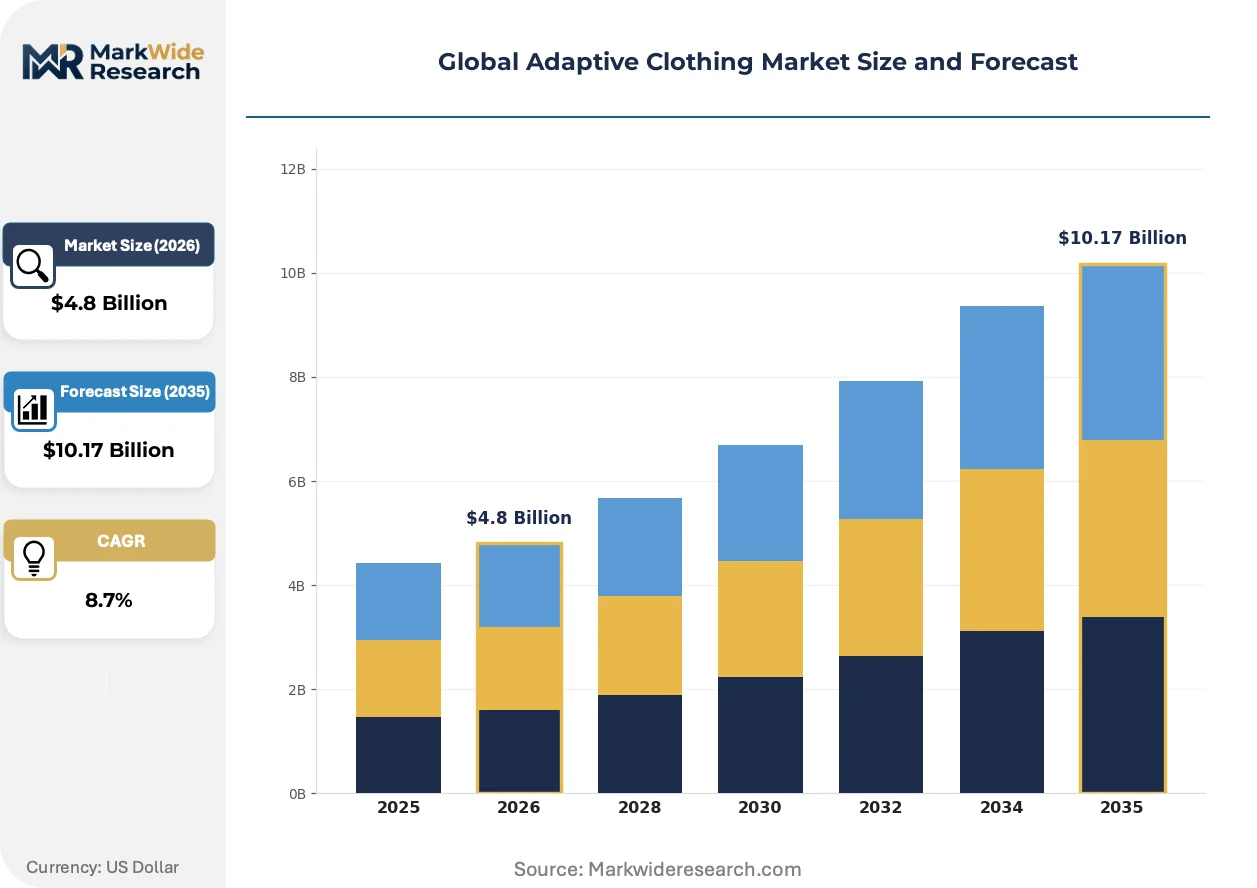
Market Dynamics
Reimbursement pathway evolution is compressing adaptive clothing from discretionary retail toward prescription-funded channels, forcing manufacturers to restructure go-to-market strategies around clinical validation requirements and payer credentialing protocols.
Growth Catalysts
- Japan's senior care procurement mandates:METI guidelines for long-term care facilities prioritize magnetic-closure garments in institutional purchasing frameworks, accelerating standardized adoption across 47 prefectures.
- REACH textile chemical restrictions:ECHA enforcement of Substances of Very High Concern limits conventional dye applications, creating competitive openings for compliant adaptive fabric specialists.
- 3D body scanning integration:Rehabilitation centers in Germany deploy digital measurement protocols to reduce garment return rates and accelerate custom-fit production cycles.
Market Restraints
- Specialized fastener supply concentration:Rare-earth magnet sourcing clusters in China's Inner Mongolia region, exposing magnetic-closure garment producers to export quota volatility and price spikes.
- EU Green Deal circularity mandates:CSRD disclosure requirements and extended producer responsibility schemes impose compliance burdens disproportionately on low-volume adaptive clothing manufacturers.
- Technical limitation in seated-wear grading:Pattern engineering for wheelchair users requires specialized anthropometric databases that remain underdeveloped outside North American and Western European populations.
Strategic Opportunities
- Brazil's underpenetrated rehabilitation network:ANVISA's expanding medical device classification framework creates pathway for adaptive sportswear entry into physical therapy channels.
- Telehealth-integrated fitting services:Remote consultation platforms enable direct-to-patient sizing protocols that bypass traditional retail distribution infrastructure.
- South Korea's disability employment quotas:MFDS alignment with corporate accessibility mandates drives B2B uniform procurement for workers requiring dressing accommodations.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Skin-contact material testing protocols delay product launches by 8-14 months for medical-adjacent garment categories.
- Pattern engineering talent scarcity:Specialized grading expertise for mobility-limitation accommodations concentrates among aging technical designers in Italy and France.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Clothing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Pants, Dresses, Outerwear Target Demographic: Children, Adults, Seniors, Individuals with Disabilities Feature: Easy Closure, Comfort Fit, Adjustable Size, Breathable Fabric Distribution Channel: Online Stores, Retail Outlets, Specialty Stores, Nonprofit Organizations |
| Companies Covered | Silvert’s Adaptive Clothing & Footwear, Tommy Hilfiger (PVH Corp.), IZ Adaptive, Nike Inc., Buck & Buck, MagnaReady, Creation Confort, NBZ Apparel International, Adaptations by Adrian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Clothing Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are converging to reshape competitive positioning, with sustainability credentials and clinical validation becoming inseparable from product differentiation rather than peripheral marketing claims.
Shape-memory alloy fasteners are collapsing the distinction between adaptive and mainstream apparel aesthetics by enabling invisible closure mechanisms that satisfy both accessibility requirements and fashion-forward design standards. Premium rehabilitation centers in Switzerland and the Netherlands adopt these components at accelerated procurement cycles. The technology is collapsing price premiums previously commanded by specialized adaptive labels as conventional brands integrate equivalent functionality.
The EU Green Deal's textile sustainability mandates force fiber provenance documentation and circular design certification across all export-bound production. ECHA enforcement of restricted substance lists elevates compliance costs for dye houses and finish applicators. Medical-adjacent garment categories face the steepest adaptation requirements as they must simultaneously satisfy REACH chemical limits and ISO 10993 biocompatibility protocols.
Institutional procurement consolidation is compressing vendor relationships as senior care networks in Japan and Germany centralize purchasing through specialized distributors. Direct-to-facility contracts displace fragmented individual caregiver purchases. This pattern is most visible in Japan's metropolitan prefectures where municipal procurement unions aggregate demand across multiple long-term care facilities.
Global Adaptive Clothing Market Segmentation
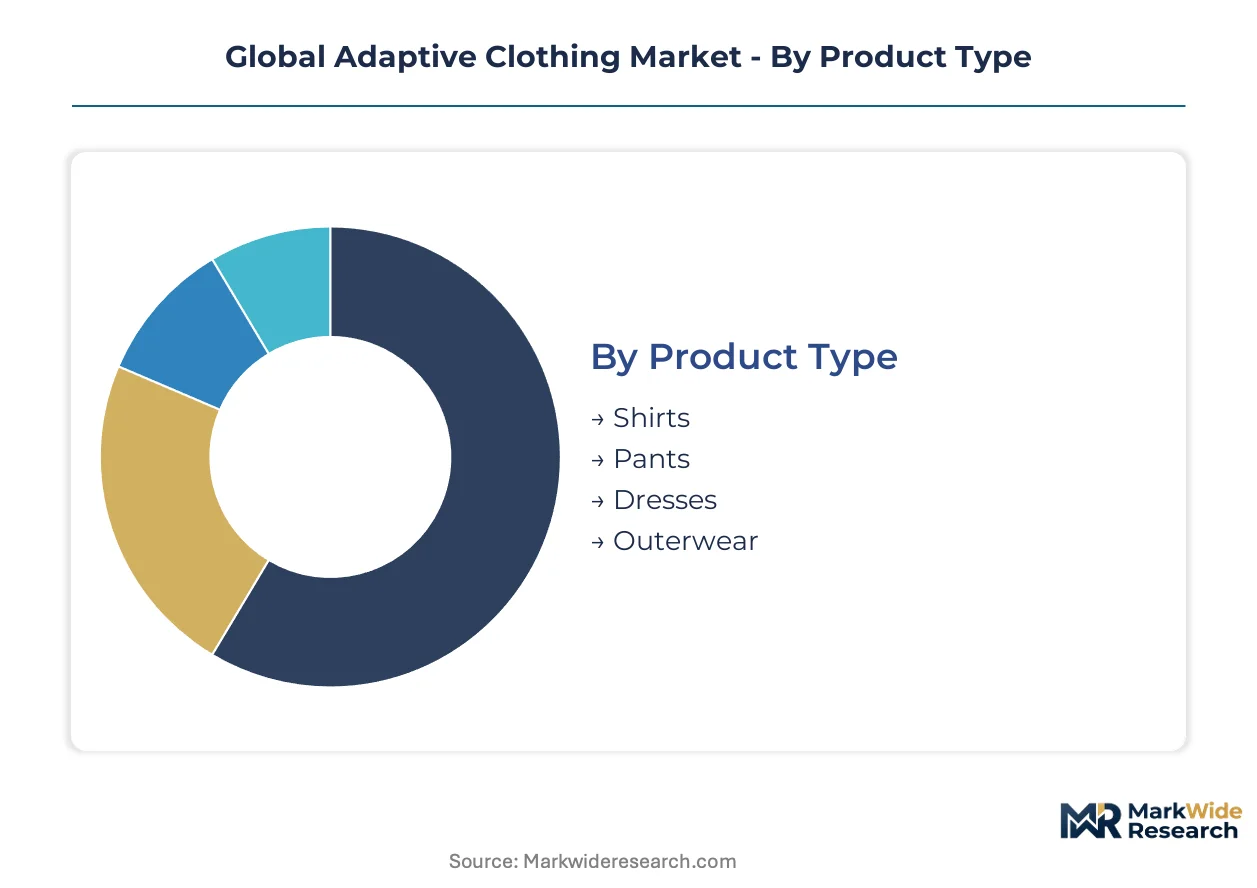
Adaptive clothing segmentation reveals how functional engineering intersects with demographic urgency and procurement channel evolution. Manufacturers must align product architecture with specific mobility limitations while navigating divergent reimbursement pathways across institutional and retail channels.
Product Type:
Mature daily-wear categories anchor procurement volumes while technical outerwear commands premium positioning through specialized fabric engineering.
- Shirts:Modified plackets with magnetic or Velcro closures replace conventional buttons; side-opening constructions accommodate seated dressing protocols. Demand concentrates in Japan's municipal long-term care networks where METI procurement guidelines mandate standardized adaptive uniforms across prefecture-level purchasing consortia.
- Pants:Elasticized waistbands with seated-wear grading adjust rise and crotch depth for wheelchair users; open-side seams enable caregiver-assisted changes. Germany's rehabilitation center networks deploy 3D body scanning to reduce return rates for custom-fit trousers, accelerating institutional procurement cycles.
- Dresses:Wrap constructions with magnetic waist closures simplify independent dressing for limited dexterity conditions.
- Outerwear:Weatherproof membranes with thermal regulation layers serve mobility-impaired users exposed to temperature sensitivity; REACH-compliant dye applications elevate compliance costs for European export markets.
Shirts retain volume leadership; outerwear holds the steepest expansion curve.
Target Demographic:
Volume distribution tilts toward aging populations while pediatric segments drive innovation investment through early-intervention program expansion.
- Children:Sensory-friendly seams and tagless constructions address autism spectrum and tactile processing disorders. Early-intervention coverage expansion in South Korea and Australia is accelerating specialized garment procurement through disability support schemes.
- Adults:Employment-focused adaptive workwear aligns with corporate accessibility mandates; MFDS-aligned procurement in South Korea drives B2B uniform contracts for workers requiring dressing accommodations.
- Seniors:Magnetic-closure daily wear dominates institutional purchasing frameworks. Japan's 47 prefectures aggregate demand through municipal procurement unions, compressing vendor relationships toward specialized distributors.
- Individuals with Disabilities:Condition-specific modifications span spinal cord injury, arthritis, and Parkinson's disease presentations; ISO 10993 biocompatibility certification delays product launches for skin-contact medical-adjacent categories.
Seniors retain volume leadership; children hold the steepest expansion curve.
Feature:
Functional priorities cluster around independence enablement versus caregiver assistance protocols, with material safety standards increasingly converging across both use cases.
- Easy Closure:Magnetic fasteners, hook-and-loop systems, and snap alternatives replace conventional buttons and zippers. Rare-earth magnet sourcing concentration in China's Inner Mongolia region exposes producers to export quota volatility and price spikes.
- Comfort Fit:Seamless constructions and flat-lock stitching reduce pressure points for seated users and sensory-sensitive wearers.
- Adjustable Size:Velcro waistbands and expandable side panels accommodate weight fluctuation from medication side effects or condition progression.
- Breathable Fabric:Moisture-wicking synthetics and organic cotton blends address thermoregulation challenges in neurological conditions; EU Green Deal fiber provenance documentation requirements elevate compliance burdens for low-volume producers.
Easy closure retains volume leadership; breathable fabric holds the steepest expansion curve.
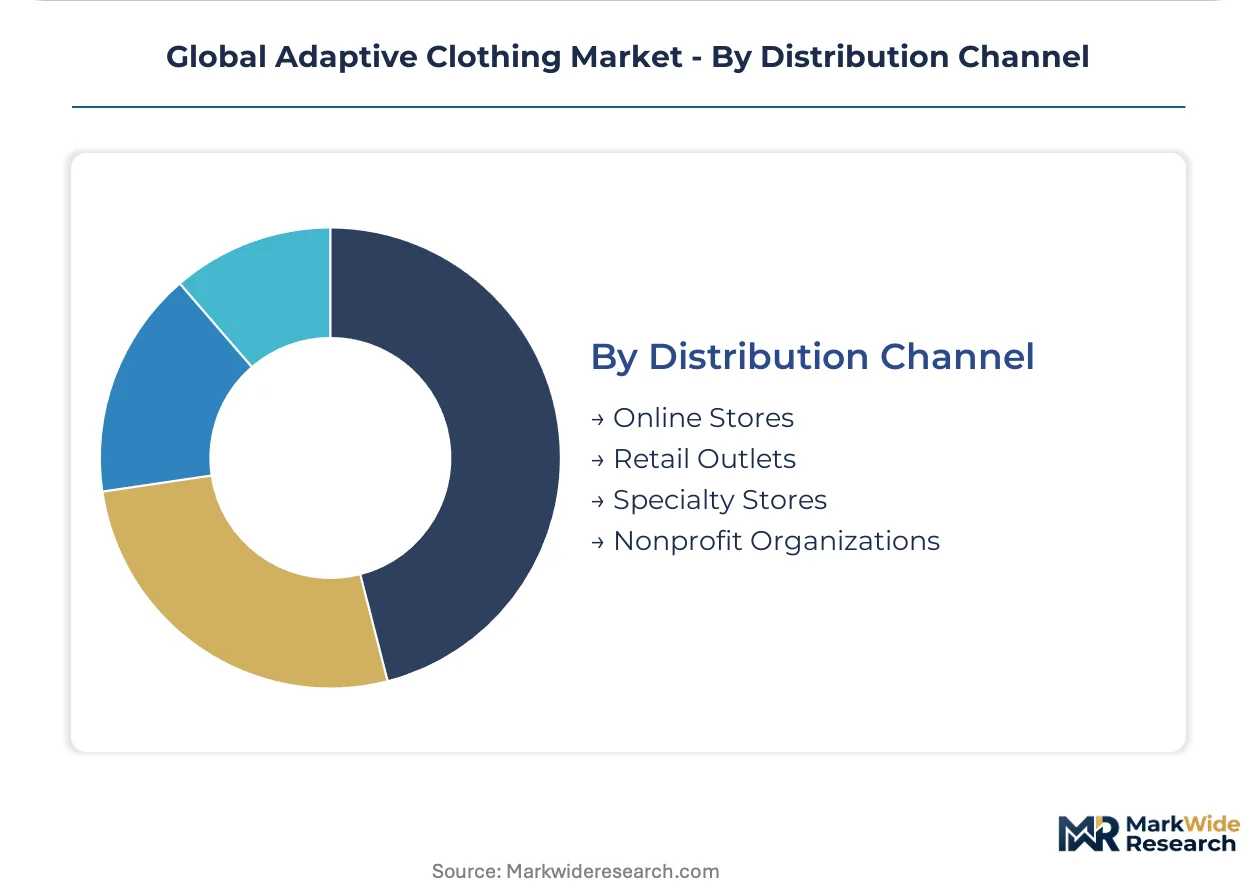
Distribution Channel:
Channel strategy fragments between direct-to-consumer platforms serving individual caregivers and centralized institutional procurement displacing fragmented purchasing.
- Online Stores:Direct-to-consumer platforms enable recurring subscription models and telehealth-integrated fitting services that bypass traditional retail infrastructure.
- Retail Outlets:Mainstream department store adaptive lines collapse price premiums through fashion-forward aesthetics competing with specialized labels.
- Specialty Stores:Medical supply retailers and rehabilitation equipment distributors serve prescription-funded channels requiring clinical validation documentation.
- Nonprofit Organizations:Donation-based distribution networks address affordability barriers for uninsured populations; reimbursement pathway evolution is compressing this channel as adaptive clothing shifts toward prescription-funded classification.
Online stores retain volume leadership; specialty stores hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity concentrates in institutional procurement channels where municipal purchasing unions negotiate volume discounts, while individual caregivers in private-pay markets absorb steeper premiums for specialized fit services.
United States
FDA textile biocompatibility standards elevate compliance costs for skin-contact garments entering medical-adjacent channels. The agency's medical device textile protocols force manufacturers to restructure fiber sourcing and finish applications. Rehabilitation centers in Florida and Arizona deploy telehealth-integrated fitting services to reduce return rates for custom-fit trousers.
Japan
METI procurement guidelines for long-term care facilities mandate magnetic-closure garments across 47 prefectures, compressing vendor relationships toward specialized distributors. Municipal purchasing unions in metropolitan prefectures aggregate demand across multiple facilities. Tokyo-based procurement consortia now standardize adaptive uniform specifications for institutional caregivers.
Germany
ECHA enforcement of REACH Substances of Very High Concern limits conventional dye applications, creating competitive openings for compliant fabric specialists. Rehabilitation center networks deploy 3D body scanning protocols to accelerate custom-fit production cycles. North Rhine-Westphalia hosts the densest concentration of technical pattern engineering talent for seated-wear grading.
South Korea
MFDS alignment with corporate disability employment quotas drives B2B uniform procurement for workers requiring dressing accommodations. Early-intervention program expansion accelerates specialized garment procurement through disability support schemes. Seoul Capital Area rehabilitation networks integrate digital measurement tools with national health insurance reimbursement pathways.
Brazil
ANVISA's expanding medical device classification framework creates entry pathways for adaptive sportswear into physical therapy channels. Price sensitivity in private-pay markets limits penetration outside insured rehabilitation networks. São Paulo's metropolitan health systems pilot prescription-funded adaptive clothing distribution through public hospital outpatient departments.
Global Adaptive Clothing Market Vendor Landscape
Capability concentration sits with specialized adaptive labels possessing technical pattern engineering expertise; scale advantage sits with mainstream apparel houses integrating accessibility features into existing manufacturing footprints. The market structures around three tiers: institutional procurement specialists serving senior care networks, fashion-forward adaptive lines competing on aesthetic parity, and performance-oriented sportswear dominating athletic rehabilitation channels. Dominant competitive moves include direct-to-consumer platform development bypassing traditional retail infrastructure and clinical validation investments qualifying products for prescription-funded reimbursement pathways.
Within the institutional procurement tier, Silvert's Adaptive Clothing & Footwear exemplifies direct-to-consumer platform strategy sustaining recurring orders from facility buyers. Tommy Hilfiger occupies a position representing fashion-forward adaptive lines that collapse price premiums through mainstream aesthetic competition. Nike anchors the performance-oriented segment with adaptive sportswear integrated into athletic rehabilitation channels.
| Leading Market Players |
|---|
| Silvert's Adaptive Clothing & Footwear |
| Tommy Hilfiger (PVH Corp.) |
| IZ Adaptive |
| Nike Inc. |
| Buck & Buck |
| MagnaReady |
| Creation Confort |
| NBZ Apparel International |
| Adaptations by Adrian |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Bangladesh's woven garment sector is compressing unit economics for adaptive clothing producers sourcing base textiles, forcing manufacturers to absorb margin erosion or migrate toward specialized knit suppliers with tighter capacity utilization and stronger pricing power.
Pricing Analysis
Aftermarket service revenue from garment modification and repair drives lifetime value across institutional procurement relationships. Three-tier pricing structure across premium, standard, and economy levels separates fashion-forward adaptive lines from medical-adjacent certified garments and basic utility wear. Cost compression in economy-tier magnetic-closure daily wear is intensifying because municipal purchasing unions in Japan aggregate volume demand. Individual caregivers in private-pay markets show lowest price sensitivity for custom-fit services.
Supply Chain Analysis
Export quota restrictions on rare-earth elements from China's Inner Mongolia region constrain magnetic fastener availability for adaptive closure systems. Manufacturing capacity clusters in Bangladesh, Vietnam, and India for base textile production, while specialized magnetic component finishing rests on Taiwanese and Japanese precision metalworking. Single-source vulnerability in rare-earth magnet sourcing exposes producers to supply disruption. Distribution runs through institutional procurement consortia and direct-to-consumer platforms serving individual caregivers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical pattern engineering expertise for seated-wear grading concentrates among aging specialists in Italy and France, creating a narrowing pipeline of talent capable of translating anthropometric data into production-ready patterns for wheelchair users.
For Market Incumbents: Harden ISO 10993 biocompatibility certification capabilities to defend institutional procurement relationships against emerging entrants lacking testing infrastructure. Deepen backward integration into magnetic fastener supply through captive relationships with rare-earth processors outside quota-restricted zones. Secure technical design talent through acquisition of Italian and French grading studios facing succession gaps. For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated rehabilitation network before ANVISA's medical device classification framework fully matures and incumbent certification advantages solidify. Target pediatric sensory-friendly segments in South Korea and Australia where early-intervention program expansion outpaces specialized supplier capacity. Deploy telehealth-integrated fitting services to bypass traditional retail distribution infrastructure and capture direct-to-patient relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutional procurement specialists serving Japan's municipal long-term care networks through multi-year facility contracts. Long-term viability hinges on clinical validation investments qualifying products for prescription-funded reimbursement pathways rather than discretionary retail positioning. Acquisition targets should demonstrate existing FDA or MFDS regulatory engagement. Monitor reimbursement classification shifts in major markets as inflection indicators for channel migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | ISO 10993 certification opens prescription-funded procurement channels in Japan and Germany. |
| Magnetic Fastener Supply Security | Captive rare-earth sourcing outside China's Inner Mongolia quota regime reduces price volatility exposure. |
| Telehealth Platform Integration | Remote fitting protocols bypass retail infrastructure and capture direct-to-patient recurring revenue. |
| Technical Talent Acquisition | Italian and French grading studio purchases secure scarce seated-wear pattern engineering capability. |
| Sustainability Certification | EU Green Deal fiber provenance documentation meets ECHA REACH compliance for European export markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and procurement records. Conversations with adaptive clothing designers, institutional purchasing managers at senior care facilities, rehabilitation center therapists, and magnetic fastener suppliers informed demand-side and supply-side dynamics. Secondary sources include FDA textile biocompatibility guidance documents, METI procurement guideline releases, ECHA REACH substance restriction updates, and municipal purchasing union contract disclosures. Bottom-up unit economics modeling triangulates against top-down market sizing from import-export statistics.
Forecast inputs span product type segmentation across shirts, pants, dresses, and outerwear; demographic splits across children, adults, seniors, and individuals with disabilities; feature categories including easy closure, comfort fit, adjustable size, and breathable fabric; and distribution channel dynamics across online stores, retail outlets, specialty stores, and nonprofit organizations. CAGRs derive from regression analysis of historical procurement volumes against projected institutional expansion and reimbursement pathway evolution. Industry-specific inputs include rare-earth magnet price indices and METI long-term care facility bed forecasts.
Stress conditions across rare-earth export quota volatility, REACH chemical restriction enforcement intensity, and reimbursement classification timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding institutional procurement consolidation rates and telehealth platform adoption curves. Material shifts in FDA medical device textile classification scope or EU Green Deal circularity mandate implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Ballet Pointe Shoes Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
North America E-Commerce Apparel Market