
 Asia Pacific Hats Market | 2026-2036
Asia Pacific Hats Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hats Market Outlook
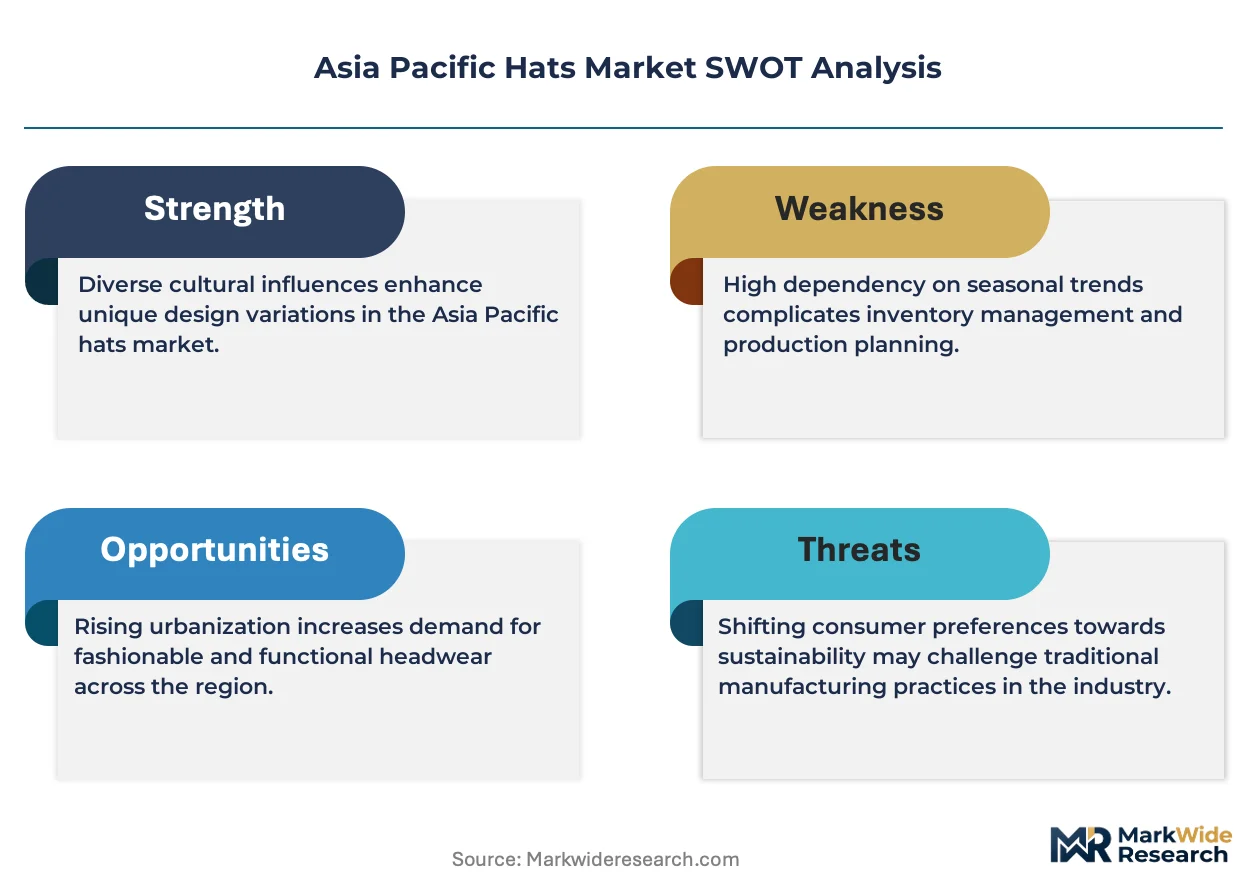
Asset-light licensing and third-party manufacturing partnerships are reshaping competitive entry in the Asia Pacific Hats Market, lowering capital barriers for brand operators without factory ownership. Nike, Inc. leverages its design-to-retail ecosystem to command premium positioning across multiple sales channels. Tan Thanh Dat Co., Ltd. anchors Vietnamese production capacity for regional private-label contracts. Zhangjiagang Huaxia Headgear Co., Ltd. specializes in synthetic fiber headwear for sports and outdoor segments.
Hats are head coverings constructed from woven, knitted, or molded materials with defined brim, crown, and closure specifications, designed for sun protection, thermal insulation, uniform compliance, or fashion expression. Baseball caps dominate volume through sports licensing and casual wear penetration, while beanies capture seasonal demand spikes in temperate North Asian climates. Straw material commands artisanal premium pricing in resort and heritage segments, whereas synthetic fiber competes on durability and moisture-wicking performance in athletic applications.
China's SAMR enforces GB textile standards that govern fiber content labeling and chemical safety for domestic hat sales, while India's BIS certification requirements for textile products create compliance checkpoints for cross-border suppliers. The EU AI Act's emerging supply-chain transparency mandates will eventually pressure Asia Pacific exporters serving European retail channels through indirect regulatory spillover. Stakeholders must monitor how digital product passport requirements and biodegradable material standards will redefine sourcing specifications and factory certification priorities across regional manufacturing hubs.
Market Dynamics
Labor cost arbitrage between Vietnamese factory zones and Chinese coastal provinces is redrawing procurement geography for branded headwear, as tariff engineering and GB standard compliance reshape supplier selection criteria across the region.
Growth Catalysts
- Outdoor recreation program expansion:Government-backed adventure tourism initiatives in New Zealand and Australia's national park systems are driving institutional procurement of UV-rated headwear for ranger uniforms and visitor services.
- Synthetic fiber performance innovation:Moisture-wicking polyester blends and recycled ocean plastic yarns are capturing athletic segment share from cotton canvas in marathon and cycling event merchandise.
- Vietnam-EU FTA tariff advantages:The EU-Vietnam Free Trade Agreement's phased duty elimination on textile articles is accelerating brand relocation of baseball cap production from China to Da Nang industrial zones.
Market Restraints
- GB 18401 textile safety compliance:China's SAMR enforcement of formaldehyde and pH limits in GB standards is forcing factory retooling costs that squeeze margin for small-batch exporters serving domestic e-commerce channels.
- Straw material supply concentration:Artisanal weaving clusters in Bangladesh and rural Philippines face climate-driven yield volatility that disrupts resort-wear production schedules and premium pricing stability.
- Polyester feedstock price linkage:Crude oil derivative costs for synthetic fiber production create margin compression that polyester-dominant suppliers cannot pass through to price-sensitive mass retail buyers.
Strategic Opportunities
- Digital product passport readiness:Early alignment with the EU's incoming supply-chain transparency mandates creates first-mover positioning for Vietnamese exporters serving European department store private-label programs.
- Biodegradable fiber conversion:PLA and hemp-blend material development opens premium positioning in Australia's eco-conscious outdoor retail channel, where biodegradable claims command shelf placement advantages.
- Live commerce integration:Douyin and Shopee Live streaming channels are collapsing traditional wholesale layers, enabling direct-to-consumer margin capture for design-forward domestic brands in tier-two Chinese cities.
Industry Challenges
- Technical pattern-making talent scarcity:Precision crown-block engineering for fitted cap production requires specialized skills concentrated in aging Guangdong technician pools that Vietnamese training programs have not yet replicated at scale.
- Dual certification timeline compression:Simultaneous pursuit of BIS textile labeling for India and GB compliance for China creates testing queue bottlenecks that delay seasonal collection launches by 6-10 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hats Market |
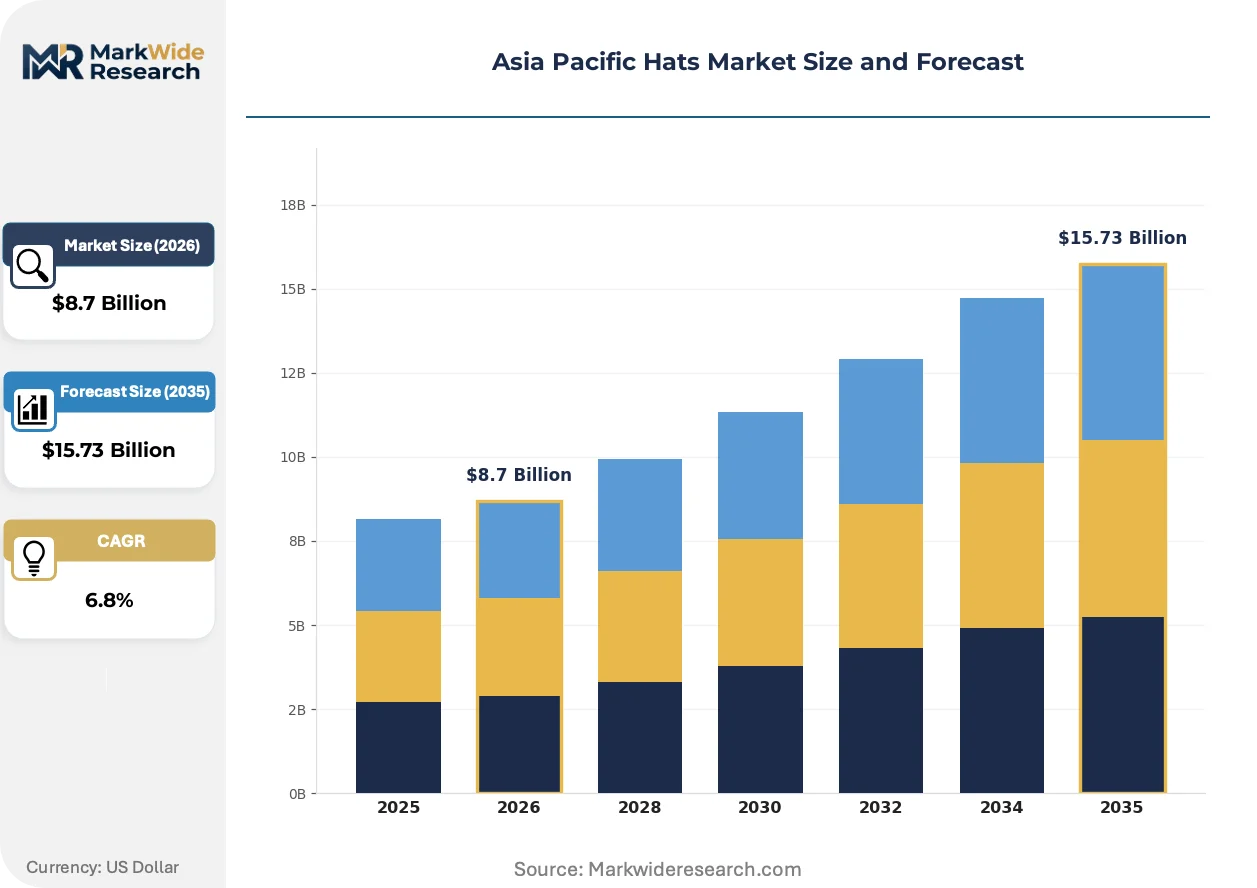
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball Caps, Beanies, Sun Hats, Fedoras Material: Cotton, Wool, Straw, Synthetic Fiber Customer Type: Men, Women, Children, Unisex Sales Channel: Online Retail, Specialty Stores, Department Stores, Marketplaces |
| Companies Covered | Dalix, Nike, Inc., Lock & Co. Hatters, Nantong Foremost Garments & Accessories Co., Ltd., Zhangjiagang Huaxia Headgear Co., Ltd., Goorin Bros., Inc., Tan Thanh Dat Co., Ltd., Richardson, Bailey Hats, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hats Market Strategic Shifts
Material science convergence with regulatory transparency mandates is compressing product development cycles while elevating traceability from marketing feature to operational necessity across Asia Pacific headwear supply chains.
3D-knit seamless construction technology eliminates stitched seams through computerized jacquard weaving that integrates crown, brim, and ventilation zones in single-piece fabrication. Marathon event organizers and professional cycling teams are specifying this construction for aerodynamic and moisture-management performance. Traditional cut-and-sew assembly with separate panel stitching is rendering obsolete in performance segments above $40 retail price points.
China's SAMR is tightening GB/T 29862 fiber content labeling enforcement through random marketplace sampling that penalizes mislabeled wool-acrylic blends with product seizure and platform delisting. Factory quality control departments are deploying near-infrared spectroscopy for incoming yarn verification. Premium-positioned brands sourcing from Zhangjiagang and Ningbo clusters face the highest inspection frequency and are restructuring supplier audit protocols accordingly.
Brand licensing agreements are shortening renewal cycles from five-year to two-year terms as sports leagues and entertainment IP holders demand faster royalty renegotiation tied to social media engagement metrics. Headwear manufacturers serving Korean pop-culture merchandise channels are absorbing design iteration costs that wholesale margins no longer cover. This contract compression is most acute in Seoul and Tokyo, where K-pop and anime licensing drives volume volatility that fixed-cost factories struggle to match.
Asia Pacific Hats Market Segmentation
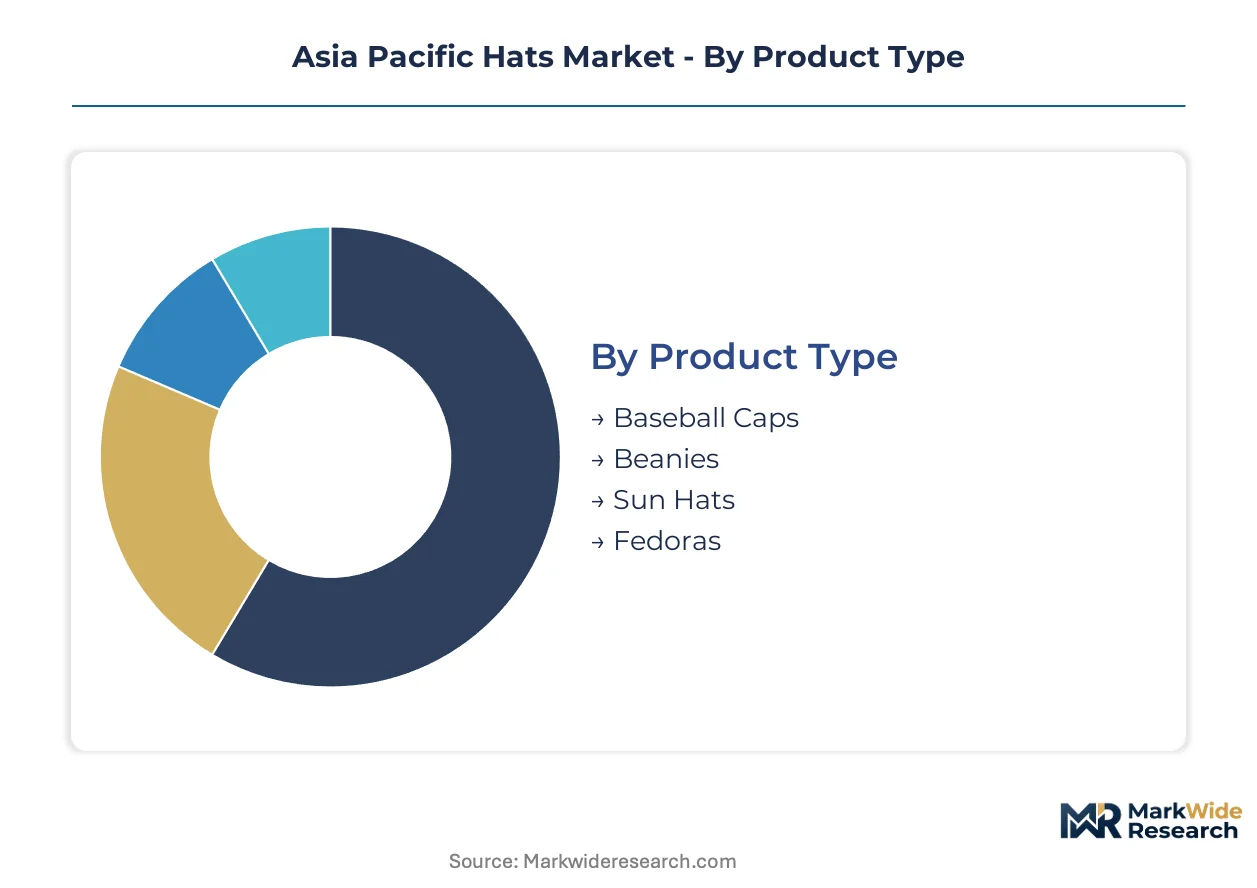
Asia Pacific headwear procurement splits across functional use cases, material performance requirements, and channel access patterns that reshape margin structures. Segment boundaries blur as athletic brands push baseball caps into fashion positioning and sun hats adopt technical synthetic construction.
Product Type:
Baseball caps turn inventory fastest through sports licensing cycles and seasonal team merchandise drops, while fedoras sit longest on retail floors awaiting occasion-driven purchases.
- Baseball Caps:Six-panel crown construction with pre-curved visor dominates mass production through adjustable snapback and fitted sizing variants. Demand concentrates in Vietnam's Da Nang industrial zones where Nike and New Era contract manufacturers exploit EU-Vietnam FTA tariff advantages for European re-export.
- Beanies:Knitted or fleece-lined close-fitting caps with fold-over cuff construction provide thermal insulation in temperate climates. Japanese and Korean markets drive premium wool-acrylic blend specifications, with Seoul's K-pop merchandise channels demanding design iteration cycles under three weeks.
- Sun Hats:Wide-brim woven or synthetic construction with UPF-rated materials serves Australia's outdoor retail and China's domestic resort channels.
- Fedoras:Structured crown with pinched front and flexible brim requires specialized blocking equipment concentrated in aging Guangdong technician pools.
Baseball caps dominate installed base across the region. Beanies are where expansion concentrates in North Asian temperate climate zones.
Material:
Cost tier stratification separates premium natural fibers from volume synthetic production, with mid-tier cotton canvas facing margin compression from both directions.
- Synthetic Fiber:Polyester and nylon blends with moisture-wicking and quick-dry finishes displace cotton in marathon and cycling event merchandise. Zhangjiagang Huaxia Headgear anchors Chinese coastal capacity for regional athletic brand contracts.
- Cotton:Canvas and twill weaves with enzyme washing or pigment dyeing serve casual wear and uniform applications. Bangladeshi spinning mills supply yarn to Ho Chi Minh City garment clusters where labor arbitrage attracts private-label sourcing.
- Wool:Merino and lambswool knits command premium positioning in Japanese department store channels with strict fiber content labeling enforcement.
- Straw:Artisanal weaving in rural Philippines and Bangladesh faces climate-driven yield volatility that disrupts resort-wear production schedules.
Synthetic fiber dominates volume throughput. Wool is climbing the fastest in premium outdoor channel positioning.
Customer Type:
Gendered purchasing patterns fragment further by age cohort, with children's licensing driving volatility that strains fixed-cost manufacturing capacity.
- Men:Sports team licensing and outdoor functional wear concentrate demand in standardized sizing with lower return rates.
- Women:Fashion-forward silhouettes and seasonal color cycles require smaller batch production with higher SKU proliferation.
- Children:Character licensing from Korean and Japanese entertainment IP demands rapid design turnaround that wholesale margins no longer cover.
- Unisex:Adjustable sizing and neutral color palettes reduce inventory risk for online retail channels across tier-two Chinese cities.
Men's segments dominate installed base. Women's fashion positioning is where expansion concentrates through Douyin and Shopee Live direct-to-consumer channels.
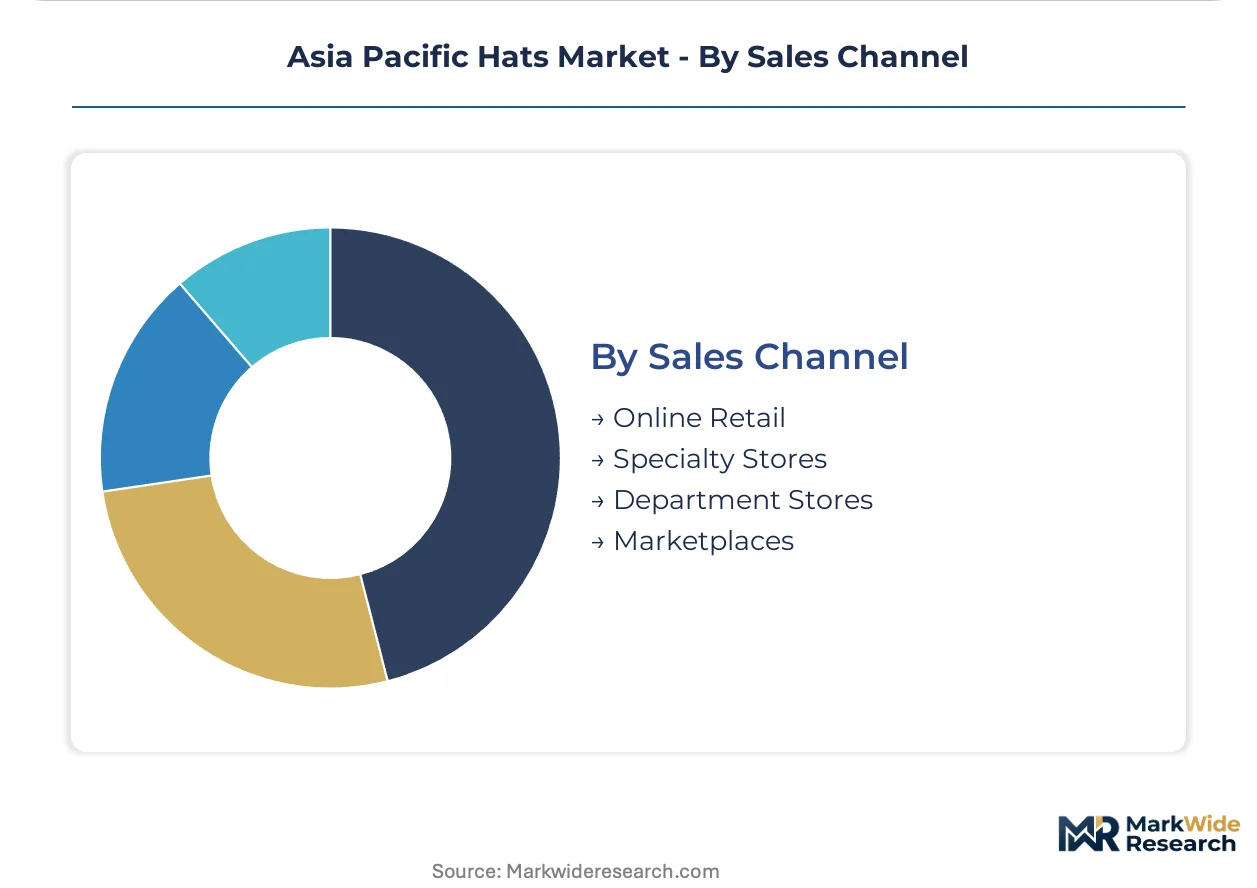
Sales Channel:
Channel mix determines working capital intensity, with marketplace fees compressing margin differently than specialty store wholesale terms.
- Online Retail:Brand-owned e-commerce and direct-to-consumer platforms capture margin formerly allocated to wholesale layers, with live commerce integration collapsing traditional distribution in China.
- Specialty Stores:Curated assortment and staff expertise support premium pricing for technical outdoor headwear in Australian and New Zealand markets.
- Department Stores:Private-label programs demand digital product passport readiness for incoming EU supply-chain transparency mandates.
- Marketplaces:Tmall, JD.com, and Shopee aggregate price-sensitive volume with platform fee structures that polyester-dominant suppliers struggle to absorb.
Marketplaces dominate installed transaction volume. Online retail is gaining share fastest through live commerce integration and direct brand-consumer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade agreements and tightening textile safety standards are redrawing procurement geography across the Asia Pacific headwear sector. Vietnam's EVFTA tariff advantages and China's GB standard enforcement are creating divergent compliance environments that reshape supplier selection criteria.
China
Domestic e-commerce channels and sports licensing programs drive volume demand for baseball caps and beanies. SAMR enforces GB 18401 textile safety standards through random marketplace sampling that penalizes mislabeled fiber blends. Zhangjiagang and Ningbo industrial clusters concentrate synthetic fiber headwear production for athletic brand contracts.
Vietnam
EU-bound export demand accelerates as the Vietnam-EU Free Trade Agreement eliminates duties on textile articles. Da Nang industrial zones attract Nike and New Era contract manufacturers seeking tariff engineering advantages. Tan Thanh Dat Co., Ltd. anchors regional private-label capacity near Ho Chi Minh City.
Japan
Premium wool-acrylic blend specifications dominate department store channels with strict fiber content labeling enforcement. METI guidelines shape product safety expectations for imported headwear. Osaka and Tokyo distribution hubs curate technical outdoor assortments for discerning consumers.
Australia
UV-rated headwear procurement expands through government-backed adventure tourism initiatives in national park systems. TGA-aligned product safety expectations influence import screening for sun protection claims. Sydney and Melbourne specialty retailers command premium positioning for technical outdoor headwear.
South Korea
K-pop merchandise channels demand design iteration cycles under three weeks for character-licensed beanies and caps. MFDS textile labeling requirements create compliance checkpoints for cross-border suppliers. Seoul's Dongdaemun district concentrates rapid-turnaround manufacturing for entertainment IP contracts.
Asia Pacific Hats Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. Asset-light licensing models and third-party manufacturing partnerships lower capital barriers for brand operators without factory ownership. Design-to-retail ecosystems and regional production specialists represent dominant archetypes. Capacity relocation toward Vietnamese industrial zones and digital product passport readiness for EU exports constitute primary competitive moves.
Within the design-to-retail tier, Nike, Inc. exemplifies channel control through integrated ecosystems spanning multiple sales channels. Among Vietnamese production specialists, Tan Thanh Dat Co., Ltd. occupies a position anchoring regional private-label contract capacity. Zhangjiagang Huaxia Headgear Co., Ltd. represents the synthetic fiber specialization archetype for sports and outdoor segment supply.
| Leading Market Players |
|---|
| Dalix |
| Nike, Inc. |
| Lock & Co. Hatters |
| Nantong Foremost Garments & Accessories Co., Ltd. |
| Zhangjiagang Huaxia Headgear Co., Ltd. |
| Goorin Bros., Inc. |
| Tan Thanh Dat Co., Ltd. |
| Richardson |
| Bailey Hats |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo container freight corridors transmit cost volatility directly into margin structures for polyester-dominant suppliers, compressing price realization at mass retail tiers while enabling premium capture for GB-compliant manufacturers serving domestic e-commerce channels. This logistics-cost feedback loop concentrates pricing power among vertically integrated operators with captive yarn-to-finished-goods capacity in Zhangjiagang industrial clusters.
Pricing Analysis
Certification level creates the primary spread between mass-market and premium positioning, with GB 18401-compliant production commanding 15-25% price premiums over non-certified alternatives in Tmall and JD.com channels. Three-tier pricing structure across premium wool blends, standard cotton canvas, and economy polyester separates inventory risk profiles, with children's licensed merchandise absorbing the steepest margin compression due to royalty stacking. Pricing pressure stems from crude oil derivative linkage in synthetic fiber feedstocks that polyester-specialist suppliers cannot pass through to price-sensitive marketplace buyers. Mass retail channels exhibit highest price sensitivity, while Australian specialty outdoor retailers demonstrate lowest elasticity for UPF-rated technical headwear.
Supply Chain Analysis
Polyester chip and recycled ocean plastic yarn feedstock availability anchors production economics for athletic segment suppliers, with Zhangjiagang and Ningbo clusters drawing from Sinopec and regional chemical fiber producers. Geographic supply concentrates in China's coastal provinces for synthetic fiber headwear, Vietnam's Da Nang and Ho Chi Minh City zones for EU-bound baseball cap exports, and Bangladesh's artisanal weaving clusters for straw resort wear. Raw material dependencies span petroleum-derived polymers, merino wool imports from Australia, and hand-woven natural fibers from rural Philippines. Tariff exposure through rules-of-origin compliance for Vietnam-EU FTA qualification constitutes the dominant supply chain risk. Distribution runs through Shopee and Tmall marketplace aggregators for volume, with Nike and New Era operating direct-to-retail ecosystems for premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical pattern-making expertise for fitted cap crown-block engineering represents the critical capability gap constraining Vietnamese manufacturing scale, with aging Guangdong technician pools creating bottleneck conditions that reshape competitive entry economics for precision headwear production.
For Market Incumbents: Pre-empt capacity constraints by securing exclusive contracting relationships with remnant Guangdong precision-engineering technicians before Vietnamese training programs achieve scale replication. Accelerate backward integration into recycled polyester yarn production to insulate margin from crude oil derivative volatility. Invest in near-infrared spectroscopy deployment for incoming fiber verification to preempt GB/T 29862 enforcement penalties from SAMR marketplace sampling. For New Entrants and Emerging Players: Australia's eco-conscious outdoor retail channel offers underpenetrated white-space for biodegradable fiber positioning, where PLA and hemp-blend claims command shelf placement advantages unavailable in saturated mass channels. Secondary tier-two Chinese cities present live commerce integration opportunities through Douyin direct-to-consumer models that collapse wholesale layer economics. Target women's fashion-forward segments with sub-three-week design iteration capabilities enabled by Seoul Dongdaemun district manufacturing partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate apparel divisions with stranded GB-compliant production capacity and underutilized Vietnamese factory assets post-EVFTA relocation. Long-term viability hinges on digital product passport readiness for incoming EU supply-chain transparency mandates. Monitor BIS certification queue compression timelines as early inflection indicator for India market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Readiness | EU department store private-label contracts will require traceability infrastructure by incoming CSRD-aligned mandates. |
| Biodegradable Fiber Conversion | PLA and hemp-blend development opens premium positioning in Australia's TGA-influenced outdoor retail channel. |
| Live Commerce Integration | Douyin and Shopee Live streaming collapses wholesale layers for design-forward domestic brands in tier-two Chinese cities. |
| GB Standard Compliance Investment | SAMR enforcement of GB 18401 and GB/T 29862 creates defensible positioning against non-compliant marketplace competitors. |
| Vietnam-EU FTA Tariff Engineering | Da Nang industrial zone relocation captures phased duty elimination advantages for baseball cap re-export volumes. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with brand licensing directors, Vietnamese factory operations managers, Chinese e-commerce platform category leads, and Australian outdoor retail buyers; and secondary validation through customs export records, SAMR enforcement bulletins, EU trade agreement tariff schedules, and synthetic fiber producer capacity disclosures. Bottom-up demand modeling across product type, material, customer segment, and channel dimensions was triangulated against top-down macroeconomic indicators for the Asia Pacific consumer goods sector.
Forecast inputs incorporated segment-specific growth drivers including sports licensing program expansion, outdoor recreation institutional procurement, and live commerce channel penetration. The analytical framework modeled volume and value trajectories across baseball caps, beanies, sun hats, and fedoras by synthetic fiber, cotton, wool, and straw material categories, with CAGRs derived from regression analysis of historical trade flows and forward-projected regulatory compliance cost impacts. K-pop merchandise cycle volatility and GB standard enforcement intensity were parameterized as scenario variables.
Practitioners should monitor SAMR sampling frequency escalation, Vietnam-EU FTA rules-of-origin interpretation changes, and crude oil derivative price movements for early signals of forecast revision necessity. Cross-checking against IEA petrochemical feedstock price benchmarks and UN Comtrade textile export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Swimwear and Beachwear Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Body Shaper Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Alpaca Apparel and Accessories Market