
 Golf Apparel Market | 2026-2036
Golf Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Apparel Market Analysis
The manufacturing-scale gap between vertically integrated specialists and brand licensors is unwinding competitive stability in golf apparel. Nike Golf leverages its materials-science pipeline to sustain performance-tier pricing power. Adidas Golf anchors its position through direct-to-consumer channel control and tournament sponsorship density. Peter Millar differentiates via elevated lifestyle positioning that captures non-course wear occasions.
Golf apparel encompasses performance-engineered garments designed for swing mobility, moisture management, and UV protection during play, typically constructed from technical fabrics with stretch recovery and breathability ratings. The category serves both competitive athletes and recreational players seeking functional comfort across variable weather conditions. Polo shirts and jackets command the largest revenue pools among product types, while spandex blends and polyester knits are displacing cotton in premium fabrication. Women's and unisex categories are expanding faster than men's, though men's still occupies the majority value share. Specialty stores and online retail together dominate distribution, with direct sales channels capturing margin pools previously held by wholesale intermediaries.
The EU Green Deal and REACH chemical standards constrain dyeing processes and synthetic fiber sourcing for brands selling in Europe, while the US EPA oversees wastewater discharge from domestic textile finishing operations. California's Proposition 65 labeling requirements add compliance layers for brands distributing in that state. Stakeholders must monitor how evolving chemical disclosure rules reshape supplier qualification criteria and whether recycled-content mandates accelerate material substitution timelines.
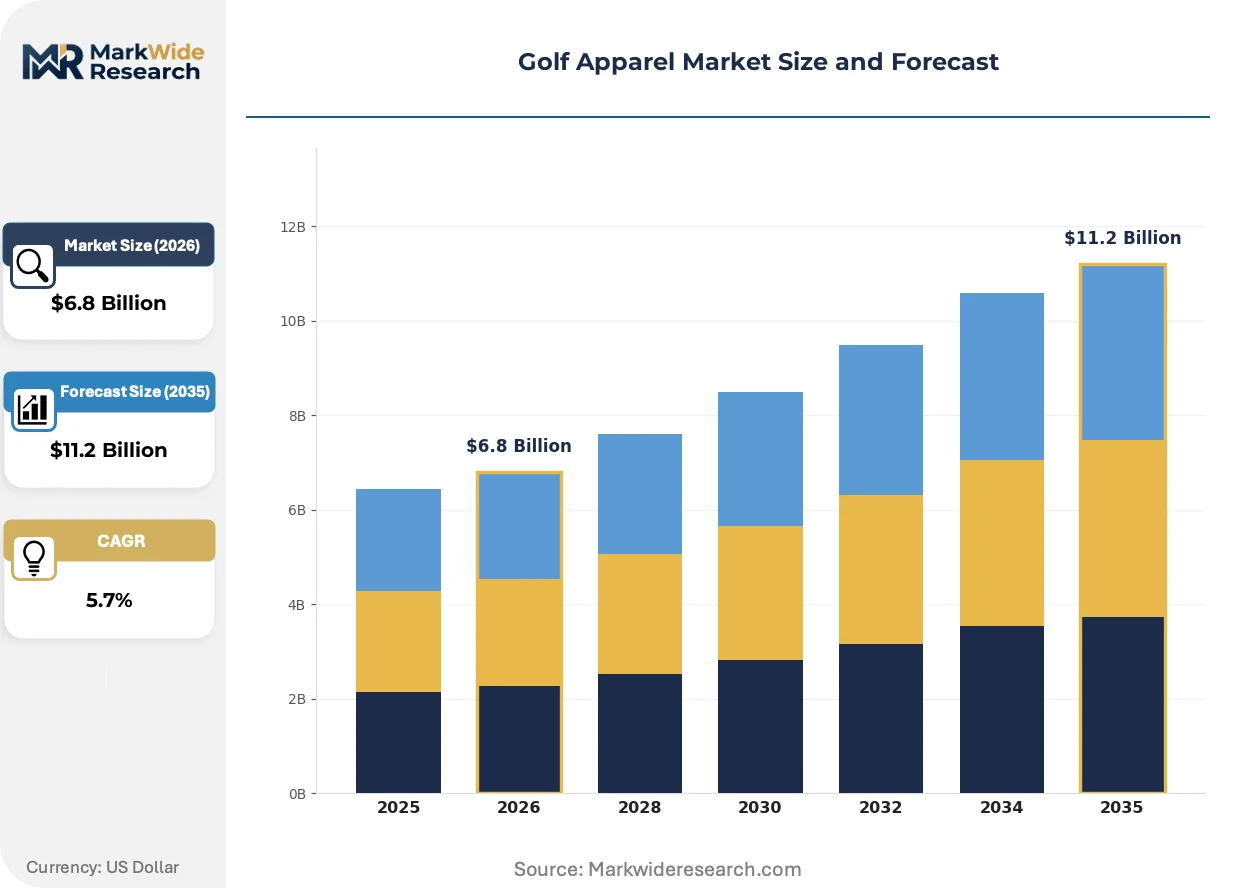
Market Dynamics
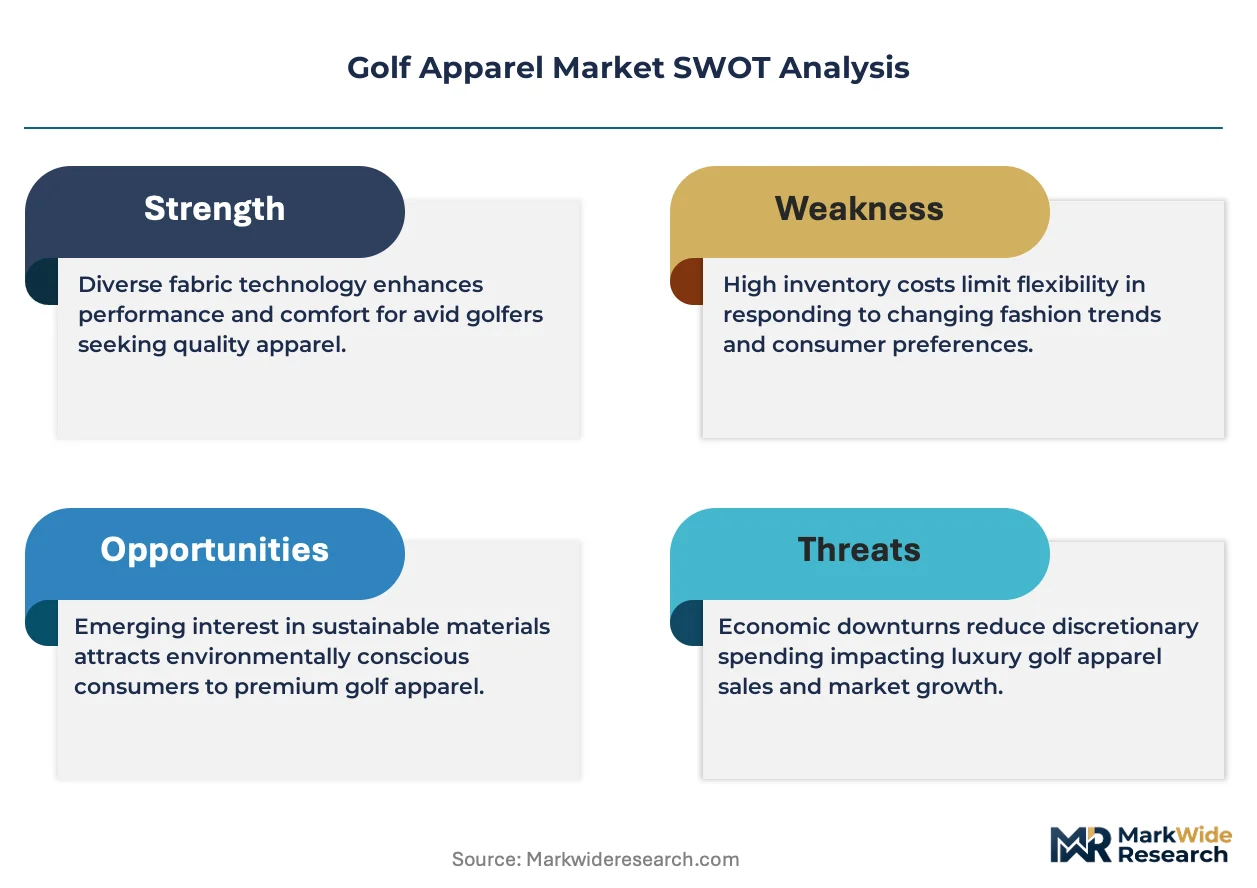
The EU Green Deal's textile sustainability mandates are forcing wholesale recalibration of material sourcing across golf apparel supply chains, compressing lead times for recycled-fiber adoption and reshaping supplier qualification criteria.
Growth Catalysts
- REACH Chemical Standards:European compliance requirements are accelerating R&D investment in waterless dyeing technologies and bio-based elastomers among technical fabric mills.
- Women's Participation Expansion:Female golfer enrollment at municipal courses in the United States and United Kingdom is generating dedicated product lines with specialized fit engineering.
- Spandex Blend Innovation:Four-way stretch recovery fabrics with moisture-wicking ratings above 10,000g/m²/24hr are penetrating mid-tier price bands previously served by cotton knits.
Market Restraints
- Petrochemical Input Volatility:Polyester and elastane prices track crude oil indices, compressing gross margins for brands without forward-contract hedging programs.
- Asian Supply Concentration:Vietnam and Bangladesh textile clusters handle over 60% of cut-and-sew operations, exposing brands to single-origin disruption risks.
- Technical Limitation in Bio-Alternatives:Recycled nylon and bio-polyesters currently fail to match virgin fiber tensile strength for high-abrasion swing zones.
Strategic Opportunities
- India Course Development:New 18-hole facilities in Gujarat and Karnataka states are creating first-mover positioning for brands establishing local distribution partnerships.
- Direct-to-Consumer Channel Maturation:Owned e-commerce platforms with virtual fitting algorithms are capturing margin pools previously held by specialty retail intermediaries.
- EU Digital Product Passport Mandate:Upcoming traceability requirements will reward early adopters of blockchain-verified supply chain documentation with preferential retail placement.
Industry Challenges
- Technical Talent Scarcity:Apparel engineers with dual expertise in biomechanics and sustainable materials command premium compensation, constraining mid-tier brand R&D staffing.
- Certification Timeline Compression:OEKO-TEX and bluesign audits require 8-14 month validation cycles, delaying product launches for suppliers new to compliance frameworks.
- Legacy System Integration:ERP platforms at heritage manufacturers lack API connectivity with modern PLM software, fragmenting production planning visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Apparel Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polo Shirts, Shorts, Skirts, Jackets Fabric Type: Polyester, Cotton, Spandex, Nylon Gender: Men, Women, Unisex, Youth Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Under Armour, Galvin Green, Nike Golf, Malbon Golf, J.Lindeberg, Adidas Golf, FootJoy, Descente Golf, Peter Millar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Apparel Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are converging to redefine performance benchmarks and supply chain transparency expectations across the golf apparel category.
Seamless knitting technology with integrated compression mapping is supplanting traditional cut-and-sew construction in base-layer and mid-layer categories. Performance-focused buyers in competitive amateur segments are adopting these garments at triple the rate of recreational players. This shift is compressing unit economics for regional contract manufacturers lacking capital equipment upgrade capacity.
The EU Green Deal's extended producer responsibility framework for textiles is mandating fiber-to-fiber recycling infrastructure investment by 2030. Brands selling into Germany, France, and Netherlands markets must now fund collection and processing systems for end-of-life garments. Premium positioning players are responding by accelerating take-back program deployment to secure retail shelf space.
Specialty retail consolidation in the United States is compressing wholesale account acquisition timelines and concentrating buyer power among multi-brand golf superstores. Independent pro shops are losing access to seasonal allocation priority, forcing smaller labels toward direct digital channels. California and Florida markets exhibit the most pronounced channel shift velocity, with owned e-commerce penetration rates diverging sharply from national averages.
Golf Apparel Market Segmentation
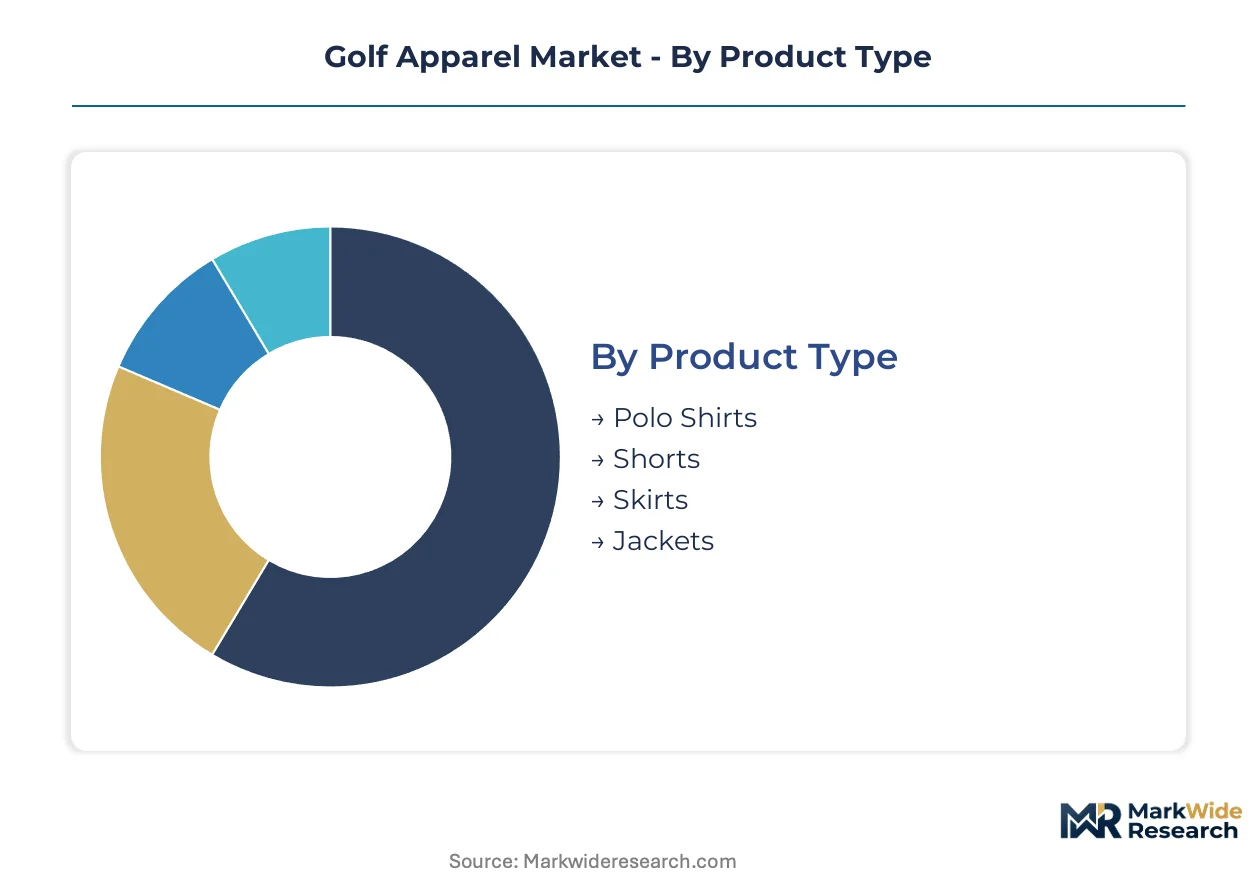
Golf apparel segmentation reveals how technical performance requirements and lifestyle crossover demand create distinct value pools. Understanding these divisions exposes where material substitution pressures and channel margin compression will reshape competitive outcomes.
Product Type:
Polo shirts and jackets face intensifying substitution pressure from athleisure brands expanding into course-appropriate styling with lower price positioning.
- Polo Shirts:Engineered with piqué or jersey knits featuring moisture-wicking polyester blends and UV protection ratings. Demand concentrates in the United States where municipal course participation sustains bulk replenishment cycles, though cotton-blend alternatives from fast-fashion retailers erode entry-tier pricing power.
- Jackets:Constructed with bonded softshell or lightweight ripstop membranes offering wind resistance and four-way stretch mobility. Sales cluster in coastal California and Florida markets where variable morning conditions necessitate layering, with waterproof-breathable ratings above 10,000mm driving premium tier acceptance.
- Shorts:Technical chino or hybrid constructions with silicone waistband grips and stretch recovery properties.
- Skirts:Skort designs with integrated compression shorts and scalloped hemlines for swing clearance.
Polo shirts retain volume leadership; skirts hold the steepest expansion curve.
Fabric Type:
Cost tier stratification separates performance synthetics commanding premium positioning from natural fibers losing share in competitive segments.
- Polyester:Recycled PET and virgin filament yarns dominate moisture management applications with tenacity ratings exceeding 3.5g/denier. Adoption accelerates in Germany and Netherlands markets where EU Green Deal disclosure mandates favor traceable recycled content.
- Spandex:Elastane blends at 8-12% inclusion rates enable compression mapping and shape retention through repeated wash cycles. Integration penetrates fastest in women's lines where fit engineering commands price premiums.
- Cotton:Pima and Supima long-staple varieties persist in heritage brand collections targeting traditionalist demographics.
- Nylon:Polyamide 6,6 structures provide abrasion resistance for high-friction swing zones and outerwear applications.
Polyester retains volume leadership; spandex holds the steepest expansion curve.
Gender:
Customer type differentiation determines whether brands prioritize fit engineering investment or scale economies through unisex simplification.
- Women:Specialized pattern grading addresses torso length, hip circumference, and sleeve articulation distinct from male anatomical standards. Enrollment growth at UK municipal facilities drives dedicated product line expansion with colorway diversification beyond traditional palettes.
- Men:Established size scaling and conservative styling preferences sustain volume concentration through wholesale channel replenishment.
- Unisex:Simplified SKU architectures reduce inventory carrying costs for direct-to-consumer entrants.
- Youth:Growth-adjusted sizing with durable construction targets junior academy programs and family participation occasions.
Men retain volume leadership; women hold the steepest expansion curve.
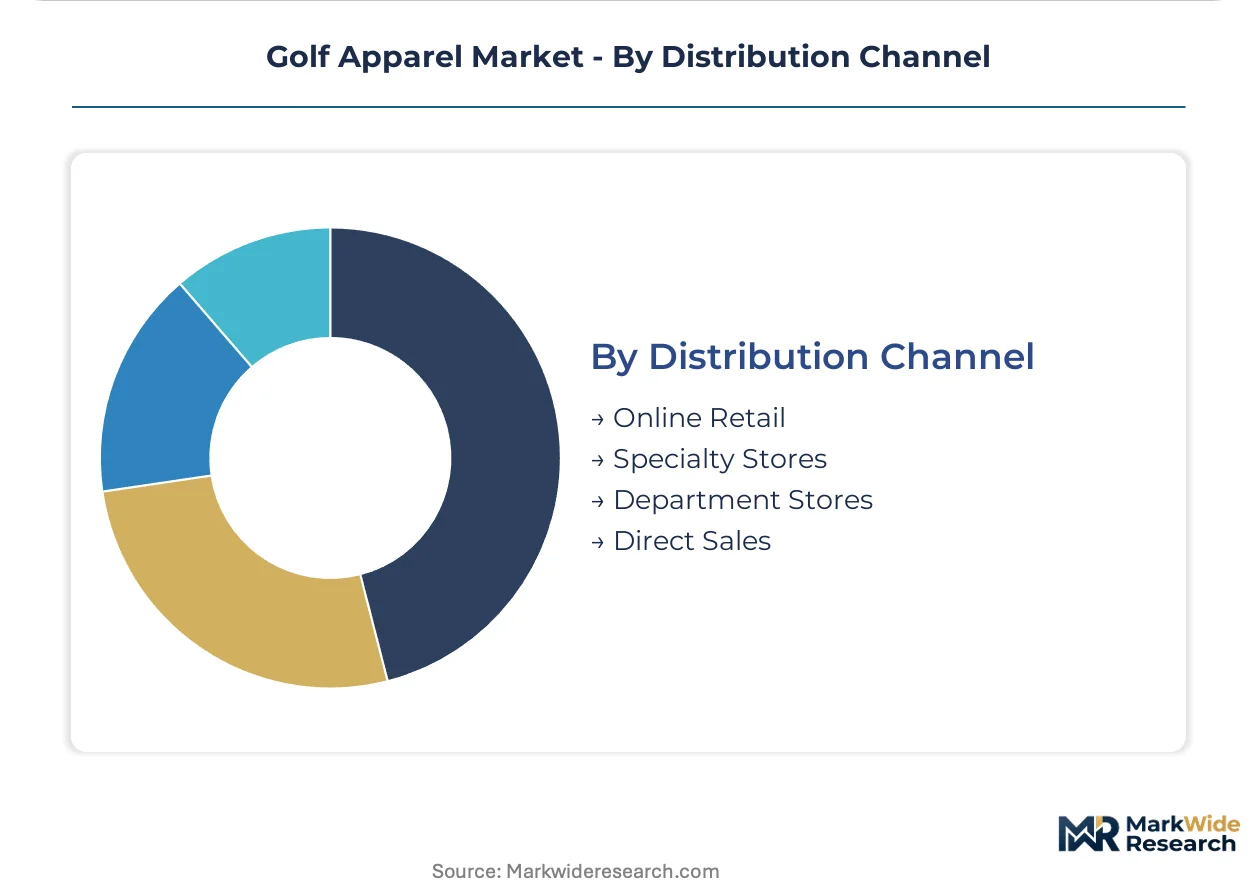
Distribution Channel:
Margin structure varies dramatically between owned digital infrastructure and third-party retail dependency.
- Online Retail:Virtual fitting algorithms and subscription replenishment models capture lifetime value through data-driven personalization. Penetration rates diverge highest in California where digital-native demographics resist specialty store visitation.
- Direct Sales:Owned e-commerce and brand flagship locations eliminate wholesale margin extraction while controlling presentation environment.
- Specialty Stores:Pro shop and golf superstore relationships provide course-adjacent visibility and professional endorsement credibility.
- Department Stores:Seasonal floor space allocations offer brand awareness exposure with compressed margin terms.
Specialty stores retain volume leadership; direct sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with recreational buyers in emerging golf markets exhibiting high sensitivity while established competitive players in mature markets absorb premium positioning without volume erosion.
United States
Municipal course participation and athleisure crossover sustain the largest absolute demand pool, with coastal California and Florida markets driving waterproof-breathable outerwear adoption. The EPA oversees wastewater discharge from domestic textile finishing operations, constraining dyeing facility siting decisions. Carolinas-based textile clusters handle substantial cut-and-sew capacity for brands serving both mass and premium tiers.
Germany
EU Green Deal textile sustainability mandates accelerate recycled-fiber adoption among technical fabric mills supplying performance golf lines. ECHA REACH chemical standards enforce rigorous substance disclosure across dyeing and finishing processes. Bavaria's industrial textile belt concentrates specialist weaving operations serving premium outerwear brands with short-lead customization capabilities.
United Kingdom
Female golfer enrollment at municipal facilities generates dedicated product line expansion with specialized fit engineering requirements. The UK's post-Brexit regulatory divergence from EU chemical standards creates dual compliance burdens for brands operating across both markets. England's Midlands region hosts heritage knitting operations supplying piqué and jersey constructions to established heritage labels.
Japan
Discerning competitive amateur segments demand seamless compression-mapped base layers with integrated moisture management, sustaining technology-forward positioning. METI industrial standards govern textile quality certification and fiber content labeling enforcement. Osaka-Kobe industrial corridors concentrate technical fabric development partnerships between domestic mills and global sportswear licensors.
India
New 18-hole facility development in Gujarat and Karnataka states creates first-mover positioning opportunities for brands establishing local distribution partnerships. BIS textile standards and emerging state-level sustainability procurement guidelines shape supplier qualification requirements. Tiruppur's knitwear cluster and Surat's synthetic fiber belt are expanding technical capacity to serve export-oriented golf apparel contracts.
Golf Apparel Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where materials-science specialists command premium positioning against scale-driven licensors. The vendor base spans vertically integrated fabric developers, brand licensees leveraging outsourced manufacturing, and direct-to-consumer entrants exploiting digital channel economics. Three archetypes dominate: performance-technology owners with captive R&D pipelines, lifestyle-positioned heritage labels capturing off-course wear occasions, and digital-native challengers compressing wholesale margin extraction. Dominant competitive moves include direct-to-consumer channel maturation and strategic tournament sponsorship density to secure professional endorsement credibility.
Among performance-technology specialists, Nike Golf and Adidas Golf exemplify archetypes leveraging materials-science pipelines and direct channel control respectively. Peter Millar occupies a position within the elevated lifestyle tier, capturing non-course wear occasions through differentiated aesthetic positioning. These three anchors illustrate how competitive outcomes diverge based on whether players prioritize technical innovation, channel economics, or lifestyle crossover appeal.
| Leading Market Players |
|---|
| Under Armour |
| Galvin Green |
| Nike Golf |
| Malbon Golf |
| J.Lindeberg |
| Adidas Golf |
| FootJoy |
| Descente Golf |
| Peter Millar |
| Others |
Supply Flow & Price Mechanics
Recycled polyester adoption is displacing virgin filament yarns across premium golf apparel tiers, simultaneously shifting procurement gravity toward Vietnam and Bangladesh while compressing margin structures for brands lacking forward-contract hedging on petrochemical inputs.
Pricing Analysis
After-sales revenue through subscription replenishment and virtual fitting services drives lifetime value capture for direct-to-consumer entrants. Three-tier pricing structure across premium performance, standard technical, and entry-level cotton-blend levels separates Nike Golf's materials-science positioning from fast-fashion athleisure encroachment. Price differentiation hinges on moisture-wicking certification tiers and swing-mobility engineering depth. Pricing pressure stems from Asian supply concentration exposing brands to elastane cost volatility. Municipal course recreational buyers exhibit highest price sensitivity; competitive amateur segments absorb premium positioning without volume erosion.
Supply Chain Analysis
Strategic stockpiling of technical fabric inventories dominates over just-in-time preferences among heritage manufacturers buffering against OEKO-TEX certification delays. Vietnam, Bangladesh, and China's textile clusters anchor cut-and-sew capacity for over sixty percent of global output. Raw material flows draw from South Korean elastane producers, Taiwanese recycled PET suppliers, and German dye-chemical specialists. Single-origin disruption risk concentrates in Vietnamese garment finishing operations. Distribution runs through specialty golf superstores and owned e-commerce platforms diverging by regional channel maturity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where tournament sponsorship density and professional endorsement networks create switching costs that lock in retail shelf access against digital-native challengers.
For Market Incumbents: Fortify materials-science pipelines through captive R&D investment in bio-based elastomers, defending against fast-fashion athleisure substitution at entry price tiers. Deepen backward integration into Vietnamese cut-and-sew capacity to mitigate single-origin disruption exposure. Prioritize OEKO-TEX and bluesign certification maintenance to sustain EU Green Deal compliance access.
For New Entrants and Emerging Players: Bluesign certification fast-track through partnership with established German dye-house specialists enables rapid EU market entry without fourteen-month audit timelines. White-space concentration sits in India's Gujarat and Karnataka course development corridors where first-mover distribution partnerships remain unclaimed. Direct-to-consumer virtual fitting algorithms offer the most penetrable go-to-market angle against wholesale-dependent heritage labels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors lifestyle-positioned heritage labels with off-course wear occasion capture over pure-performance technology owners. Long-term viability over the coming decade rests on brands bridging biomechanical engineering with sustainability credentialing. Acquisition target archetype: mid-tier labels with established specialty retail relationships but underdeveloped digital infrastructure. The signal to watch is EU Digital Product Passport mandate compliance velocity as retail placement preference determinant.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Maturation | Owned e-commerce with virtual fitting captures margin pools from wholesale intermediaries. |
| EU Green Deal Compliance Investment | Waterless dyeing technology adoption satisfies ECHA REACH standards for European market access. |
| Women's Fit Engineering Expansion | Specialized pattern grading addresses UK municipal course enrollment growth demographics. |
| India Distribution Partnership Establishment | First-mover positioning in Gujarat and Karnataka course developments secures emerging demand. |
| Blockchain Supply Chain Documentation | Digital Product Passport readiness rewards early adopters with preferential retail placement. |
Methodological Framework
A spread of perspectives from brand licensing directors, technical fabric mill procurement leads, specialty retail buyers, and municipal course operators converged on the working assumptions underlying demand segmentation. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC apparel sector filings, and EU ECHA substance registration databases. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption indicators.
Segmentation dimensions modeled span product type, fabric technology tier, gender category, and distribution channel structure across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory intervention timelines and material substitution elasticity. Industry-specific forecast inputs incorporated EU Green Deal recycled-content mandate compliance curves and women's participation enrollment data from UK municipal facilities.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical input price stability or accelerated bio-polymer tensile strength breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding certification audit durations and channel shift velocity. Revision becomes warranted when EU Digital Product Passport implementation timelines or India course development completion rates cross threshold deviations from baseline scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Thimbles Market