
 Spoon in Lid Packaging Market | 2026-2036
Spoon in Lid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spoon in Lid Packaging Market Intelligence
The substitution of traditional polystyrene and polypropylene with biodegradable bioplastics is restructuring the cost models for single-serve food containers. Greiner Packaging International GmbH leverages its polymer expertise to develop sustainable alternatives for its dairy and food-to-go clients. Amcor Plc competes on a global scale by offering a broad portfolio of lid and utensil combinations for major food brands. Huhtamäki Oyj differentiates through its focus on fiber-based and compostable packaging solutions.
Spoon in lid packaging integrates a utensil, typically a foldable or telescopic spoon, directly into the over-cap or foil seal of a container. This design provides a complete, self-contained solution for on-the-go consumption, eliminating the need for separate cutlery. The ready-to-eat meals and instant noodles applications represent the largest volume segments due to consumer convenience trends. Within product types, plastic spoons still dominate, but biodegradable and wooden spoon options represent the fastest-growing category.
Food contact material standards from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern material safety and migration limits. Concurrently, regulations like the EU's Single-Use Plastics Directive and China's dual carbon goals are pushing manufacturers towards recyclable or compostable materials. Supplier selection will increasingly hinge on the ability to provide certified sustainable materials that meet both regulatory mandates and consumer expectations.
Market Dynamics
The market's central dynamic is the conflict between persistent consumer demand for on-the-go convenience and intensifying regulatory mandates, such as the EU's plastics directive, which are compelling a rapid, and costly, shift toward sustainable materials.
Growth Catalysts
- Urban Convenience Demand:Consumption of ready-to-eat meals and instant noodle products in dense urban centers, particularly in China, creates sustained volume demand for integrated, single-use utensil solutions.
- Regulatory Incentives:The EU Single-Use Plastics Directive is actively creating markets for alternatives by phasing out conventional plastic cutlery, directly benefiting producers of certified compostable and fiber-based spoons.
- Material Innovation:Advances in thermoforming for fiber-based materials and the development of new bioplastic polymers with improved heat stability are expanding the addressable applications for non-plastic spoon in lid designs.
Market Restraints
- Cost Disparity:Biodegradable bioplastics and wood-based materials carry a significant cost premium over traditional polystyrene and polypropylene, impacting the price competitiveness of the final food product.
- Material Performance Gaps:Certain sustainable alternatives exhibit lower durability, heat resistance, or moisture barrier properties compared to plastics, limiting their use in applications like hot soups or certain dairy products.
- Fragmented Regulations:Manufacturers face complexity in ensuring a single product SKU complies with divergent food contact material standards from authorities like the FDA in the United States and EFSA in Europe.
Strategic Opportunities
- Nutraceutical Applications:The single-serve powder supplement market, including protein powders and collagen, presents an untapped application for integrated scoops, offering consumers precise dosage and convenience.
- Geographic Expansion:Markets such as India and Brazil, with their large populations and growing middle-class demand for convenience foods, offer significant white space for market entry and expansion.
- Smart Packaging Integration:Incorporating QR codes or NFC tags onto the lid or foil seal offers opportunities for enhanced consumer engagement, traceability, and verification of sustainability claims.
Industry Challenges
- Supply Chain Overhaul:Shifting procurement from established, high-volume petrochemical supply chains to sourcing certified, food-grade bioplastics or wood fiber requires significant investment and qualification of new suppliers.
- Certification Bottlenecks:The time and expense required to achieve food contact safety certifications from both the FDA and EFSA for new sustainable materials can delay product launches by several quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spoon in Lid Packaging Market |
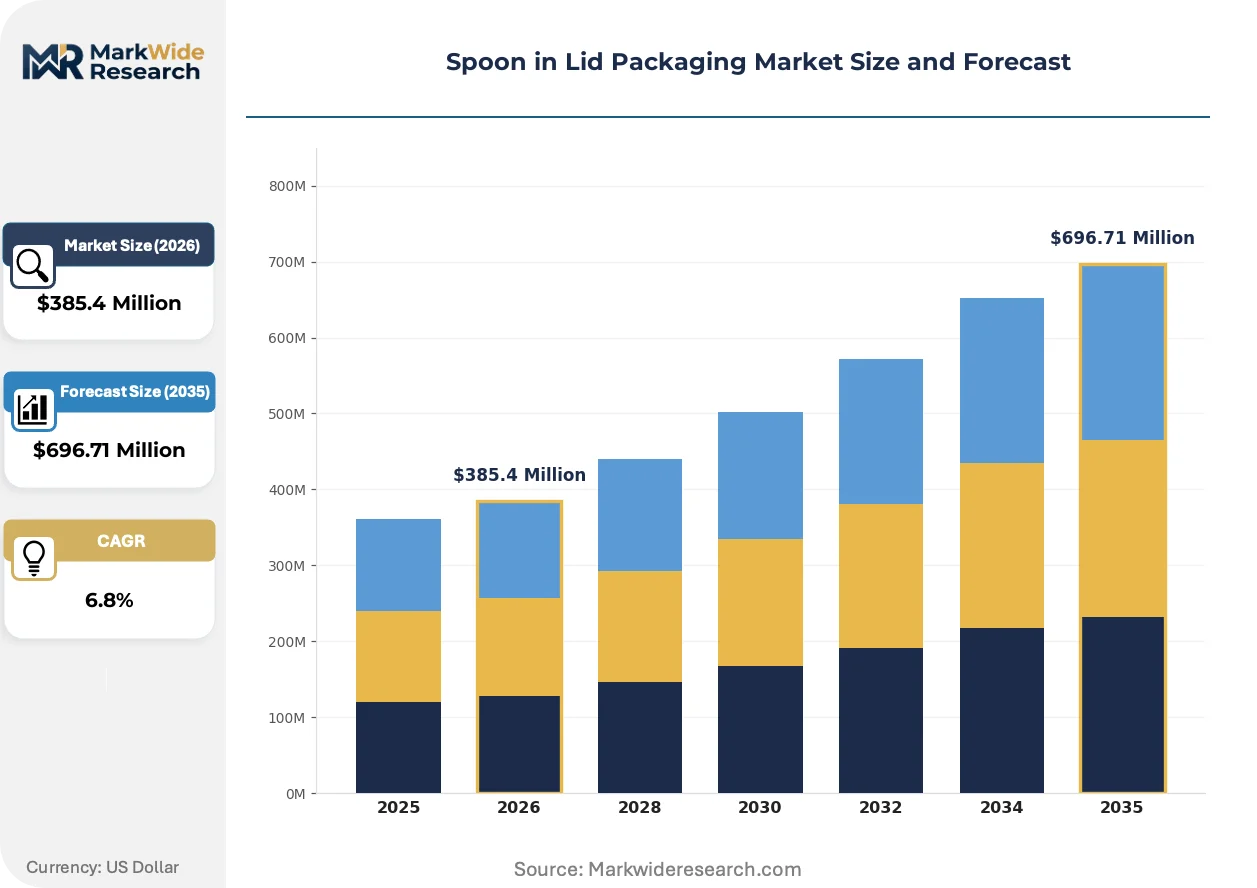
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Spoon, Wooden Spoon, Biodegradable Spoon, Metal Spoon, Composite Spoon Application: Ready-to-Eat Meals, Beverage Cups, Frozen Desserts, Snack Containers, Instant Noodles Packaging Material: Polypropylene, Polystyrene, Paperboard, Bioplastic, Aluminum Foil End User: Foodservice Operators, Cafeterias, Catering Services, Meal Delivery Providers, Institutional Kitchens |
| Companies Covered | Greiner Packaging International GmbH, SP Containers, ITC Packaging, Fourmark Manufacturing, Polyoak Packaging Group, Plasticos Regina, Amcor Plc, Huhtamäki Oyj, Berry Global Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spoon in Lid Packaging Market Strategic Shifts & Innovations
Material science advancements are colliding with a new class of environmental regulations. This dynamic is fundamentally altering product design, pushing innovation away from cost-optimized plastics and toward performance-validated sustainable alternatives for single-serve packaging.
New manufacturing equipment is designed specifically for handling delicate, foldable utensils made from fiber or bioplastics. Food processors in the yogurt and instant meal segments are rapidly adopting these systems to maintain throughput. This specialized machinery is automating the previously manual-intensive process of quality checking and placing fragile utensils, removing a key production bottleneck.
The European Union’s Single-Use Plastics Directive (SUPD) serves as a powerful market-shaping force. It directly prohibits placing certain plastic cutlery items on the market, creating a non-negotiable requirement for material substitution. The dairy and food-to-go segments have been most impacted, now prioritizing the adoption of compliant wooden and fiber-based utensils to continue serving the European market.
A consumer preference is forming for products with explicit on-pack sustainability certifications, such as "compostable" or "FSC-certified". This shift disrupts historical procurement models based on unit cost, forcing brands to factor in the marketing value of environmental claims. The behavior is most pronounced in North American and European markets for premium organic and health-focused foods.
Spoon in Lid Packaging Market Segmentation
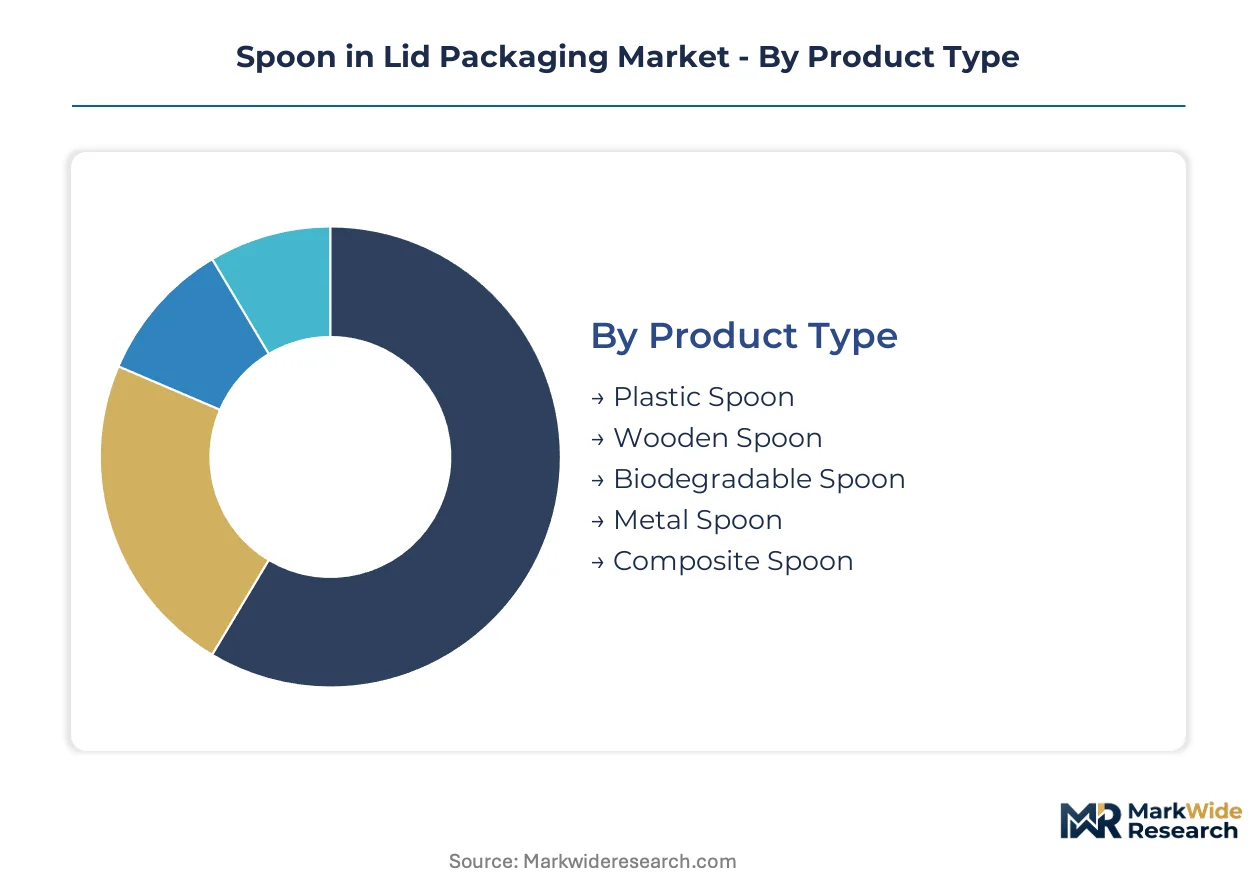
The Spoon in Lid Packaging Market segmentation reveals how material innovations and consumer preferences shape product offerings. Understanding these distinct segments allows businesses to align product development with specific demand drivers and regulatory pressures. This granular analysis highlights areas of both established volume and rapid expansion.
Product Type:
The product type segmentation reflects an ongoing upgrade cycle, driven by sustainability mandates and evolving consumer expectations for eco-friendly solutions.
- Biodegradable Spoon:These spoons are manufactured from plant-based polymers like PLA or PHA, designed to decompose under specific conditions. Demand concentrates in European and North American markets, driven by the EU's Single-Use Plastics Directive and consumer preference for compostable options.
- Wooden Spoon:Crafted from sustainably sourced wood, these utensils offer a natural, non-plastic alternative. Adoption is significant in the dairy and food-to-go segments within the European Union, responding directly to bans on conventional plastic cutlery.
- Plastic Spoon:Comprising traditional polypropylene and polystyrene, these spoons offer cost-effectiveness and established performance for mass-market products.
- Metal Spoon:Reusable metal spoons are less common in single-use packaging but appear in premium, re-sealable meal kits for enhanced user experience.
- Composite Spoon:These combine materials, often a plastic core with a bioplastic coating, balancing cost and sustainability attributes.
Volume placements concentrate in Plastic Spoon; the faster expansion belongs to Biodegradable Spoon.
Application:
The application segments highlight how convenience, shelf-life, and consumption patterns dictate the integration of spoon-in-lid solutions.
- Ready-to-Eat Meals:This segment encompasses a wide array of pre-prepared dishes, from salads to microwaveable entrees, requiring a utensil for immediate consumption. High volume demand in urban centers, particularly in China, drives this category's growth.
- Instant Noodles:Instant noodle cups and bowls represent a significant application, where the integrated spoon facilitates quick, hot meal preparation and consumption. This segment sees substantial demand across Asia due to its convenience.
- Beverage Cups:Spoon-in-lid solutions for beverage cups are less common but serve applications like layered parfaits or thick smoothies.
- Frozen Desserts:Individual portions of ice cream or yogurt often incorporate a small spoon for on-the-go enjoyment in convenience stores.
- Snack Containers:This includes fruit cups, yogurt pots, and other single-serve snacks where a utensil enhances portability for consumers.
Ready-to-Eat Meals and Instant Noodles collectively account for the largest share of spoon-in-lid packaging volume.
Packaging Material:
The choice of packaging material is increasingly shaped by regulatory compliance and brand commitments to environmental stewardship.
- Bioplastic:Derived from renewable biomass sources, bioplastics like PLA and PHA are gaining traction as sustainable alternatives to conventional plastics. The EU's dual carbon goals and consumer demand for eco-friendly packaging are accelerating their adoption.
- Paperboard:Often coated for moisture resistance, paperboard offers a fiber-based, recyclable, and compostable option for spoon-in-lid designs. Innovation in thermoforming for fiber-based materials supports its expansion in food-to-go applications.
- Polypropylene:A widely used thermoplastic, polypropylene provides excellent moisture barrier and heat resistance at a low cost for diverse products.
- Polystyrene:Historically used for its rigidity and clarity, polystyrene faces regulatory pressure due to its single-use plastic status in many regions.
- Aluminum Foil:Primarily used as a seal or lid component, aluminum foil maintains product freshness and tamper evidence for various food items.
Bioplastic and Paperboard materials are experiencing the most rapid expansion as brands seek compliant and sustainable options.
End User:
End-user segments reflect diverse operational scales and distribution models, each with specific requirements for convenience and packaging efficiency.
- Meal Delivery Providers:These services rely heavily on self-contained packaging solutions to ensure convenience for consumers receiving food at home or office. Growth in this segment is driven by the global rise of e-commerce and food delivery platforms.
- Foodservice Operators:Restaurants, cafes, and quick-service establishments utilize spoon-in-lid packaging for their grab-and-go offerings. Urbanization and busy lifestyles in regions like North America increase demand for such convenient formats.
- Cafeterias:Institutional and corporate cafeterias use integrated packaging for efficiency in high-volume serving environments, reducing separate cutlery needs.
- Catering Services:Catering operations benefit from pre-packaged, utensil-inclusive meals for events and remote locations, simplifying logistics.
- Institutional Kitchens:Hospitals, schools, and other large-scale kitchens employ these solutions for portion control and hygiene in regulated settings.
Meal Delivery Providers and Foodservice Operators are the primary drivers of demand for integrated spoon-in-lid solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for on-the-go convenience products, particularly ready-to-eat meals and instant noodles, drives the global spoon in lid packaging market. Urbanization patterns across major economies concentrate this demand in specific geographic hubs. Regulatory shifts towards sustainability also reshape material procurement in key regions.
China
China's dense urban centers generate substantial demand for integrated spoon-in-lid solutions in instant noodles and ready-to-eat meals. The country's dual carbon goals accelerate the shift towards bioplastic and paperboard packaging materials. Manufacturers in coastal industrial zones like the Yangtze River Delta focus on scaling sustainable production for domestic consumption.
Germany
German consumers increasingly seek sustainable food-to-go packaging, particularly for dairy and instant meal products. The EU's Single-Use Plastics Directive mandates the phase-out of conventional plastic cutlery, driving material innovation. Food processing hubs in Bavaria and North Rhine-Westphalia are rapidly adopting compliant wooden and fiber-based utensils.
United States
United States demand for spoon-in-lid packaging stems from convenience foods, snack containers, and emerging nutraceutical applications. The U.S. Food and Drug Administration (FDA) governs material safety and migration limits for all food contact packaging. Urban centers in California and the Northeast Corridor see concentrated demand for premium, sustainable options.
India
India's expanding middle class drives significant demand for convenient, on-the-go meal solutions and food delivery services. The Bureau of Indian Standards (BIS) establishes material and safety standards for food packaging. Major metropolitan areas like Mumbai and Bengaluru represent key growth markets for integrated utensil solutions.
Brazil
Brazilian urbanization trends fuel demand for ready-to-eat meals, frozen desserts, and snack containers. ANVISA, Brazil's health surveillance agency, mandates compliance with food contact material safety regulations. Food manufacturers in São Paulo and Rio de Janeiro are exploring sustainable spoon-in-lid options.
Spoon in Lid Packaging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the spoon in lid packaging market. The market exhibits a tiered structure, with large multinational packaging corporations competing with agile regional manufacturers. Strategic archetypes include integrated solution providers, material innovation leaders, and cost-efficient volume producers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach.
Global packaging corporations, including Amcor Plc, exemplify the integrated solution provider archetype, offering broad portfolios of lid and utensil combinations across diverse geographies. Huhtamäki Oyj represents a key specialist in fiber-based and compostable packaging solutions, particularly relevant for sustainability-driven markets and regulatory compliance. Greiner Packaging International GmbH, leveraging its polymer expertise, occupies a position focused on developing sustainable alternatives for dairy and food-to-go clients. These firms collectively navigate evolving regulatory landscapes and persistent consumer demand for convenient, yet eco-friendly, materials.
| Leading Market Players |
|---|
| Greiner Packaging International GmbH |
| SP Containers |
| ITC Packaging |
| Fourmark Manufacturing |
| Polyoak Packaging Group |
| Plasticos Regina |
| Amcor Plc |
| Huhtamäki Oyj |
| Berry Global Inc |
| Others |
Cost & Logistics Intelligence
Specialized labor for thermoforming fiber-based materials in European and Chinese manufacturing hubs influences the cost structure, creating distinct pricing tiers between traditional plastic and sustainable spoon-in-lid solutions. This labor-cost differential directly impacts the final product price for food manufacturers, particularly for those adopting compliant materials.
Pricing Analysis
Volume-driven segments often prioritize cost, while premium offerings command higher prices for sustainability attributes. The dominant pricing structure in this market is per-unit transactional, heavily influenced by material costs and manufacturing efficiency. Price differentiation stems from the material's certification level, such as FDA or EFSA compliance, and the volume scale of the order. Pricing softness runs through the conventional plastic spoon segment due to regulatory pressure and increasing consumer preference for alternatives. Mass-market instant noodle brands are generally more price-sensitive than premium organic food producers.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China, Southeast Asia, and Europe shapes the global supply chain for spoon-in-lid packaging. Supply concentration for conventional plastics resides primarily in China and other Asian countries, leveraging established petrochemical infrastructure. Raw material dependencies include polypropylene and polystyrene for traditional options, alongside plant-based polymers like PLA and PHA, and wood pulp for sustainable alternatives. A structural supply chain risk is commodity price volatility for both petrochemicals and bioplastic feedstocks. Distribution runs predominantly B2B, directly from packaging manufacturers to large food brands and co-packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intensifying regulatory pressure, particularly the EU's Single-Use Plastics Directive, is forcing a consolidation play where smaller, less adaptable manufacturers face significant headwinds.
For Market Incumbents: Anticipate continued regulatory evolution by investing heavily in sustainable material research and development. Secure long-term supply agreements for certified bioplastics and fiber-based materials to mitigate commodity price volatility. This proactive investment in polymer expertise and certification capabilities will defend against emerging sustainable material specialists. Focus R&D on enhancing the performance of compliant materials to close existing material performance gaps.
For New Entrants and Emerging Players: Niche technology integration for fiber-based thermoforming presents a significant wedge for new market players. Target underpenetrated application areas like nutraceuticals and single-serve powder supplements, where premium pricing supports sustainable material costs. The most penetrable segment for new entrants is the premium organic food market in North American and European urban centers. Emphasize explicit on-pack sustainability certifications to differentiate products and capture consumer attention.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to build a portfolio of sustainable packaging solutions. Long-term viability hinges on companies with robust intellectual property in bioplastics or advanced fiber-based materials. Target specialized manufacturers with existing FDA and EFSA certifications for sustainable food contact materials. A critical signal to watch is the acceleration of bioplastic adoption in mass-market food categories, indicating broader acceptance and scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bioplastic R&D | Enhances material performance and broadens application scope for sustainable solutions. |
| Secure Certified Material Supply | Mitigates supply chain risk and ensures regulatory compliance for food brands. |
| Expand Fiber-Based Thermoforming | Addresses demand for compostable packaging, particularly in the European market. |
| Target Nutraceutical Applications | Captures new revenue streams in the growing single-serve supplement market. |
| Develop Smart Packaging Features | Enhances consumer engagement and traceability for brand owners. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of the Spoon in Lid Packaging Market. This was complemented by primary interviews with packaging engineers, procurement managers at major food brands, material scientists, and regulatory compliance officers. The research combined bottom-up analysis of company-level data with top-down validation against overall market trends and macroeconomic indicators.
Data-stream reconciliation integrated historical market performance with projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, packaging material, end-user, and geographic region, alongside material performance tiers. Compound annual growth rates were derived from a synthesis of historical data, anticipated market shifts, and expert consensus. Key forecast inputs included material cost trends, regulatory impact assessments, and evolving consumer preference shifts.
Several conditions sit outside the modeled scope, including specific company-level strategic maneuvers and short-term macroeconomic fluctuations. Forecasts reflect assumptions regarding sustained consumer demand for convenience and the continued tightening of environmental regulations. Material deviation in global trade policies or raw material availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Gable Top Container Market
Packaging
Corrugated Shippers Market
Packaging
Twist Tie Machines Market
Packaging
Active and Modified Atmosphere Packaging Market
Packaging
Corrugated Fiberboard Market
Packaging
Global in Store Theater Packaging Market
Packaging
Global Recyclable Packaging Market
Packaging
India Plastic Packaging Market
Packaging
United Kingdom Corrugated Packaging Market
Packaging
Mesh Bags Market
Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Packaging
Smart Bottle Market
Packaging
Global Nano Enabled Packaging Market
Packaging
Transplant Box Market
Packaging
Stackable Beaker Market
Packaging
Anti-Fog Lidding Films Market