
 Products from Food Waste Market | 2026-2036
Products from Food Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Products from Food Waste Market Outlook
Pet food formulation is shifting toward upcycled protein concentrates as conventional meat meal costs pressure margin structures. ReGrained leverages proprietary stabilization technology to convert brewers spent grain into shelf-stable flour for CPG partners. Bio-bean Ltd. anchors London's industrial coffee waste stream through pyrolysis-derived logs and biochemical extraction. Renewal Mill specializes in okara and oat pulp processing, occupying the gluten-free baking ingredient niche with defatted fiber concentrates.
Products from food waste encompass commercially viable outputs derived from agricultural, processing, and post-consumer organic residues through mechanical, biological, or thermochemical transformation, typically achieving 15-40% protein recovery rates or lignocellulosic fiber yields suitable for composite applications. Anaerobic digestion dominates installed capacity for energy production but faces margin compression as renewable natural gas offtake terms tighten. Fermentation is accelerating fastest among technology categories, driven by precision-controlled mycelium propagation and organic acid synthesis from fruit sugars. Compost retains volume leadership in product type but commands lower unit economics than upcycled packaging substrates molded from cellulose-rich pomace.
The EPA landfill diversion thresholds and EU F-Gas Regulation on packaging alternatives shape compliance-driven procurement in North America and Europe, while India's FSSAI novel food ingredient approvals create market access friction for imported upcycled concentrates. ISO 22000 and HACCP adaptation for waste-derived inputs remains uneven across inspectorates, fragmenting cross-border trade eligibility. Stakeholders must monitor evolving contaminant testing protocols for mycotoxin and pesticide bioaccumulation in circular feedstocks.
Market Dynamics
Landfill diversion mandates and renewable natural gas offtake tightening are compressing anaerobic digestion margins while accelerating capital flows toward precision fermentation and mycelium propagation platforms.
Growth Catalysts
- EU Green Deal landfill diversion targets:Germany and France now enforce organic refuse valorization quotas that redirect waste streams from disposal to ingredient recovery, expanding feedstock availability for upcycled protein processors.
- Pet food formulation economics:Conventional meat meal cost inflation drives manufacturers toward brewers spent grain and fruit pomace concentrates that stabilize margin structures without sacrificing protein density.
- Wageningen University commercialization clusters:Netherlands-based government incubators accelerate pilot-to-scale transitions for upcycled ingredient startups, reducing technology validation timelines.
Market Restraints
- Renewable natural gas offtake compression:Tightened renewable natural gas contract terms squeeze anaerobic digestion facility margins, limiting reinvestment capacity for technology upgrades.
- Feedstock supply concentration in agricultural belts:Fruit pomace and spent grain availability clusters in specific growing regions, creating transport cost penalties for processors outside 200-kilometer radii.
- ISO 22000 adaptation fragmentation:Uneven inspectorate interpretation of HACCP protocols for waste-derived inputs fragments cross-border trade eligibility, delaying market access for imported concentrates.
Strategic Opportunities
- India FSSAI novel food ingredient pathway:Regulatory clarity on upcycled concentrate approvals creates first-mover advantage for compliant exporters targeting functional food applications.
- Cellulose-rich pomace packaging substrates:Mycelium-molded protective packaging derived from fruit processing residues displaces expanded polystyrene in e-commerce fulfillment, capturing premium unit economics over compost.
- Precision fermentation scale-up:Convergence of synthetic biology platforms with organic acid synthesis from fruit sugars enables pharmaceutical-grade ingredient production from previously uneconomic waste fractions.
Industry Challenges
- Mycotoxin and pesticide bioaccumulation testing protocols:Evolving contaminant detection standards for circular feedstocks require continuous analytical method upgrades, stretching quality control budgets.
- Legacy food safety inspectorate training gaps:HACCP adaptation for waste-derived inputs demands specialized auditor competency development that outpaces current certification program rollout.
- Capital intensity of stabilization technology:Shelf-stable flour production from high-moisture brewers spent grain requires proprietary drying infrastructure that blocks mid-scale market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Products from Food Waste Market |
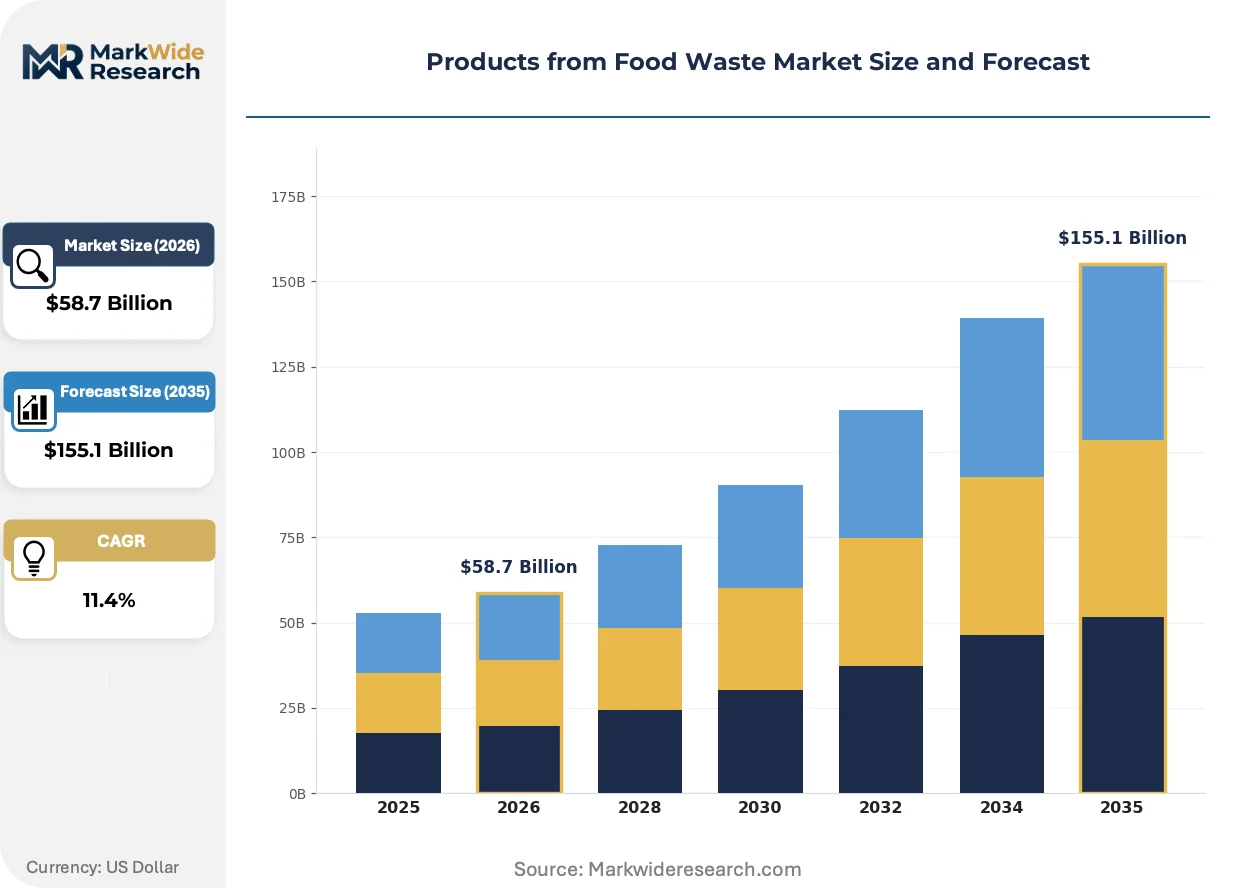
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Biofuels, Animal Feed, Packaging End User: Agriculture, Food Industry, Retail, Restaurants Application: Sustainability Initiatives, Waste Management, Energy Production, Nutrient Recovery Technology: Anaerobic Digestion, Fermentation, Enzymatic Treatment, Composting Methods |
| Companies Covered | Aeropowder, Bio-bean Ltd., Circular Systems S.P.C., Fruitcycle, GroCycle, ReGrained, Rise Products, Rubies in the Rubble, Renewal Mill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Products from Food Waste Market Strategic Shifts
Valorization technology maturation is compressing the gap between laboratory-scale protein recovery and commercial ingredient supply, reshaping how food processors conceptualize waste streams as input assets rather than disposal liabilities.
Mycelium propagation platforms is converging with precision-controlled fermentation systems to enable standardized protein concentrate production from heterogeneous organic residues. Pet food manufacturers and CPG formulators are adopting these inputs at pilot scale now, with commercial volumes projected to follow facility commissioning timelines. This convergence is compressing the traditional 18-month ingredient qualification cycle into 6-month validation windows.
The EU F-Gas Regulation on packaging alternatives compounds with EPA landfill diversion thresholds to create compliance-driven procurement pools in North America and Europe. Industrial buyers now embed upcycled substrate mandates into supplier scorecards, shifting RFP weighting toward circularity credentials. Foodservice distributors in the Netherlands and Germany respond fastest, integrating upcycled ingredient SKUs into centralized procurement catalogs ahead of mandated disclosure deadlines.
Certification-driven preference rotation now governs ingredient selection in premium pet nutrition and clean-label baking segments. Buyers substitute conventional fiber sources with defatted okara and oat pulp concentrates when third-party upcycling verification accompanies technical specifications. This rotation is most visible in Dutch retail channels and Pacific Northwest specialty food manufacturing clusters, where shelf placement and contract manufacturing decisions increasingly hinge on circularity documentation rather than price-point alone.
Products from Food Waste Market Segmentation
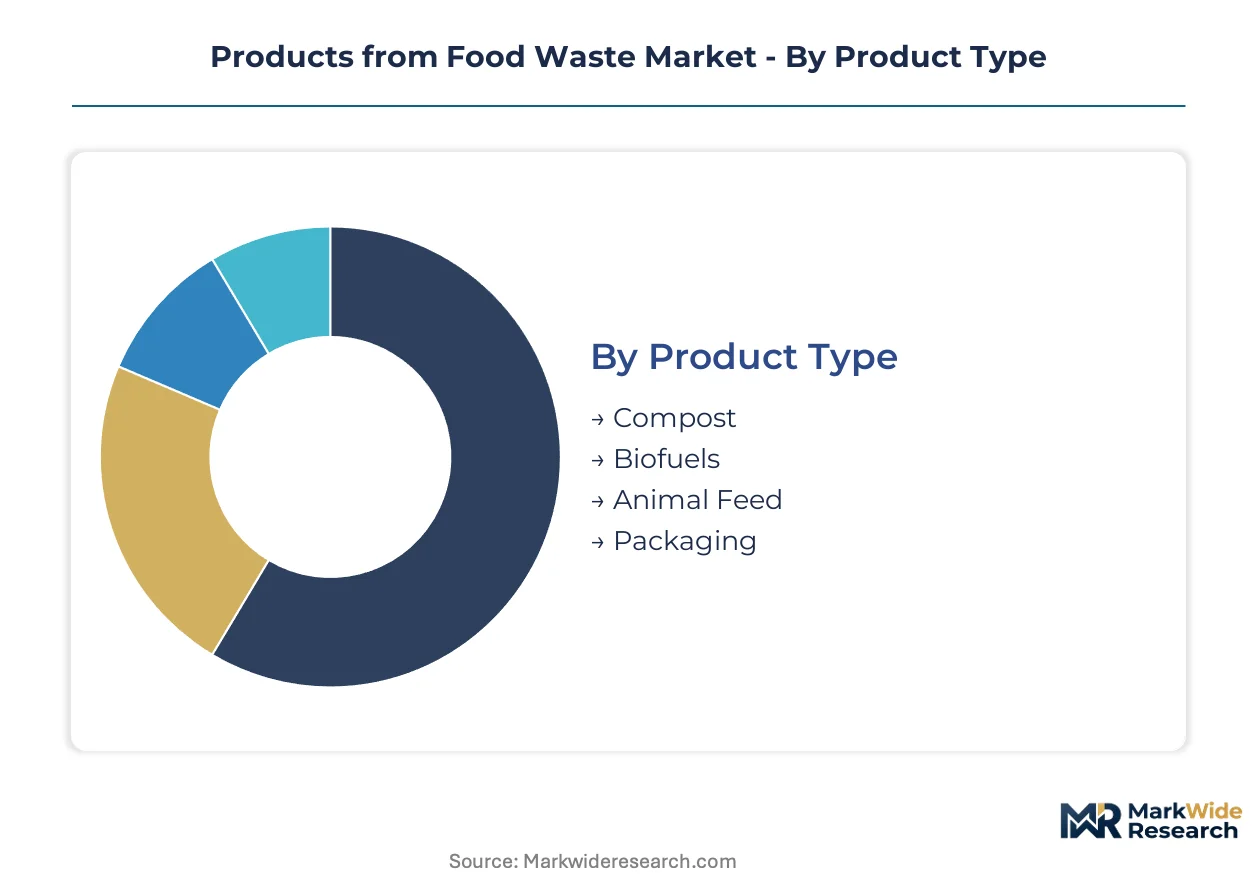
Segmentation in the Products from Food Waste Market reveals how valorization pathways align with distinct buyer economics and regulatory exposure. Each dimension exposes different margin structures, technology readiness thresholds, and compliance burdens that reshape competitive positioning across the value chain.
Product Type:
Buyers differentiate by end-use value capture and unit economics rather than feedstock origin alone.
- Animal Feed:Protein concentrates from brewers spent grain and fruit pomace deliver 15-40% protein recovery rates that stabilize pet food manufacturer margins against conventional meat meal cost inflation. Dutch and German processors dominate procurement catalogs through third-party upcycling verification.
- Packaging:Mycelium-molded substrates from cellulose-rich pomace displace expanded polystyrene in e-commerce fulfillment, commanding premium unit economics over compost through EU F-Gas Regulation compliance. Netherlands-based government incubators accelerate pilot-to-scale transitions for substrate startups.
- Compost:Volume leadership position with lower per-ton margins than upcycled alternatives; demand concentrates in agricultural belt soil amendment programs.
- Biofuels:Renewable natural gas offtake terms compress anaerobic digestion facility margins, limiting reinvestment capacity for technology upgrades.
Volume sits with Compost; growth tilts toward Packaging.
End User:
Procurement sophistication varies by sector-specific traceability requirements and circularity disclosure mandates.
- Food Industry:CPG formulators adopt upcycled protein concentrates at pilot scale now, with commercial volumes following facility commissioning timelines; ReGrained stabilization technology enables shelf-stable flour partnerships.
- Agriculture:Soil amendment buyers prioritize compost volume and transport cost optimization within 200-kilometer radii of fruit pomace and spent grain clusters.
- Retail:Centralized procurement catalogs in the Netherlands and Germany integrate upcycled ingredient SKUs ahead of mandated disclosure deadlines.
- Restaurants:Foodservice distributors respond fastest to certification-driven preference rotation when third-party upcycling verification accompanies technical specifications.
Procurement maturity peaks in Food Industry; Restaurants present the steepest expansion trajectory as disclosure mandates tighten.
Application:
Functional priorities separate compliance-driven buyers from value-optimizing adopters.
- Waste Management:EPA landfill diversion thresholds and EU Green Deal organic refuse valorization quotas redirect waste streams from disposal to ingredient recovery, expanding feedstock availability.
- Nutrient Recovery:Precision fermentation platforms enable pharmaceutical-grade ingredient production from previously uneconomic waste fractions through synthetic biology convergence.
- Energy Production:Anaerobic digestion dominates installed capacity but faces margin compression as renewable natural gas offtake terms tighten.
- Sustainability Initiatives:Industrial buyers embed upcycled substrate mandates into supplier scorecards, shifting RFP weighting toward circularity credentials.
Regulatory compliance drives Waste Management adoption; Nutrient Recovery is gaining share fastest through precision-controlled platforms.
Technology:
Capital intensity and scale economics determine processor technology selection and facility location strategy.
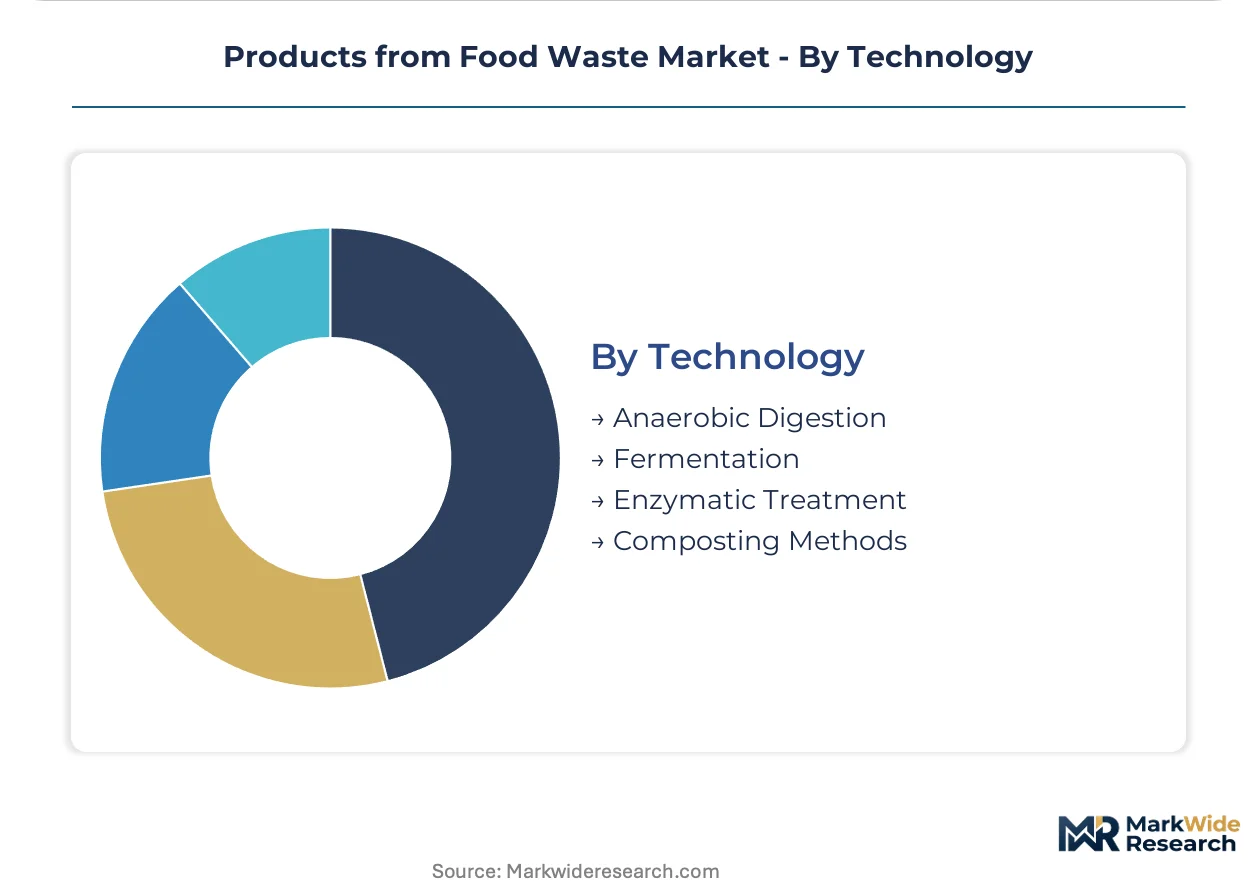
- Fermentation:Precision-controlled mycelium propagation and organic acid synthesis from fruit sugars accelerates fastest among technology categories, compressing 18-month ingredient qualification cycles into 6-month validation windows.
- Anaerobic Digestion:Installed capacity leader facing margin compression; tightened renewable natural gas contract terms squeeze facility economics and limit reinvestment.
- Enzymatic Treatment:Protein recovery rates and lignocellulosic fiber yields suitable for composite applications require continuous analytical method upgrades for mycotoxin and pesticide bioaccumulation detection.
- Composting Methods:Mature, low-capital pathway with uneven ISO 22000 and HACCP adaptation across inspectorates, fragmenting cross-border trade eligibility.
Installed base concentrates in Anaerobic Digestion; capital flows tilt toward Fermentation scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wageningen University's food innovation cluster anchors European concentration through government-backed incubators that compress commercialization timelines for upcycled ingredient startups. Tax-advantaged zones in the Netherlands accelerate pilot-to-scale transitions that reshape how processors valorize organic refuse across national borders.
Netherlands
Wageningen University clusters drive pet food manufacturer adoption of brewers spent grain concentrates. The EU Green Deal landfill diversion targets redirect organic refuse from disposal to ingredient recovery pipelines. Government incubators in Gelderland province accelerate commercialization of defatted okara and oat pulp fiber concentrates for gluten-free baking applications.
Germany
National landfill diversion mandates compel food processors to valorize fruit pomace rather than dispose of it. The country's federal packaging ordinance intersects with EU F-Gas Regulation compliance to create procurement pools for cellulose-rich substrate alternatives. Berlin-Brandenburg industrial zones anchor anaerobic digestion capacity expansion despite renewable natural gas offtake margin compression.
United States
EPA landfill diversion thresholds reshape procurement scorecards for CPG formulators seeking shelf-stable flour partnerships. California's SB 1383 organic waste regulations mandate 75% reduction in edible food disposal by 2025. Pacific Northwest specialty food manufacturing clusters adopt third-party upcycling verification ahead of mandated disclosure deadlines.
France
ANSM and national organic refuse valorization quotas redirect agricultural processing residues toward protein concentrate recovery. The country's agri-food regulatory framework tightens contaminant testing protocols for mycotoxin detection in circular feedstocks. Lyon and Auvergne-Rhône-Alpes industrial belts concentrate enzymatic treatment capacity for lignocellulosic fiber extraction.
India
FSSAI novel food ingredient approval pathways create market access friction for imported upcycled concentrates while opening first-mover advantage for compliant exporters. The country's PLI scheme for food processing infrastructure accelerates domestic valorization platform deployment. Maharashtra and Gujarat industrial corridors concentrate pilot-scale fermentation capacity for organic acid synthesis from fruit sugars.
Products from Food Waste Market Competitive Environment
Top-tier vendors anchor stabilization technology licensing, while mid-scale processors compete on feedstock procurement radius and transport cost optimization. The vendor base stratifies across proprietary drying infrastructure owners, precision fermentation platform operators, and regional compost volume leaders. Strategic archetypes include technology licensors with patent-protected stabilization methods, integrated processors with captive brewery and fruit processing partnerships, and contract manufacturers serving CPG qualification timelines. Dominant competitive moves encompass capacity expansion within 200-kilometer feedstock radii and strategic partnerships with pet food manufacturers seeking protein concentrate supply security.
Within the technology licensing tier, ReGrained and Renewal Mill occupy positions that exemplify proprietary stabilization approaches to high-moisture feedstock processing. Bio-bean Ltd. represents the industrial waste stream anchoring archetype through pyrolysis-derived output categories. These three entities illustrate how geographic concentration in brewing and fruit processing belts shapes competitive positioning without requiring vertical integration into upstream agriculture.
| Leading Market Players |
|---|
| Aeropowder |
| Bio-bean Ltd. |
| Circular Systems S.P.C. |
| Fruitcycle |
| GroCycle |
| ReGrained |
| Rise Products |
| Rubies in the Rubble |
| Renewal Mill |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation scale-up simultaneously compresses ingredient qualification timelines and concentrates production economics in facilities with synthetic biology platform control. This technology transition redirects margin capture toward processors with proprietary stabilization infrastructure while fragmenting feedstock procurement across agricultural belt clusters.
Pricing Analysis
Short lead-time premiums attach to mycelium-molded packaging substrates qualifying under EU F-Gas Regulation compliance windows, while spot inventory of compost-grade outputs trades at discounts. Contract-based long-term offtake dominates protein concentrate procurement, with price differentiation hinging on third-party upcycling verification and transport radius within 200-kilometer feedstock clusters. Cost compression in anaerobic digestion-derived biofuels is intensifying because renewable natural gas contract terms tightened. Pet food manufacturers show least price sensitivity due to margin stabilization needs, while agricultural compost buyers exhibit highest elasticity to per-ton delivered costs.
Supply Chain Analysis
Dual-sourcing requirements now govern CPG formulator procurement, with buyers mandating multi-supplier qualification for brewers spent grain and fruit pomace concentrates to mitigate single-source vulnerability. Geographic supply concentrates in the Netherlands, Germany, and the United States, where Wageningen University clusters, federal packaging ordinances, and EPA landfill diversion thresholds respectively anchor production. Raw material dependencies center on barley malting byproducts, citrus and apple processing residues, and coffee roasting waste streams. Distribution runs through government-backed incubators in Gelderland province and Pacific Northwest specialty food manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where precision-controlled fermentation platforms displace legacy anaerobic digestion for higher-margin ingredient categories.
For Market Incumbents: Acquire proprietary stabilization technology assets to block mid-scale entrants from shelf-stable flour production. Defensive consolidation demands captive brewery partnerships in Germany and the Netherlands, plus ISO 22000 certification investment to preempt inspectorate fragmentation. Threat substitution from mycelium propagation platforms compresses traditional protein recovery margins. For New Entrants and Emerging Players: Foodservice distributors in the Netherlands present the most penetrable channel partner type, with certification-driven preference rotation creating white-space for third-party verified concentrates. Target India's FSSAI novel food ingredient pathway for functional food applications, exploiting regulatory clarity gaps that delay imported concentrate market access. Go-to-market leverage rests on pilot-to-scale acceleration through government incubator partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by CPG formulators seeking backward integration into circular feedstock security. Long-term viability favors precision fermentation platform operators with pharmaceutical-grade organic acid synthesis capability. Watch mycotoxin detection protocol evolution as inflection indicator for quality control budget escalation and trade eligibility fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Partnerships | Captive supply of brewers spent grain from Heineken and Anheuser-Busch InBev facilities secures volume commitment. |
| Precision Fermentation Scale-Up | Synthetic biology convergence with Wageningen University research clusters accelerates mycelium propagation commercialization. |
| Third-Party Upcycling Certification Investment | ISO 22000 and HACCP adaptation for waste-derived inputs unlocks Dutch and German retail channel access. |
| Geographic Capacity Expansion | Facility commissioning within 200-kilometer radii of fruit pomace clusters in France and Spain optimizes transport economics. |
| Regulatory Compliance Pathway Development | FSSAI novel food ingredient approval navigation creates first-mover positioning in India's functional food import market. |
Study Parameters
Multi-period observation of anaerobic digestion margin compression, fermentation capacity buildout, and certification program rollout anchored the trend analysis, supplemented by interviews with pet food formulation directors, CPG procurement managers, government incubator program officers, and specialty food manufacturing cluster executives. Secondary validation drew from EPA landfill diversion filings, EU Green Deal implementation progress reports, FSSAI novel food ingredient approval databases, and Wageningen University commercialization output disclosures. Bottom-up facility capacity modeling and top-down regulatory impact assessment enabled triangulation across valorization technology categories.
Segment-weighting approaches applied differential growth assumptions across fermentation, anaerobic digestion, enzymatic treatment, and composting methods, with cross-dimensional analysis of product type, end user, application, and technology readiness thresholds. Modeled dimensions included protein recovery rate tiers, packaging substrate compliance grades, nutrient recovery purity levels, and energy production offtake contract structures. CAGRs were derived from feedstock availability projections, facility commissioning timelines, and regulatory mandate phase-in schedules across the analysis window.
Caveats apply where renewable natural gas contract renegotiation, mycotoxin detection standard escalation, or FSSAI approval timeline extension could materially shift the outlook. Deviation in EU F-Gas Regulation enforcement intensity or EPA landfill diversion threshold adjustment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Vegan Eggs Market