
 Asia-Pacific Nutraceutical Excipients Market | 2026-2036
Asia-Pacific Nutraceutical Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nutraceutical Excipients Market Outlook
Modular excipient bundling is decoupling from traditional all-in-one supplier contracts across the Asia-Pacific nutraceutical sector. BASF leverages its polymer science heritage to anchor high-performance coating systems for tablet manufacturers in Japan and Southeast Asia. Roquette competes through plant-based filler specialization, while Cargill, Incorporated extends its starch-derived excipient portfolio to serve clean-label powder formulations.
Nutraceutical excipients comprise pharmacologically inactive substances formulated with active nutraceutical compounds to enhance stability, bioavailability, processing characteristics, and finished-product performance in dosage forms such as tablets, capsules, and liquid suspensions. These materials typically meet compendial standards for moisture content, particle size distribution, and flow properties to ensure batch-to-batch consistency during high-speed manufacturing. Fillers and binders occupy the largest volume share within product type segments, driven by universal application across solid oral dosage forms. Coatings represent the fastest-expanding category as delayed-release and taste-masking technologies gain traction in functional foods and sports nutrition applications across the region.
India's FSSAI, Australia's TGA, and China's NMPA each enforce distinct purity and labeling standards that shape excipient qualification protocols and import documentation burdens for cross-border suppliers. Japan's MHLW through PMDA oversight adds additional layers of novel food contact substance review, particularly for innovative capsule shell polymers and enteric coating materials. Stakeholders must monitor divergent regulatory timetables for excipient master file harmonization while building flexible formulation pipelines capable of adapting to multiple national pre-approval requirements without redundant development cycles.
Market Dynamics
Clean-label formulation mandates across Asia-Pacific are forcing excipient suppliers to abandon synthetic binders and coatings in favor of plant-derived alternatives certified under multiple national food safety regimes.
Growth Catalysts
- India's FSSAI purity standards:Domestic supplement manufacturers in Hyderabad and Mumbai corridors now require compendial-grade excipients, creating captive demand for local producers scaling GMP-certified output.
- Sports nutrition clean-label pivot:Australian and South Korean brands are accelerating capsule-grade binder procurement as revised food safety codes tighten additive disclosure requirements.
- Delayed-release coating technology:Enteric polymers enabling taste-masking and targeted intestinal release are expanding application scope in functional foods across Japan and Southeast Asia.
Market Restraints
- Starch derivative input volatility:Maize and tapioca supply fluctuations in Thailand and Indonesia compress margins for plant-based filler specialists dependent on agricultural commodity cycles.
- Regulatory documentation fragmentation:Divergent excipient master file requirements between Australia's TGA, China's NMPA, and Japan's PMDA impose redundant qualification burdens on cross-border suppliers.
- Synthetic polymer substitution ceiling:Performance gaps in moisture barrier properties limit complete displacement of petroleum-derived coatings in high-humidity storage conditions.
Strategic Opportunities
- Vietnam and Indonesia manufacturing corridors:Underpenetrated dietary supplement production clusters offer first-mover positioning for excipient distributors establishing regional blending facilities.
- PLI scheme alignment in India:Production-linked incentive frameworks for pharmaceutical and nutraceutical manufacturing create procurement pull for domestic excipient capacity expansion.
- E-commerce direct sourcing:Powder supplement brands in South Korea are bypassing traditional distributor tiers to contract directly with excipient manufacturers for custom granulation services.
Industry Challenges
- Novel polymer toxicology dossier preparation:Japan's MHLW requires extensive food contact substance reviews for innovative capsule shell materials, extending commercialization timelines by 18-24 months.
- Multi-site GMP audit coordination:Excipient suppliers serving both pharmaceutical contractors and nutraceutical brands must maintain simultaneous compliance with IPEC-PQG and national food GMP standards.
- Particle engineering talent scarcity:Formulation science expertise in controlled-release matrix design concentrates in legacy pharmaceutical hubs, constraining regional clean-label innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nutraceutical Excipients Market |
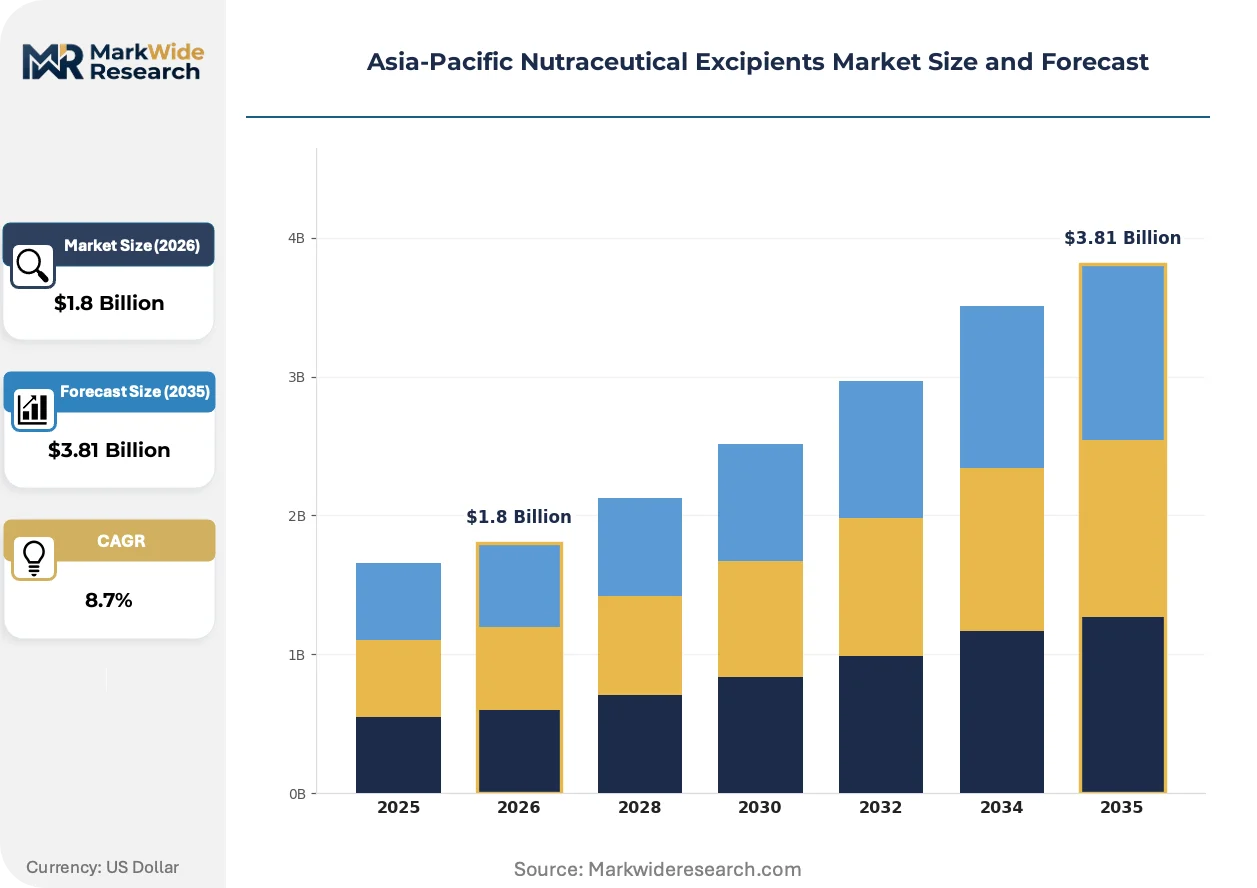
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Fillers, Disintegrants, Coatings Delivery Mode: Capsules, Tablets, Powders, Liquid End User: Pharmaceuticals, Dietary Supplements, Functional Foods, Animal Nutrition Application: Health Supplements, Weight Management, Sports Nutrition, Energy Products |
| Companies Covered | Barentz, BASF, SPI Pharma, BEHN MEYER, JRS PHARMA, DuPont, Cargill, Incorporated, Roquette, Dow, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nutraceutical Excipients Market Strategic Shifts
Functional coating systems and plant-derived polymer platforms are displacing conventional excipient categories as Asia-Pacific manufacturers pursue differentiated dosage form performance.
Hydroxypropyl methylcellulose (HPMC) based delayed-release coatings are rewriting the competitive terrain for tablet and capsule manufacturers. Japanese nutraceutical brands are adopting these enteric systems at accelerated pace to enable probiotic viability through gastric transit. The technology is compressing the addressable market for traditional gelatin capsule shells while expanding formulation possibilities for acid-sensitive active ingredients.
China's NMPA implementation of enhanced excipient registration requirements for imported dietary supplements is tightening qualification protocols for cross-border suppliers. The policy shift forces foreign manufacturers to establish local technical documentation capabilities or partner with domestic filing agents. Powder and liquid formulation categories face the steepest compliance ramps as novel food contact substance reviews expand beyond traditional pharmaceutical excipient scopes.
Ingredient sourcing decisions in Australia's sports nutrition segment now prioritize TGA-registered excipient grades over uncertified alternatives regardless of unit cost differentials. Brand procurement teams are consolidating supplier relationships toward dual-use pharmaceutical-nutraceutical excipient houses capable of providing batch-specific CoA documentation. This certification-driven preference shift is most visible in Melbourne and Sydney contract manufacturing facilities serving export-oriented clean-label brands.
Asia-Pacific Nutraceutical Excipients Market Segmentation
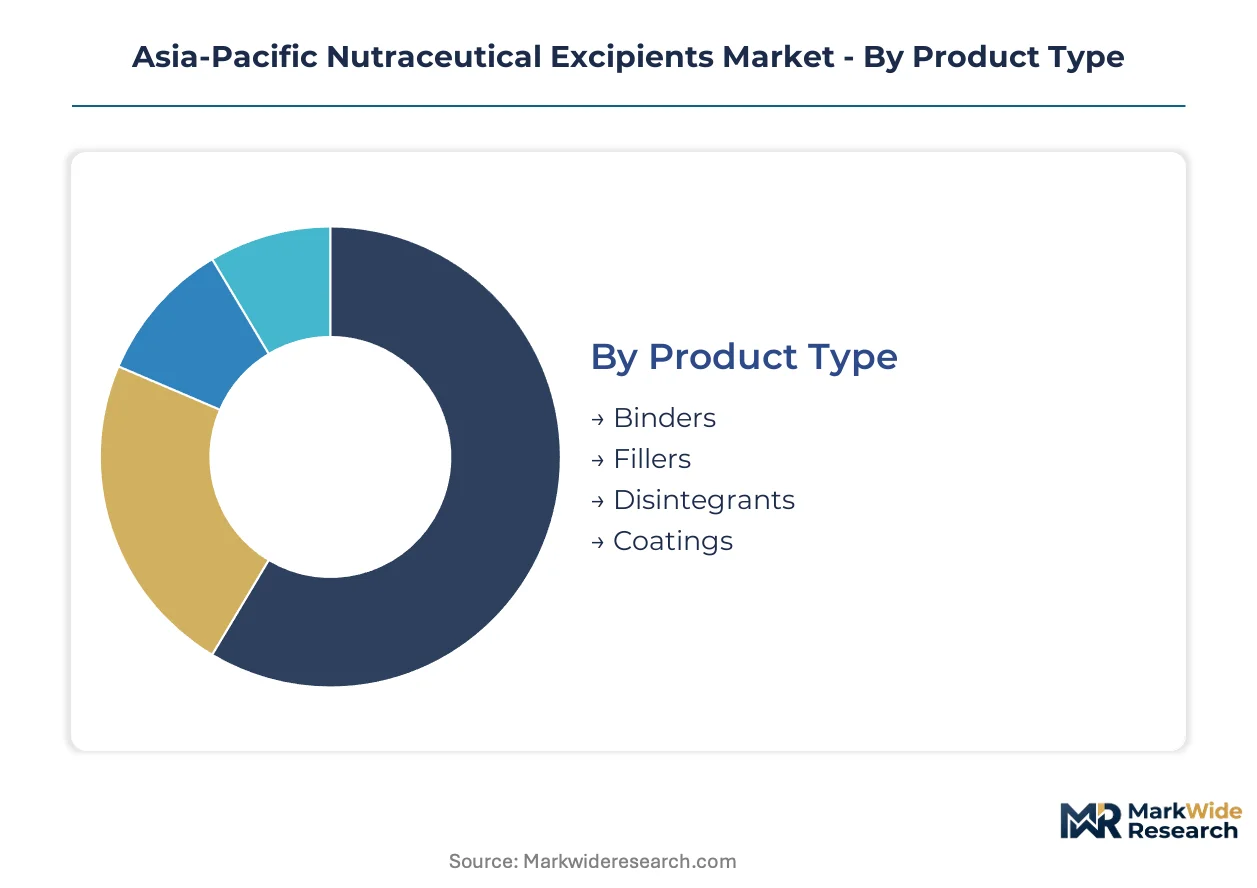
Excipient procurement decisions in Asia-Pacific diverge sharply across dosage form requirements and end-use regulatory burdens. Manufacturers configure supply contracts around performance specifications that vary by delivery mode and national food safety codes.
Product Type:
Formulation scientists prioritize functional performance over unit cost when selecting from this category.
- Binders:These agents provide structural integrity to solid dosage forms through adhesive and cohesive properties. Demand concentrates in Hyderabad and Mumbai manufacturing corridors where India's FSSAI purity standards compel domestic supplement brands to source compendial-grade materials.
- Fillers:Inert bulking agents adjust tablet weight and capsule fill volume while maintaining flow characteristics. Australian and South Korean sports nutrition brands are accelerating procurement of plant-derived alternatives as revised food safety codes tighten additive disclosure requirements.
- Disintegrants:Substances promoting rapid tablet breakup upon contact with aqueous media.
- Coatings:Functional layers enabling delayed-release, taste-masking, and moisture protection.
Volume sits with fillers; growth tilts toward coatings.
Delivery Mode:
Equipment compatibility and clean-label positioning drive selection across manufacturing facilities.
- Capsules:Gelatin and HPMC shells offer unit-dose convenience with rapid dissolution profiles. Japanese nutraceutical brands are adopting enteric polymer systems at accelerated pace to enable probiotic viability through gastric transit.
- Tablets:Compressed solid forms dominate high-volume production economics. Powder supplement brands in South Korea are bypassing traditional distributor tiers to contract directly with excipient manufacturers for custom granulation services.
- Powders:Bulk blends serving functional food and beverage applications.
- Liquid:Suspensions and solutions requiring viscosity-modifying excipients.
Tablets command the largest share; capsules are expanding most quickly.
End User:
Regulatory classification determines qualification protocols and documentation burdens for excipient suppliers.
- Pharmaceuticals:Drug-grade applications demanding IPEC-PQG compliance and extensive CoA documentation. China's NMPA implementation of enhanced excipient registration requirements is tightening qualification protocols for cross-border suppliers.
- Dietary Supplements:Health product formulations operating under food GMP frameworks. Vietnam and Indonesia manufacturing corridors offer first-mover positioning for excipient distributors establishing regional blending facilities.
- Functional Foods:Fortified products with excipient roles in texture and stability.
- Animal Nutrition:Veterinary supplement applications with distinct purity specifications.
Pharmaceuticals absorb the most volume; dietary supplements are gaining share fastest.
Application:
Consumer positioning and channel requirements shape excipient performance specifications.
- Health Supplements:General wellness products emphasizing bioavailability enhancement. India's PLI scheme alignment for pharmaceutical and nutraceutical manufacturing creates procurement pull for domestic excipient capacity expansion.
- Sports Nutrition:Performance-oriented formulations with clean-label imperatives. Melbourne and Sydney contract manufacturing facilities serving export-oriented brands now prioritize TGA-registered excipient grades regardless of unit cost differentials.
- Weight Management:Calorie-controlled and satiety-enhancing products.
- Energy Products:Stimulant and metabolic support formulations.
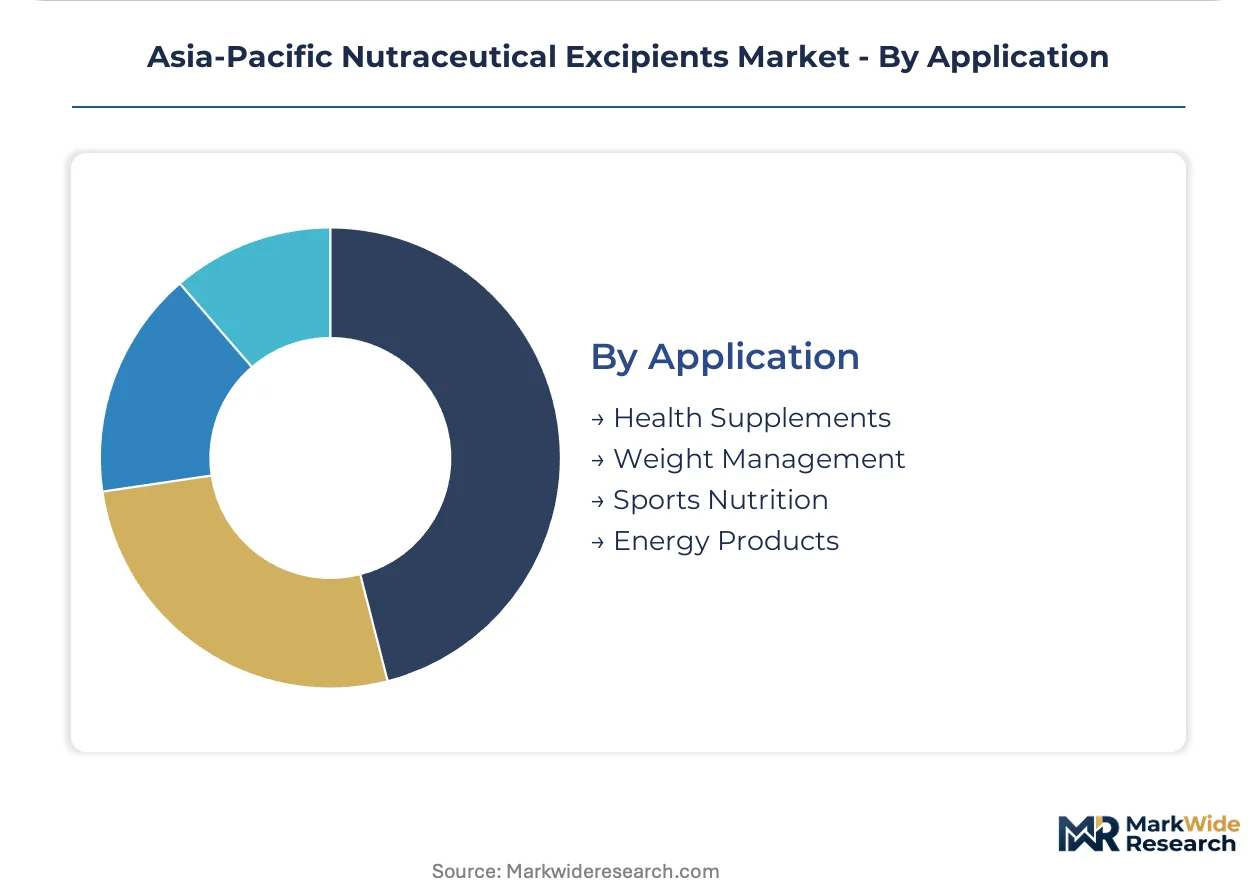
Health supplements dominate current volume; sports nutrition shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's excipient production corridors now supply domestic dietary supplement manufacturers and pharmaceutical contractors, while Japan and Australia drive premium-grade consumption. Consumption gravity pulls toward regulatory-stringent markets, but manufacturing scale concentrates where cost structures and government incentives align.
India
Hyderabad and Mumbai manufacturing corridors generate captive demand for compendial-grade binders and fillers as domestic supplement brands scale output. FSSAI purity standards compel manufacturers to source certified materials, eliminating uncertified alternatives from procurement lists. Production-linked incentive frameworks for pharmaceutical and nutraceutical manufacturing create procurement pull for domestic excipient capacity expansion across Telangana and Maharashtra.
Japan
Probiotic and acid-sensitive active ingredient formulations accelerate adoption of HPMC-based enteric coating systems. MHLW through PMDA oversight imposes extensive food contact substance reviews for innovative capsule shell polymers, extending commercialization timelines. Kanto region tablet and capsule manufacturers prioritize delayed-release technologies that enable viability through gastric transit.
Australia
Melbourne and Sydney contract manufacturing facilities serving export-oriented sports nutrition brands now prioritize TGA-registered excipient grades regardless of unit cost differentials. Revised food safety codes tighten additive disclosure requirements, forcing procurement teams to consolidate supplier relationships toward dual-use pharmaceutical-nutraceutical houses. Certification-driven preference shifts eliminate uncertified alternatives from consideration sets.
South Korea
Seoul-based powder supplement brands bypass traditional distributor tiers to contract directly with excipient manufacturers for custom granulation services. MFDS registration requirements shape qualification protocols for cross-border suppliers entering the dietary supplement segment. Capsule-grade binder procurement accelerates as clean-label formulation mandates tighten across domestic sports nutrition portfolios.
China
NMPA implementation of enhanced excipient registration requirements for imported dietary supplements tightens qualification protocols for cross-border suppliers. Foreign manufacturers must establish local technical documentation capabilities or partner with domestic filing agents. Yangtze River Delta manufacturing clusters face the steepest compliance ramps as novel food contact substance reviews expand beyond traditional pharmaceutical excipient scopes.
Asia-Pacific Nutraceutical Excipients Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific nutraceutical excipients sector. The vendor base organizes into three tiers: global chemical conglomerates with polymer science heritage, plant-based ingredient specialists with agricultural supply chain integration, and regional distributors with formulation technical service capabilities. Market structure rewards simultaneous compliance with IPEC-PQG pharmaceutical standards and national food GMP frameworks. Competitive moves concentrate on regional blending facility establishment and direct e-commerce sourcing channel development.
Within the diversified chemical conglomerate tier, BASF and Dow occupy positions anchored by polymer science capabilities serving coating and controlled-release applications. Roquette and Cargill, Incorporated exemplify the plant-derived specialization archetype, leveraging agricultural commodity processing heritage into clean-label filler and binder portfolios. JRS PHARMA represents the focused pharmaceutical-nutraceutical hybrid model, maintaining dual-use certification capabilities that satisfy both drug-grade and food-grade procurement requirements across the region.
| Leading Market Players |
|---|
| Barentz |
| BASF |
| SPI Pharma |
| BEHN MEYER |
| JRS PHARMA |
| DuPont |
| Cargill, Incorporated |
| Roquette |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical contract manufacturers in India's Hyderabad and Mumbai corridors anchor pricing power through volume consolidation, driving tiered structures that separate compendial-grade excipients from uncertified alternatives. This buyer concentration enables domestic suppliers to command premiums for FSSAI-certified materials while imported grades face cost-down pressure.
Pricing Analysis
Margin tightening in standard-grade binders traces to starch derivative input volatility across Thailand and Indonesia agricultural markets. Three-tier pricing structure across compendial-certified, food-grade, and technical-grade levels separates procurement tiers by documentation burden and purity specification. Cost-down pressure on uncertified imports accelerates because domestic Indian capacity expansion under PLI schemes narrows quality gaps. Dietary supplement manufacturers show highest price sensitivity, while pharmaceutical contractors prioritize certification compliance over unit cost differentials.
Supply Chain Analysis
Dual-sourcing mandates from Japanese and Australian pharmaceutical-nutraceutical hybrid manufacturers require excipient suppliers to maintain redundant qualification dossiers across multiple production sites. Geographic supply concentration centers on India, China, and Thailand for plant-derived fillers and binders. Raw material dependencies rest on maize and tapioca starch streams, petroleum-derived coating polymers, and HPMC cellulose ethers. Single-source vulnerability emerges from novel polymer toxicology dossier preparation bottlenecks under Japan's MHLW review timelines. Distribution runs through regional blending facilities serving contract manufacturing clusters with direct technical service support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compendial-grade excipient capacity scarcity across Asia-Pacific props pricing premiums, constraining rapid market entry for uncertified suppliers. This supply bottleneck favors incumbents with established dual-use pharmaceutical-food GMP compliance.
For Market Incumbents: Anchor defensive positioning through backward integration into starch processing and captive HPMC polymer production, neutralizing agricultural commodity volatility. Secure IPEC-PQG certification maintenance across multi-site manufacturing networks to defend against emerging plant-based specialists with narrower compliance scopes. Prioritize technical documentation localization in China to preempt NMPA registration requirement tightening. For New Entrants and Emerging Players: Begin with Vietnam and Indonesia dietary supplement manufacturing corridors, where underpenetrated production clusters lack established excipient blending infrastructure. Target direct e-commerce sourcing relationships with Seoul-based powder supplement brands seeking custom granulation services, bypassing traditional distributor markups. Lead with plant-derived binder specialization certified under multiple national food safety regimes to exploit clean-label formulation mandates. For Investors and Strategic Acquirers: The window for entry favors dual-use pharmaceutical-nutraceutical excipient houses with simultaneous IPEC-PQG and national food GMP compliance capabilities. Long-term viability rests on acquisition targets with established toxicology dossiers for novel capsule shell polymers, compressing Japan MHLW commercialization timelines. Watch for PLI scheme capacity expansion announcements in Telangana and Maharashtra as inflection indicators for domestic Indian supply-demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Blending Facility Establishment | Vietnam and Indonesia corridors gain first-mover positioning for underpenetrated dietary supplement production. |
| Backward Integration into Starch Processing | Maize and tapioca supply volatility in Thailand compresses margins for plant-based filler specialists without upstream control. |
| Dual-Use Certification Investment | Simultaneous IPEC-PQG pharmaceutical and food GMP compliance satisfies Melbourne and Sydney contract manufacturing procurement consolidation. |
| Direct E-Commerce Sourcing Channel | Seoul powder supplement brands bypass traditional distributor tiers for custom granulation services. |
| Local Technical Documentation Capability | China NMPA enhanced registration requirements force foreign manufacturers to establish domestic filing partnerships. |
Study Parameters
Trade databases, customs records, and national pharmaceutical regulator filings formed the secondary backbone, cross-referenced with primary interviews involving excipient procurement managers at dietary supplement manufacturers, technical directors at plant-derived ingredient specialists, regulatory affairs leads navigating FSSAI and NMPA registration pathways, and distribution channel partners across Asia-Pacific blending facilities. Bottom-up volume modeling triangulated against top-down market sizing across product type, delivery mode, and end-user segmentation dimensions.
Historical trendline analysis established baseline growth patterns across the projection horizon, with analytical framework incorporating dosage form compatibility requirements, clean-label certification tier adoption curves, and regional regulatory cluster divergence. CAGRs derived from segmented growth rate application weighted by baseline volume shares. Industry-specific forecast inputs included PLI scheme capacity expansion timelines in India and novel food contact substance review queue depths under Japan's MHLW.
Underlying measurement precision varies by segment; pharmaceutical-grade excipient volumes carry tighter precision than dietary supplement categories with fragmented manufacturer bases. Forecasts reflect assumptions around regulatory timetable harmonization and agricultural commodity price stabilization. A model refresh is warranted upon material change in China NMPA excipient registration enforcement intensity or India PLI scheme capacity commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Austria Protein Supplements Market