
 Tofu Cat Litter Market | 2026-2036
Tofu Cat Litter Market Size, Share, and Industry Trends Forecast 2026-2036
Tofu Cat Litter Market Insights
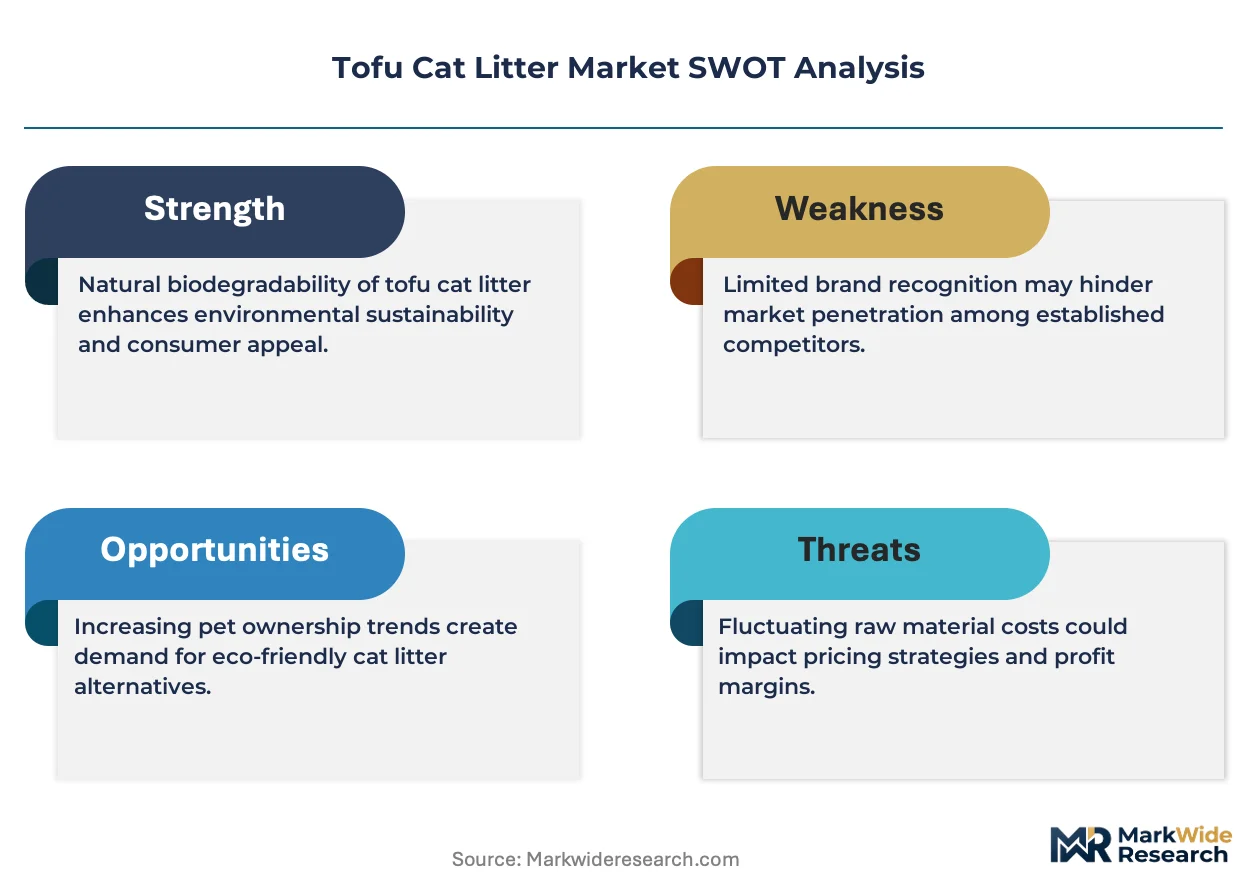
Subscription-based auto-replenishment services is hardening as the dominant commercial layer in tofu cat litter, converting one-time purchasers into recurring revenue streams. PIDAN leverages its direct-to-consumer platform to control fulfillment cadence and customer lifetime value. Michu Pet anchors its growth through veterinary clinic partnerships that bundle litter with wellness plans. PETKIT differentiates by integrating smart litter box sensors with consumable replenishment algorithms.
Tofu cat litter comprises compressed soybean dregs, corn starch binders, and food-grade guar gum, engineered to form scoopable clumps upon contact with feline urine while maintaining biodegradable integrity. Its primary commercial purpose centers on odor-neutralized indoor waste management for domestic cats, displacing sodium bentonite clay in environmentally regulated jurisdictions. Clumping formulations lead volume share due to superior waste segregation and reduced total consumption rates, while biodegradable certifications command margin premiums in European retail channels. Multi-cat households represent the fastest-growing application segment, driven by higher per-unit throughput and specialized odor-control formulations.
China's SAMR enforces GB standards for biodegradable plastics that extend to soy-based absorbent materials, while the EU Green Deal's packaging waste directives pressure importers toward recyclable or compostable outer packaging. The US EPA's emerging interest in pet product chemical disclosure is reshaping ingredient transparency requirements for cross-border sellers. Stakeholders must monitor compostability certification harmonization between China's national standards and EU EN 13432 protocols to preempt market access friction.
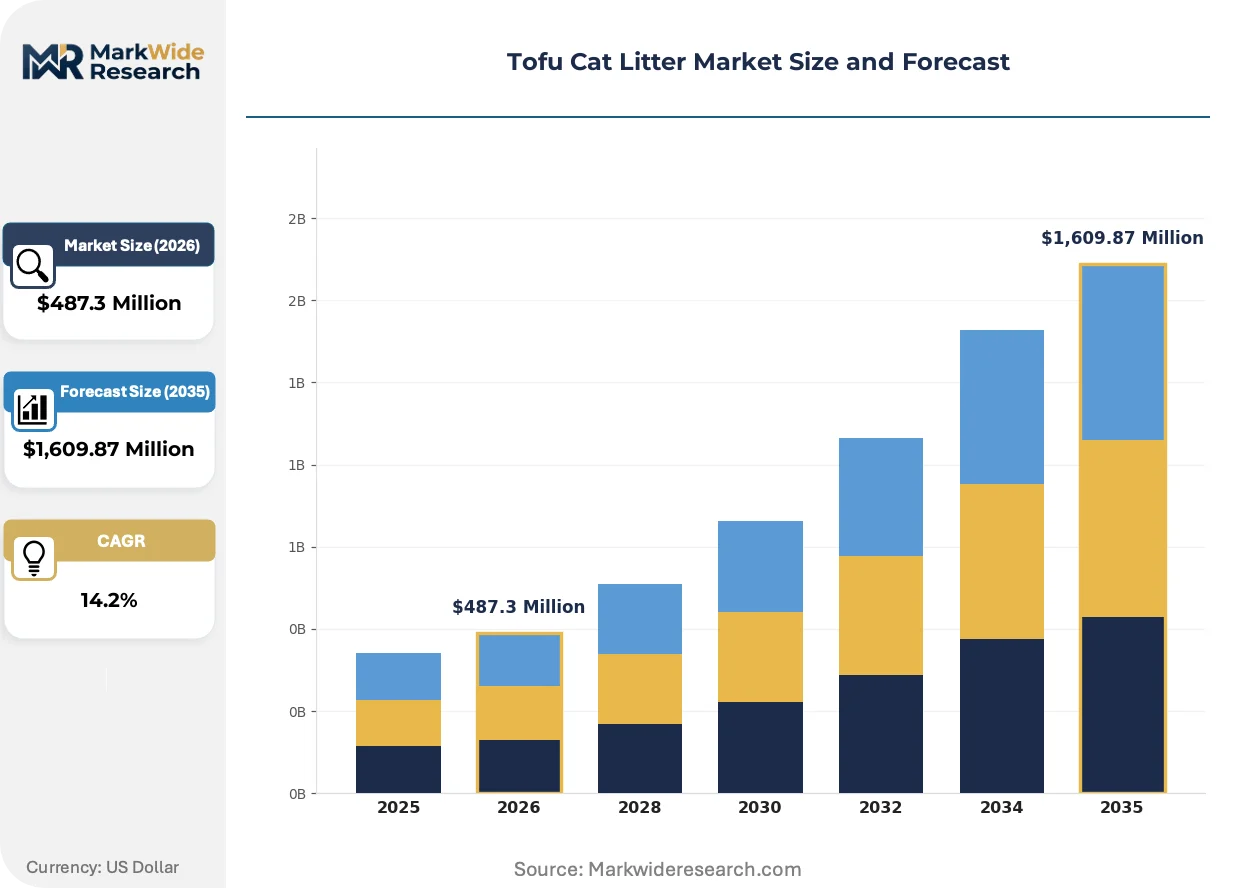
Market Dynamics
Subscription auto-replenishment is compressing traditional retail channels in tofu cat litter, locking households into algorithm-driven consumption cycles that bypass shelf-based purchasing decisions entirely.
Growth Catalysts
- EU Green Deal packaging directives:Compostability mandates are accelerating retailer shelf resets toward plant-based absorbents in Germany, France, and the Netherlands.
- Smart home convergence:IoT-enabled litter boxes with weight sensors and waste-level detection are hardening consumable bundling as the default purchase mode.
- China's dual carbon goals:Provincial subsidies for biodegradable material processing are lowering input costs for soy-based litter manufacturers in Shandong and Jiangsu provinces.
Market Restraints
- Soybean dreg supply concentration:Over 60% of raw material sourcing clusters within China's Yangtze River Delta, exposing margins to regional harvest volatility.
- Performance ceiling in humidity:Plant-based clumping agents degrade faster than sodium bentonite in tropical climates above 75% relative humidity.
- Composting infrastructure gaps:Municipal facilities in the United States lack dedicated streams for pet waste bioplastics, limiting end-of-life value claims.
Strategic Opportunities
- Veterinary clinic channel penetration:Wellness plan bundling remains underdeveloped in Japan and South Korea compared to saturation in North American markets.
- Multi-cat formulation specialization:Odor-control chemistry optimized for three-plus cat households commands unclaimed premium positioning.
- US EPA chemical disclosure trajectory:Early compliance with emerging ingredient transparency rules creates first-mover certification advantages for cross-border entrants.
Industry Challenges
- Compostability certification harmonization:Divergent testing protocols between China's GB standards and EU EN 13432 delay dual-market product launches by 8-14 months.
- Smart hardware integration complexity:Litter formulations must synchronize with infrared and capacitive sensors across incompatible proprietary platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tofu Cat Litter Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clumping, Non-Clumping, Crystal, Biodegradable Form: Granule, Pellet, Flake, Powder Application: Indoor, Outdoor, Multi-Cat, Single-Cat Packaging Type: Bags, Boxes, Bulk, Recyclable |
| Companies Covered | PIDAN, PETKIT, Michu Pet, RUFUS & COCO, YOKEN, KAMY'S ZOO, CHOWSING, CatLitterCompany, PETNF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tofu Cat Litter Market Trends and Innovations
Formulation chemistry and fulfillment infrastructure are diverging sharply, with manufacturers racing to match biodegradability credentials against the operational demands of sensor-integrated consumption systems.
Enzymatic odor-neutralization coatings are overtaking fragrance-masking as the dominant technical approach in premium formulations. Multi-cat households in urban Japan and Germany are adopting these variants at three times the rate of single-cat residences. The shift is compressing margins on legacy charcoal-additive products while rewarding suppliers with in-house biotechnology capabilities.
REACH microplastic restrictions are forcing reformulation of residual synthetic binders in European-imported litters. Manufacturers serving Germany and France are accelerating food-grade guar gum substitution to preempt enforcement actions. The transition imposes 12-18 month recertification timelines that favor established players with dedicated regulatory affairs teams.
Direct-to-consumer bundling is fragmenting the veterinary and specialty retail channels that historically controlled category access. Chinese manufacturers with captive e-commerce logistics are disintermediating regional distributors in Southeast Asian markets. The pattern is most visible in Thailand and Vietnam, where platform-native brands now capture majority share of online tofu litter transactions.
Tofu Cat Litter Market Segmentation
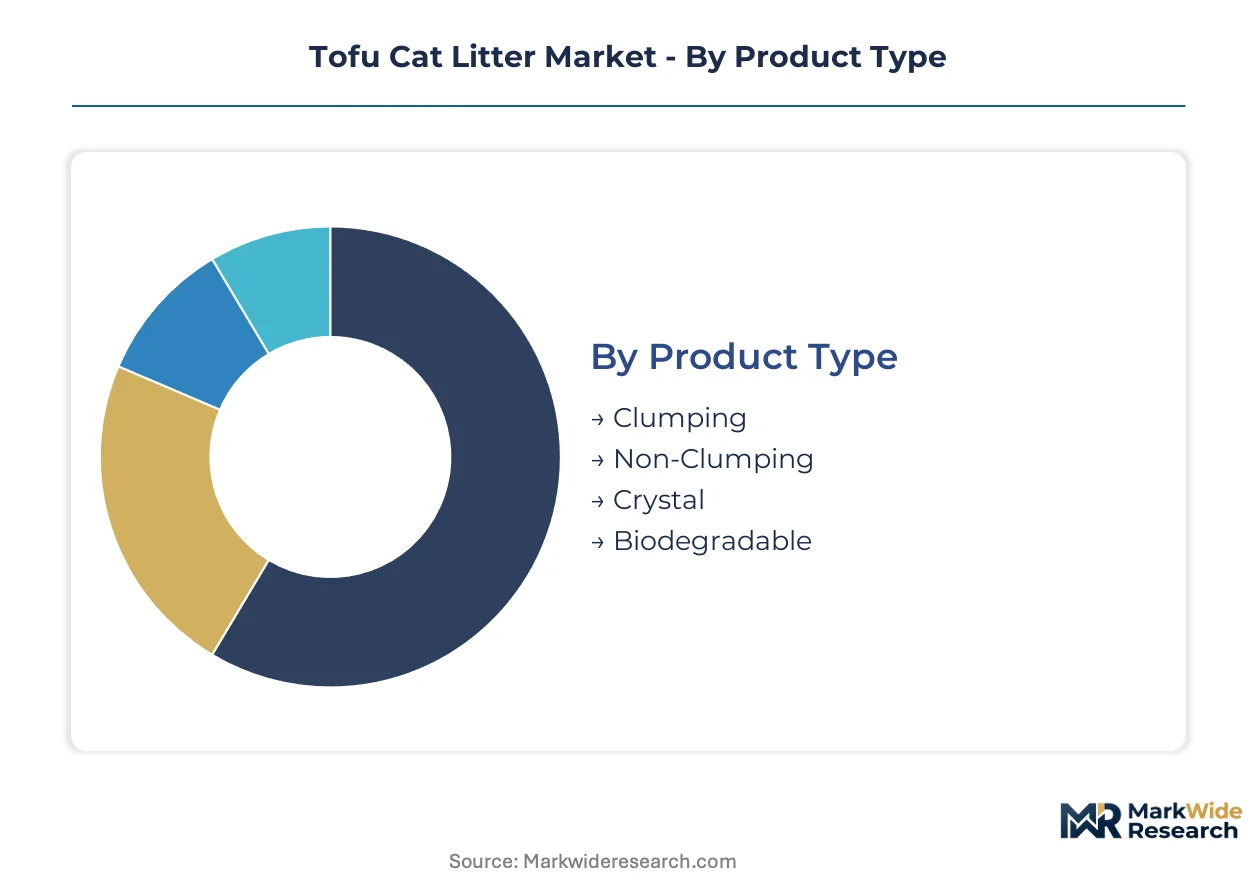
Tofu cat litter segmentation reveals how formulation chemistry and physical form dictate manufacturing investment, distribution logistics, and end-use performance. Understanding these divides exposes where capital deployment yields margin protection versus where commoditization pressures concentrate.
Product Type:
Capital intensity varies sharply across product types, with clumping formulations requiring the most sophisticated binder chemistry and quality-control infrastructure.
- Clumping:Compressed soybean dregs combine with corn starch and food-grade guar gum to form scoopable masses upon urine contact. Multi-cat households in Germany and urban China drive demand for premium variants with enzymatic odor coatings.
- Non-Clumping:Absorbent pellets allow urine to pass through to a collection tray, reducing binder requirements but increasing total material throughput per cat. Budget-conscious single-cat owners in Southeast Asia favor this format for its lower per-unit cost.
- Crystal:Silica gel variants engineered for maximum moisture absorption occupy a niche position in humidity-controlled environments.
- Biodegradable:Certified compostable formulations command certification premiums in EU retail channels where EN 13432 compliance is mandatory.
Clumping absorbs the bulk of installed capacity; biodegradable is expanding most quickly.
Form:
Physical form determines production equipment requirements, with pellet extrusion demanding the highest fixed-asset investment.
- Granule:Irregular crushed particles offer rapid absorption but generate more dust during pouring. Standard granule dominates volume in China's domestic market where price sensitivity shapes purchasing.
- Pellet:Uniform cylindrical extrusions minimize tracking and dust, requiring specialized die and cutting machinery. Japanese consumers pay premiums for low-dust pellet formulations in compact urban apartments.
- Flake:Thin compressed sheets dissolve fastest in water, suiting flushable claims in markets with advanced sewage infrastructure.
- Powder:Fine-ground material serves specialized veterinary and breeding applications requiring maximum surface area contact.
Granule commands the largest production footprint; pellet is climbing the fastest on urban space constraints.
Application:
Application segmentation tracks household composition and environmental control, with multi-cat formulations requiring the most advanced odor-chemistry R&D.
- Multi-Cat:Enhanced enzymatic neutralization systems handle three-plus cat waste loads without fragrance masking. Tokyo and Seoul apartment complexes with strict ventilation rules drive adoption of hospital-grade odor control variants.
- Indoor:Standard formulations optimize for confined-space ammonia suppression with moderate clumping speed. China's tier-one cities concentrate demand as pet ownership shifts from courtyard to high-rise living.
- Single-Cat:Baseline formulations serve cost-sensitive owners with lower throughput requirements and simpler odor management needs.
- Outdoor:Weather-resistant variants resist humidity degradation for catio and shelter use in subtropical climates.
Indoor applications lock in the majority of formulation patents; multi-cat is gaining share fastest on household consolidation trends.
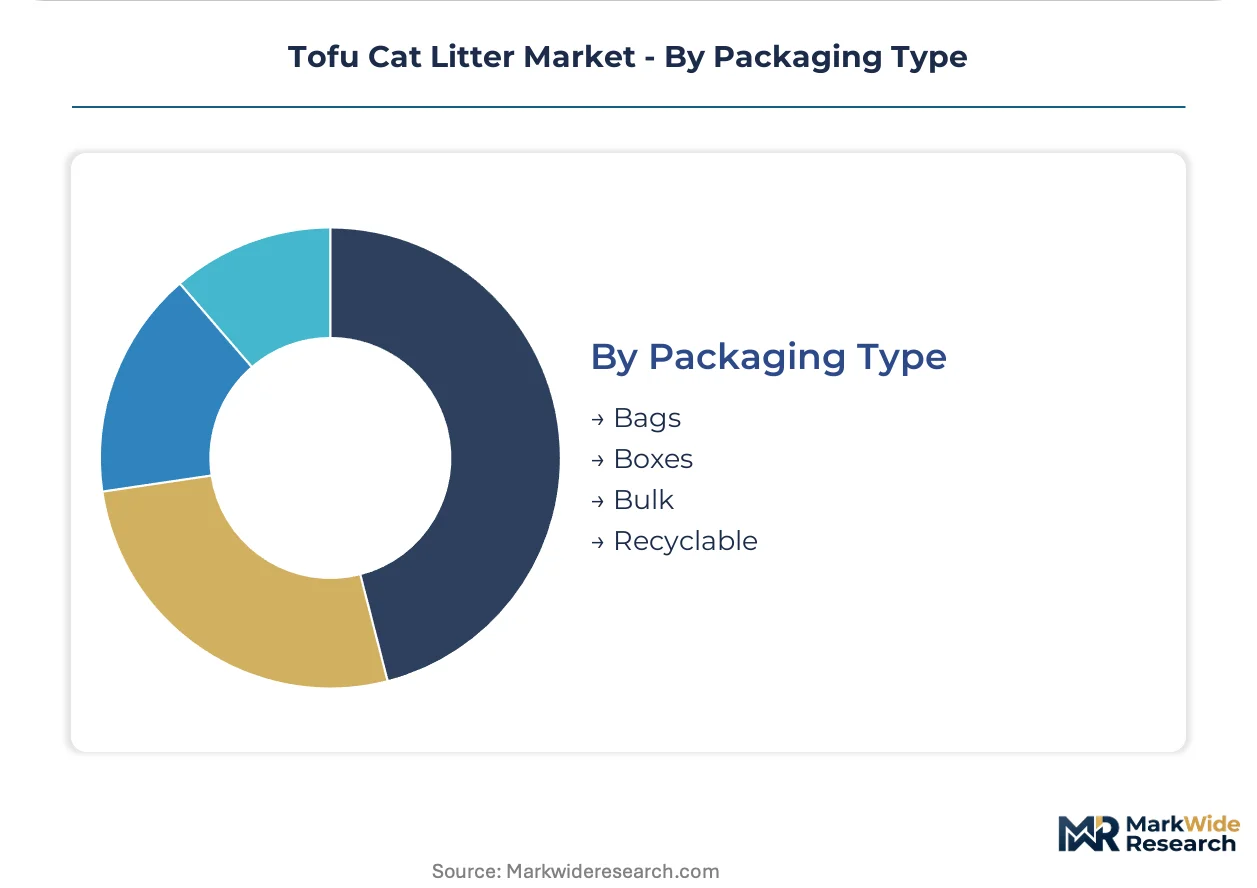
Packaging Type:
Packaging segmentation reflects sustainability compliance costs and logistics economics, with bulk formats requiring the most warehouse and freight optimization.
- Bags:Flexible multi-layer pouches dominate e-commerce fulfillment for their shipping cube efficiency. Subscription services in North America specify bag formats for automated packing line compatibility.
- Boxes:Rigid cardboard containers support retail shelf presence and stackability for warehouse club channels. EU Green Deal packaging directives are accelerating shifts from plastic windows to fully recyclable box constructions.
- Bulk:Refill totes and dispensers minimize per-kilogram packaging cost for high-volume commercial catteries and shelter operations.
- Recyclable:Mono-material designs certified for curbside collection satisfy retailer sustainability scorecards in France and the Netherlands.
Bags carry the highest shipment volumes; recyclable formats are scaling fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates tofu cat litter manufacturing capacity while Germany and Japan drive premium consumption. Raw soybean dreg processing clusters along the Yangtze River Delta supply formulation inputs. Urban pet ownership patterns in East Asia and regulatory pressure in Western Europe are reconfiguring trade flows.
China
Shandong and Jiangsu provinces host the densest concentration of soy-processing facilities feeding litter production. SAMR enforces GB standards for biodegradable materials that manufacturers must meet for domestic certification. Qingdao-based producers are expanding pellet extrusion capacity to serve Japanese export contracts.
Germany
Multi-cat households in Berlin and Munich absorb premium enzymatic formulations at rates exceeding EU averages. The EU Green Deal's packaging waste directives force retailers toward compostable outer packaging. Hamburg distribution hubs are consolidating inbound shipments from Chinese manufacturers to reduce per-unit freight costs.
Japan
Tokyo apartment dwellers prioritize low-dust pellet formats suited to compact living spaces. METI guidelines on pet product labeling shape ingredient disclosure requirements for domestic brands. Osaka-Kobe industrial corridors host blending facilities that reprocess imported Chinese base materials into specialized formulations.
United States
Subscription auto-replenishment penetration in California and New York Metro exceeds traditional retail channels for plant-based litter. EPA interest in chemical disclosure is pressuring cross-border sellers toward ingredient transparency. Pacific Northwest municipal composting pilots are testing dedicated streams for pet waste bioplastics.
South Korea
Seoul Capital Area pet owners are adopting smart litter box bundled consumables faster than regional peers. MFDS regulations on animal product safety extend to litter contact standards. Busan-Ulsan logistics zones are emerging as transshipment points for Chinese exports to Southeast Asian markets.
Tofu Cat Litter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tofu cat litter value chain. The market structure splits between integrated soy-processors with captive raw material supply and brand-focused marketers outsourcing formulation. Three archetypes dominate: subscription-platform operators controlling customer data, veterinary-channel bundlers capturing wellness plan attachment, and smart-hardware integrators locking consumable replenishment to sensor ecosystems. Capacity expansion and direct-to-consumer channel capture represent the primary competitive vectors.
Within the subscription-platform tier, PIDAN exemplifies the direct-to-consumer archetype through its owned fulfillment infrastructure. PETKIT occupies a position at the hardware-consumable integration frontier, while Michu Pet represents veterinary-channel bundling strategy. These three anchors illustrate how divergent go-to-market models coexist without direct feature-for-feature competition.
| Leading Market Players |
|---|
| PIDAN |
| PETKIT |
| Michu Pet |
| RUFUS & COCO |
| YOKEN |
| KAMY'S ZOO |
| CHOWSING |
| CatLitterCompany |
| PETNF |
| Others |
Pricing and Supply Chain Analysis
Family-owned soy-processing specialists in Shandong and Jiangsu provinces anchor raw material supply, translating harvest volatility into asymmetric pricing power that favors integrated manufacturers over brand-only marketers during input cost spikes.
Pricing Analysis
Margin tightening in economy-tier granule formats reflects soybean dreg cost pass-through limitations in Southeast Asian export markets. Three-tier pricing structure across premium enzymatic formulations, standard clumping variants, and economy non-clumping pellets tracks certification grade and odor-control chemistry sophistication. Cost-down pressure on standard-tier products accelerates because Chinese manufacturers compete for Vietnamese and Thai distributor shelf space. Single-cat households in Indonesia and Philippines exhibit highest price sensitivity, while multi-cat owners in Germany and Japan accept enzymatic formulation premiums.
Supply Chain Analysis
Soybean dreg supply rests on Yangtze River Delta processing clusters, corn starch binders draw from Northeast China grain belt facilities, and food-grade guar gum sources from India and Pakistan harvests. Tariff exposure on Indian guar gum imports into China creates formulation cost volatility for pellet extrusion specialists. Distribution runs through Qingdao and Shanghai port consolidation for European and Japanese export contracts, with Bangkok and Ho Chi Minh City emerging as Southeast Asian transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tofu cat litter sector is consolidating around subscription-platform operators and smart-hardware integrators, with REACH compliance costs and compostability certification timelines forcing sub-scale formulators toward acquisition or exit.
For Market Incumbents: Acquire pellet extrusion capacity in Shandong province to secure captive supply of low-dust formulations for Japanese export contracts. Preempt enzymatic coating specialists before biotechnology capabilities become acquisition targets for hardware-integrator competitors. Lock veterinary clinic channel access through wellness plan bundling before Michu Pet's partnership model replicates across North American markets. For New Entrants and Emerging Players: Enter via underdeveloped veterinary clinic channels in Japan and South Korea, where wellness plan bundling remains unsaturated compared to North American penetration. Target multi-cat enzymatic formulations for Tokyo and Seoul apartment complexes with strict ventilation regulations. Deploy direct-to-consumer platform native to Southeast Asian e-commerce ecosystems, bypassing distributor margins that compress Chinese exporter returns. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulators with EN 13432 certification progress but stalled EU market entry, particularly those concentrated in Jiangsu province with stranded pellet capacity. Long-term viability hinges on smart-hardware integration readiness and subscription fulfillment infrastructure rather than formulation chemistry alone. Watch compostability certification harmonization between China's GB standards and EU protocols as the inflection signal for dual-market launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Coating Capability Acquisition | Biotechnology R&D assets in Japan and Germany command premium positioning in multi-cat odor-control segments. |
| Veterinary Channel Partnership Expansion | Wellness plan bundling in North American clinics locks recurring revenue and displaces retail shelf dependence. |
| Smart Litter Box Sensor Integration | PETKIT's consumable replenishment algorithms demonstrate hardware-software bundling as the default purchase mode. |
| EU Compostability Certification Investment | EN 13432 compliance unlocks German and French retailer shelf resets under Green Deal packaging directives. |
| Southeast Asian E-Commerce Platform Buildout | Direct-to-consumer logistics in Thailand and Vietnam disintermediate distributor layers that erode exporter margins. |
Research Methodology
Trade databases, customs export records, and pet product retailer inventory systems formed the secondary backbone for volume and trade flow calibration. Primary interviews with soy-processing plant managers, veterinary clinic procurement leads, subscription platform operations directors, and enzymatic coating R&D specialists validated formulation cost structures and channel economics. Bottom-up capacity assessments across Shandong and Jiangsu manufacturing clusters were triangulated against top-down consumption estimates derived from household pet ownership surveys.
Bottom-up modeling tracked clumping versus non-clumping production line utilization, pellet versus granule form factor preferences by geography, and multi-cat versus single-cat application mix across urban household types. CAGRs were derived from segment-level volume build-ups cross-referenced against pricing trajectory assumptions. Forecast inputs incorporated GB standard enforcement timelines, EU Green Deal packaging directive implementation phases, and smart litter box hardware installation curves in East Asian markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under soybean harvest disruption scenarios or prolonged EN 13432 recertification delays. Projections reflect assumptions regarding composting infrastructure buildout in US municipal systems and harmonization progress between Chinese and EU biodegradability testing protocols. A small set of named triggers—regulatory certification timelines, smart hardware adoption rates, and raw material harvest volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Pet Tech Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
US Pet Food Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Cannabidiol CBD Pet Market