
 Europe Pet Diet Market | 2026-2036
Europe Pet Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Diet Market Insights
A widening capital-intensity gap between multinational feed manufacturers and boutique organic labels is reorganizing competitive tiers across the continent. Mars, Incorporated leverages integrated supply chains spanning protein rendering to retail distribution, while Nestlé Purina PetCare sustains category leadership through veterinary channel dominance and prescription diet portfolios. Farmina Pet Foods competes on ingredient provenance, sourcing Mediterranean-sourced wild-caught fish and Italian-grown spelt to differentiate within the grain-free segment.
Europe pet diet encompasses nutritionally formulated feed products engineered to meet species-specific metabolizable energy requirements, amino acid profiles, and digestibility coefficients standardized by FEDIAF nutritional guidelines. Manufacturing employs extrusion cooking for dry kibble at barrel temperatures exceeding 120°C, followed by enrobing with lipid-based palatability enhancers, while wet food retort sterilization ensures commercial sterility and extended shelf stability. Dry food occupies the largest volume share across mass retail channels, yet wet food and supplements represent the fastest-expanding margin pools as pet humanization drives veterinary-recommended therapeutic nutrition. The ingredient source dimension shows organic and natural formulations capturing disproportionate growth in France and Benelux markets, where retailer private-label expansion pressures conventional positioning.
The European Food Safety Authority (EFSA) and EU Feed Hygiene Regulation (183/2005/EC) govern ingredient safety, additive authorization, and manufacturing facility compliance across member states. REACH and the EU Green Deal's Packaging and Packaging Waste Regulation are forcing reformulation of synthetic preservatives and petroleum-derived packaging substrates toward biodegradable alternatives. Stakeholders must monitor pending revisions to FEDIAF nutritional adequacy protocols and national veterinary prescribing frameworks that could reshape channel access for therapeutic diet manufacturers.
Market Dynamics
The EU Green Deal's Packaging and Packaging Waste Regulation is forcing simultaneous reformulation of synthetic preservatives and petroleum-derived substrates, compressing formulation flexibility while elevating compliance costs for mid-tier manufacturers across the continent.
Growth Catalysts
- Urban Millennial Ownership:Dense metropolitan corridors in Germany, France, and the United Kingdom concentrate demand for veterinary-endorsed therapeutic diets with premium shelf positioning in specialty retail.
- REACH-Driven Clean Labeling:The ECHA framework accelerates substitution of artificial additives with Mediterranean-sourced wild proteins and Italian heritage grains in grain-free formulations.
- Wet Food Processing Scale:Retort sterilization technology enables commercial sterility at extended shelf stability, unlocking margin expansion in veterinary-channel prescription portfolios.
Market Restraints
- Protein Input Volatility:Wild-caught fish and heritage grain supply from Mediterranean catch zones and Italian cooperative farms faces seasonal availability constraints.
- Therapeutic Channel Concentration:Veterinary endorsement networks in Germany's metropolitan corridors limit access for non-prescription manufacturers seeking premium positioning.
- F-Gas Refrigeration Compliance:Wet food cold-chain distribution requires retrofitting of hydrocarbon-based cooling systems under EU fluorinated gas phase-down mandates.
Strategic Opportunities
- Benelux Organic Penetration:France and Benelux markets show disproportionate growth capture for natural formulations where retailer private-label expansion pressures conventional positioning.
- Biodegradable Packaging Convergence:EU Green Deal mandates intersect with FEDIAF nutritional adequacy protocols to create first-mover advantage in compostable barrier films.
- Metropolitan Corridor Density:Germany's urban veterinary networks offer concentrated access points for therapeutic diet subscription models bypassing mass retail.
Industry Challenges
- Extrusion Thermal Expertise Gap:Dry kibble manufacturing at barrel temperatures exceeding 120°C requires process engineers capable of optimizing lipid-based palatability enrobing without oxidation degradation.
- Cross-Border Feed Hygiene Harmonization:EU Feed Hygiene Regulation (183/2005/EC) implementation varies across member state competent authorities, complicating multi-facility certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Diet Market |
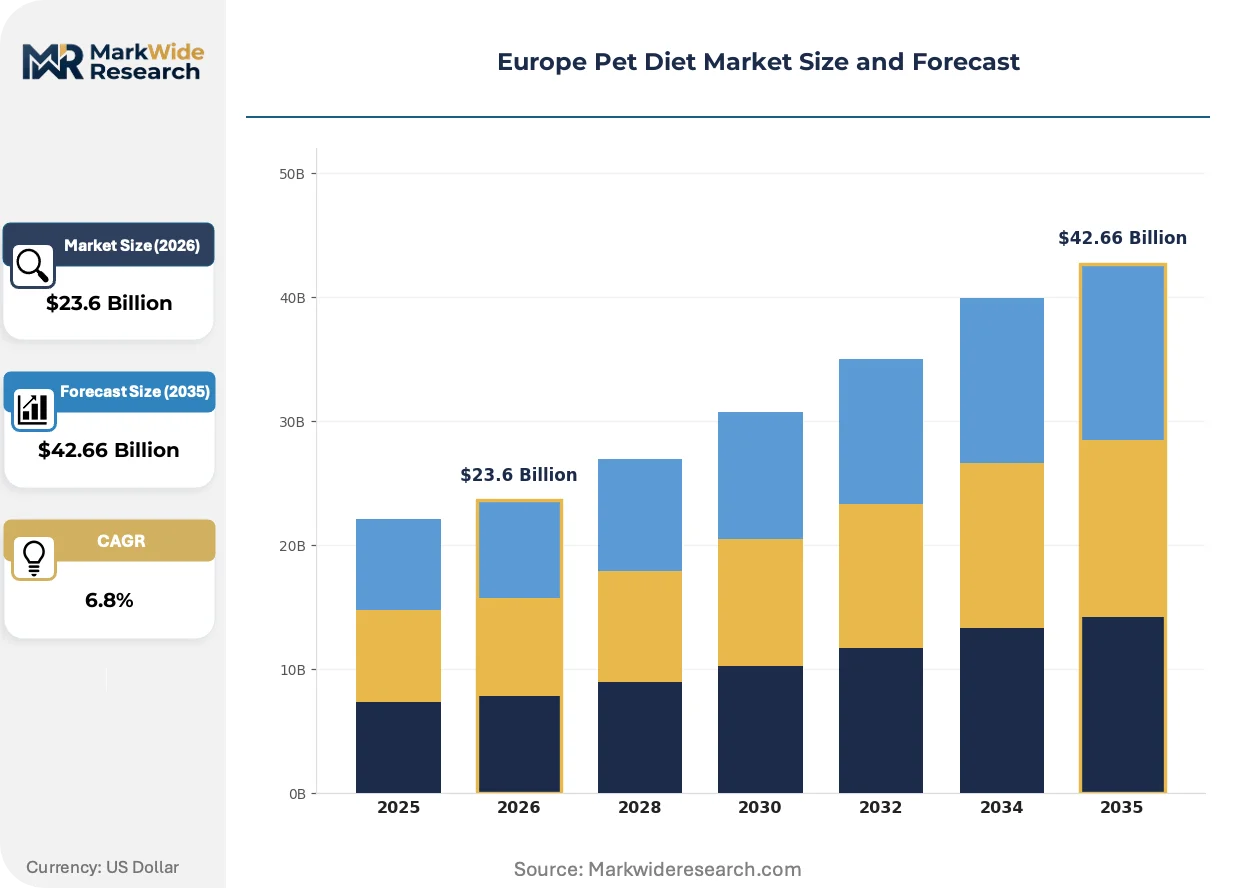
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Birds, Small Animals Ingredient Source: Organic, Grain-Free, Natural, Conventional Distribution Channel: Online, Pet Stores, Supermarkets, Direct Sales |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition, General Mills, Inc., Affinity Petcare, United Petfood, Farmina Pet Foods, The J.M. Smucker Company, Deuerer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Diet Market Trends and Innovations
Formulation science and packaging substrate innovation are diverging along regulatory-compliance and premium-positioning axes simultaneously. Manufacturers must now synchronize thermal processing advances with biodegradable material science to maintain channel access.
Cold-chain wet food distribution is bifurcating between hydrocarbon-refrigerated premium segments and ambient-stable retort formats. Urban millennial owners in Paris and Berlin veterinary practices adopt fresh-frozen subscription models requiring last-mile cold logistics, while mass retail in secondary cities favors shelf-stable cans. This technology split compresses economies of scale for mid-sized processors lacking capital for dual-format production lines.
REACH substance restriction protocols are forcing synthetic preservative substitution with rosemary extract and mixed tocopherol alternatives. The ECHA authorization timeline creates formulation lock-in periods of 18-24 months. Wet food manufacturers with Mediterranean ingredient sourcing relationships respond fastest, while conventional kibble producers face extended reformulation cycles.
Subscription-based veterinary channel purchasing is displacing episodic retail buying among therapeutic diet users. German metropolitan pet owners now receive automated replenishment of renal and gastrointestinal prescription formulas through practice-affiliated platforms. This behavioral shift concentrates buyer power with veterinary endorsement networks, marginalizing conventional pet specialty retailers in Berlin, Munich, and Hamburg corridors.
Europe Pet Diet Market Segmentation
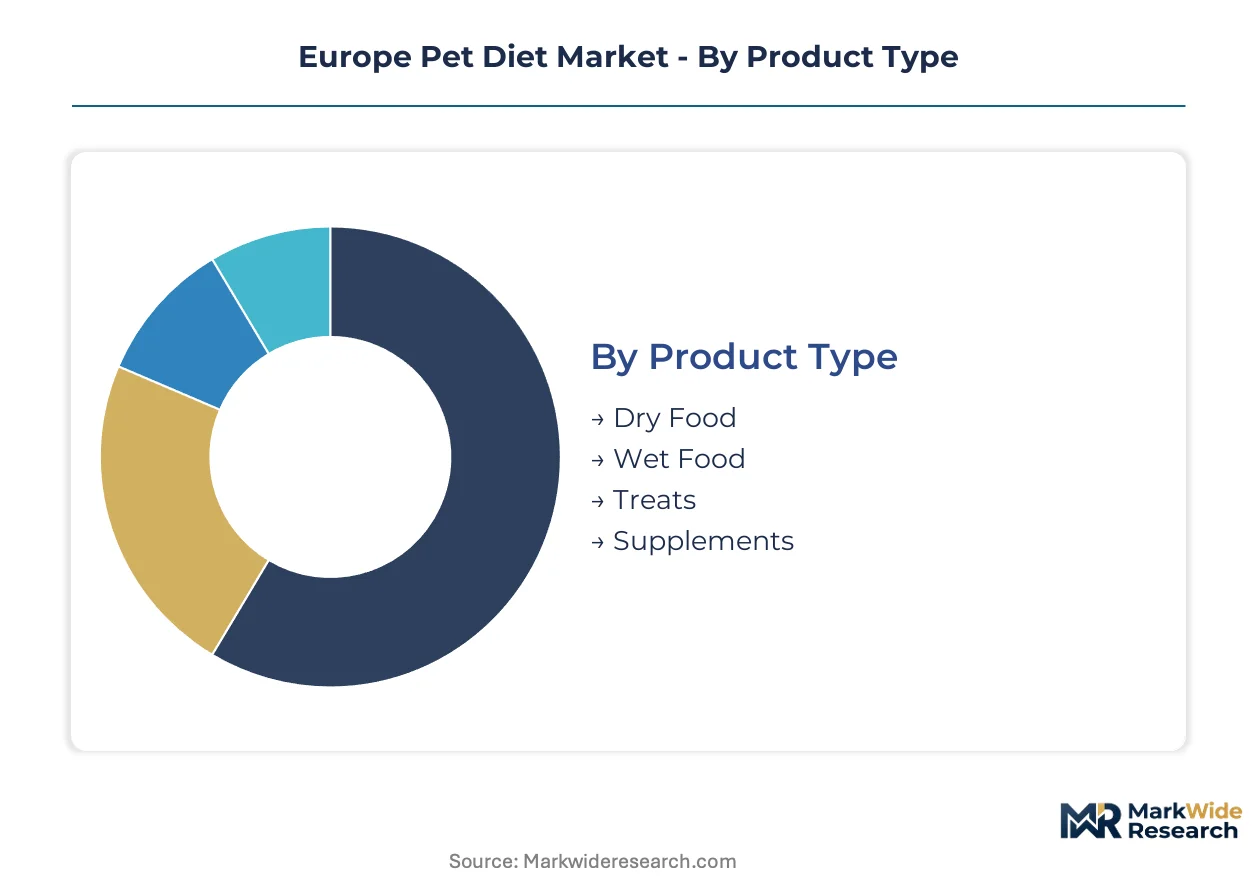
Segmentation in the Europe Pet Diet Market reveals how margin pools concentrate across processing technologies, species-specific nutritional requirements, and channel access barriers. Manufacturers optimize portfolio mix by aligning thermal processing capabilities with regulatory compliance costs and veterinary endorsement networks.
Product Type:
Dry food commands the largest volume base through mass retail penetration, yet wet food and supplements capture disproportionate margin expansion as pet humanization accelerates.
- Dry Food:Extrusion cooking at barrel temperatures exceeding 120°C produces kibble with lipid-based palatability enrobing. German and French mass retail channels dominate volume placement, though oxidation degradation risks during thermal processing compress margins for mid-tier manufacturers lacking process engineering expertise.
- Wet Food:Retort sterilization ensures commercial sterility and extended shelf stability. Urban millennial owners across Berlin, Paris, and London veterinary practices drive subscription-based replenishment of premium formulations, creating concentrated margin pools in prescription portfolios.
- Treats:Functional and dental categories gain shelf space in Benelux specialty retailers.
- Supplements:Joint health and probiotic formulations expand fastest through online direct-to-consumer channels.
The dominant share belongs to Dry Food, while Wet Food is closing the gap fastest.
Animal Type:
Species-specific metabolizable energy requirements and amino acid profiles create distinct formulation expertise barriers, with canine and feline segments absorbing the majority of R&D investment.
- Dogs:Large-breed and senior formulations require precise calcium-phosphorus ratios and glucosamine enrichment. German metropolitan corridors concentrate demand for veterinary-endorsed therapeutic diets addressing obesity and renal conditions.
- Cats:Obligate carnivore protein requirements drive premium wet food adoption in French and UK urban households. Taurine and arachidonic acid fortification mandates under FEDIAF guidelines elevate compliance costs for new entrants.
- Birds:Seed and pellet blends serve specialized avian retailers in Italy and Spain.
- Small Animals:Rabbit and guinea pig hay-based diets grow through pet store expansion in Eastern European markets.
Canine nutrition retains the volume lead, yet feline formulations are expanding most quickly as wet food humanization penetrates Southern Europe.
Ingredient Source:
Clean-label positioning and REACH-driven additive restrictions are reorganizing procurement priorities across Mediterranean supply zones and Italian cooperative networks.
- Organic:Certified ingredient chains with full traceability command shelf positioning in French and Benelux natural specialty retailers. EU organic regulation compliance adds 15-20% formulation cost premiums that compress price elasticity in mass channels.
- Grain-Free:Italian-grown spelt and Mediterranean-sourced wild-caught fish differentiate positioning through heritage grain and marine protein provenance. German urban millennials drive repeat purchase in this segment.
- Natural:Rosemary extract and mixed tocopherol preservatives substitute synthetic alternatives under ECHA timelines.
- Conventional:Standard formulations retain price-sensitive volume in Eastern European supermarkets.
Conventional sourcing still dominates tonnage, though Organic is climbing the fastest as retailer private-label expansion pressures mid-tier positioning.
Distribution Channel:
Channel access determines margin capture, with veterinary endorsement networks and cold-chain logistics creating divergent capital intensity requirements.
- Online:Subscription models for therapeutic diets bypass mass retail through practice-affiliated platforms. Automated replenishment of renal and gastrointestinal formulas concentrates buyer power with German metropolitan veterinary networks.
- Pet Stores:Specialty retailers in France and Benelux face margin compression from natural formulation private-label expansion.
- Supermarkets:Dry food volume placement dominates in UK and Spanish mass retail.
- Direct Sales:Breeder and kennel bulk procurement persists in Italian and Polish markets.
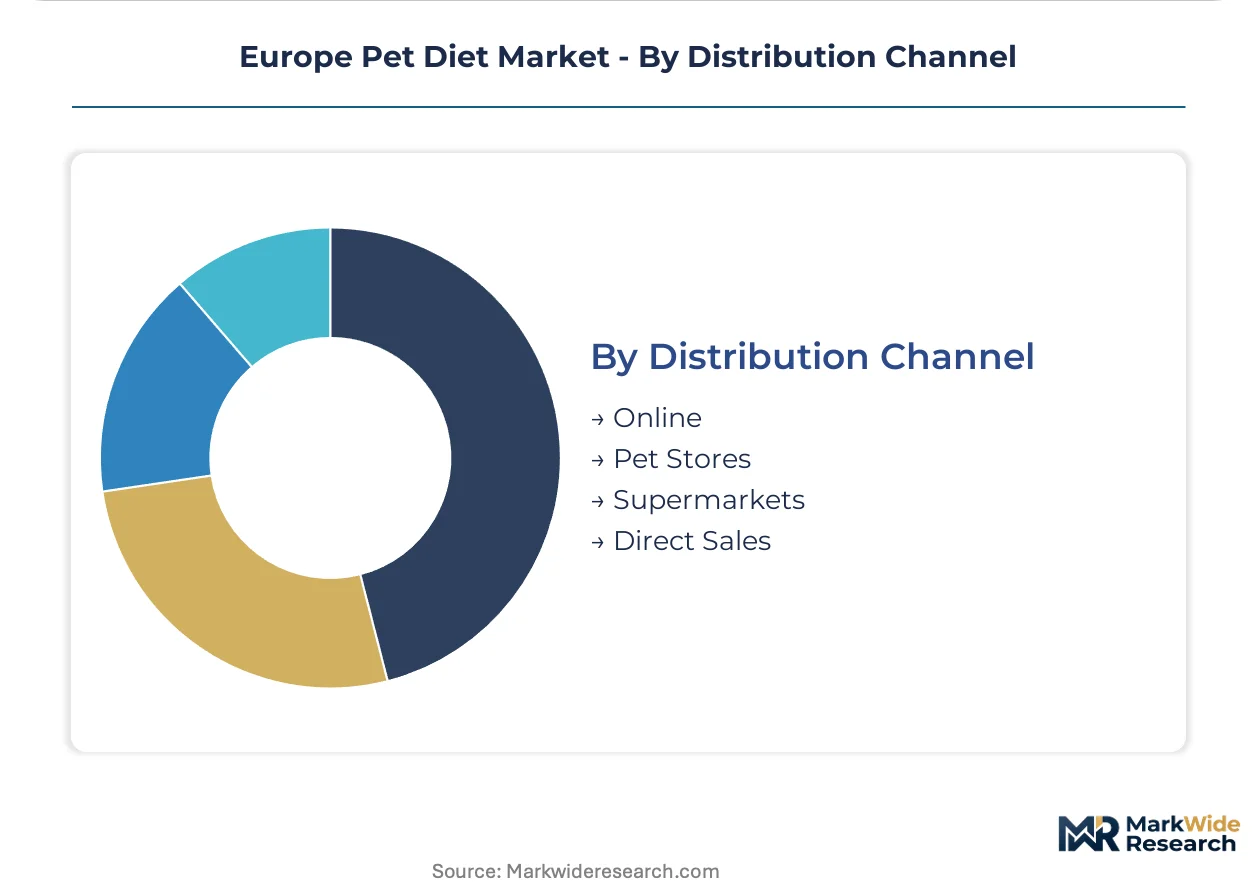
Pet Stores hold the established share position, yet Online is gaining share fastest as subscription platforms consolidate therapeutic diet purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metropolitan corridors concentrate veterinary-endorsed therapeutic diet consumption, while French and Benelux markets disproportionately favor organic and natural formulations through specialty retail channels.
Germany
Berlin, Munich, and Hamburg veterinary networks drive subscription-based replenishment of renal and gastrointestinal prescription formulas. The EU Green Deal's Packaging and Packaging Waste Regulation forces reformulation of petroleum-derived substrates for manufacturers supplying these urban corridors. Bavaria's industrial clusters host extrusion cooking facilities optimized for lipid-based palatability enrobing at barrel temperatures exceeding 120°C.
France
Parisian pet owners adopt fresh-frozen wet food subscription models requiring last-mile cold logistics infrastructure. ECHA REACH frameworks accelerate rosemary extract and mixed tocopherol substitution for synthetic preservatives in formulations targeting Île-de-France households. Auvergne-Rhône-Alpes cooperatives supply Italian-grown spelt and Mediterranean wild-caught fish for grain-free positioning.
United Kingdom
London veterinary practices concentrate demand for obesity and senior canine therapeutic diets with precise calcium-phosphorus ratios. FEDIAF nutritional adequacy protocols govern taurine and arachidonic acid fortification mandates for feline formulations distributed through UK specialty retailers. Midlands mass retail channels dominate dry food volume placement for price-sensitive segments.
Italy
Northern Italian rendering facilities and Mediterranean catch zones supply protein inputs for heritage grain and marine protein provenance differentiation. Italian cooperative farms face seasonal availability constraints for spelt and wild-caught fish sourcing under REACH-driven clean-label requirements. Lombardy and Piedmont industrial districts host retort sterilization facilities for wet food commercial sterility production.
Netherlands
Benelux natural specialty retailers capture disproportionate growth for certified organic ingredient chains with full traceability. EU organic regulation compliance adds formulation cost premiums that compress price elasticity in Dutch mass channels. Randstad logistics hubs coordinate cold-chain distribution requiring hydrocarbon-based cooling system retrofits under F-Gas Regulation phase-down mandates.
Europe Pet Diet Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational feed manufacturers leveraging captive supply chains from protein rendering through retail distribution. Boutique organic labels compete on Mediterranean ingredient provenance and heritage grain sourcing. Three archetypes dominate: integrated multinationals with veterinary channel dominance, regional specialists with clean-label positioning, and private-label suppliers serving retailer expansion. Competitive moves concentrate on backward integration into protein rendering and subscription platform development for therapeutic diet replenishment.
Within the integrated multinational tier, Mars, Incorporated and Nestlé Purina PetCare occupy positions defined by supply chain scope and veterinary endorsement network density. Farmina Pet Foods exemplifies the regional specialist archetype, with Italian operational roots and Mediterranean sourcing relationships. These three companies represent the competitive spectrum from mass-market scale to provenance-driven differentiation in grain-free formulation segments.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| General Mills, Inc. |
| Affinity Petcare |
| United Petfood |
| Farmina Pet Foods |
| The J.M. Smucker Company |
| Deuerer |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for Mediterranean wild-caught fish and Italian heritage grains lock in supply access for premium wet food manufacturers while anchoring price visibility against seasonal protein volatility. These arrangements concentrate procurement power with integrated multinationals capable of pre-committing volume to cooperative farms and rendering facilities.
Pricing Analysis
Subscription-based capacity reservation dominates therapeutic diet segments, with veterinary-channel prescription formulas commanding premium positioning through automated replenishment platforms. Price differentiation separates FEDIAF-certified therapeutic tiers from mass-market formulations based on ingredient provenance and cold-chain service bundling. Pricing pressure stems from retailer private-label expansion in Benelux organic segments, compressing margins for mid-tier natural brands. Mass retail dry food buyers in Eastern European supermarkets exhibit highest price sensitivity, while German metropolitan veterinary clients show lowest elasticity due to endorsement-driven loyalty.
Supply Chain Analysis
Strategic stockpiling of rosemary extract and mixed tocopherol alternatives buffers REACH-driven reformulation timelines, while just-in-time fresh-frozen distribution serves urban millennial subscription models in Paris and Berlin. Protein rendering draws from Northern Italian facilities and Mediterranean catch zones, with heritage grain sourcing anchored in Auvergne-Rhône-Alpes cooperatives. Single-source vulnerability concentrates in wild-caught fish seasonal availability, compounded by F-Gas Regulation cold-chain retrofit requirements. Distribution runs through veterinary endorsement networks for premium tiers and mass retail consolidation for dry food volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Pet Diet Market is recovering from input cost cyclicality as Mediterranean protein availability normalizes and REACH compliance costs stabilize across reformulation cycles.
For Market Incumbents: Secure backward integration into protein rendering facilities in Bavaria and Lombardy to defend against boutique organic label encroachment. Expand captive supply relationships with Italian cooperative farms to lock in heritage grain access before REACH-driven clean-label demand intensifies.
For New Entrants and Emerging Players: EU organic regulation fast-track certification opens shelf positioning in French and Benelux specialty retailers facing private-label saturation. Target underpenetrated Eastern European small animal segments with hay-based formulations, leveraging direct-to-breeder sales models bypassing veterinary channel concentration.
For Investors and Strategic Acquirers: Regional specialists with Mediterranean ingredient provenance relationships offer acquisition exposure to grain-free margin expansion. Long-term viability rests on cold-chain logistics capabilities and FEDIAF nutritional adequacy protocol compliance. Watch for hydrocarbon refrigeration retrofit completion rates as inflection signal for wet food distribution cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Captive protein supply from Northern Italian facilities secures cost stability against wild-catch volatility. |
| Subscription Platform Development | Practice-affiliated automated replenishment concentrates buyer power with German veterinary networks. |
| Biodegradable Packaging Transition | EU Green Deal compliance creates first-mover positioning in compostable barrier film segments. |
| Therapeutic Diet Certification Investment | FEDIAF nutritional adequacy protocols unlock veterinary channel access for renal and gastrointestinal formulas. |
| Cold-Chain Logistics Expansion | Hydrocarbon-based cooling retrofits enable fresh-frozen distribution under F-Gas Regulation mandates. |
Research Methodology
A standing panel of veterinary nutritionists, pet specialty retail category managers, protein rendering facility operators, and EFSA regulatory affairs specialists provided ongoing calibration against secondary validation. Primary interviews with German metropolitan veterinary practice owners, French organic cooperative farm representatives, and Benelux retail procurement directors combined with trade data from FEDIAF industry reports, EU Feed Hygiene Regulation compliance filings, and ECHA REACH substance restriction timelines. Bottom-up facility capacity assessments and top-down retail audit data triangulated volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning product type, animal species, ingredient source certification tier, and distribution channel access. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporated F-Gas phase-down compliance costs and EU Green Deal packaging reformulation timelines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained Mediterranean protein supply stability or accelerated REACH substance restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding veterinary endorsement network density and cold-chain infrastructure investment rates. Revision becomes warranted when hydrocarbon refrigeration retrofit adoption crosses threshold penetration in German and French distribution networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Netherlands Pet Food Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Pet Tech Market
Pet Care Products
Animal Bedding Products Market