
 Aquarium and Fish Bowls Market | 2026-2036
Aquarium and Fish Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Aquarium and Fish Bowls Market Outlook
Skilled aquascaping artisans is collapsing across Western Europe, forcing manufacturers to automate curved-glass bonding and outsource decorative molding to specialized workshops. Hagen Group leverages captive breeding partnerships to secure consistent live-stock supply chains for its retail channels. Central Garden & Pet anchors North American distribution through pet-specialty and mass-retail shelf placement. EHEIM GmbH & Co. KG dominates precision pump and filtration engineering, sustaining premium positioning through German manufacturing standards.
Aquarium and fish bowls are transparent enclosures, typically constructed from soda-lime glass, acrylic polymethyl methacrylate, or polycarbonate, designed to maintain aquatic ecosystems through controlled water chemistry, temperature regulation, and gas exchange. Residential end users represent the largest installed base, though commercial installations in hospitality and healthcare settings command higher per-unit margins due to custom sizing and service contracts. Glass material segments retain volume leadership across all capacity tiers, while acrylic is displacing traditional materials in large-format and extra-large tanks where weight reduction and impact resistance justify cost premiums.
EPA guidelines on water discharge and chemical treatment affect commercial aquarium operations, while REACH compliance governs substrate and sealant compositions sold across European markets. California's Proposition 65 mandates warning labels on products containing trace heavy metals, directly impacting glass and ceramic sourcing decisions for brands distributing in the United States. Stakeholders must monitor evolving state-level chemical disclosure laws and assess whether regional compliance investments outweigh market access benefits.
Market Dynamics
Curved glass bonding automation is collapsing artisan labor availability across Western Europe, forcing manufacturers to restructure production footprints and outsource decorative finishing to specialized regional workshops.
Growth Catalysts
- REACH chemical disclosure mandates:European manufacturers accelerating substitution of heavy-metal sealants with compliant alternatives, creating upgrade cycles across installed base.
- Biophilic residential design:Hobbyists in Germany and Japan integrating aquascaping into interior architecture, expanding tank capacity per household.
- China curved-glass production scaling:Domestic manufacturing of integrated filtration systems capturing export demand from Southeast Asian markets.
Market Restraints
- Silica sand supply concentration:High-purity soda-lime glass feedstock sourcing narrows to specific coastal deposits, exposing cost volatility.
- California Proposition 65 compliance friction:Warning label requirements for trace heavy metals complicate cross-border distribution logistics.
- Acrylic substitution ceiling:Large-format tank buyers face persistent optical clarity trade-offs versus glass despite weight advantages.
Strategic Opportunities
- Healthcare biophilic installations:Hospitals and eldercare facilities in the Netherlands deploying custom aquariums for patient environment enhancement.
- EU Green Deal material incentives:Recycled glass content targets creating certified sustainable product tier differentiation.
- Direct-to-consumer filtration subscriptions:E-commerce channels bypassing traditional pet-specialty retail for consumable replacement parts.
Industry Challenges
- Skilled aquascaping artisan attrition:Master glass-benders retiring faster than apprenticeship programs replenish Western European labor pools.
- Multi-jurisdiction certification timelines:EPA discharge permits for commercial installations requiring 18-24 month approval cycles in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquarium and Fish Bowls Market |
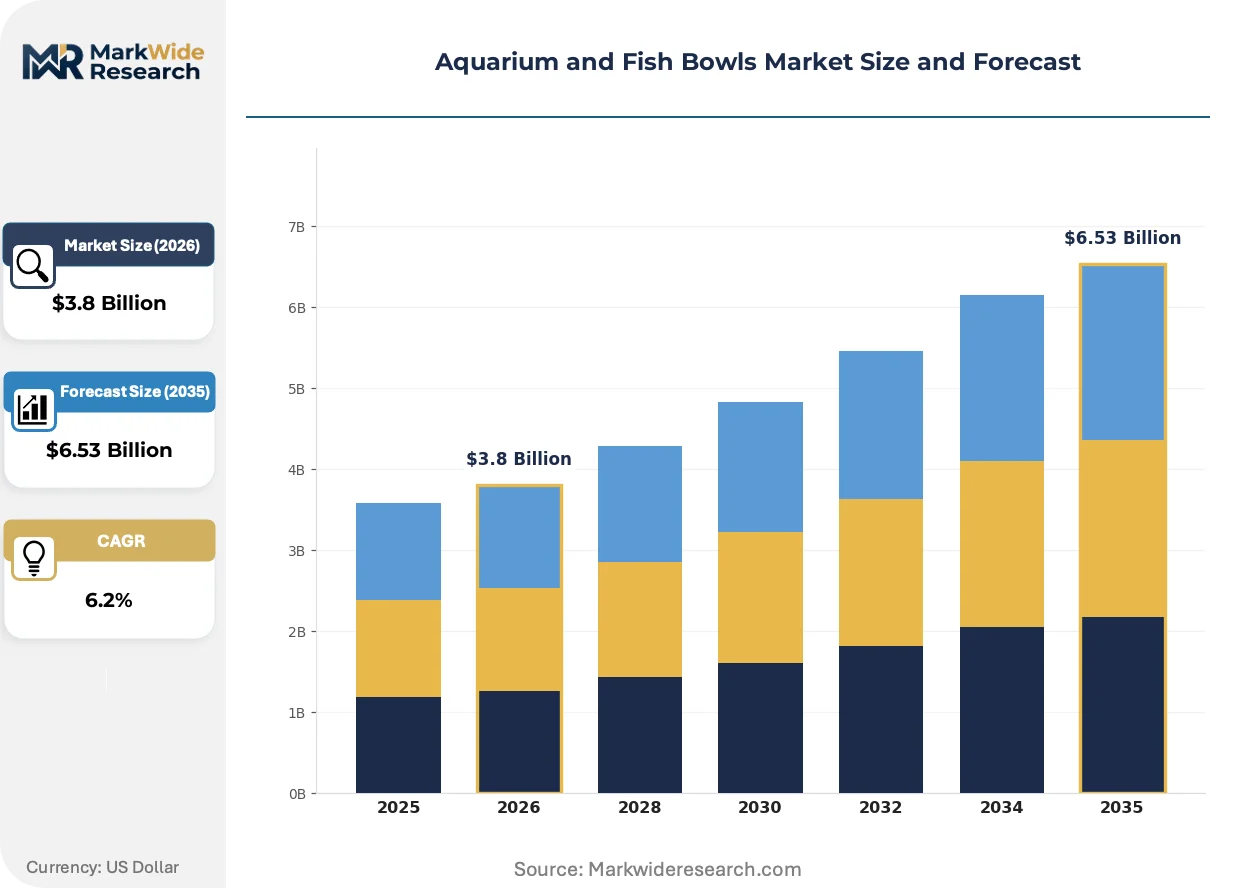
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freshwater Aquariums, Saltwater Aquariums, Fish Bowls, Tank Accessories End User: Residential, Commercial, Educational Institutions, Hobbyists Material: Glass, Acrylic, Plastic, Ceramic Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Hagen Group, Spectrum Brands Holdings, Central Garden & Pet, OASE GmbH, EHEIM GmbH & Co. KG, Aqua Design Amano, Juwel Aquarium AG & Co. KG, Penn-Plax, Red Sea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquarium and Fish Bowls Market Strategic Shifts
Smart monitoring integration and material substitution are compressing traditional equipment replacement cycles while elevating service contract attachment rates across premium residential segments.
Precision pump engineering is fragmenting across price-performance tiers. Variable-frequency drive technology enables granular flow control for sensitive species habitats. High-end residential adopters in Japan and Germany specify app-integrated units. Equipment vendors face compressed margins as mid-tier functionality encroaches on premium positioning.
California's Proposition 65 enforcement is tightening trace-element documentation requirements for ceramic substrate and decorative glass components. Manufacturers must redesign supply chain auditing protocols or withdraw from the state's distribution network. Decorative molding suppliers face the steepest compliance cost escalation.
After-sales service unbundling is altering channel economics. Retailers now separate installation, water chemistry consultation, and livestock sourcing into discrete revenue streams. Specialist aquascaping studios in Copenhagen and Singapore capture premium margins through subscription-based ecosystem maintenance. Mass-market distributors struggle to replicate high-touch service intensity.
Aquarium and Fish Bowls Market Segmentation
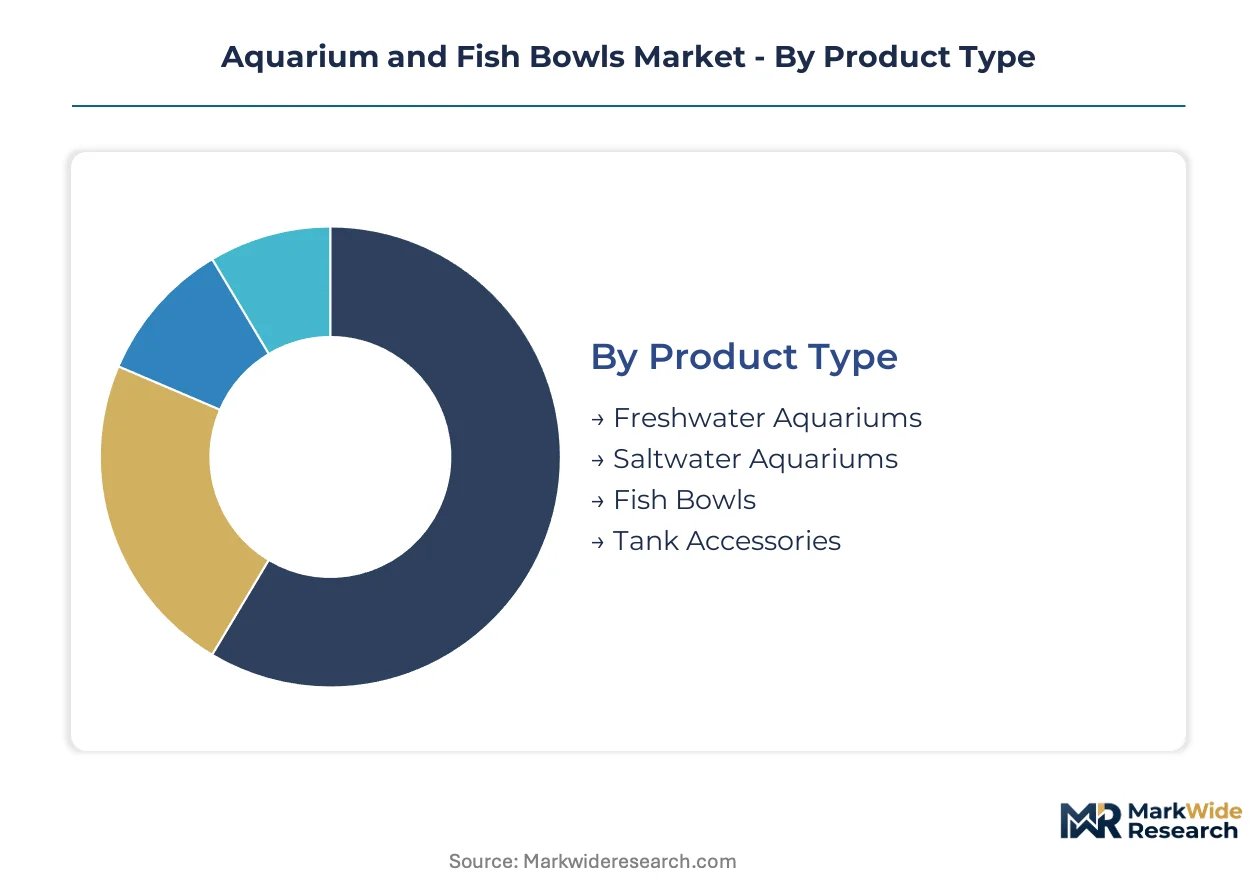
Segmentation in aquarium markets exposes divergent compliance burdens and margin structures. Glass and acrylic face distinct REACH and Proposition 65 obligations, while residential and commercial buyers demand incompatible service intensity levels.
Product Type:
REACH chemical disclosure mandates and California Proposition 65 warning requirements apply differentially across enclosure categories based on sealant composition and decorative element sourcing.
- Freshwater Aquariums:Soda-lime glass construction with silicone bonding dominates unit economics. Hobbyists in Germany and Japan drive demand for integrated filtration systems in this category, with biophilic interior design accelerating tank capacity expansion per household.
- Saltwater Aquariums:Acrylic polymethyl methacrylate gains share in reef-ready configurations requiring precise temperature stability. Commercial installations in Netherlands healthcare facilities specify custom sizing with service contracts, commanding premium margins unavailable in standard residential channels.
- Fish Bowls:Compact glass vessels face displacement by entry-level acrylic in mass retail.
- Tank Accessories:Precision pumps and filtration components concentrate German engineering expertise.
Established volume favors Freshwater Aquariums; emerging adoption favors Saltwater Aquariums.
End User:
Cost tier stratification separates high-touch service contracts from disposable retail transactions.
- Residential:Largest installed base with fragmented purchasing across pet-specialty and e-commerce channels. Curved-glass automation in Chinese manufacturing reduces per-unit costs, though Western European hobbyists pay premiums for artisan-finished decorative molding.
- Commercial:Hospitality and healthcare settings in the Netherlands and Singapore deploy custom aquariums for patient environment enhancement. EPA discharge permits for United States commercial installations require 18-24 month approval cycles, compressing addressable market velocity.
- Educational Institutions:Budget-constrained procurement favors plastic and small-capacity configurations.
- Hobbyists:Specialist aquascaping studios in Copenhagen capture subscription-based ecosystem maintenance revenue.
Margin concentration sits with Commercial; volume scale sits with Residential.
Material:
Supply concentration in high-purity silica sand deposits governs glass cost volatility, while acrylic optical clarity trade-offs persist despite weight advantages.
- Glass:Soda-lime formulations retain volume leadership across all capacity tiers. REACH compliance and California Proposition 65 trace heavy metal documentation complicate cross-border distribution for decorative ceramic substrate suppliers.
- Acrylic:Polymethyl methacrylate displaces traditional materials in large-format and extra-large tanks where impact resistance justifies cost premiums. Weight reduction enables wall-mounted and elevated installations in Japanese residential architecture.
- Plastic:Entry-level fish bowls and educational institution procurement dominate this tier.
- Ceramic:Decorative substrate applications face steepest Proposition 65 compliance cost escalation.
Optical performance favors Glass; installation flexibility favors Acrylic.
Capacity:
Customer type and application maturity separate commodity small-format sales from engineered large-system contracts.
- Large:Curved-glass bonding automation enables Chinese manufacturers to scale integrated filtration exports to Southeast Asian markets. Custom sizing requirements in commercial healthcare and hospitality segments sustain premium pricing power.
- Extra Large:Acrylic substitution accelerates where structural load constraints prohibit glass. Netherlands hospitals and eldercare facilities specify these configurations for biophilic patient environment programs.
- Small:Mass-market retail distribution concentrates in impulse-purchase fish bowls.
- Medium:Standard residential aquascaping represents the most contested price tier.
Service contract attachment favors Extra Large; replacement cycle frequency favors Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing cost advantages through curved-glass automation, while Germany sustains premium pricing through precision engineering heritage. This asymmetry shapes trade flows across Southeast Asian export markets and Western European specialty channels.
China
Domestic aquascaping hobbyists and Southeast Asian export demand propel curved-glass tank production. SAMR oversees product safety standards for integrated filtration systems. Guangdong Province manufacturers scale automated bonding lines for both local consumption and regional export.
Germany
Biophilic interior architecture drives household tank capacity expansion among affluent hobbyists. REACH chemical disclosure mandates accelerate heavy-metal sealant substitution. EHEIM GmbH & Co. KG anchors precision pump engineering in Deizisau, sustaining premium positioning through German manufacturing standards.
United States
Commercial installations in hospitality and healthcare settings command elevated per-unit margins through custom sizing contracts. EPA discharge permits for commercial aquarium operations require 18-24 month approval cycles. California's Proposition 65 mandates warning labels on products containing trace heavy metals, directly impacting glass sourcing decisions for brands distributing nationwide.
Netherlands
Hospitals and eldercare facilities deploy custom aquariums for patient environment enhancement programs. EU Green Deal material incentives create certified sustainable product tier differentiation. Randstad region specialist aquascaping studios capture subscription-based ecosystem maintenance revenue.
Japan
Residential adopters specify app-integrated variable-frequency drive pumps for sensitive species habitats. METI oversees energy efficiency standards for aquarium equipment. Kanto region hobbyists integrate aquascaping into compact urban interior architecture, expanding wall-mounted and elevated installations.
Aquarium and Fish Bowls Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. German and Japanese specialists dominate precision engineering segments, while Chinese manufacturers capture volume through automated production scale. Three strategic archetypes define competitive positioning: heritage engineering houses with captive R&D, automated mass producers with export orientation, and specialist studios with subscription service models. M&A activity concentrates on captive breeding partnerships and decorative molding workshop acquisitions.
Among heritage engineering houses, EHEIM GmbH & Co. KG and OASE GmbH exemplify the precision pump and filtration tier, while Hagen Group occupies a position across integrated supply chains. Central Garden & Pet represents North American distribution consolidation through pet-specialty and mass-retail channel control. These three anchors illustrate how geographic specialization and channel integration create defendable market positions without direct technology competition.
| Leading Market Players |
|---|
| Hagen Group |
| Spectrum Brands Holdings |
| Central Garden & Pet |
| OASE GmbH |
| EHEIM GmbH & Co. KG |
| Aqua Design Amano |
| Juwel Aquarium AG & Co. KG |
| Penn-Plax |
| Red Sea |
| Others |
Value Chain & Pricing Dynamics
Curved-glass automation scale in Guangdong Province manufacturing compresses unit economics for standard-format tanks while elevating price floors for artisan-finished decorative molding sourced from Western European workshops. This asymmetry between mass-production efficiency and skilled-labor scarcity shapes margin distribution across the value chain, with Chinese exporters capturing volume and German specialists retaining premium positioning.
Pricing Analysis
The customization-premium spread separates commodity curved-glass exports from configured-to-order commercial installations. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and certification grade, with REACH-compliant sealant formulations commanding tier premiums. Cost compression in entry-level acrylic bowls intensifies as Chinese manufacturers scale automated bonding, while pricing pressure stems from silica sand feedstock volatility in high-purity coastal deposits. Mass-market residential buyers exhibit highest price sensitivity; Netherlands healthcare procurement shows lowest sensitivity due to biophilic program budgets.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites logistics risk for Southeast Asian export flows from Guangdong manufacturers. Supply concentrates in China for curved-glass bonding and integrated filtration systems, Germany for precision pump engineering, and Vietnam for decorative molding subcontracting. Raw material dependencies rest on high-purity silica sand deposits, silicone sealant formulations, and acrylic polymethyl methacrylate resin. Single-source vulnerability in artisan glass-bending labor pools threatens decorative component availability. Distribution runs through pet-specialty retail chains, mass-market big-box, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master glass-bending artisan attrition across Western Europe constrains decorative finishing capacity faster than apprenticeship pipelines replenish, compressing supply elasticity for premium-tier producers. This capability gap rewards players who secure captive workshop relationships or automate bonding processes ahead of competitors.
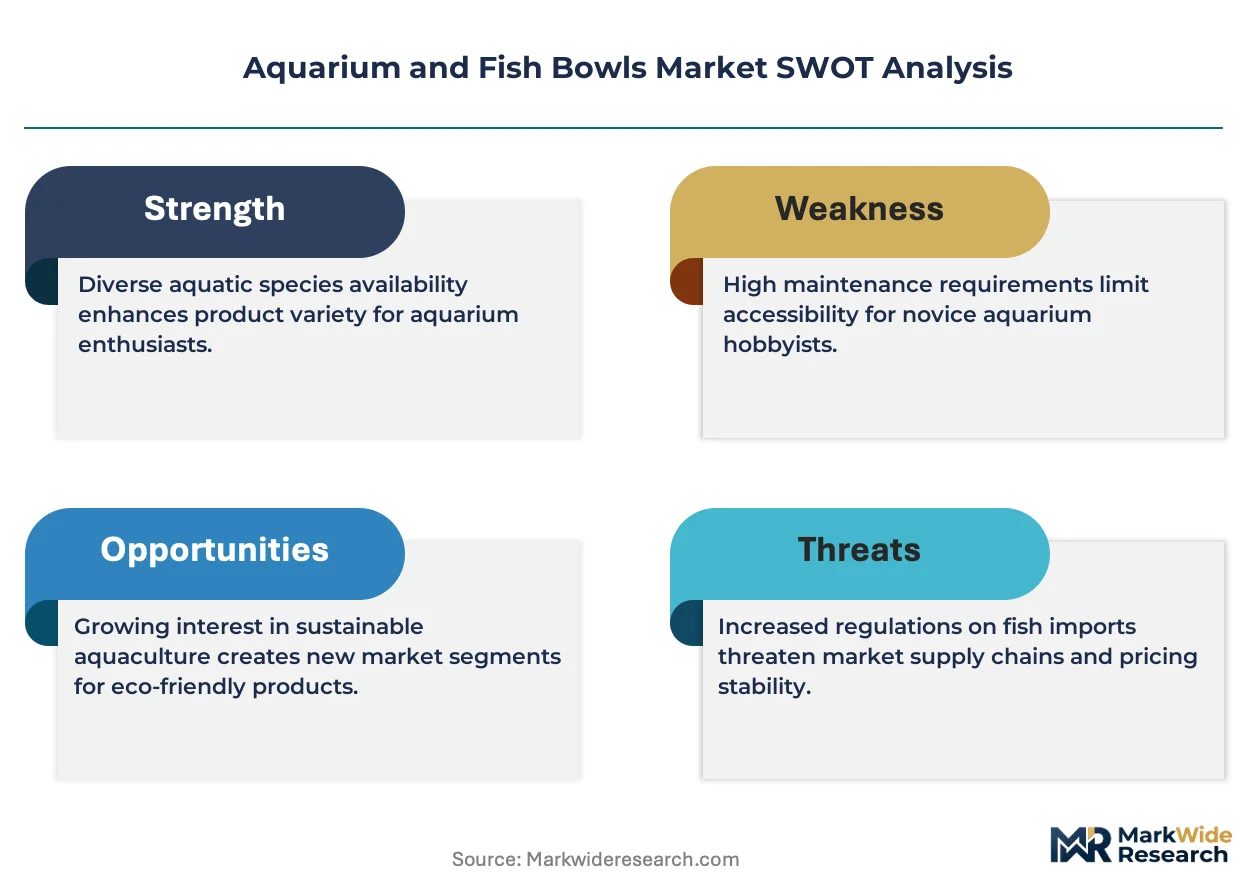
For Market Incumbents: Fortify supply chain control through captive breeding partnerships for live-stock consistency and backward integration into automated curved-glass bonding to offset artisan labor collapse. Accelerate REACH-compliant sealant substitution ahead of regulatory deadlines to capture upgrade cycle revenue. Defend margin position by locking long-term contracts with remaining Western European decorative molding workshops before capacity tightens further. For New Entrants and Emerging Players: Subscription-based ecosystem maintenance services represent the most penetrable white-space where mass-market distributors under-serve high-touch demand. Target Netherlands and Singapore healthcare biophilic installation segments with direct-to-consumer filtration subscription models. Capture margin through specialist aquascaping studio positioning rather than competing on tank hardware commodity economics. For Investors and Strategic Acquirers: Automated mass producers with Southeast Asian export orientation present the most compelling acquisition archetype for long-term viability within a 5-10 year window. Monitor curved-glass bonding automation capex cycles as inflection indicator for manufacturing cost leadership shifts. Assess whether decorative molding workshop acquisitions justify premium multiples given irreversible artisan attrition trends.| Strategic Initiative | Industry Significance |
|---|---|
| Curved-Glass Bonding Automation | Guangdong manufacturers compress unit costs while displacing Western European artisan dependency. |
| REACH-Compliant Sealant Substitution | ECHA mandates accelerate upgrade cycles across European installed base for compliant alternatives. |
| Captive Breeding Partnerships | Hagen Group model secures live-stock supply chain consistency for retail channel reliability. |
| Direct-to-Consumer Filtration Subscriptions | E-commerce channels bypass pet-specialty retail for recurring consumable replacement revenue. |
| Healthcare Biophilic Installation Contracts | Netherlands hospitals and eldercare facilities command premium margins through custom sizing. |
Study Parameters
Desk research of trade customs data, SAMR product safety filings, and ECHA REACH registration databases preceded structured interviews with aquarium equipment plant managers, pet-specialty retail category buyers, aquascaping studio operators, and commercial installation procurement leads across China, Germany, and the Netherlands. Secondary validation drew from customs export records, SEC 10-K disclosures of listed distributors, and EU Green Deal material incentive program documentation. Bottom-up tank shipment data triangulated against top-down end-user spending estimates.
Variance decomposition across product type, material composition, end-user segment, and capacity tier informed the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends, with specific inputs including silica sand price indices, REACH compliance cost escalation curves, and curved-glass automation capex deployment schedules.
Forecasts assume regulatory continuity in REACH chemical disclosure regimes and California Proposition 65 enforcement patterns; material policy shifts would require re-modeling supply chain compliance cost structures. Practitioners should keep alternative scenarios live as artisan labor availability and EPA discharge permit timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dry Pet Food Market
Pet Care Products
Dog Pen Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Dog Clothes Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Cat Bed Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Cat Harness Market