
 Indestructible Dog Toys Market | 2026-2036
Indestructible Dog Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Indestructible Dog Toys Market Analytics
A shift from outsourced Asian manufacturing toward multi-source regional production is recalibrating supply chain risk profiles across the indestructible dog toys sector. KONG Company leverages captive rubber compounding expertise to sustain margin control across its classic and extreme product lines. Benebone anchors its position through domestic nylon injection molding that differentiates against commodity imports. West Paw competes via Montana-based thermoplastic recycling operations that occupy a defensible sustainability niche.
Indestructible dog toys are engineered consumer products designed to withstand sustained mechanical stress from aggressive chewing, typically employing Shore A hardness ratings above 80, tensile strengths exceeding 15 MPa, and food-grade polymer formulations tested for bite fragmentation resistance. Their commercial purpose centers on reducing ingestion hazards, extending product replacement cycles, and supporting canine dental health through abrasive surface textures. Rubber formulations lead material segmentation due to established veterinary endorsement and moldability for hollow treat-dispensing geometries, while TPR compounds represent the fastest-growing material class as manufacturers seek Shore A tunability without cross-linking costs. Large and extra-large size categories concentrate margin pools because unit economics favor premium pricing against disproportionately lower raw material increments.
FDA Center for Veterinary Medicine guidelines on food-contact substances and CPSC small-part choking standards shape material selection and product testing protocols for manufacturers distributing in the United States. ASTM F963 toy safety benchmarks and state-level California Proposition 65 chemical disclosure requirements add compliance layers that favor scaled producers with dedicated quality infrastructure. Stakeholders must monitor evolving biopolymer certification schemes and veterinary dental health claims substantiation as regulatory scrutiny intensifies on performance marketing.
Market Dynamics
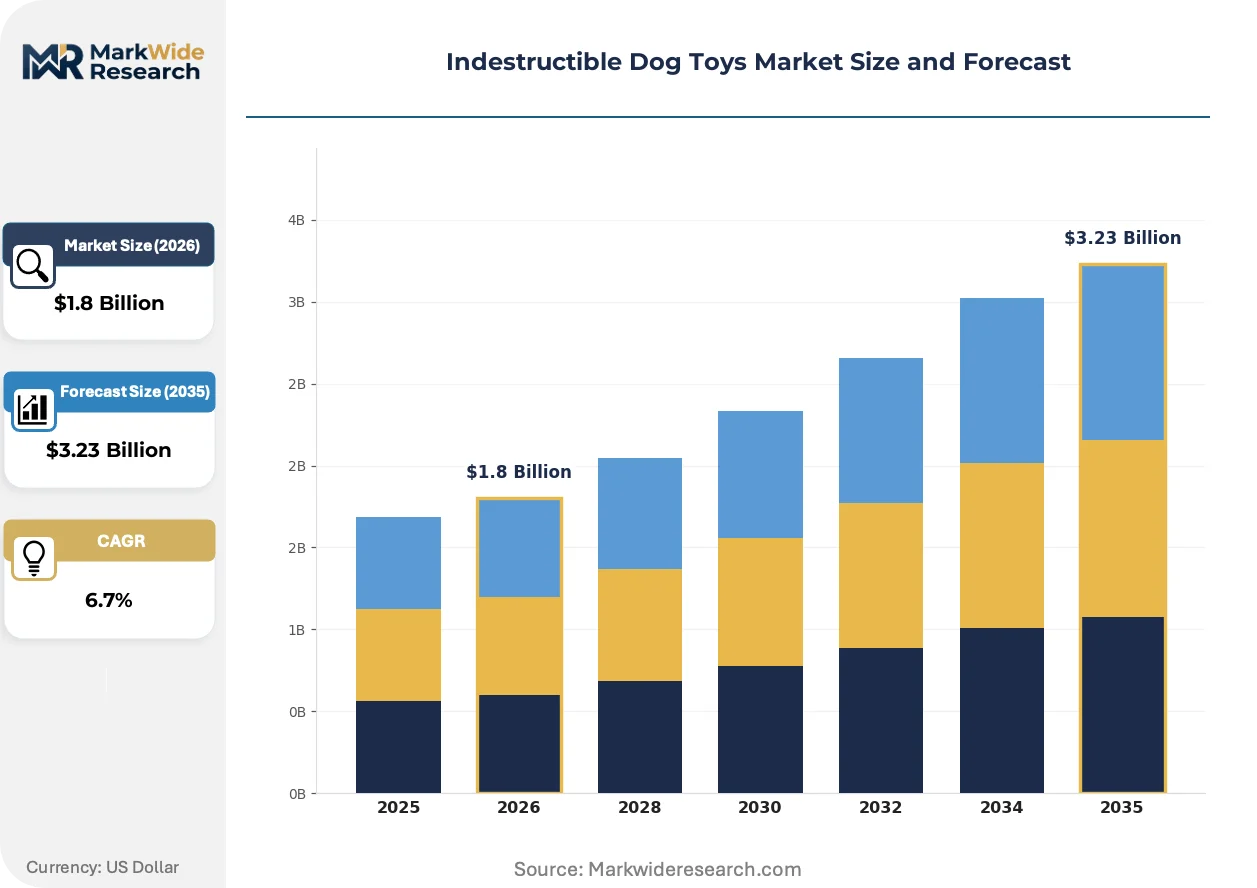
Pet humanization is compressing replacement cycles and elevating safety expectations, forcing manufacturers to reconcile premium material costs with mass-market accessibility while navigating tightening FDA and CPSC compliance frameworks.
Growth Catalysts
- Heavy Chewer Breed Ownership:Rising adoption of power-chewing breeds like Pit Bulls, Rottweilers, and German Shepherds is expanding addressable demand for extreme-durability products.
- FDA Center for Veterinary Medicine Guidelines:Formalized food-contact substance standards are legitimizing premium pricing for certified-safe formulations and accelerating veterinary endorsement.
- TPR Compounding Advances:Thermoplastic rubber Shore A tunability without vulcanization costs is enabling mid-tier manufacturers to bridge performance gaps against cross-linked rubber.
Market Restraints
- Petroleum-Derived Feedstock Volatility:Synthetic rubber and nylon resin costs fluctuate with crude oil indices, compressing margin predictability for non-integrated compounders.
- Asian Manufacturing Concentration:Mold tooling and injection capacity clustering in Guangdong and Zhejiang provinces creates geopolitical and logistics risk exposure for brands without regional diversification.
- Biopolymer Performance Ceiling:PLA and PHA alternatives currently fail bite-fragmentation thresholds above 80 Shore A, limiting substitution for aggressive chewer applications.
Strategic Opportunities
- Veterinary Dental Health Claims:Substantiated abrasive-texture benefits for tartar reduction open prescription-channel positioning and reimbursement-adjacent revenue streams.
- State-Level Extended Producer Responsibility:California and New York packaging waste mandates are creating first-mover advantage for closed-loop recyclable TPR programs.
- Direct-to-Consumer Subscription Models:Chew-cycle personalization based on breed-specific durability testing reduces customer acquisition costs and improves lifetime value metrics.
Industry Challenges
- Polymer Toxicology Expertise Scarcity:FDA food-contact notification preparation requires specialized regulatory affairs talent that mid-size manufacturers struggle to recruit.
- Multi-Jurisdiction Certification Timelines:Simultaneous ASTM F963, California Proposition 65, and emerging biopolymer scheme compliance extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indestructible Dog Toys Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, Nylon, Kevlar, TPR Size: Small, Medium, Large, Extra Large Type: Chew Toys, Fetch Toys, Interactive Toys,Puzzle Toys End User: Pet Owners, Dog Trainers, Retailers, Dog Daycares |
| Companies Covered | Benebone, ZippyPaws, KONG Company, Beco Pets, Bulletproof Pet Products, West Paw, Chuckit!, Jolly Pets, GoughNuts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indestructible Dog Toys Market Evolving Landscape
Material science convergence with veterinary behavioral research is redefining durability benchmarks, while regulatory fragmentation and channel disintermediation are compressing traditional go-to-market timelines.
TPR compounding with mineral-fill reinforcement is overtaking conventional vulcanized rubber in mid-premium positioning. Breed-specific durability testing protocols from veterinary behaviorists are accelerating adoption among specialty retailers seeking differentiated assortment. This shift is compressing SKU proliferation strategies and forcing legacy mold houses to retool for faster changeover cycles.
REACH substance restriction expansions and EU Green Deal biopolymer certification schemes are elevating material disclosure requirements for exporters. Compounders must now document full supply chain substance inventories to maintain CE-marking eligibility. European veterinary channel distributors are responding by consolidating supplier bases toward integrated manufacturers with captive laboratory testing.
Specialty pet retail consolidation is displacing independent boutique purchasing autonomy. Chewy and PetSmart's private label development teams now specify custom Shore A hardness ranges and surface texture profiles directly with compounders. This concentration is most visible in the United States, where premium indestructible SKUs increasingly bypass distributor intermediaries for direct brand-retailer negotiation.
Indestructible Dog Toys Market Segmentation
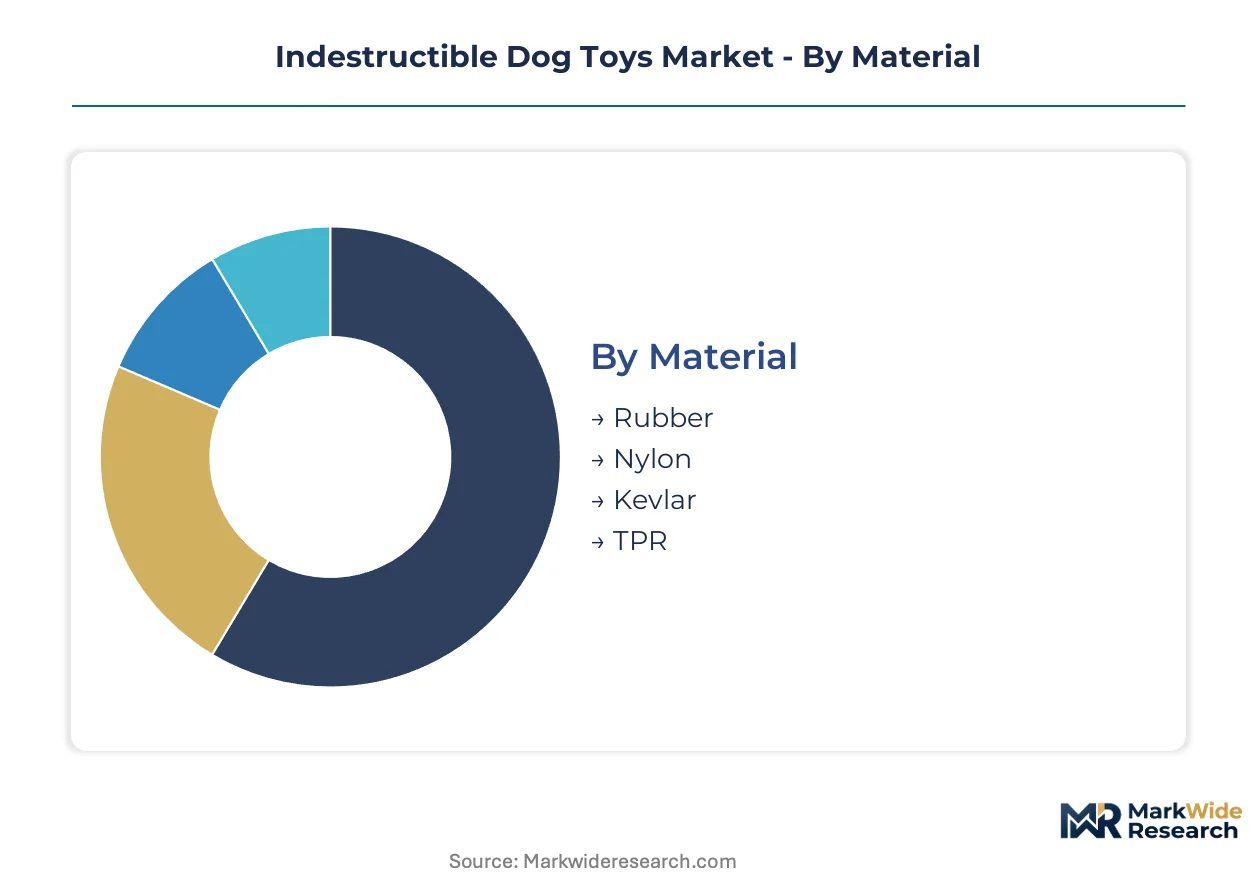
Segmentation in indestructible dog toys reveals how material science, canine biomechanics, and distribution channel economics intersect to create distinct margin pools. Buyers prioritize bite-fragmentation resistance and Shore A hardness ratings differently across breed sizes and usage contexts.
Material:
Buyer prioritization of durability versus cost elasticity determines material selection trajectories across price tiers.
- Rubber:Vulcanized natural and synthetic rubber formulations achieve Shore A ratings above 85 with established FDA food-contact substance compliance. Veterinary endorsement concentrates demand in the United States among owners of aggressive chewers seeking hollow treat-dispensing geometries.
- TPR:Thermoplastic rubber compounds enable Shore A tunability without cross-linking costs, allowing mid-tier manufacturers to bridge performance gaps. Domestic compounding operations in Montana and Ohio are gaining share fastest as brands seek regional supply chain diversification.
- Nylon:Injection-molded formulations deliver abrasion resistance for dental health applications.
- Kevlar:Aramid fiber reinforcement targets extreme-durability positioning for working dog segments.
Rubber leads on scale; TPR leads on momentum.
Size:
Unit economics favor premium pricing disproportionately against raw material increments in larger formats.
- Large:Formats engineered for German Shepherds, Rottweilers, and similar breeds concentrate margin pools through premium positioning. United States specialty retailers allocate disproportionate shelf space to large-format SKUs given replacement cycle compression in heavy chewer households.
- Extra Large:Breed-specific durability testing protocols validate bite-force resistance for giant breeds. Veterinary behaviorist endorsement is expanding addressable demand among owners of Great Danes and Mastiffs seeking prescription-channel positioning.
- Medium:Mass-market accessibility targets multi-dog households with varied breed sizes.
- Small:Compact formats address toy breeds with proportionally lower material throughput.
Large formats dominate revenue contribution; extra large formats show steepest expansion trajectory.
Type:
Functional engagement duration and behavioral enrichment value differentiate type selection across buyer segments.
- Chew Toys:Sustained mechanical stress designs with abrasive surface textures support dental health claims. FDA Center for Veterinary Medicine food-contact certification is legitimizing premium pricing for safety-validated formulations in the United States.
- Interactive Toys:Motion-activated and sensor-integrated formats extend engagement duration through behavioral feedback. Direct-to-consumer subscription models are personalizing chew-cycle matching based on breed-specific durability testing.
- Fetch Toys:Aerodynamic geometries prioritize retrieval flight stability over bite resistance.
- Puzzle Toys:Treat-dispensing mechanisms integrate cognitive challenge with mechanical durability.
Chew toys anchor volume; interactive toys command pricing premiums.
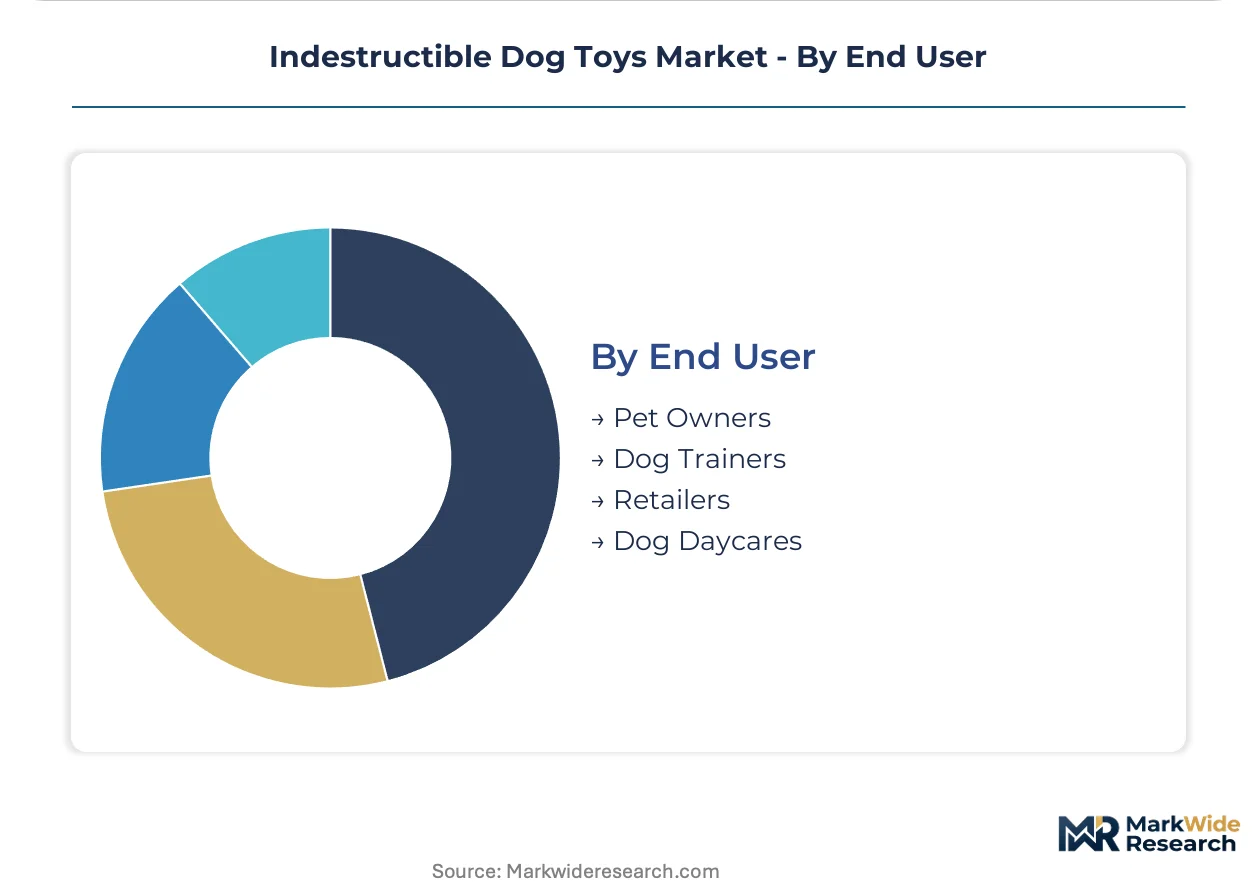
End User:
Procurement authority and volume scale separate institutional buyers from household purchasing patterns.
- Pet Owners:Individual household purchasing decisions prioritize safety certification and veterinary endorsement. California and New York extended producer responsibility mandates are shifting preference toward closed-loop recyclable TPR programs.
- Dog Daycares:High-throughput institutional environments demand extreme durability with sanitization compatibility. ASTM F963 toy safety compliance is non-negotiable for liability coverage in commercial boarding facilities.
- Dog Trainers:Behavioral reinforcement applications require predictable reward timing and consistent texture profiles.
- Retailers:Assortment breadth requirements drive private label specification of custom Shore A hardness ranges.
Pet owners represent transaction volume; dog daycares concentrate bulk procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Montana-based thermoplastic recycling operations anchor North American supply chain diversification as pet humanization deepens premium spending across developed economies.
United States
Heavy chewer breed ownership and veterinary endorsement concentrate demand for FDA food-contact certified formulations. California Proposition 65 chemical disclosure requirements and state-level extended producer responsibility mandates favor domestic TPR compounders. Montana and Ohio injection molding clusters capture share from Guangdong-sourced imports as brands seek regional supply security.
Germany
REACH substance restriction expansions and EU Green Deal biopolymer certification schemes elevate material disclosure requirements for compounders. ECHA documentation mandates for full supply chain substance inventories consolidate supplier bases toward integrated manufacturers. Bavarian laboratory testing facilities serve as CE-marking gateways for exporters targeting European veterinary channels.
China
Guangdong and Zhejiang mold tooling clusters retain cost advantages for commodity-grade nylon and rubber formulations. SAMR food-contact material standards and dual carbon goals are pressuring smaller compounders toward consolidation. Yangtze River Delta manufacturers are retooling for faster changeover cycles as specialty retailer consolidation demands SKU flexibility.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance burdens for compounders serving both markets. London-based specialty pet retail consolidation displaces independent boutique purchasing autonomy. Midlands distribution hubs increasingly bypass distributor intermediaries for direct brand-retailer negotiation on custom Shore A specifications.
Japan
METI industrial standards for pet product safety and JIS material certification requirements sustain premium pricing for validated formulations. Kanto region veterinary behaviorist research institutions accelerate breed-specific durability testing protocol adoption. Osaka-based compounders specialize in mineral-fill reinforced TPR for dental health positioning in aging pet demographics.
Indestructible Dog Toys Market Competitive Landscape
Global majors compete with regional champions across material compounding expertise and veterinary channel access. The vendor base stratifies into three tiers: integrated compounders with captive rubber expertise, domestic injection molders leveraging regional supply security, and sustainability-positioned recyclers occupying niche differentiation. Strategic moves center on backward integration into polymer compounding and geographic capacity diversification to mitigate Asian manufacturing concentration risks.
Within the integrated compounder tier, KONG Company and Benebone exemplify divergent moat construction. KONG Company leverages captive rubber compounding expertise to sustain margin control across classic and extreme product lines. Benebone anchors its position through domestic nylon injection molding that differentiates against commodity imports. West Paw occupies a defensible sustainability niche via Montana-based thermoplastic recycling operations serving closed-loop recyclable TPR demand.
| Leading Market Players |
|---|
| Benebone |
| ZippyPaws |
| KONG Company |
| Beco Pets |
| Bulletproof Pet Products |
| West Paw |
| Chuckit! |
| Jolly Pets |
| GoughNuts |
| Others |
Value Network & Pricing Analysis
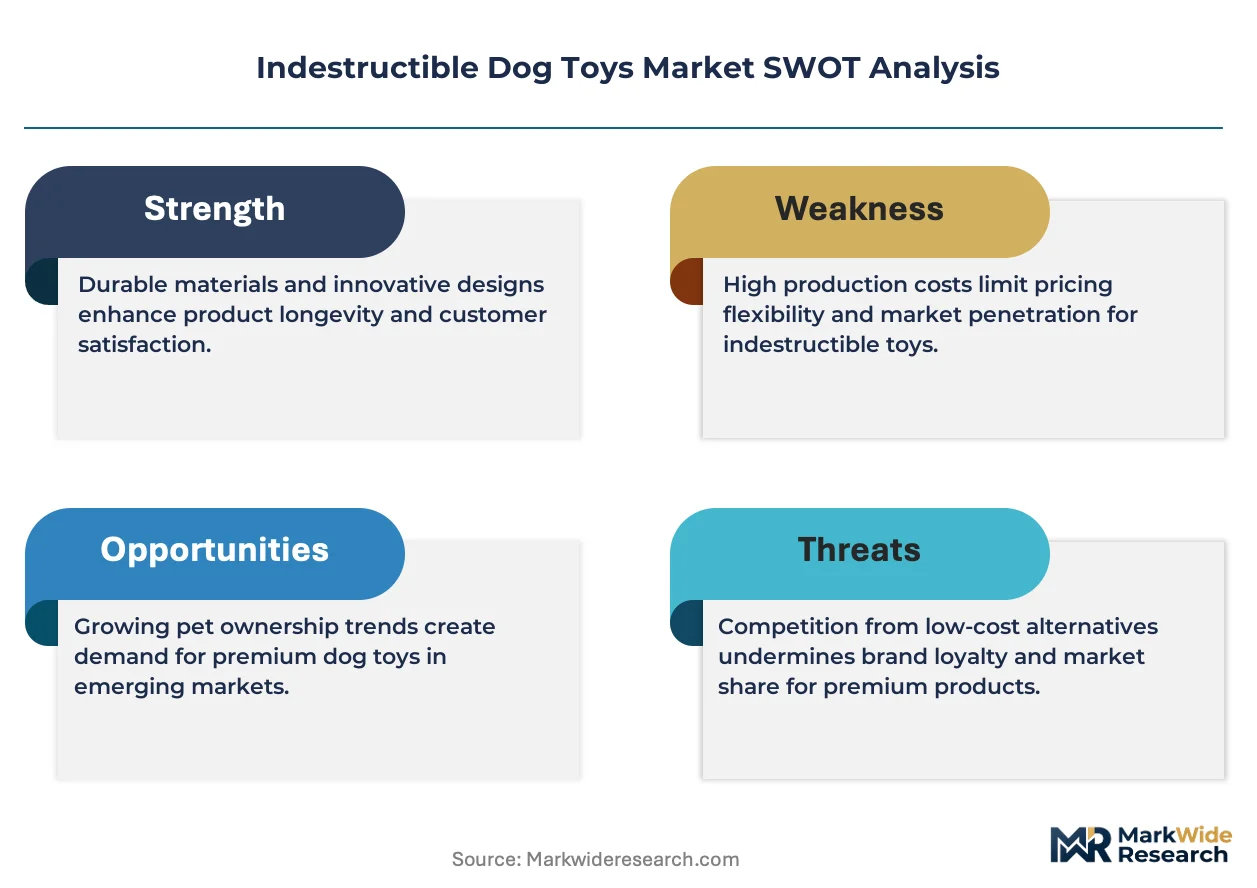
Certification-grade divergence between FDA food-contact validated formulations and commodity imports splits pricing power across parallel supply chains. Premium tiers capture margin through captive rubber compounding and veterinary endorsement, while mid-market TPR alternatives compete on regional sourcing flexibility against Asian manufacturing concentration.
Pricing Analysis
Petroleum-derived synthetic rubber and nylon resin pass-through costs from crude oil indices compress margin predictability for non-integrated compounders. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA certification status and Shore A hardness validation. Pricing pressure stems from TPR compounding advances enabling mid-tier performance without cross-linking costs. Heavy chewer breed owners show lowest price sensitivity; mass-market multi-dog households exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification across domestic TPR compounders and Asian mold houses. Manufacturing draws from China, the United States, and Germany for tooling, compounding, and testing respectively. Raw material dependencies center on synthetic rubber feedstocks, nylon resins, and mineral-fill reinforcements. Single-source vulnerability concentrates in Guangdong injection molding clusters. Distribution runs through specialty pet retail consolidation and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indestructible dog toys constitute a late-cycle quality story as pet humanization shifts demand toward FDA-validated safety specifications and breed-specific durability testing. Premium positioning now requires substantiated veterinary claims rather than commodity durability marketing.
For Market Incumbents: Lock in captive rubber compounding expertise and domestic injection capacity to defend against TPR substitution and regional supply chain diversification demands. Invest in backward integration toward polymer feedstock control. Prioritize California and New York extended producer responsibility compliance to capture closed-loop recyclable program advantages.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting heavy chewer breed owners with personalized chew-cycle matching based on durability testing protocols. Exploit white space in giant breed extra-large formats where veterinary behaviorist endorsement remains underdeveloped. Pursue prescription-channel positioning through substantiated dental health claims.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size manufacturers lack dedicated FDA food-contact notification preparation capabilities and specialized regulatory affairs talent. Long-term viability favors integrated compounders with captive laboratory testing and multi-jurisdiction certification infrastructure. Watch biopolymer certification scheme adoption rates as inflection indicator for sustainability-premium capture potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive rubber expertise sustains margin control against TPR substitution threats. |
| FDA Food-Contact Certification Investment | Veterinary endorsement legitimizes premium pricing in United States specialty channels. |
| Regional Manufacturing Footprint Expansion | Montana and Ohio TPR operations reduce Guangdong concentration risk exposure. |
| Direct-to-Consumer Subscription Launch | Breed-specific durability testing reduces customer acquisition costs and improves lifetime value. |
| Sustainability Repositioning via Closed-Loop TPR | California extended producer responsibility mandates create first-mover recyclable program advantages. |
Research Methodology
Coverage spans the United States, Germany, China, the United Kingdom, and Japan, with primary inputs from each market. The approach combines interviews with veterinary behaviorists, specialty pet retail category buyers, polymer compounders, and regulatory affairs specialists with secondary validation from FDA Center for Veterinary Medicine filings, CPSC safety standard databases, ECHA REACH substance inventories, and customs trade records. Bottom-up SKU-level demand modeling triangulates against top-down macroeconomic pet spending indicators.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models material type, size category, functional type, and end-user procurement authority as core segmentation dimensions. CAGRs derive from breed-specific ownership trajectories, premium spending elasticity, and replacement cycle compression patterns. Forecast inputs incorporate Shore A hardness specification adoption curves and veterinary channel endorsement velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biopolymer performance ceiling constraints and geopolitical logistics disruption scenarios. Deviation in FDA enforcement intensity or state-level extended producer responsibility acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Cat Harness Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Asia-Pacific Pet Travel Services Market