
 South America Cat Food Market | 2026-2036
South America Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cat Food Market Insights
Aftermarket nutritional consulting and subscription-based feeding programs is reshaping margin pools away from one-time dry food transactions. Mars Incorporated leverages its Purina and Royal Canin portfolios to anchor premium positioning across Brazilian veterinary channels. Nestle Purina PetCare competes through specialized wet food formulations targeting renal and digestive health segments. Total Alimentos dominates mid-range dry food distribution through deep penetration into independent pet stores and regional supermarket chains.
South America cat food encompasses complete and complementary diets formulated to feline nutritional requirements, typically manufactured through extrusion, canning, or retort processing with protein contents ranging from 25% to 45% on a dry matter basis, designed to deliver essential taurine, arachidonic acid, and vitamin A not synthesized by obligate carnivores. Wet food commands disproportionate shelf space in Brazilian pet stores as owners prioritize hydration-linked urinary health, while grain-free positioning attracts allergy-conscious purchasers despite higher per-kilogram cost structures. Private label lines occupy expanding retail territory as supermarket chains develop captive pet food portfolios under Mercosur-compliant manufacturing partnerships.
ANVISA enforces ingredient declaration and contaminant thresholds for imported and domestically produced pet foods, while Brazil's Ministry of Agriculture (MAPA) monitors slaughterhouse byproduct sourcing through SIF-inspected facilities; Mercosur's GMC resolutions facilitate cross-border trade but require harmonized additive approvals across member states. Argentina's SENASA maintains parallel inspection protocols that delay non-regional product entry. Stakeholders must monitor pending GMO labeling expansions and proposed restrictions on synthetic preservatives that could force reformulation across mid-range product tiers.
Market Dynamics
Pet humanization in Brazil's metropolitan corridors is restructuring purchase patterns toward subscription-based nutritional programs and veterinary-channel premiumization, compressing traditional supermarket dry-food transactions.
Growth Catalysts
- ANVISA Traceability Mandates:Harmonized ingredient declaration standards across Mercosur member states reduce cross-border friction for Brazilian manufacturers exporting to Argentina and Uruguay.
- Wet Food Formulation Advances:Retort processing improvements enable higher protein retention in shelf-stable formats, aligning with urinary health positioning sought by São Paulo's urban cat owners.
- Veterinary Channel Expansion:Specialized renal and digestive health diets distributed through Brazilian veterinary clinics capture margin pools unavailable through mass retail.
Market Restraints
- Poultry Byproduct Supply Concentration:Brazil's SIF-inspected slaughterhouse network concentrates protein sourcing in the South and Southeast regions, exposing formulations to regional supply shocks.
- Import Inspection Friction:Argentina's SENASA maintains non-harmonized entry protocols that delay non-regional product clearance, limiting competitive pressure on domestic producers.
- Synthetic Preservative Restrictions:Pending MAPA limitations on BHA and BHT usage force mid-tier manufacturers toward shorter shelf-life natural alternatives with higher spoilage risk.
Strategic Opportunities
- Subscription Direct-to-Consumer Models:São Paulo and Rio de Janeiro metro areas show underpenetrated demand for automated replenishment services bypassing traditional retail markup.
- GMO Labeling Pre-Positioning:Anticipated Mercosur expansion of genetically modified organism disclosure requirements creates first-mover advantage for certified non-GMO product lines.
- Independent Pet Store Consolidation:Regional chains in Brazil's Northeast and Central-West seek captive private-label partnerships with MAPA-compliant manufacturers.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Brazilian universities produce insufficient feline clinical nutrition specialists to staff expanding veterinary-channel consultation services.
- Extrusion Equipment Retrofit Costs:Grain-free and high-moisture formulation shifts require capital-intensive extruder modifications at existing Brazilian production facilities.
- Cross-State Cold Chain Gaps:Temperature-controlled distribution infrastructure remains underdeveloped between Brazil's coastal manufacturing centers and interior consumption markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cat Food Market |
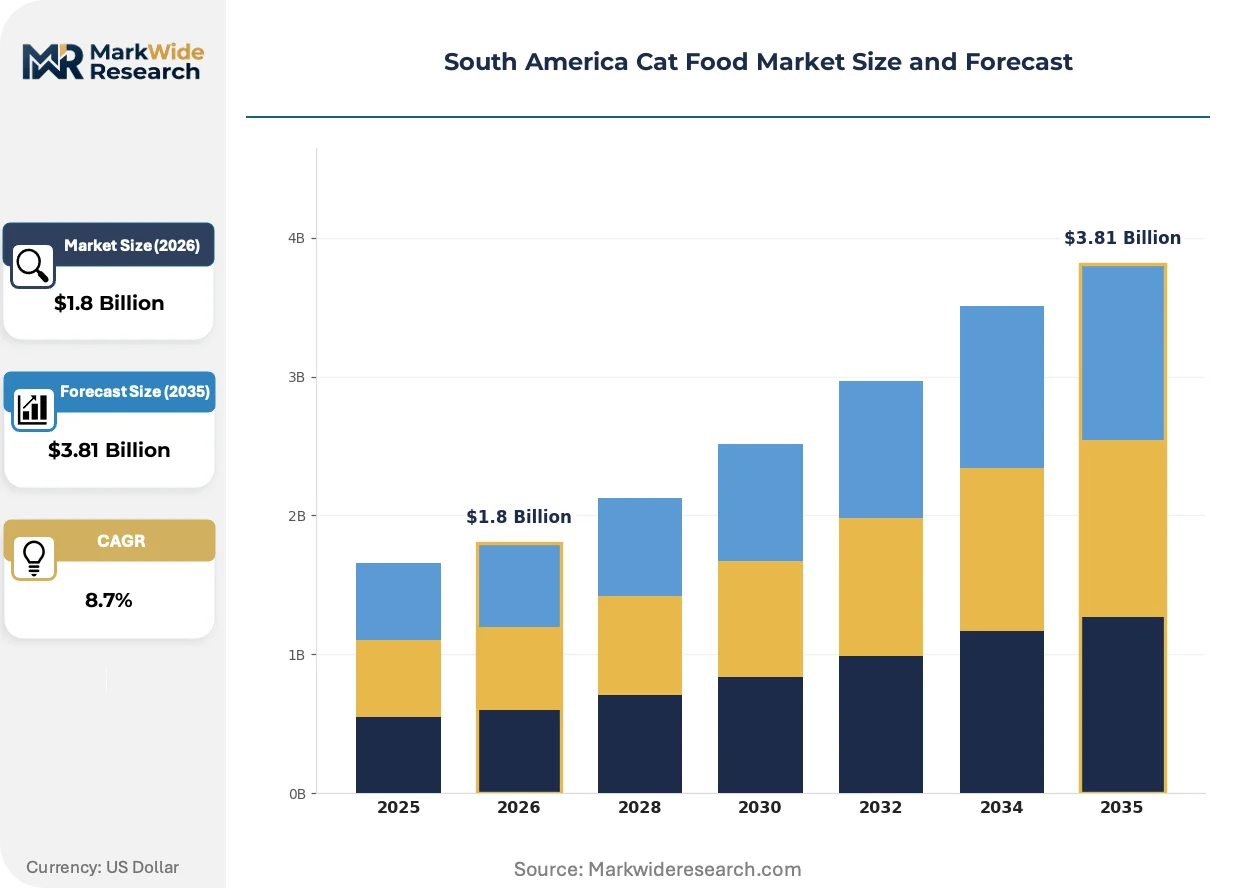
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Grain-Free Distribution Channel: Supermarkets, Pet Stores, Online Retail, Veterinary Clinics Customer Type: Cat Owners, Shelters, Breeders, Hobbyists Brand Positioning: Premium, Mid-Range, Budget, Private Label |
| Companies Covered | Mars Incorporated, Nestle Purina PetCare, PremieRpet, BRF Global, Empresas Carozzi, ADM, Hill's Pet Nutrition, General Mills, Total Alimentos, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cat Food Market Trends and Innovations
Digital integration across formulation, distribution, and customer relationship management is compressing traditional margin structures while enabling precision nutrition delivery.
Blockchain-based ingredient traceability systems are digitizing supply chain verification from Brazilian SIF facilities through to retail shelf. Mid-sized manufacturers in São Paulo state deploy these platforms to preempt ANVISA audit requirements and accelerate Mercosur cross-border documentation. The technology is digitizing compliance cost structures, shifting competitive advantage toward data-integrated producers.
ANVISA's pending expansion of contaminant threshold testing for mycotoxins and heavy metals is tightening quality assurance protocols across Brazilian manufacturing. Domestic producers face accelerated laboratory certification timelines while imported products encounter enhanced border inspection sampling. Wet food and treat categories bear disproportionate compliance burden due to higher moisture content risk profiles.
Veterinary-channel bundling of diagnostic testing with prescribed therapeutic diets is displacing standalone retail purchasing in Brazil's Southeast corridor. São Paulo metropolitan clinics integrate in-house bloodwork with automated diet recommendation engines, capturing recurring revenue streams. This pattern concentrates most visibly among renal and diabetic feline patient populations.
South America Cat Food Market Segmentation
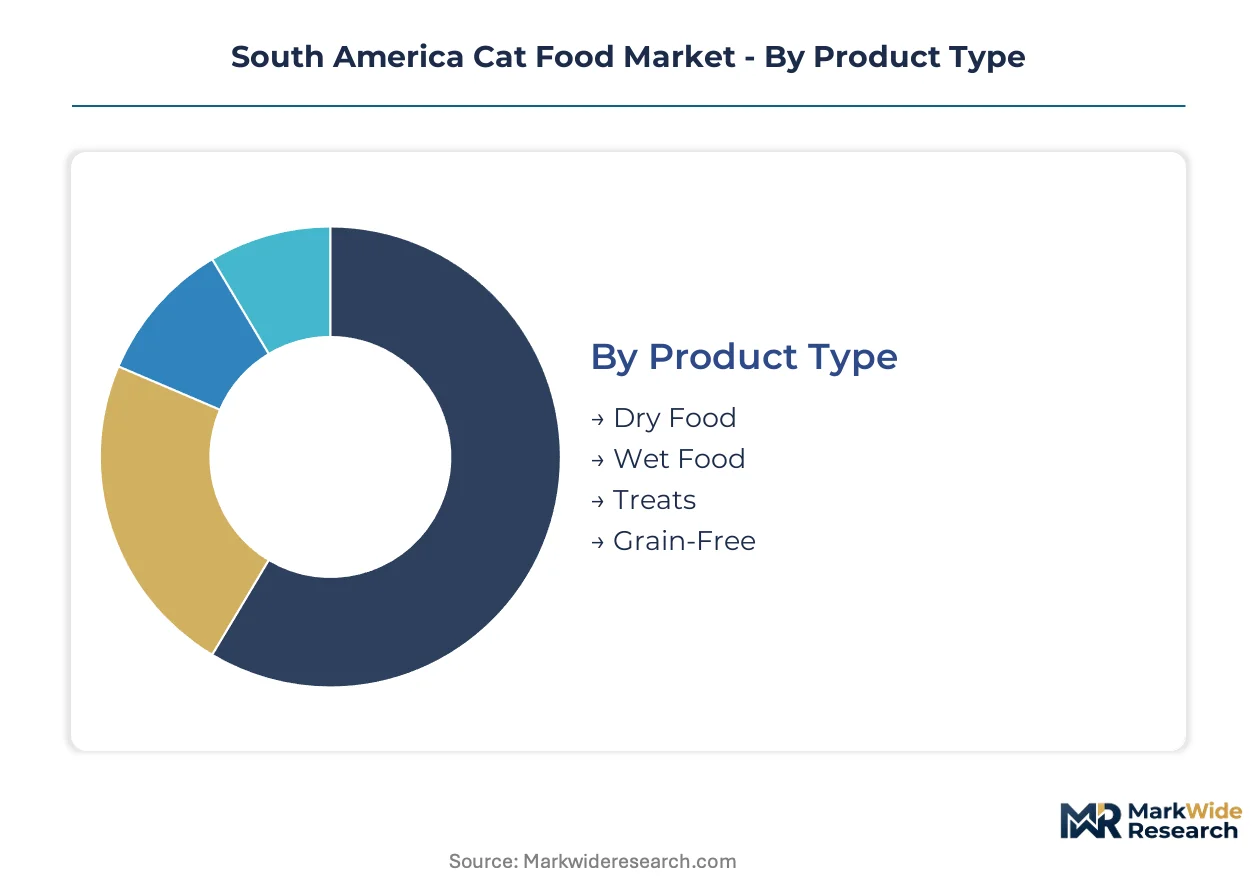
Cat food segmentation across South America reveals distinct consumption patterns tied to urbanization gradients, veterinary-channel sophistication, and regional income stratification. Manufacturers calibrate formulation, packaging, and pricing architectures against these intersecting dimensions to capture margin pools.
Product Type:
Dry formulations dominate volume throughput across cost-sensitive households, while wet and specialized diets concentrate in metropolitan corridors where urinary health awareness drives purchase decisions.
- Dry Food:Extruded kibble with 25-35% protein content serves as the baseline nutritional format across Brazil's interior states and Argentina's secondary cities. São Paulo's peripheral municipalities sustain bulk purchasing patterns through supermarket promotions and private-label penetration.
- Wet Food:Retort-processed cans and pouches with 75-85% moisture content address hydration-linked urinary tract health concerns among São Paulo and Rio de Janeiro's apartment-dwelling cat owners. ANVISA's contaminant threshold expansions disproportionately burden this category due to elevated spoilage risk profiles.
- Treats:Complementary nutritional and dental formulations occupy impulse-purchase positioning at veterinary clinic counters and pet store checkout zones.
- Grain-Free:Alternative carbohydrate sourcing through cassava and potato starches attracts allergy-conscious purchasers despite 15-25% per-kilogram cost premiums over conventional formulations.
The dominant share belongs to Dry Food, while Wet Food is closing the gap fastest.
Distribution Channel:
Channel selection directly determines margin capture, with veterinary and digital routes offering price integrity unavailable through mass retail price wars.
- Supermarkets:Hypermarket and grocery chains across Brazil's Southeast and Argentina's Buenos Aires province move high-velocity dry food SKUs through promotional slotting arrangements. Private-label expansion compresses branded manufacturer margins in this channel.
- Pet Stores:Independent and chain specialty retailers concentrate wet food and treat assortment depth, with São Paulo's metropolitan corridor hosting the densest network of MAPA-compliant stocking points.
- Online Retail:Subscription-based replenishment platforms bypass traditional distributor markups in Brazil's major metros, though cold chain limitations constrain wet food penetration to coastal zones.
- Veterinary Clinics:Therapeutic diet distribution through São Paulo's clinic network captures recurring revenue through prescription-linked renal and digestive health formulations.
Veterinary Clinics command the highest margin per transaction, while Online Retail is expanding most quickly.
Customer Type:
End-user economics stratify sharply between individual household premiumization and institutional procurement constraints.
- Cat Owners:Individual households across Brazil's urban corridors drive premium wet food and grain-free demand through pet humanization expenditure shifts.
- Shelters:Municipal and NGO-operated facilities in Argentina and Brazil prioritize cost-optimized dry food procurement through tender-based volume purchasing.
- Breeders:Professional cattery operations in São Paulo state and Buenos Aires province require specialized kitten growth and reproductive health formulations.
- Hobbyists:Small-scale breeding and exhibition participants sustain niche demand for show-quality coat and conditioning supplements.
Cat Owners account for the dominant revenue share, while Breeders demonstrate the steepest per-capita expenditure trajectory.
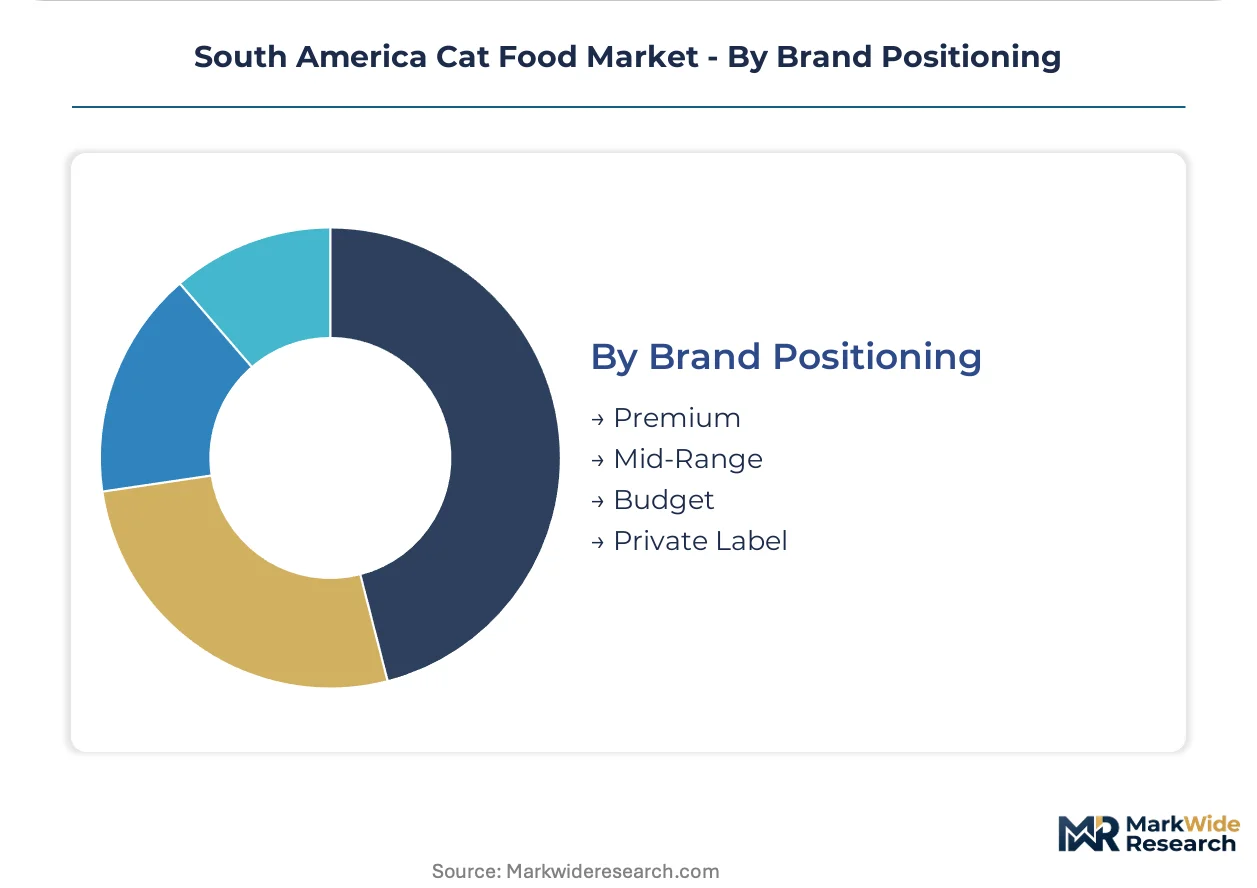
Brand Positioning:
Price-tier architecture aligns with channel access and ingredient sourcing transparency expectations.
- Premium:Veterinary-channel and specialty retail positioning with ANVISA-traceable ingredient declarations and specialized health claims. São Paulo's metropolitan corridor sustains the densest concentration of premium purchasing.
- Mid-Range:Supermarket and independent pet store distribution balancing quality signaling with mass-market accessibility across Brazil's Northeast and Central-West expansion zones.
- Budget:Price-driven dry food procurement through hypermarket promotions and regional wholesale clubs serving cost-constrained households.
- Private Label:Captive supermarket and chain pet store portfolios manufactured under Mercosur-compliant partnerships, gaining share through retail margin retention.
Mid-Range positioning holds the dominant volume position, while Private Label is gaining share fastest through retail chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across South American markets, with Brazilian metropolitan buyers absorbing premium wet food premiums while Argentine interior households remain tethered to bulk dry food procurement.
Brazil
Pet humanization in São Paulo's metropolitan corridor drives subscription-based nutritional programs and veterinary-channel premiumization. ANVISA's traceability mandates and MAPA's SIF-inspected facility requirements tighten ingredient sourcing protocols. São Paulo state anchors manufacturing concentration, with retort processing facilities clustering along the coastal logistics corridor.
Argentina
Urban cat owners in Buenos Aires province prioritize urinary health formulations, sustaining wet food demand despite macroeconomic volatility. SENASA maintains non-harmonized import inspection protocols that delay non-regional product clearance. Buenos Aires metropolitan area concentrates specialty retail and veterinary clinic distribution networks.
Chile
Santiago's apartment-dwelling cat owners exhibit strong hydration-awareness, supporting shelf-stable wet food penetration. The country's national agricultural regulator enforces contaminant thresholds aligned with Mercosur harmonization standards. Metropolitan Santiago hosts the densest network of MAPA-compliant import distribution points.
Colombia
Bogotá's emerging middle class drives mid-range dry food volume through supermarket promotional cycles. Pending GMO labeling expansions create regulatory uncertainty for imported formulations. Bogotá and Medellín metropolitan corridors concentrate pet store chain expansion and private-label portfolio development.
Uruguay
Montevideo's small but premium-oriented market sustains specialized therapeutic diet demand through veterinary channels. Mercosur's GMC resolutions facilitate Brazilian cross-border supply, reducing import friction. Montevideo anchors distribution for regional supermarket chains developing captive pet food portfolios.
South America Cat Food Market Competitive Landscape
Capability concentration sits with multinational nutrition science portfolios; scale advantage sits with domestic manufacturing networks optimized for Mercosur distribution. The market structures around three tiers: global nutrition specialists with veterinary-channel anchoring, regional mid-range manufacturers with supermarket penetration, and emerging private-label platforms. Consolidation pressures concentrate among mid-tier Brazilian producers facing extrusion equipment retrofit costs. Dominant competitive moves include backward integration into SIF-inspected protein sourcing and subscription platform development bypassing traditional retail markup.
Within the global specialist tier, Mars Incorporated and Nestle Purina PetCare occupy positions defined by veterinary-channel density and renal health formulation portfolios. Among Brazil-based manufacturers, Total Alimentos exemplifies mid-range scale advantage through independent pet store and regional supermarket chain penetration. These three anchors represent divergent strategic postures: nutrition science premiumization, mass-market distribution efficiency, and regional manufacturing consolidation.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle Purina PetCare |
| PremieRpet |
| BRF Global |
| Empresas Carozzi |
| ADM |
| Hill's Pet Nutrition |
| General Mills |
| Total Alimentos |
| Others |
Pricing and Supply Chain Analysis
Poultry byproduct supply concentration in Brazil's SIF-inspected slaughterhouse network determines both pricing tier spreads and supply chain shape, compressing mid-range margins while amplifying premium-tier veterinary-channel pricing power. ANVISA's pending synthetic preservative restrictions are forcing shorter shelf-life alternatives that reshape cost structures across formulation tiers.
Pricing Analysis
Subscription-based nutritional consulting drives lifetime value beyond one-time dry food transactions, displacing transactional supermarket purchasing. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-prescribed renal formulations from mid-range independent pet store SKUs and budget hypermarket promotions. Cost compression in the mid-tier intensifies because private-label expansion at regional Brazilian chains erodes branded manufacturer margins. Shelters and municipal procurement teams exhibit highest price sensitivity, while São Paulo metropolitan cat owners absorbing wet food premiums show least elasticity.
Supply Chain Analysis
Upstream feedstock dependency on Brazil's South and Southeast region slaughterhouse byproducts concentrates protein sourcing within Mercosur's SIF-inspected facility network. Raw material inputs draw from poultry meal, fish hydrolysates, and cassava starch alternatives for grain-free positioning. Single-source vulnerability in Brazil's interior cold chain gaps exposes wet food distribution to temperature excursion risks. Distribution runs through São Paulo's coastal manufacturing corridor into veterinary clinics, independent pet stores, and emerging subscription platforms bypassing traditional wholesale markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a defensive-moat story anchored in regulatory entrenchment: ANVISA's traceability mandates and MAPA's SIF facility requirements create compliance barriers that protect incumbent veterinary-channel positioning.
For Market Incumbents: Insulate premium positioning through backward integration into SIF-inspected protein sourcing, securing captive supply of slaughterhouse byproducts against regional supply shocks. Deepen veterinary-channel control by embedding diagnostic testing capabilities within São Paulo metropolitan clinics, creating switching costs for cat owners with prescribed therapeutic diets. Counter private-label encroachment through blockchain-based ingredient traceability platforms that preempt ANVISA audit requirements.
For New Entrants and Emerging Players: Brazil's Northeast and Central-West regional chains present underpenetrated white space for MAPA-compliant private-label partnerships, bypassing saturated Southeast corridor competition. Subscription direct-to-consumer models in Rio de Janeiro metro areas offer automated replenishment entry points unclaimed by incumbent distributor networks. Lead with GMO-labeling pre-positioning to capture anticipated Mercosur disclosure expansion first-mover advantage.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-range manufacturers with extrusion equipment retrofit capabilities and established independent pet store penetration. Long-term viability hinges on cold chain infrastructure investment bridging coastal production to interior consumption markets. Watch ANVISA's synthetic preservative restriction timeline as inflection indicator for natural alternative formulation capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SIF-Inspected Protein Sourcing | Captive supply of slaughterhouse byproducts secures formulation cost stability against regional supply shocks. |
| Veterinary Diagnostic Testing Bundling | São Paulo clinic networks integrate bloodwork with automated diet recommendations, capturing recurring revenue streams. |
| Blockchain Traceability Platform Deployment | São Paulo state manufacturers digitize supply chain verification to preempt ANVISA audit requirements. |
| Subscription Direct-to-Consumer Launch | Automated replenishment platforms in Rio de Janeiro bypass traditional retail markup and distributor control. |
| GMO Labeling Pre-Positioning | Certified non-GMO product lines capture first-mover advantage ahead of anticipated Mercosur disclosure expansion. |
Research Methodology
Desk research of ANVISA regulatory filings, MAPA SIF facility registries, and Mercosur GMC resolution databases preceded structured interviews with veterinary nutrition specialists, independent pet store procurement managers, and regional supermarket category buyers. Secondary validation drew from Brazilian customs trade records, pet industry association production surveys, and clinic network expansion databases. Bottom-up demand modeling across cat owner expenditure tiers triangulated against top-down manufacturer capacity assessments.
Assumptions held ANVISA traceability mandate implementation timelines and MAPA preservative restriction scopes fixed while varying protein input cost trajectories and veterinary-channel penetration rates across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and brand positioning tier. CAGRs derived from volume-weighted average price movements and segment-level demand elasticity coefficients, with wet food formulation advances and subscription platform adoption as industry-specific demand shapers.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or Argentine peso volatility would shift import competitiveness and cross-border manufacturing investment trajectories. Forecasts reflect documented assumptions regarding regulatory implementation pacing and cold chain infrastructure development. Cross-checking against veterinary clinic network expansion benchmarks and pet store chain consolidation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Cat Cage Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Automatic Dog Feeder Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Dog Brush Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Pet Collar Market
Pet Care Products
Dog Seat Covers Market