
 Pet Food Nutraceutical Market | 2026-2036
Pet Food Nutraceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Nutraceutical Market Analytics
North American production capacity is tilting toward dedicated pet nutraceutical facilities as brands respond to ingredient traceability mandates. Mars Incorporated leverages backward integration into omega-3 sourcing to secure supply chain stability for its therapeutic diets. Nestlé Purina PetCare Company anchors its position through veterinary-exclusive distribution channels that require clinical validation. Hill's Pet Nutrition, Inc. dominates prescription-grade formulations with science-backed protocols developed in collaboration with academic veterinary centers.
Pet food nutraceuticals comprise bioactive compounds including glucosamine, probiotics, omega fatty acids, and antioxidants formulated into palatable matrices that deliver measurable physiological benefits beyond basic nutrition. These products undergo extrusion or cold-press processing to preserve thermolabile active ingredients, with stability testing confirming label claim potency through stated shelf life. Functional treats lead volume due to owner compliance advantages, while supplements command premium positioning through veterinary endorsement and condition-specific dosing protocols. Plant-based ingredient sourcing is accelerating fastest as sustainability-conscious owners reject marine-derived inputs, though synthetic vitamins retain cost advantages in mass-market formulations.
The FDA Center for Veterinary Medicine scrutinizes structure-function claims to prevent unapproved drug categorization, while the Association of American Feed Control Officials establishes nutrient profiles that manufacturers must meet for complete-and-balanced designations. State-level feed control officials conduct facility inspections and label audits that determine market access for new entrants. Stakeholders must monitor evolving positions on cannabidiol and other novel ingredients, as regulatory clarity will determine which innovation pipelines achieve commercial scale.
Market Dynamics
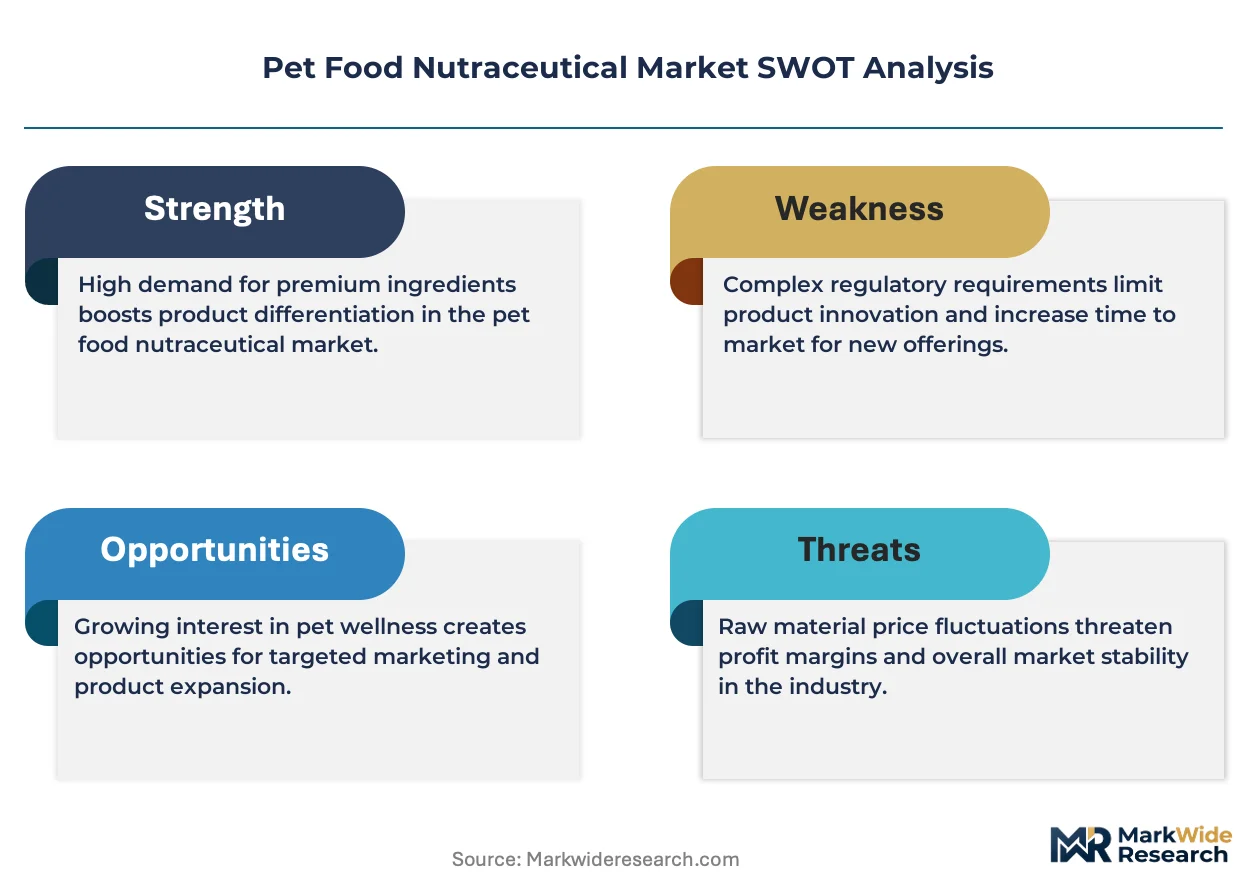
Veterinary prescription protocols are compressing the boundary between therapeutic diets and over-the-counter supplements, forcing manufacturers to recalibrate formulation strategies around clinical validation requirements.
Growth Catalysts
- Condition-Specific Formulation Demand:Senior dog populations with diagnosed osteoarthritis and cognitive dysfunction syndrome now drive veterinary channel volume for glucosamine and phosphatidylserine matrices.
- EFSA Novel Food Guidance:Clarified safety assessment pathways for plant-derived bioactives accelerate European commercialization timelines for algae-sourced omega-3 alternatives.
- Cold-Press Processing Scale-Up:Equipment manufacturers deploy low-temperature extrusion lines that preserve thermolabile probiotic viability through finished goods distribution.
Market Restraints
- Marine Ingredient Price Volatility:Peruvian anchovy quota fluctuations transmit directly to krill oil and fish oil concentrate input costs, destabilizing margin structures for mass-market omega-3 formulations.
- FDA Structure-Function Scrutiny:The Center for Veterinary Medicine's intensified review of joint health claims creates regulatory friction that delays product launches and necessitates claim hedging.
- Probiotic Strain Patent Thickets:Exclusive licensing arrangements around documented canine gut microbiome strains concentrate viable commercial options among three supplier networks.
Strategic Opportunities
- Subscription Direct-to-Consumer Channels:Automated replenishment platforms bypass veterinary gatekeepers for maintenance-phase supplements, capturing lifetime value from acquired pet owners.
- AAFCO Nutritional Adequacy Expansion:Proposed profiles for geriatric life-stage diets create regulatory tailwind for condition-specific complete-and-balanced positioning.
- Plant Protein Fermentation Convergence:Precision fermentation of mycoprotein and algal biomass intersects with palatability engineering to displace rendered animal proteins in hypoallergenic matrices.
Industry Challenges
- Clinical Trialist Scarcity:Veterinary nutrition researchers with GCP certification command premium retainers, bottlenecking evidence generation for structure-function substantiation.
- Legacy ERP Integration:Batch record systems designed for conventional feed manufacturing require expensive reconfiguration to capture nutraceutical potency tracking and stability data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Nutraceutical Market |
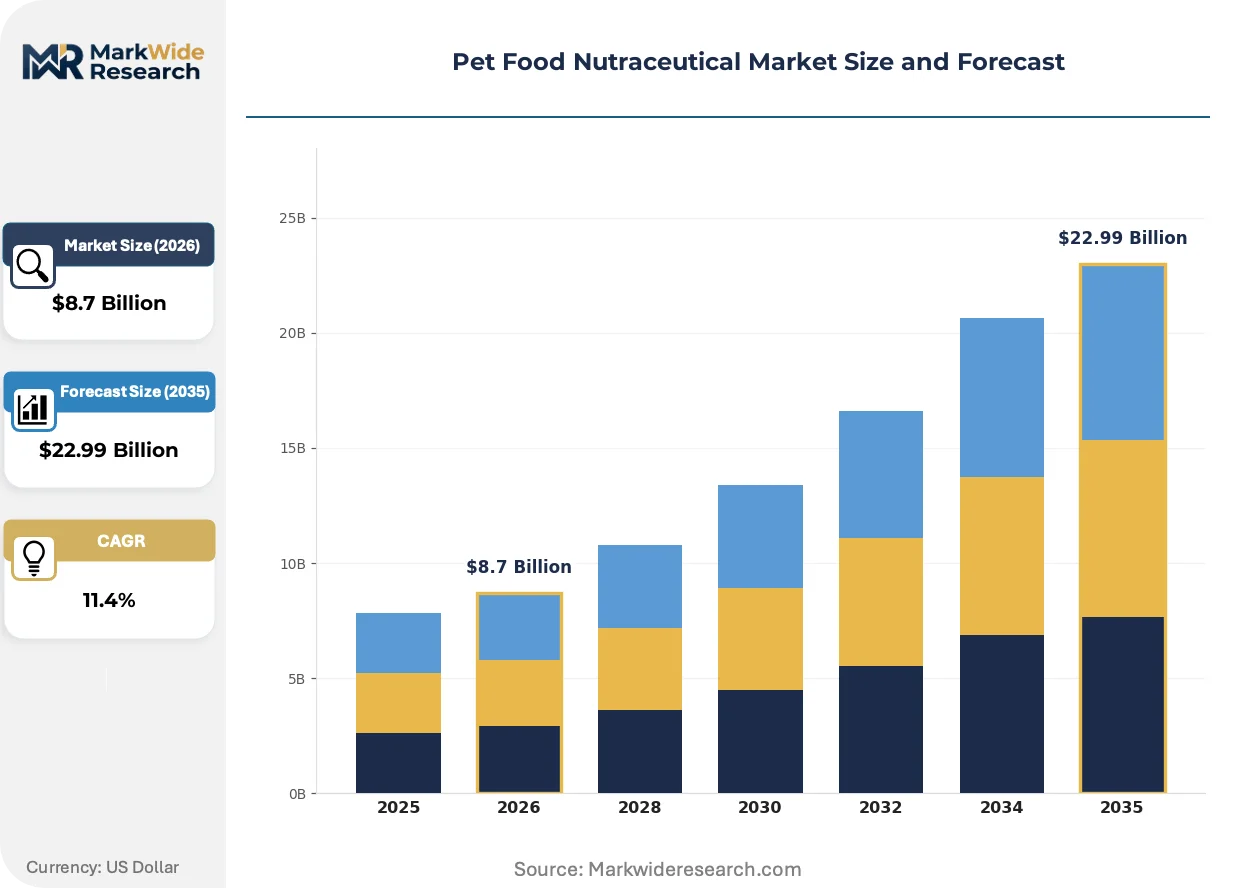
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Functional Treats, Vitamins, Herbal Remedies Ingredient Source: Plant-Based, Animal-Sourced, Synthetic, Natural Extracts Animal Type: Cats, Dogs, Birds, Small Mammals Distribution Channel: Online Retail, Pet Specialty Stores, Veterinary Clinics, Supermarkets |
| Companies Covered | The J. M. Smucker Company, WellPet LLC, Mars Incorporated, Nutramax Laboratories Veterinary Sciences, Inc., Spectrum Brands Holdings, Inc., Nestlé Purina PetCare Company, General Mills Inc., Elanco Animal Health Incorporated, Hill's Pet Nutrition, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Nutraceutical Market Evolving Landscape
Formulation science is converging with digital health infrastructure to create measurable outcome linkages that justify premium positioning beyond ingredient marketing.
Microencapsulation technology is collapsing the stability gap between shelf-stable and refrigerated probiotic delivery. Veterinary-exclusive brands now specify colony-forming unit retention at 18-month shelf life as a procurement threshold. This compression enables mass-market distribution without cold-chain dependency, restructuring competitive requirements across retail and professional channels.
REACH authorization timelines for novel feed additives are extending safety data requirements for European market entry. Manufacturers must now submit extended one-generation toxicity studies for botanical extracts previously grandfathered under botanical status. Small and mid-scale formulators without dedicated regulatory affairs functions face exclusion from the EU market, consolidating access among resourced multinationals.
Pet owner purchasing has migrated toward veterinary-validated subscription bundles that integrate diagnostic testing with tailored supplementation protocols. Telehealth platforms now capture recurring revenue through algorithm-driven reorder triggers based on at-home health monitoring data. This channel shift concentrates most visibly in United States metropolitan markets where veterinary deserts have normalized remote care relationships.
Pet Food Nutraceutical Market Segmentation
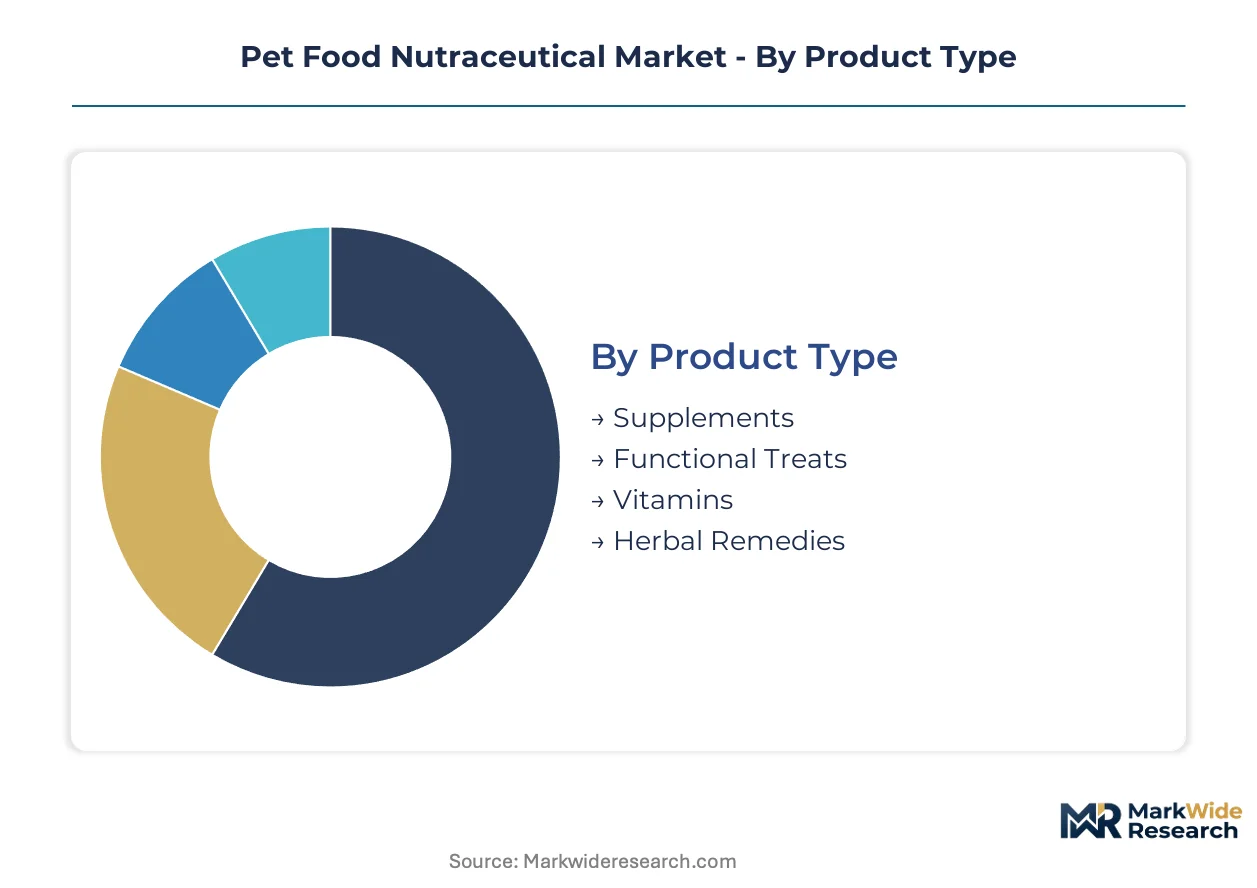
Segmentation in pet food nutraceuticals determines formulation priorities, regulatory pathways, and channel economics. Product type and ingredient sourcing decisions cascade through manufacturing investments and margin structures. Distribution channel selection locks in customer acquisition costs and repeat purchase rates.
Product Type:
Functional treats turn inventory fastest through impulse-driven replenishment cycles, while veterinary-exclusive supplements sit longest on shelves awaiting prescription authorization.
- Functional Treats:Palatable matrices embed glucosamine, omega fatty acids, and antioxidants into extruded or cold-pressed formats. United States metropolitan markets concentrate demand for dental-functional hybrids that combine joint support with tartar control, driven by owner compliance advantages over pill-form alternatives.
- Supplements:Condition-specific powders, liquids, and capsules require veterinary endorsement and precise dosing protocols. Prescription-grade formulations for canine osteoarthritis and cognitive dysfunction syndrome anchor professional channel volume, constrained by FDA Center for Veterinary Medicine scrutiny of structure-function claims.
- Vitamins:Synthetic and natural vitamin premixes address nutritional gaps in homemade or limited-ingredient diets.
- Herbal Remedies:Botanical extracts including turmeric and ashwagandha target anxiety and inflammation management.
Functional treats anchor the volume base while supplements gain share at the steepest rate through veterinary channel expansion.
Ingredient Source:
Cost tiering separates premium-positioned natural extracts from commodity synthetic inputs, with plant-based sourcing commanding formulation investment due to sustainability-driven owner preferences.
- Plant-Based:Algae-sourced omega-3 alternatives and fermented mycoprotein displace marine ingredients in hypoallergenic matrices. EFSA novel food guidance accelerates European commercialization timelines for these bioactives, though REACH authorization extends safety data requirements for botanical extracts.
- Animal-Sourced:Krill oil, fish oil concentrates, and rendered proteins deliver bioavailable nutrients. Peruvian anchovy quota volatility destabilizes margin structures for mass-market omega-3 formulations dependent on marine inputs.
- Synthetic:Laboratory-produced vitamins and amino acids retain cost advantages in mass-market complete-and-balanced formulations.
- Natural Extracts:Cold-pressed botanicals and minimally processed marine derivatives target premium positioning through traceability narratives.
Synthetic inputs anchor the volume base while plant-based alternatives gain share at the steepest rate through sustainability-aligned procurement shifts.
Animal Type:
Application severity varies sharply across species, with canine formulations commanding the deepest clinical validation investments and feline products facing palatability engineering constraints.
- Dogs:Senior dog populations with diagnosed osteoarthritis and cognitive dysfunction syndrome drive veterinary channel volume for glucosamine and phosphatidylserine matrices. Condition-specific protocols developed in collaboration with academic veterinary centers dominate prescription-grade positioning.
- Cats:Palatability engineering requirements exceed canine standards due to finicky consumption patterns. Limited-volume formulations concentrate in renal support and urinary health applications where therapeutic diets intersect with supplement protocols.
- Birds:Avian-specific vitamin and mineral premixes address feather quality and reproductive health in companion parrots and poultry.
- Small Mammals:Rabbit, guinea pig, and ferret formulations target digestive and dental health through high-fiber and abrasive matrices.
Canine applications anchor the volume base while feline formulations gain share at the steepest rate through specialty channel expansion.
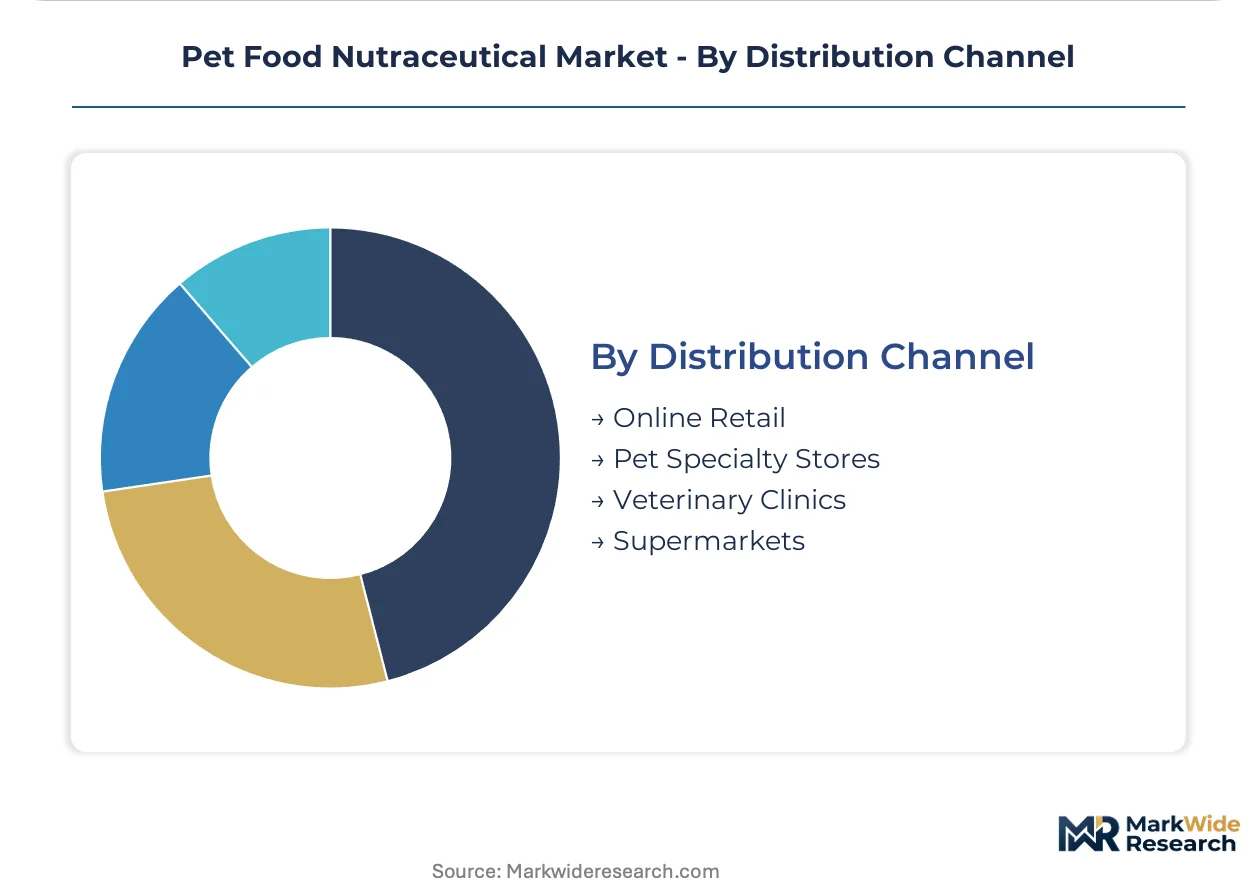
Distribution Channel:
Customer type stratification concentrates lifetime value in subscription direct-to-consumer platforms while veterinary clinics capture highest-margin prescription protocols.
- Veterinary Clinics:Exclusive distribution channels require clinical validation and condition-specific dosing protocols. Telehealth platforms now capture recurring revenue through algorithm-driven reorder triggers based on at-home health monitoring data.
- Online Retail:Automated replenishment platforms bypass veterinary gatekeepers for maintenance-phase supplements. United States metropolitan markets show highest subscription penetration where veterinary deserts have normalized remote care relationships.
- Pet Specialty Stores:Staff-trained recommendation environments support premium functional treat and supplement discovery.
- Supermarkets:Mass-market vitamin and basic supplement placement competes on price and shelf visibility.
Pet specialty stores anchor the volume base while online retail gains share at the steepest rate through subscription infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for pet food nutraceuticals clusters in jurisdictions with established feed control infrastructure and proximity to raw ingredient terminals. Regulatory stringency varies sharply across export markets, forcing producers to maintain multiple formulation dossiers.
United States
Veterinary prescription protocols and premiumization trends concentrate demand in metropolitan corridors. The FDA Center for Veterinary Medicine enforces structure-function claim boundaries that shape product development timelines. Kansas and Missouri host extrusion manufacturing clusters serving both therapeutic diets and over-the-counter supplements.
Germany
Sustainability-aligned procurement drives algae-sourced omega-3 formulation investments. EFSA novel food guidance accelerates safety assessments for plant-derived bioactives. The Baden-Württemberg region anchors precision fermentation R&D for mycoprotein-based hypoallergenic matrices.
China
Domestic pet ownership expansion creates import substitution pressure for condition-specific supplements. SAMR feed additive registration requirements tighten for foreign-manufactured probiotic strains. Zhejiang and Jiangsu provinces concentrate contract manufacturing capacity for export-oriented functional treat production.
United Kingdom
Veterinary channel consolidation elevates demand for clinically validated senior dog formulations. FSA and VMD coordinated oversight of pet supplement claims creates dual-track compliance obligations. The Southeast England corridor houses distribution hubs serving European subscription direct-to-consumer platforms.
Japan
Aging pet demographics mirror human trends, deepening demand for cognitive dysfunction and joint support products. MAFF and PMDA joint consultation procedures govern functional ingredient approvals. The Kanto region concentrates palatability engineering laboratories serving feline formulation requirements.
Pet Food Nutraceutical Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and processing equipment. The market structure tilts toward consolidated multinational platforms with captive veterinary distribution channels, while mid-scale formulators compete through subscription infrastructure and novel ingredient positioning. Three archetypes dominate: science-backed prescription-grade houses, mass-market functional treat platforms, and precision fermentation ingredient suppliers. Competitive moves concentrate on backward integration into omega-3 sourcing and cold-press processing scale-up.
Among diversified consumer goods conglomerates, Mars Incorporated and Nestlé Purina PetCare Company occupy positions as platform integrators with veterinary-exclusive channel control. Nutramax Laboratories Veterinary Sciences, Inc. exemplifies the clinical validation archetype through prescription-grade supplement protocols. These three anchors illustrate how regulatory compliance investment and distribution infrastructure determine tier positioning.
| Leading Market Players |
|---|
| The J. M. Smucker Company |
| WellPet LLC |
| Mars Incorporated |
| Nutramax Laboratories Veterinary Sciences, Inc. |
| Spectrum Brands Holdings, Inc. |
| Nestlé Purina PetCare Company |
| General Mills Inc. |
| Elanco Animal Health Incorporated |
| Hill's Pet Nutrition, Inc. |
| Others |
Value Network & Pricing Analysis
Kansas and Missouri extrusion manufacturing clusters concentrate production capacity for therapeutic diets and over-the-counter supplements, concentrating formulation expertise that commands premium pricing power over dispersed competitors lacking cold-press processing scale.
Pricing Analysis
FDA Center for Veterinary Medicine structure-function claim boundaries dictate the pricing tier structure across prescription-grade, veterinary-exclusive, and mass-market channels. Three-tier pricing separates clinically validated supplements with GCP certification from maintenance-phase functional treats and economy-positioned synthetic vitamin premixes. Pricing pressure stems from Peruvian anchovy quota volatility transmitting directly to marine-derived omega-3 input costs. Mass-market synthetic formulations face highest price sensitivity from cost-conscious owners, while prescription-grade protocols retain inelastic demand through veterinary endorsement.
Supply Chain Analysis
REACH authorization timelines for novel feed additives act as export-control equivalents, restricting European market flows for botanical extracts lacking extended one-generation toxicity studies. Raw material sourcing concentrates in Peru for marine omega-3s, Germany for precision fermentation mycoprotein, and China for contract manufacturing of functional treats. Cold-press processing equipment, probiotic strain licenses, and algae-derived bioactives constitute critical input dependencies. Single-source vulnerability concentrates in three supplier networks controlling documented canine gut microbiome strains. Distribution runs through veterinary clinics for prescription protocols and subscription direct-to-consumer platforms for maintenance-phase supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet food nutraceutical market exhibits cyclical recovery characteristics as post-pandemic veterinary visit normalization restores prescription protocol volumes that lagged during telehealth migration periods.
For Market Incumbents: Entrench competitive position through backward integration into omega-3 sourcing and captive cold-press processing capacity additions in Kansas manufacturing corridors. Defend against plant-based ingredient disruptors by securing exclusive licensing arrangements for documented probiotic strains before patent thickets consolidate further. Priority lever rests on veterinary-exclusive channel control through clinical validation investments that delay generic substitution. For New Entrants and Emerging Players: Southeast Asian veterinary deserts present underpenetrated demand for subscription direct-to-consumer platforms integrating at-home diagnostic testing with tailored supplementation protocols. White-space targets include feline cognitive dysfunction formulations where palatability engineering requirements exceed incumbent R&D investment thresholds. Go-to-market angle should leverage telehealth platform partnerships that bypass established veterinary gatekeeper relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods conglomerates seeking to divest non-core pet nutrition assets lacking veterinary channel integration. Long-term viability over the projection horizon favors precision fermentation ingredient suppliers with EFSA novel food guidance alignment and REACH authorization capabilities. Signal to monitor: AAFCO nutritional adequacy expansion for geriatric life-stage diets that would revalue condition-specific complete-and-balanced positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | GCP-certified veterinary nutrition research generates FDA-defensible structure-function claims for prescription-grade positioning. |
| Backward Integration into Omega-3 Sourcing | Captive algae fermentation capacity insulates margin structures from Peruvian anchovy quota volatility. |
| Veterinary-Exclusive Distribution Expansion | Telehealth platform partnerships capture recurring revenue through algorithm-driven reorder triggers. |
| Cold-Press Processing Scale-Up | Low-temperature extrusion lines preserve thermolabile probiotic viability through 18-month shelf life. |
| Plant-Based Ingredient Repositioning | Precision fermentation of mycoprotein aligns with sustainability-conscious owner procurement shifts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, AAFCO nutrient profile proposals, EFSA novel food safety assessments, and customs trade data for omega-3 concentrate imports. Primary interviews engaged formulation scientists at extrusion manufacturing clusters, regulatory affairs leads at veterinary-exclusive brands, procurement directors at algae fermentation facilities, and telehealth platform operators. Secondary validation drew from SEC filings of diversified pet care conglomerates, patent databases for probiotic strain licensing, and stability testing records for microencapsulation technologies. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Forecast inputs span condition-specific product type segmentation, ingredient source tiering, animal type application severity, and distribution channel economics across the analysis window. Modeled dimensions include functional treats versus supplements versus vitamins, plant-based versus marine-derived versus synthetic inputs, canine versus feline versus avian applications, and veterinary clinic versus online retail versus pet specialty store channels. CAGRs derive from elasticity-adjusted penetration curves calibrated against historical premiumization rates and regulatory approval timelines. Industry-specific inputs incorporate EFSA novel food guidance acceleration effects and REACH authorization timeline extensions.
Practitioners should monitor FDA structure-function claim enforcement intensity, Peruvian anchovy quota announcements, and AAFCO geriatric diet profile adoptions for early signals of forecast revision. Forecasts reflect assumptions regarding regulatory clarity on cannabidiol and novel botanical extracts, cold-chain infrastructure deployment for probiotic distribution, and veterinary telehealth platform consolidation trajectories. Material shifts in FDA Center for Veterinary Medicine oversight posture or EFSA safety data requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Perfume Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Cat Litter Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Pet Pens Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Canada Pet Training Services Market