
 Sensitive Stomach Cat Food Market | 2026-2036
Sensitive Stomach Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Sensitive Stomach Cat Food Market Analytics
AAFCO nutrient profiles and substantiated health claims is collapsing the competitive field to manufacturers with dedicated feeding-trial infrastructure. Hill's Science Diet leverages its captive veterinary channel to sustain prescription diet revenues. Royal Canin anchors its position through breed-specific digestive formulations. Ziwi Peak differentiates via air-dried novel protein sourcing from New Zealand.
Sensitive stomach cat food comprises nutritionally complete diets formulated with hydrolyzed proteins, single-source carbohydrates, and added prebiotic fibers to minimize gastrointestinal distress in felines with food intolerances, inflammatory conditions, or post-surgical recovery needs. Wet food commands margin pools through higher palatability and moisture content that aids renal function, while veterinary diets restrict distribution to clinic channels that enforce professional oversight. Grain-free and limited-ingredient categories attract owner attention amid allergen concerns, though digestive-health formulations with documented microbial strains represent the fastest-growing ingredient segment.
FDA Center for Veterinary Medicine oversight of pet food labeling and AAFCO model regulations govern nutritional adequacy statements and ingredient definitions across the United States. The EU's FEDIAF nutritional guidelines and national feed law implementations in Germany and France impose parallel compositional requirements on imported products. Stakeholders must monitor evolving veterinary telehealth regulations and direct-to-consumer prescription enforcement, as channel restrictions will determine which brand types capture the expanding clinically validated segment.
Market Dynamics
AAFCO feeding-trial requirements and FDA substantiation protocols are compressing product development timelines while elevating capital barriers for new entrants seeking veterinary channel access.
Growth Catalysts
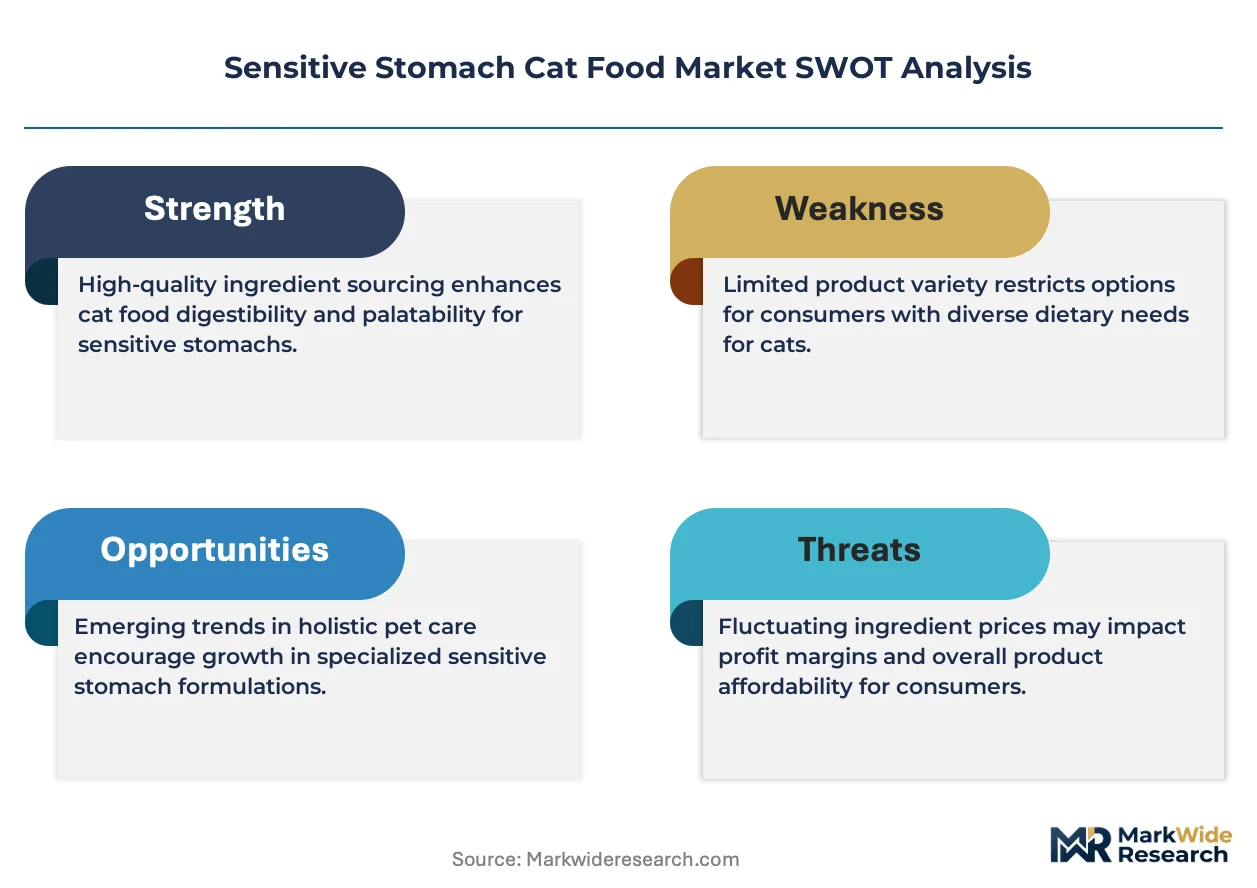
- FDA Center for Veterinary Medicine oversight:Stringent labeling and health-claim substantiation protocols favor established manufacturers with captive clinical trial infrastructure, consolidating market share among compliant producers.
- Urban millennial pet ownership clusters:Concentrated demand in metropolitan United States, Germany, and Japan markets drives premiumization toward limited-ingredient and novel-protein formulations with documented digestive benefits.
- Hydrolyzed protein processing:Advanced enzymatic hydrolysis technology reduces antigenic protein fragments, enabling broader feline tolerance profiles and expanding the addressable patient population for therapeutic diets.
Market Restraints
- Novel protein supply concentration:Dependence on New Zealand-sourced venison, kangaroo, and rabbit creates geographic supply vulnerability and input cost volatility during livestock disease outbreaks or export disruptions.
- Veterinary channel gatekeeping:Prescription diet classification under FDA enforcement restricts direct-to-consumer distribution, compressing margin capture for brands lacking established clinic relationships.
- Grain-free formulation substitution:Legume and pulse-based carbohydrate alternatives face scrutiny over dilated cardiomyopathy correlations, creating reputational risk and reformulation costs for affected product lines.
Strategic Opportunities
- Veterinary telehealth regulatory evolution:Relaxed state-level telemedicine prescribing rules in the United States enable remote diet authorization, expanding addressable markets beyond traditional clinic footprints.
- Microbiome-directed synbiotic convergence:Integration of strain-specific probiotics with targeted prebiotic fibers creates differentiated positioning in the fastest-growing ingredient segment.
- Direct-to-consumer subscription channels:Bypassing veterinary intermediaries through digital-first distribution models captures margin pools currently allocated to clinic markups.
Industry Challenges
- Feeding-trial talent scarcity:Veterinary nutritionists and clinical trial specialists command premium compensation, constraining mid-tier manufacturers from building compliant substantiation capabilities.
- Dual-label compliance complexity:Simultaneous satisfaction of AAFCO nutritional adequacy claims and EU FEDIAF guidelines extends product launch timelines and increases regulatory legal expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensitive Stomach Cat Food Market |
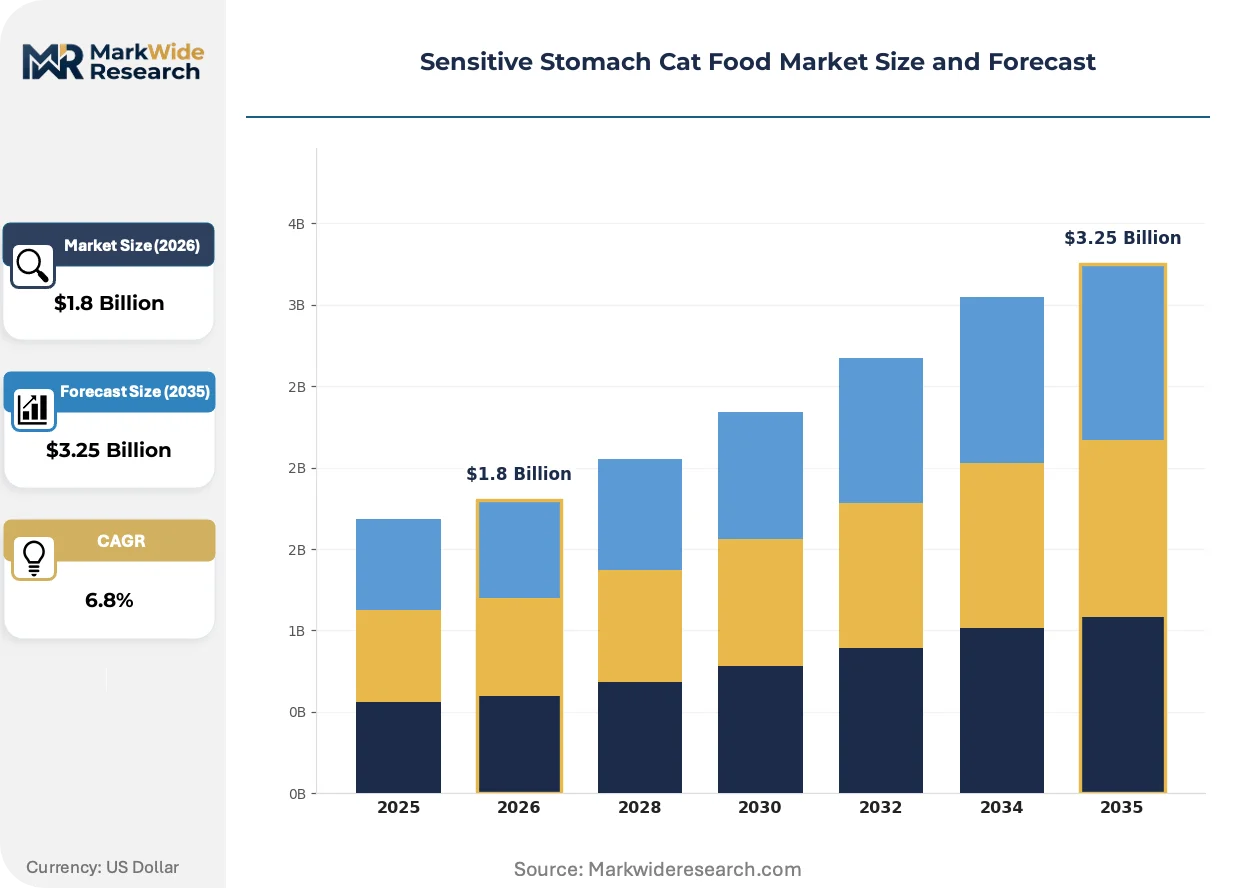
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Snacks, Probiotics Ingredient Type: Grain-Free, Limited Ingredient, Novel Proteins, Digestive Health Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Veterinarian Clinics Brand Type: Premium, Natural, Veterinary Diets, Mass Market |
| Companies Covered | Merrick, Ziwi Peak, Royal Canin, Fromm, Go! Solutions, Hill's Science Diet, Blue Buffalo, Orijen, Purina Pro Plan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensitive Stomach Cat Food Market Evolving Landscape
Digestive-health formulation science is pivoting from passive allergen avoidance toward active microbiome modulation, with documented strain efficacy replacing ingredient-list marketing.
Air-dried novel protein preservation is supplanting conventional extrusion and retort processing for premium positioning. Urban specialty retailers and direct-to-consumer subscribers in the United States and Japan are adopting these formats at accelerated velocity. This processing shift is compressing thermal degradation of bioactive compounds while enabling cleaner label claims that command shelf price premiums.
The EU's FEDIAF nutritional guideline updates and parallel national feed law implementations in Germany and France are tightening compositional tolerances for imported therapeutic diets. Manufacturers must reformulate mineral and vitamin premixes to satisfy divergent maximum and minimum thresholds across Atlantic regulatory regimes. Wet food and veterinary diet exporters to European markets face the steepest compliance burden and are consolidating formulation platforms to reduce SKU proliferation.
Subscription-based replenishment models are displacing periodic bulk purchasing at brick-and-mortar pet specialty retailers. Millennial cat owners in metropolitan United States markets prioritize convenience and portion control over per-unit cost optimization. This channel rotation is most visible in coastal urban clusters where same-day delivery infrastructure supports just-in-time inventory management for prescription diet continuity.
Sensitive Stomach Cat Food Market Segmentation
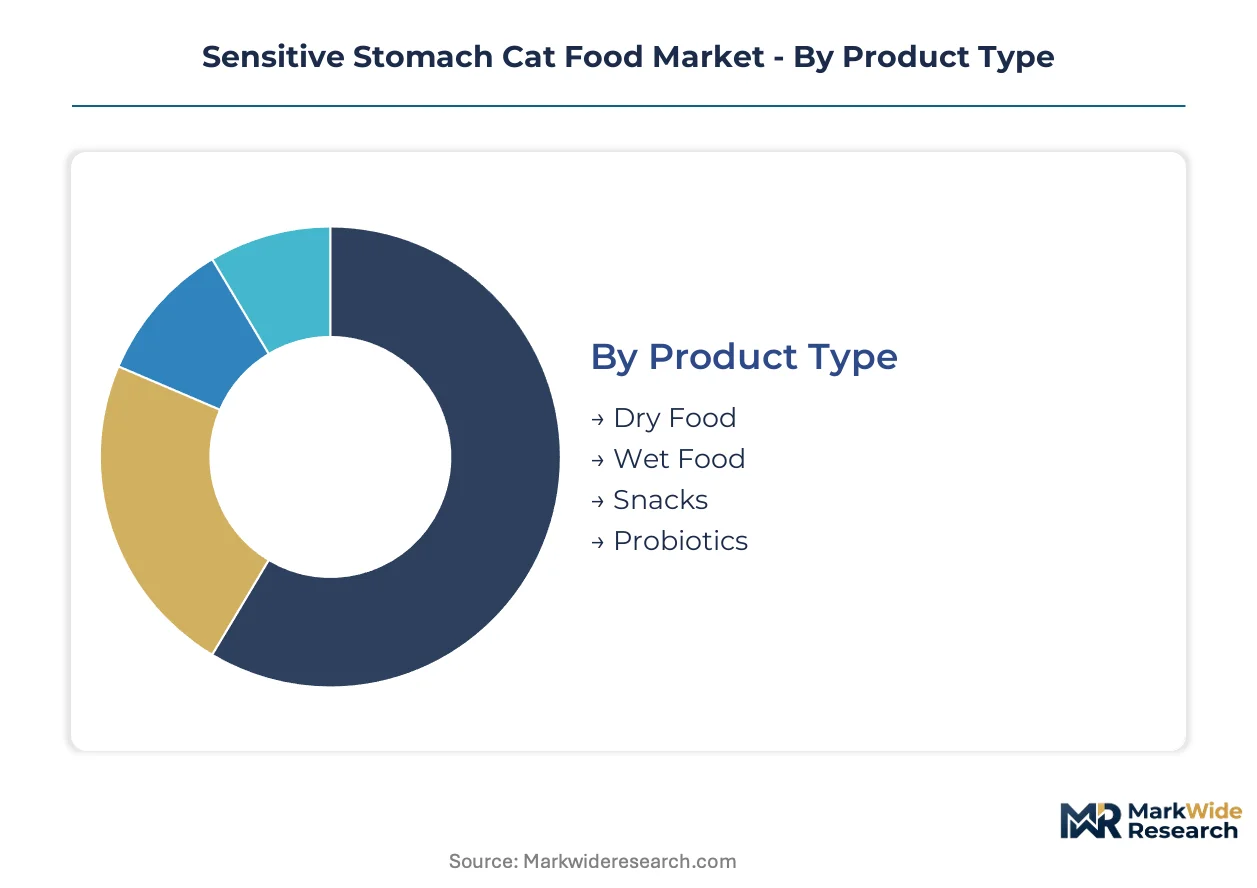
Segmentation in the sensitive stomach cat food market reveals how formulation science, channel control, and owner purchasing behavior create distinct profit pools. Manufacturers align R&D investment and distribution strategy to capture margin concentration in therapeutic and premium natural tiers.
Product Type:
Premium margin pools concentrate in moisture-rich formats that address renal health alongside digestive sensitivity.
- Wet Food:Higher palatability and moisture content support feline renal function while delivering superior digestibility for sensitive stomachs. Urban millennial owners in United States metropolitan clusters drive concentrated demand for veterinary-recommended wet formulations. The dominant share belongs to Wet Food, while Probiotics is closing the gap fastest.
- Dry Food:Extruded kibble with hydrolyzed proteins and single-source carbohydrates offers cost-efficient daily nutrition for multi-cat households. Shelf stability and bulk purchasing appeal to suburban owners managing chronic feline digestive conditions.
- Snacks:Limited-ingredient treats with novel protein bases serve as tolerance-testing vehicles during elimination diet protocols.
- Probiotics:Strain-specific microbial supplements represent the ingredient segment expanding most quickly, with documented CFU counts replacing vague digestive support claims.
Wet food commands the steepest price premiums, though probiotics are gaining share fastest through veterinary endorsement.
Ingredient Type:
Cost tier stratification separates allergen-avoidance formulations from active microbiome modulation products.
- Novel Proteins:Venison, kangaroo, and rabbit sourced from New Zealand provide low-antigen alternatives for cats with multiple protein intolerances. FDA feeding-trial substantiation requirements favor established manufacturers with captive clinical infrastructure. Grain-Free captures volume leadership, while Digestive Health is climbing the fastest.
- Digestive Health:Synbiotic formulations combining strain-specific probiotics with targeted prebiotic fibers create the fastest-expanding ingredient category. German and Japanese regulatory acceptance of documented microbial efficacy accelerates premium positioning.
- Limited Ingredient:Single-protein, single-carbohydrate recipes simplify elimination diet protocols for veterinary diagnosis of food allergies.
- Grain-Free:Legume and pulse-based alternatives face reformulation pressure amid dilated cardiomyopathy correlations in feline nutrition research.
Grain-free maintains volume leadership despite regulatory scrutiny, while digestive health formulations are gaining share fastest through clinical validation.
Distribution Channel:
Channel control determines margin capture, with professional gatekeeping creating the highest price realization.
- Veterinarian Clinics:Prescription diet classification under FDA enforcement restricts distribution to licensed professionals, sustaining premium pricing for therapeutic formulations. Captive clinic relationships defend margin pools against direct-to-consumer disruption. Veterinarian Clinics dominate value capture, while Online Retail is expanding most quickly.
- Online Retail:Subscription-based replenishment models displace periodic bulk purchasing among United States coastal urban clusters. Same-day delivery infrastructure supports just-in-time inventory management for prescription diet continuity.
- Pet Specialty Stores:Staff-trained consultative selling drives premium natural and limited-ingredient selections in metropolitan Japan markets.
- Supermarkets:Mass-market placement captures price-sensitive owners seeking basic sensitive stomach formulations without veterinary consultation.
Veterinary clinics retain the dominant value share, though online retail is climbing fastest through millennial subscription adoption.
Brand Type:
Customer type segmentation aligns pricing power with professional endorsement depth and ingredient sourcing transparency.
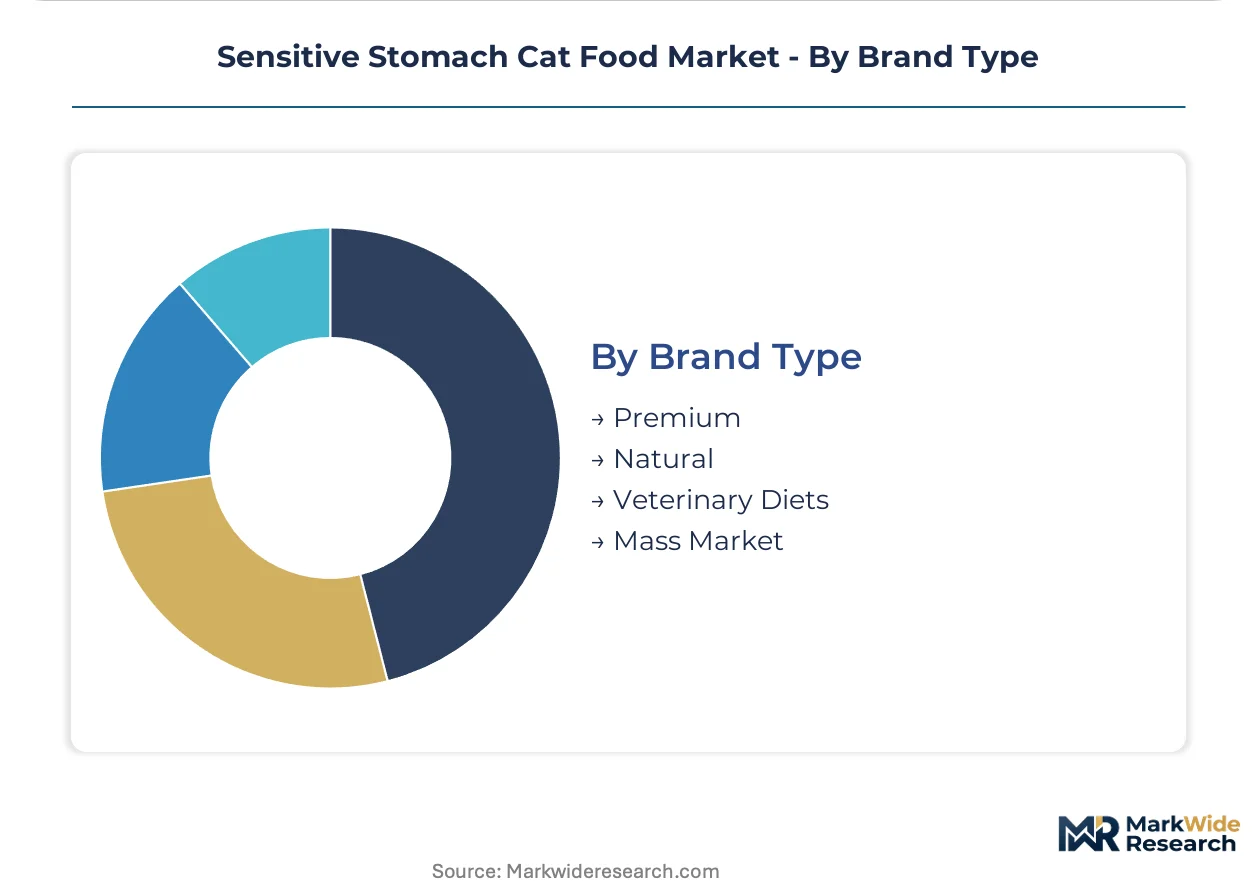
- Veterinary Diets:Clinically validated formulations with AAFCO feeding-trial substantiation command the highest price realization through restricted distribution. Hill's Science Diet and Royal Canin anchor this tier through captive veterinary channel relationships. Premium holds volume leadership, while Veterinary Diets are gaining share fastest.
- Premium:Air-dried novel protein products from New Zealand-sourced ingredients capture urban specialty retail and direct-to-consumer demand in United States and Japanese markets.
- Natural:Clean-label positioning with documented supply chain transparency appeals to ingredient-conscious millennial owners.
- Mass Market:Price-competitive formulations with basic digestive support claims serve budget-constrained multi-pet households.
Premium brands dominate volume, while veterinary diets are expanding most quickly through telehealth-enabled prescription access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine feeding-trial protocols and AAFCO nutritional adequacy standards accelerate product development timelines in the United States. Germany enforces parallel compositional requirements through EU FEDIAF guidelines and national feed law implementations. Japan's METI standards and urban pet ownership clusters in Tokyo and Osaka drive premium wet food demand.
United States
Millennial pet owners in coastal metropolitan clusters prioritize subscription-based replenishment and same-day delivery infrastructure. FDA oversight of prescription diet classification restricts direct-to-consumer distribution for therapeutic formulations. Greater Boston and Pacific Northwest urban centers concentrate demand for limited-ingredient and novel-protein formulations with documented digestive benefits.
Germany
FEDIAF nutritional guidelines and national feed law implementations impose strict compositional tolerances on imported therapeutic diets. German veterinary clinics enforce professional gatekeeping for prescription diet distribution, sustaining premium pricing structures. The North Rhine-Westphalia industrial corridor hosts formulation facilities serving domestic and EU export markets with consolidated SKU platforms.
Japan
Urban pet ownership density in Tokyo and Osaka metropolitan areas drives concentrated demand for moisture-rich wet food formats. METI standards and JIS regulatory frameworks govern pet food labeling and nutritional adequacy claims. Kanto region specialty retailers and direct-to-consumer channels adopt air-dried novel protein products at accelerated velocity.
United Kingdom
Post-Brexit divergence from EU FEDIAF guidelines creates dual-label compliance complexity for manufacturers serving both markets. London and Southeast England urban clusters exhibit strong subscription adoption among millennial cat owners. Midlands-based distribution centers manage cross-border regulatory documentation for continental European exports.
Canada
Health Canada and PMRA oversight of pet food safety aligns closely with FDA protocols, enabling streamlined cross-border product registration. Ontario and Quebec veterinary channels mirror United States prescription diet classification practices. Pacific Northwest supply chain linkages facilitate novel protein ingredient sourcing from British Columbia processing facilities.
Sensitive Stomach Cat Food Market Competitive Landscape
Player mix skews toward multinational pet nutrition conglomerates with captive veterinary channel relationships and specialized premium natural brands with transparent sourcing narratives. Market structure concentrates around three strategic archetypes: prescription diet manufacturers with AAFCO feeding-trial infrastructure, air-dried novel protein specialists with geographic ingredient advantages, and mass-market brands with retail distribution scale. Dominant competitive moves include portfolio diversification into microbiome-directed synbiotic formulations and strategic partnerships with veterinary telehealth platforms to bypass traditional clinic intermediaries.
Within the prescription diet tier, Hill's Science Diet and Royal Canin exemplify manufacturers with established veterinary channel anchoring and clinical validation infrastructure. Ziwi Peak occupies a position representing air-dried novel protein specialists leveraging New Zealand-sourced ingredient provenance for premium positioning. These three companies collectively illustrate the competitive segmentation between clinically validated therapeutic formulations and transparency-driven natural positioning.
| Leading Market Players |
|---|
| Merrick |
| Ziwi Peak |
| Royal Canin |
| Fromm |
| Go! Solutions |
| Hill's Science Diet |
| Blue Buffalo |
| Orijen |
| Purina Pro Plan |
| Others |
Value Network & Pricing Analysis
Air-dried novel protein preservation supplanting conventional extrusion and retort processing simultaneously relocates production geography toward New Zealand ingredient hubs and compresses thermal degradation costs that previously inflated premium tier pricing. This substitution dynamic concentrates margin capture among manufacturers with captive sourcing relationships while elevating input cost volatility for brands dependent on spot-market novel protein procurement.
Pricing Analysis
Cost-plus contracts indexed to New Zealand venison and kangaroo livestock auction prices dominate ingredient procurement for premium formulations. Three-tier pricing structure across premium, standard, and economy levels separates AAFCO-substantiated veterinary diets from limited-ingredient natural brands and mass-market digestive support lines. Pricing pressure stems from veterinary channel gatekeeping that restricts direct-to-consumer distribution for therapeutic classifications. Mass-market buyers exhibit highest price sensitivity, while millennial urban subscribers demonstrate lowest elasticity for documented microbiome efficacy.
Supply Chain Analysis
New Zealand anchors novel protein supply with venison, kangaroo, and rabbit processing infrastructure serving premium export markets. The supply chain draws from Australian rendering facilities for hydrolyzed protein concentrates and Thai extrusion plants for cost-optimized kibble manufacturing. Single-source vulnerability in New Zealand livestock disease exposure creates geographic concentration risk. Distribution runs through veterinary clinic intermediaries for prescription tiers and direct-to-consumer platforms for premium natural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary telehealth regulatory relaxation constitutes a technological-regulatory inflection that will disrupt traditional clinic-mediated distribution models and accelerate market expansion beyond conventional gatekeeping structures.
For Market Incumbents: Secure captive veterinary channel relationships through exclusive formulary agreements before telehealth platforms erode clinic foot traffic. Invest in backward integration into New Zealand novel protein rendering capacity to defend margin position against input cost volatility from livestock disease outbreaks.
For New Entrants and Emerging Players: Subscription-based replenishment service gaps in coastal United States metropolitan clusters offer white-space entry points where incumbents under-serve millennial convenience preferences. Target direct-to-consumer microbiome supplement segments with strain-specific CFU documentation as the most penetrable application tier.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors AAFCO feeding-trial infrastructure owners over marketing-dependent natural brands. Acquisition targets with captive clinical validation capabilities and established veterinary formulary presence demonstrate superior long-term viability. Monitor state-level telemedicine prescribing rule evolution as the primary inflection signal for channel disruption timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Directed Synbiotic Development | Strain-specific probiotic-prebiotic convergence captures fastest-growing ingredient segment through veterinary endorsement. |
| Veterinary Telehealth Platform Partnership | Remote prescription authorization expands addressable markets beyond traditional clinic footprint constraints. |
| Air-Dried Novel Protein Capacity Expansion | New Zealand-sourced ingredient provenance commands shelf price premiums in urban specialty retail channels. |
| AAFCO Feeding-Trial Infrastructure Investment | Clinical validation capabilities defend market access against FDA substantiation protocol elevation. |
| Direct-to-Consumer Subscription Launch | Digital-first distribution captures margin pools currently allocated to veterinary clinic markups. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary nutritionists, pet food formulation scientists, clinic procurement managers, and specialty retail category buyers and refined through secondary validation against FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, EU FEDIAF nutritional guidelines, and import customs records. Bottom-up segment sizing triangulated with top-down macroeconomic demand modeling across the analysis window.
Variance decomposition separated volume drivers from pricing dynamics across product type, ingredient category, distribution channel, and brand tier segmentation dimensions. CAGRs were derived from fitted growth curves incorporating urban pet ownership density projections, regulatory telehealth evolution scenarios, and novel protein supply elasticity assumptions.
Forecasts assume regulatory continuity in FDA prescription diet classification and EU FEDIAF guideline implementations; material policy shifts affecting veterinary channel access or compositional tolerance thresholds would require re-modeling. Recalibration cycles align with material shifts in telehealth adoption rates and novel protein supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Omega-3 Pet Supplement Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Dog Treats Market