
 Australia Organic Food Market | 2026-2036
Australia Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Organic Food Market Insights
A capital-intensity divergence between certified farm operations and uncertified conventional suppliers is unwinding competitive dynamics across Australian organic supply chains. Woolworths Group leverages its private-label organic range and direct grower contracts to control shelf-space allocation in metropolitan stores. Coles Group sustains price competitiveness through streamlined procurement partnerships with mid-scale Victorian and Queensland farms. Australian Organic Food Co. anchors its position in premium branded segments with vertically controlled processing facilities.
Australia organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, meeting certified organic standards that mandate soil health management and biodiversity preservation across minimum three-year conversion periods. The primary commercial purpose centers on delivering verified chemical-free nutrition to health-conscious consumers and institutional foodservice buyers seeking traceable supply chains. Fruits and vegetables command the largest product category share due to established consumer familiarity and shorter conversion cycles for domestic growers, while online retail represents the fastest-expanding distribution channel as direct-to-consumer platforms reduce intermediary markups and expand regional access beyond supermarket catchments.
The Australian Certified Organic standard, administered by Australian Organic Limited, governs labelling legitimacy and farm-to-shelf traceability, with non-compliance exposing operators to penalties under Australian Competition and Consumer Commission enforcement. Food Standards Australia New Zealand maintains the Australia New Zealand Food Standards Code, which delineates organic claim permissibility and restricts certain processing aids in certified product manufacturing. Stakeholders must monitor evolving certification harmonisation pressures between domestic standards and imported USDA Organic equivalency arrangements that could reshape import-competitive positioning for local processors.
Market Dynamics
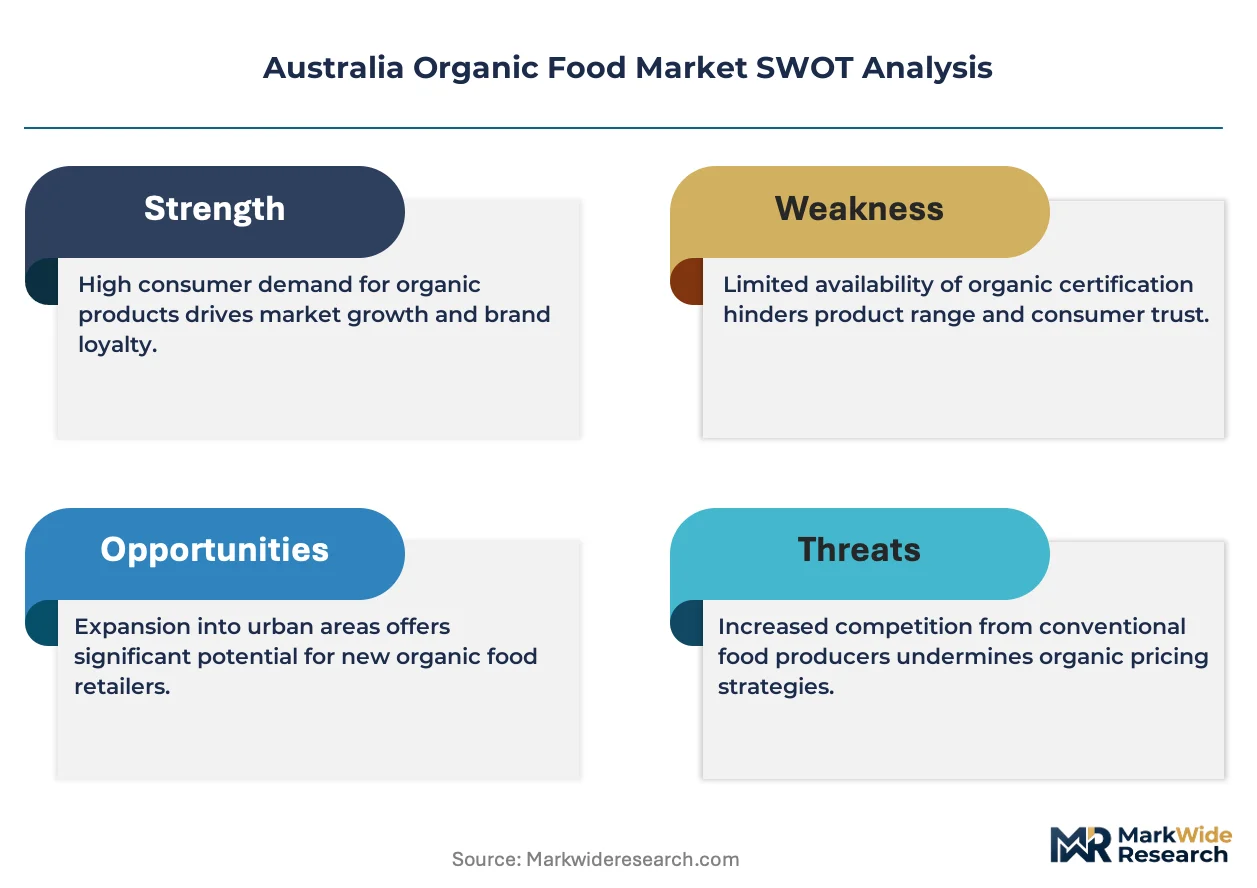
Certification cost inflation under the Australian Certified Organic standard is fragmenting grower economics and forcing consolidation among mid-scale operations unable to absorb three-year conversion timelines and annual audit expenses.
Growth Catalysts
- New South Wales and Victoria urban density:Metropolitan retail infrastructure concentration creates captive demand clusters for premium organic produce, with supermarket private-label expansion accelerating shelf-space allocation for verified suppliers.
- Competition and Consumer Act labelling requirements:Tighter enforcement by the Australian Competition and Consumer Commission is squeezing uncertified claimants from shelf positioning, redirecting volume toward legitimate certified operators.
- Direct-to-consumer platform proliferation:Online retail channel expansion collapses intermediary markups and extends regional access beyond traditional supermarket catchments into under-served postcodes.
Market Restraints
- Three-year organic conversion timelines:Australian Certified Organic mandates lock land out of conventional revenue streams during transition, straining working capital for wheat and dairy operations with thin margin buffers.
- Imported USDA Organic equivalency pressure:Harmonisation negotiations with United States standards expose domestic processors to price competition from California and Latin American suppliers with scale advantages.
- Synthetic input substitution risk:Conventional produce with residue levels below detectable thresholds captures price-sensitive household segments unconvinced of measurable nutritional differentiation.
Strategic Opportunities
- Queensland and South Australia regional penetration:Sparse premium retail infrastructure in these states creates first-mover whitespace for direct-to-consumer subscription models and farmers market network expansion.
- Foodservice institutional procurement:Traceability requirements from hospital and aged care contract caterers open bulk volume channels with multi-year offtake agreements and reduced price volatility.
- Soil carbon credit stacking:Emerging integration between organic certification and Emissions Reduction Fund methodologies allows growers to monetise biodiversity co-benefits alongside produce revenue.
Industry Challenges
- Certified organic auditor scarcity:Australian Organic Limited's limited pool of accredited inspectors creates inspection backlog delays that extend time-to-market for newly converted operations.
- Legacy supply chain traceability gaps:Mid-scale aggregators lack batch-level digital tracking infrastructure required by export customers and domestic supermarket compliance portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Organic Food Market |
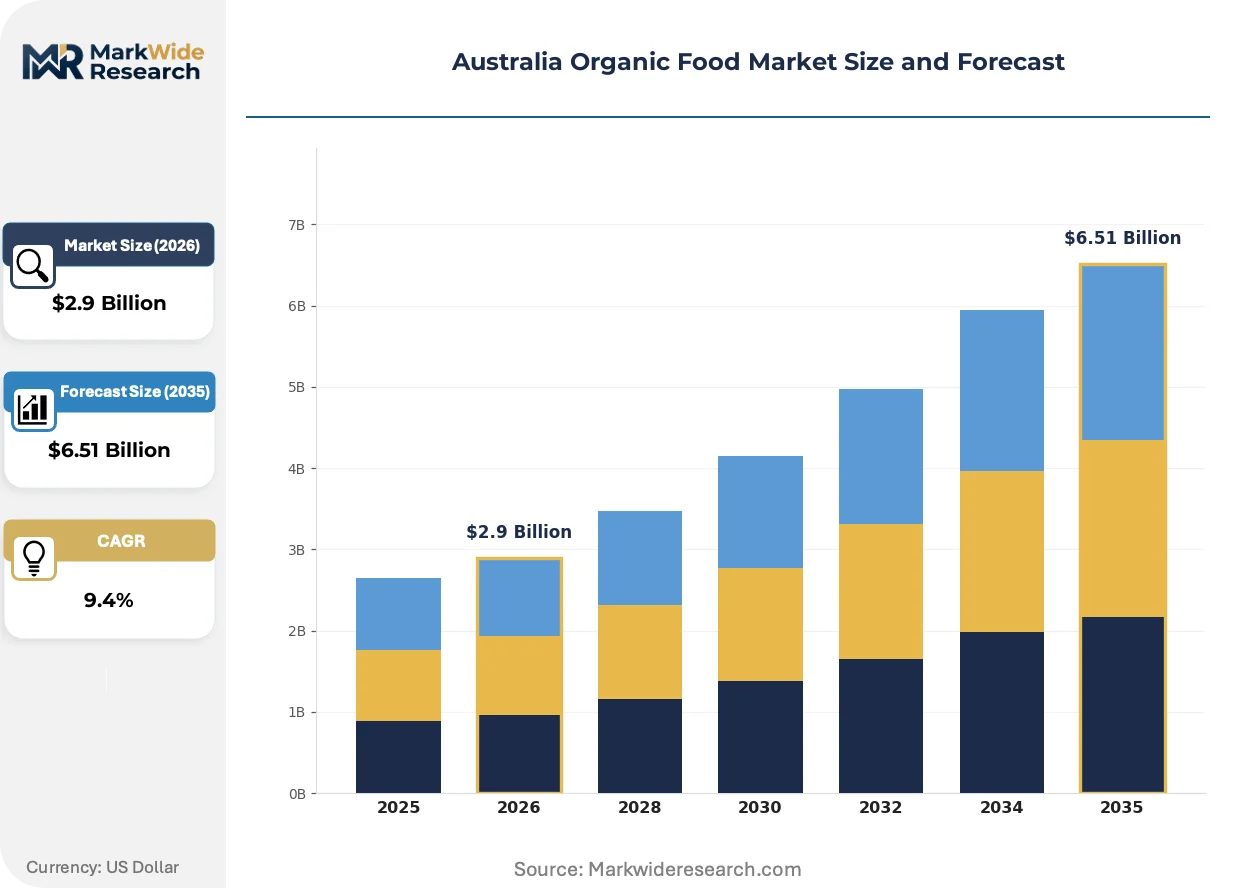
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Fruits, Vegetables, Dairy, Grains Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Health Food Stores End User: Households, Restaurants, Cafés, Food Manufacturers Certification Type: Australian Certified Organic, USDA Organic, Bio-Dynamic, Others |
| Companies Covered | Australian Organic Food Co., Aloe Vera Australia Pty Ltd., Woolworths Group, Bubs Australia Ltd, Wild One Beverages, Coles Group, Ozganics Australia Pty Ltd., Oliver's Real Food Ltd, Trumps Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Organic Food Market Trends and Innovations
Digital traceability infrastructure and regenerative agriculture integration are reconfiguring how Australian organic growers demonstrate compliance and capture premium positioning beyond baseline certification.
Blockchain-enabled provenance tracking is bifurcating the supplier base into technology-capable operators and legacy aggregators. Woolworths Group and Coles Group are mandating scan-accessible batch records for private-label organic lines. This technology compression is forcing mid-scale Victorian and Queensland farms into costly ERP upgrades or exit from supermarket supply tiers.
Food Standards Australia New Zealand is tightening processing aid restrictions under the Australia New Zealand Food Standards Code. Manufacturers face reformulation costs for organic packaged goods previously reliant on synthetic preservatives. The chilled ready-meal segment is absorbing the steepest compliance burden as shelf-life compression demands alternative natural preservation protocols.
Household purchasing is rotating toward subscription-based produce box models that displace intermittent supermarket trips. Victorian and New South Wales urban consumers are consolidating weekly vegetable procurement through direct farm relationships. This channel migration is most pronounced in Melbourne and Sydney inner-ring postcodes with established farmers market cultures and high digital payment penetration.
Australia Organic Food Market Segmentation
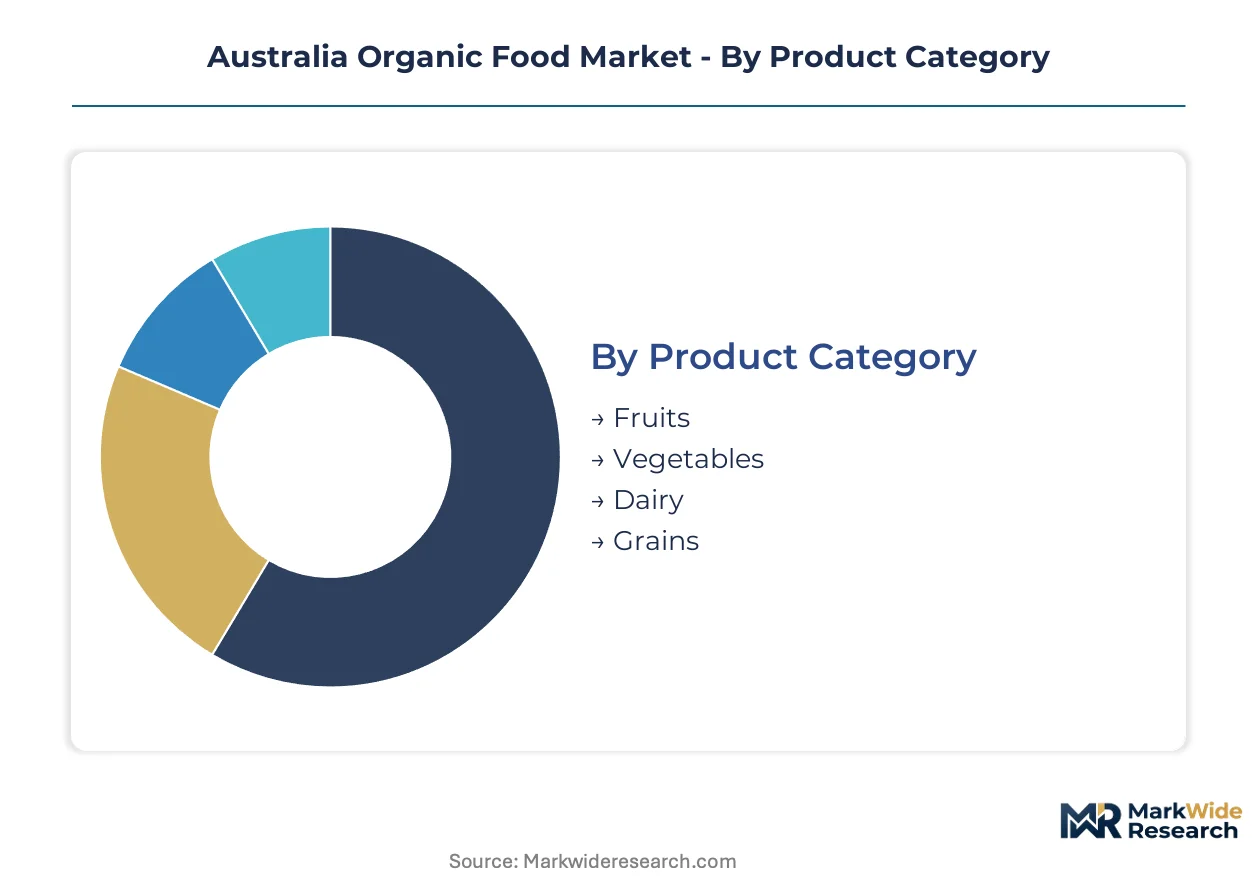
Australian organic food segmentation reveals how certification tiers and channel access determine margin capture. Product category concentration shapes farm conversion priorities, while distribution channel evolution is redrawing competitive boundaries between incumbent retailers and direct-to-consumer insurgents.
Product Category:
Channel-mix patterns vary sharply across fresh versus processed segments, with perishability dictating supermarket dependency versus online viability.
- Fruits:Short conversion cycles and established consumer familiarity drive volume leadership. New South Wales and Victoria metropolitan supermarkets absorb the bulk of national supply, with Woolworths and Coles private-label programs capturing premium shelf positioning through direct grower contracts.
- Vegetables:Leafy greens and root vegetables face compressed margins due to cold-chain intensity. Melbourne and Sydney inner-ring subscription box services are displacing intermittent supermarket trips for time-constrained households, collapsing intermediary markups by eliminating distribution layers.
- Dairy:Extended three-year conversion timelines and livestock herd management costs restrict supplier entry. Victorian pasture-based operations dominate certified milk and cheese supply to foodservice contract caterers.
- Grains:Wheat and cereal operations struggle with working capital strain during organic transition periods. Queensland dryland growers increasingly supply flour mills and bakery manufacturers seeking traceable inputs.
Fruits dominate installed base. Vegetables is where expansion concentrates.
Distribution Channel:
Margin compression intensity separates high-volume supermarket supply from relationship-based direct channels with pricing autonomy.
- Supermarkets:Woolworths and Coles control metropolitan shelf-space allocation through private-label organic ranges and exclusive grower contracts. Compliance portals mandate batch-level digital traceability that forces mid-scale farms into costly ERP upgrades.
- Online Retail:Direct-to-consumer platforms collapse intermediary markups and extend regional access beyond traditional catchments. Victorian and New South Wales urban consumers consolidate weekly procurement through subscription produce boxes.
- Farmers' Markets:Face-to-face transactions sustain price premiums through provenance storytelling and relationship trust. Melbourne and Sydney inner-ring postcodes with established market cultures show highest penetration.
- Health Food Stores:Specialty retail channels capture supplement-adjacent organic demand with higher margin tolerance. Bio-dynamic and niche certification types find shelf access unavailable in mainstream supermarkets.
Supermarkets dominate installed base. Online retail is climbing the fastest.
End User:
Volume scale and traceability requirements create divergent supplier economics across household and institutional segments.
- Households:Australian households represent the fastest-expanding end-user segment as purchasing shifts toward verified organic produce. New South Wales and Victoria urban density clusters drive metropolitan retail infrastructure concentration.
- Restaurants:Farm-to-table positioning demands batch-level documentation that mid-scale aggregators struggle to supply. Sydney and Melbourne fine-dining establishments source directly through grower networks.
- Cafés:Smaller operational scale limits procurement flexibility, concentrating demand on distributors with consolidated organic lines. Melbourne's specialty coffee culture sustains premium milk and produce sourcing.
- Food Manufacturers:Multi-year offtake agreements from contract caterers open bulk volume channels with reduced price volatility. Hospital and aged care traceability requirements favor certified suppliers with digital infrastructure.
Households dominate installed base. Food manufacturers is where expansion concentrates.
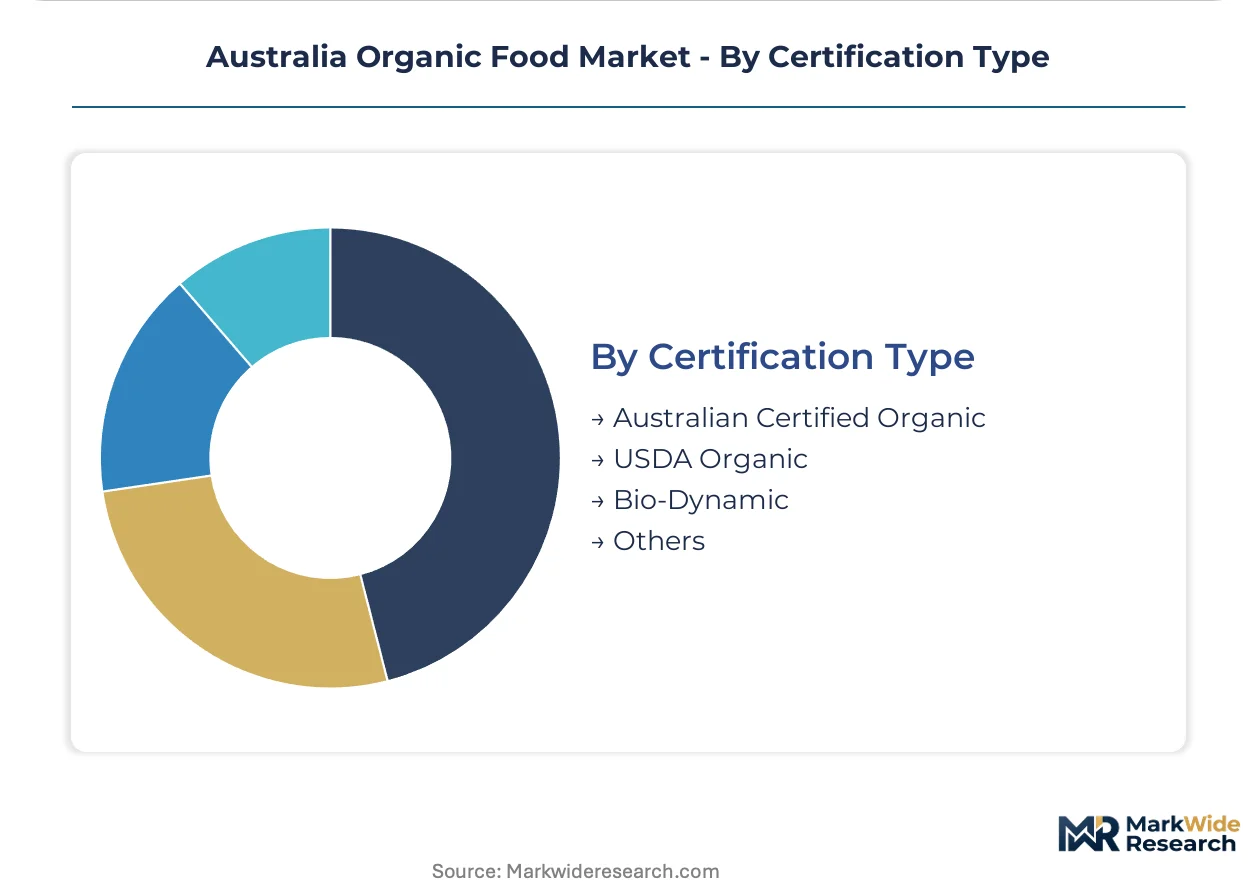
Certification Type:
Compliance cost tiers and market access rights stratify grower economics across domestic and equivalency arrangements.
- Australian Certified Organic:Administered by Australian Organic Limited, this standard governs labelling legitimacy and farm-to-shelf traceability. Non-compliance exposes operators to Australian Competition and Consumer Commission penalties.
- USDA Organic:Harmonisation negotiations with United States standards expose domestic processors to price competition from California and Latin American suppliers with scale advantages.
- Bio-Dynamic:Demeter certification commands niche premiums through enhanced soil health protocols. Health food stores provide primary shelf access unavailable to conventional organic suppliers.
- Others:Nascent certification schemes and import equivalency arrangements create regulatory fragmentation. Stakeholders monitor evolving harmonisation pressures that could reshape import-competitive positioning.
Australian Certified Organic dominates installed base. Bio-Dynamic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Australian states, with Queensland and South Australia households showing higher elasticity to organic premiums while New South Wales and Victoria consumers absorb markups with lower volume attrition.
New South Wales
Sydney's inner-ring postcodes drive metropolitan demand density for certified produce, with Woolworths and Coles private-label expansion capturing shelf-space allocation. The Australian Competition and Consumer Commission enforces tighter labelling requirements under the Competition and Consumer Act, squeezing uncertified claimants from retail positioning. The Sydney-Melbourne corridor concentrates foodservice procurement for hospital and aged care contract caterers demanding traceable supply chains.
Victoria
Melbourne's established farmers market culture sustains direct-to-consumer subscription box penetration, with households consolidating weekly vegetable procurement through farm relationships. Food Standards Australia New Zealand maintains processing aid restrictions under the Australia New Zealand Food Standards Code, forcing reformulation costs for organic packaged goods manufacturers. The state's pasture-based dairy operations dominate certified milk and cheese supply to institutional buyers.
Queensland
Sparse premium retail infrastructure creates first-mover whitespace for direct-to-consumer platforms extending regional access beyond supermarket catchments. Australian Organic Limited administers certification standards with limited accredited inspector pools creating backlog delays for newly converted operations. Brisbane and Gold Coast urban clusters show nascent demand concentration as digital payment penetration enables subscription model adoption.
South Australia
Adelaide's lower urban density limits metropolitan retail infrastructure concentration, pushing demand toward online retail channels that collapse intermediary markups. The Emissions Reduction Fund methodologies enable soil carbon credit stacking for growers monetising biodiversity co-benefits alongside produce revenue. The state's dryland grain operations increasingly supply flour mills seeking traceable organic inputs.
Western Australia
Perth's geographic isolation from eastern supply chains elevates transport costs for certified produce, compressing margins for mid-scale aggregators lacking batch-level digital tracking infrastructure. The Australian Certified Organic standard's three-year conversion timelines strain working capital for wheat operations with thin margin buffers. Local farmers market networks sustain price premiums through provenance storytelling in face-to-face transactions.
Australia Organic Food Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Australian organic food supply chains. Woolworths Group and Coles Group control metropolitan shelf-space allocation through private-label organic ranges and exclusive grower contracts, while mid-scale Victorian and Queensland farms occupy the specialist tier with streamlined procurement partnerships. Three archetypes dominate: vertically integrated retailers with captive processing facilities, mid-scale certified growers with direct supermarket supply relationships, and direct-to-consumer platforms with subscription-based produce box models. Competitive moves concentrate on ERP upgrades for batch-level digital traceability compliance and geographic expansion into under-served regional postcodes.
Among retailer-integrated operators, Woolworths Group and Coles Group exemplify the scale-driven archetype with private-label organic ranges and controlled shelf-space allocation. Australian Organic Food Co. occupies a position within the premium branded segment, representing vertically controlled processing capabilities that anchor market positioning beyond baseline certification compliance.
| Leading Market Players |
|---|
| Australian Organic Food Co. |
| Aloe Vera Australia Pty Ltd. |
| Woolworths Group |
| Bubs Australia Ltd |
| Wild One Beverages |
| Coles Group |
| Ozganics Australia Pty Ltd. |
| Oliver's Real Food Ltd |
| Trumps Pty Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Victorian dairy operations and foodservice contract caterers lock in supply access and price visibility across three-year conversion timelines, insulating certified growers from spot-market volatility while exposing conventional suppliers to Australian Competition and Consumer Commission enforcement risk.
Pricing Analysis
After-sales service revenue from subscription produce box renewals drives lifetime value for direct-to-consumer platforms. Pricing stratifies across Australian Certified Organic premium tiers, Bio-Dynamic niche positioning, and uncertified conventional substitutes. Cost compression in leafy vegetable categories intensifies as cold-chain logistics absorb margin. Price-sensitive Queensland and South Australia households attrition at organic premiums above conventional benchmarks, while New South Wales and Victoria urban consumers absorb markups with lower volume loss.
Supply Chain Analysis
New South Wales and Victoria anchor metropolitan retail infrastructure concentration, with Queensland and South Australia supplying grains and sparse premium produce. Australian organic food draws from pasture-based livestock inputs, dryland cereal cultivation, and imported USDA Organic equivalency arrangements. Single-source vulnerability concentrates in Australian Organic Limited's limited accredited inspector pool. Distribution runs through Woolworths and Coles private-label procurement portals, direct-to-consumer subscription platforms, and farmers market networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian organic food market fragmentation creates entry niches as household purchasing rotates toward verified traceability and subscription-based procurement models displace intermittent supermarket trips.
For Market Incumbents: Compound shelf-space control through exclusive grower contracts mandating batch-level digital traceability compliance, forcing mid-scale Victorian and Queensland farms into costly ERP upgrades or exit from supermarket supply tiers. Deepen backward integration into captive processing facilities to anchor premium branded positioning beyond baseline certification. Defend against direct-to-consumer insurgents by replicating subscription box convenience through private-label online portals. For New Entrants and Emerging Players: Anchor in Queensland and South Australia regional whitespace where sparse premium retail infrastructure creates first-mover advantage for subscription models extending beyond supermarket catchments. Target foodservice institutional procurement with multi-year offtake agreements from hospital and aged care contract caterers demanding traceable supply chains. Deploy soil carbon credit stacking as differentiated value proposition under Emissions Reduction Fund methodologies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically controlled processing capabilities with Australian Certified Organic certification and existing supermarket compliance portal access. Long-term viability hinges on digital traceability infrastructure and geographic diversification into under-served regional postcodes. Acquisition target archetype: mid-scale certified growers with direct foodservice relationships and batch-level tracking capability. The signal to watch is harmonisation negotiation outcomes between Australian Certified Organic and USDA Organic equivalency arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription produce boxes collapse intermediary markups and extend regional access beyond Woolworths and Coles catchments. |
| Soil Carbon Credit Stacking | Emissions Reduction Fund integration allows growers to monetise biodiversity co-benefits alongside Australian Certified Organic produce revenue. |
| Batch-Level Digital Traceability Upgrade | ERP infrastructure satisfies Woolworths and Coles compliance portal mandates for private-label organic line supply. |
| Foodservice Institutional Procurement Partnership | Multi-year offtake agreements with hospital and aged care contract caterers open bulk volume channels with reduced price volatility. |
| Bio-Dynamic Certification Investment | Demeter standard commands niche premiums through enhanced soil health protocols with health food store shelf access unavailable to conventional organic suppliers. |
Research Methodology
A standing panel of Australian Certified Organic certification officers, Woolworths and Coles category buyers, foodservice procurement managers at hospital contract caterers, and Victorian dairy farm operators provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from Australian Organic Limited audit records, Australian Competition and Consumer Commission enforcement filings, Food Standards Australia New Zealand processing aid restriction updates, and Emissions Reduction Fund methodology documentation. Bottom-up farm-level production estimates and top-down retail channel revenue analysis underwent triangulation.
Consistency checks validated volume and value outputs against Australian Bureau of Agricultural and Resource Economics trade data and supermarket private-label expansion disclosures across the projection horizon. Segmentation modeling captured product category, distribution channel, end user, and certification type dimensions plus soil carbon credit eligibility tier as industry-specific variable. CAGRs derived from trend extrapolation of conversion timeline completions, inspector pool expansion rates, and subscription platform adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable Australian Certified Organic audit capacity and continued USDA Organic equivalency recognition; material deviation would warrant model refresh. Specific risk factors include certification harmonisation negotiation outcomes, synthetic input substitution capture of price-sensitive segments, and inspector backlog delays extending time-to-market for newly converted operations. Recalibration cycles align with material shifts in Competition and Consumer Act enforcement intensity and direct-to-consumer platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Soda Market