
 Middle East and Africa Prepaid Card Market | 2026-2036
Middle East and Africa Prepaid Card Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Prepaid Card Market Foresight
The UAE's central bank mandate for wage protection system compliance is consolidating prepaid payroll card issuance across Emirates-based employers. First Abu Dhabi Bank leverages its government banking relationships to sustain dominance in corporate salary disbursement products. Capitec Bank anchors South Africa's consumer segment through low-cost digital onboarding and branch-light distribution. Mastercard competes aggressively on virtual card APIs for e-commerce platforms serving the region's young demographics.
A prepaid card is a payment instrument loaded with funds prior to transaction execution, typically bearing a 16-digit PAN, EMV chip, and either single-load or reloadable functionality, designed to enable electronic purchasing without linked credit or traditional deposit account dependency. Its primary commercial purpose spans payroll distribution, gift disbursement, travel expense management, and financial inclusion for unbanked populations. Reloadable cards occupy the structural core of issuer portfolios due to recurring fund flows and activation longevity, while virtual cards represent the fastest-expanding segment as mobile-first banking penetration deepens across the region. Corporate gifting applications concentrate margin pools through bulk procurement contracts and white-label customization services.
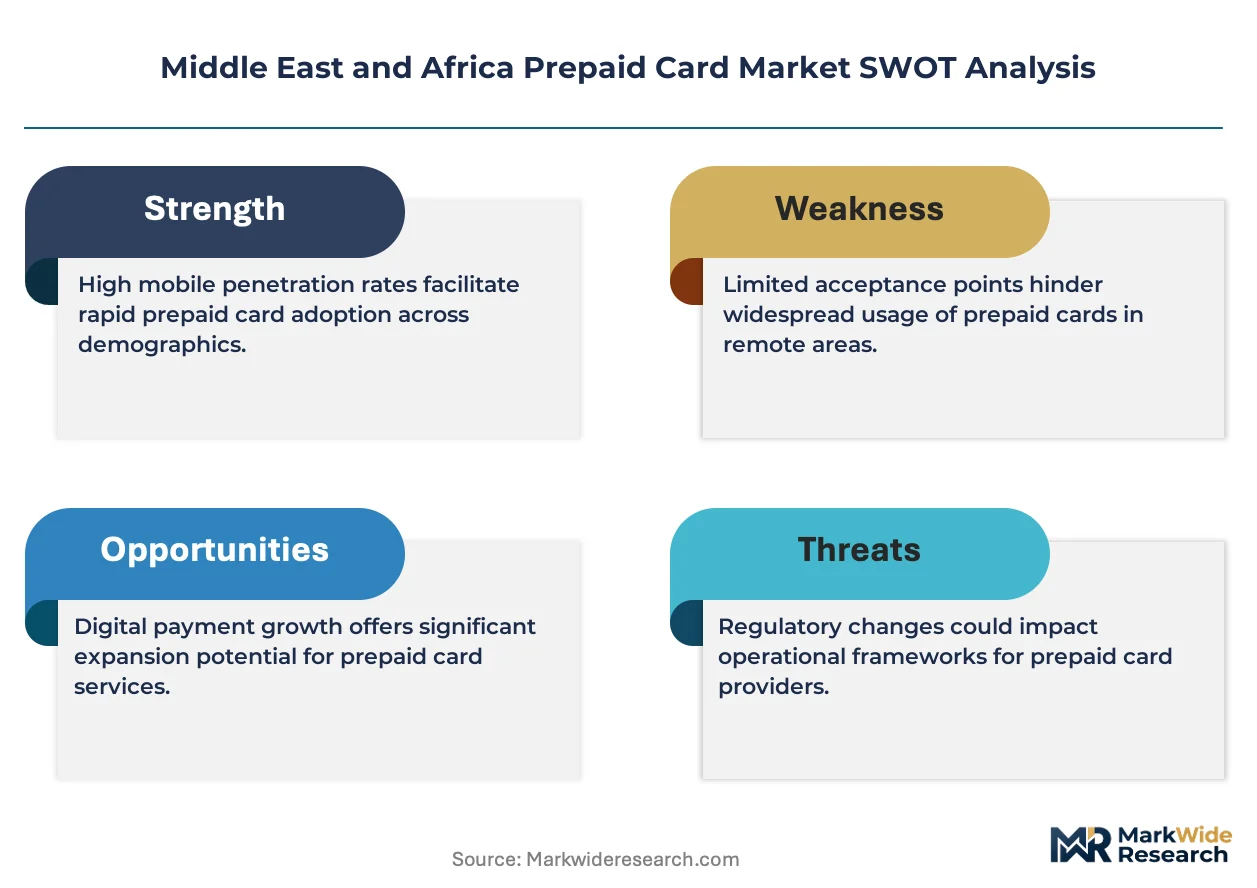
South Africa's Financial Sector Conduct Authority, the UAE Central Bank, and Saudi Arabia's Saudi Central Bank collectively shape product standards through e-money licensing frameworks, consumer protection mandates, and anti-money laundering transaction monitoring requirements. These regulators enforce KYC tiering that directly determines card load limits, interoperability obligations, and cross-border remittance accessibility. Stakeholders must monitor evolving open-banking directives and real-time payment infrastructure rollouts that could either disintermediate prepaid architectures or embed cards more deeply as wallet funding rails.
Market Dynamics
The UAE Central Bank's wage protection system mandate is compressing payroll disbursement into prepaid rails, forcing employers across Emirates-based construction, hospitality, and domestic labor sectors to abandon cash salary distribution.
Growth Catalysts
- GCC Payroll Digitization:Saudi Arabia's Nitaqat program and Qatar's labor law reforms mandate electronic wage payments, accelerating corporate prepaid card issuance across construction and services sectors.
- South Africa FSCA Licensing:The Financial Sector Conduct Authority's streamlined e-money licensing framework reduces capital requirements for fintech entrants, expanding issuer competition beyond incumbent banks.
- Mobile Wallet Convergence:USSD-to-wallet interoperability in Nigeria and Kenya embeds prepaid cards as funding rails for unbanked populations lacking traditional deposit access.
Market Restraints
- FX Volatility Exposure:Naira and Rand depreciation against dollar-denominated card scheme fees compresses issuer margins in Nigeria and South Africa.
- KYC Infrastructure Gaps:Biometric identity verification shortages in rural Kenya and Ethiopia extend customer onboarding timelines beyond mobile-native competitor benchmarks.
- Interoperability Fragmentation:Non-standardized local switch protocols between Ghana, Nigeria, and Kenya limit cross-border prepaid utility for regional remittance corridors.
Strategic Opportunities
- Ethiopia Financial Inclusion:The unbanked population exceeding 60 million and state bank dominance create white space for mobile-first prepaid distribution through telecom partnerships.
- Virtual Card APIs:E-commerce platforms serving MENA's under-30 demographic demand instant issuance for single-use transaction security, bypassing physical card logistics.
- Saudi Vision 2030:The National Transformation Program's cashless society targets embed prepaid products into government disbursement, transit, and tourism payment flows.
Industry Challenges
- AML Compliance Talent Scarcity:Transaction monitoring system implementation requires scarce data science and regulatory technology expertise across Johannesburg, Lagos, and Dubai financial centers.
- Legacy Core Integration:Bank issuers in Egypt and Morocco face multi-year migration timelines to connect prepaid card management systems with 1980s-era mainframe deposit infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Prepaid Card Market |
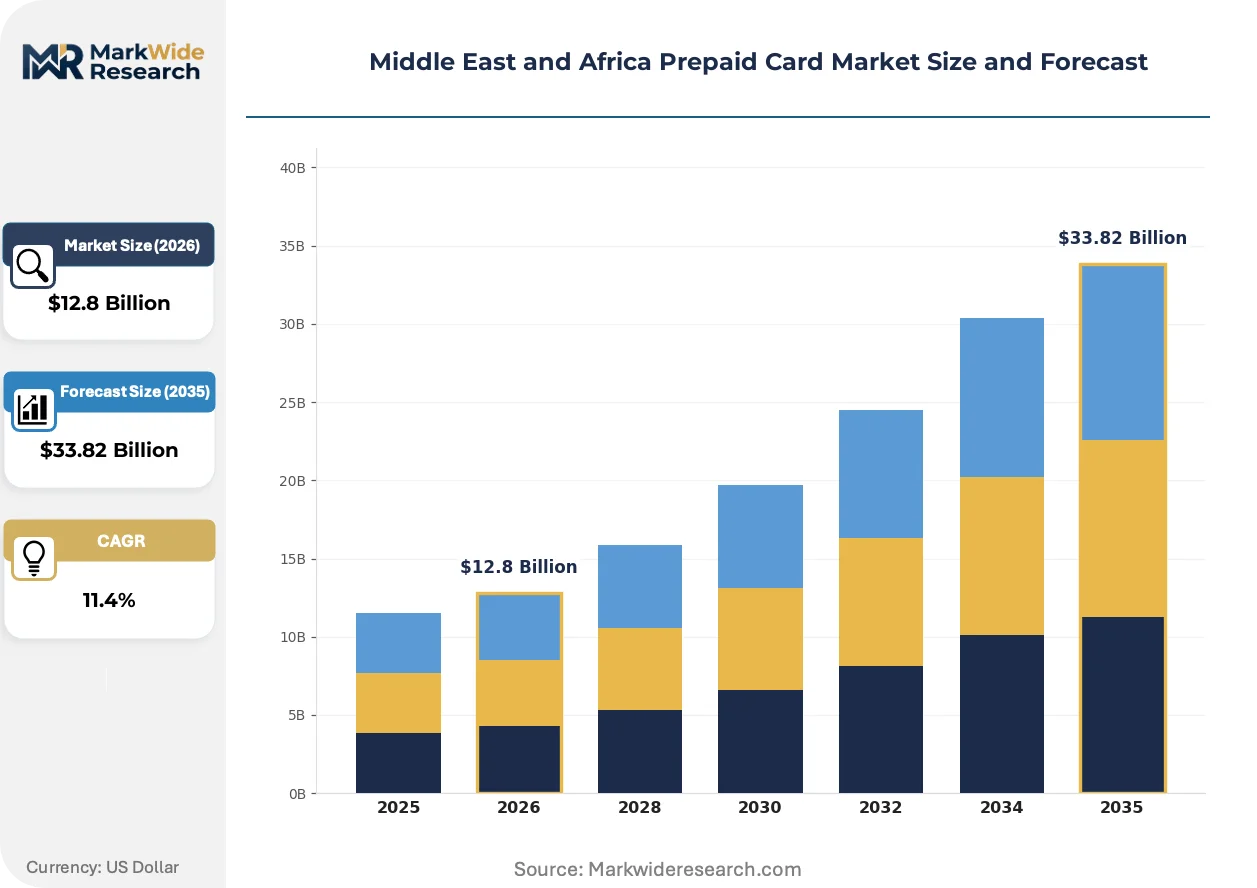
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Virtual Cards, Gift Cards, Travel Cards, Reloadable Cards Application: Retail Payments, Online Shopping, Travel Expenses, Corporate Gifting End User: Consumers, Corporates, Tourists, Students Distribution Channel: Banks, Retail Outlets, Online Platforms, Mobile Apps |
| Companies Covered | Access Bank Plc, Capitec Bank, Visa, Next Plc, Equity Bank, American Express, First Abu Dhabi Bank, Mastercard, Alawwal Bank, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Prepaid Card Market Shifts & Advancements
Prepaid architecture is bifurcating between physical reloadable products anchoring payroll and government disbursement, and virtual instant-issuance rails capturing e-commerce and gig economy payments.
Biometric authentication is expanding into cardholder verification protocols across the Middle East and Africa. Fingerprint and facial recognition modules embedded in POS terminals and mobile banking apps reduce PIN dependency for low-literacy user bases. Retail merchants and transit operators in Dubai, Nairobi, and Lagos deploy these systems to accelerate transaction throughput and reduce fraud chargeback exposure. The technology is expanding into rural agent banking networks where traditional KYC document verification fails.
Saudi Arabia's Saudi Central Bank issued open banking framework guidelines in 2023, mandating standardized APIs for account information and payment initiation services. This regulatory architecture enables prepaid wallet providers to link directly to customer bank accounts for real-time funding, displacing cash load networks. Fintech issuers in Riyadh and Jeddah leverage these rails to offer hybrid prepaid-debit products with lower operational overhead than branch-dependent competitors.
Gig platform workers across the Middle East and Africa increasingly demand same-day wage access rather than monthly or bi-weekly cycles. Ride-hailing, delivery, and domestic services platforms in Cairo, Johannesburg, and Dubai respond by integrating earned wage access features into prepaid card apps. This behavioral shift compresses float revenue for issuers while creating transaction volume density through micro-withdrawal and instant transfer functionality.
Middle East and Africa Prepaid Card Market Segmentation
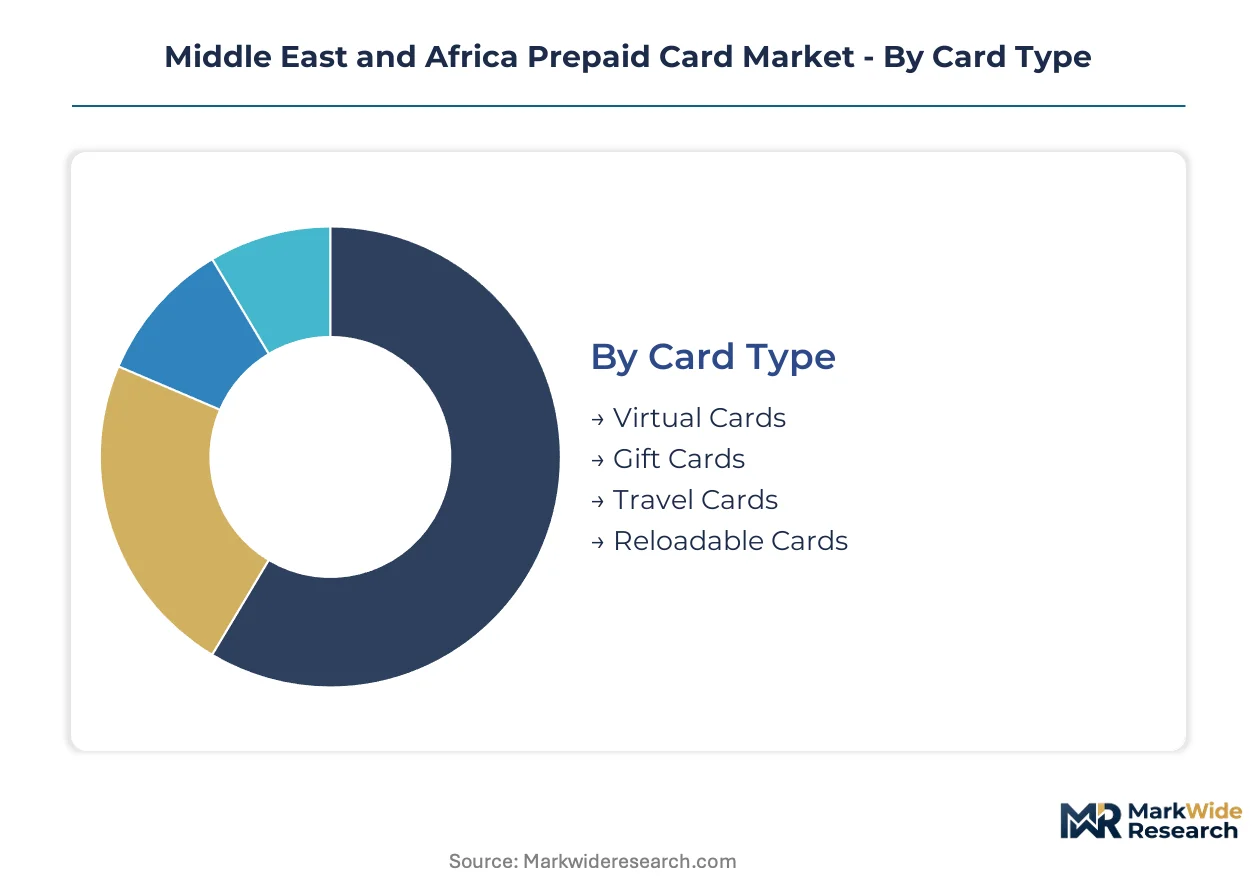
Prepaid card segmentation across the Middle East and Africa reveals divergent commercial logics between physical infrastructure-dependent products and digital-native issuance. Card type determines margin structure, application defines regulatory exposure, end user shapes KYC complexity, and distribution channel dictates customer acquisition economics.
Card Type:
Buyers in this category separate between those requiring physical payment instruments for payroll compliance and those prioritizing instant digital issuance for e-commerce security.
- Reloadable Cards:These products sustain recurring fund flows through EMV-chip physical form factors, with activation longevity exceeding single-load alternatives. Demand concentrates among UAE and Saudi construction sector employers mandated by wage protection system regulations to abandon cash salary distribution.
- Virtual Cards:Instant-issuance 16-digit PANs generated through API integrations enable single-use transaction security without logistics overhead. Egypt and Nigeria's e-commerce platforms targeting under-30 demographics drive adoption, bypassing physical card distribution constraints in remote areas.
- Gift Cards:Single-load closed-loop products with fixed denominations serve seasonal corporate procurement cycles across Gulf retail networks.
- Travel Cards:Multi-currency reloadable instruments with FX lock-in features address inbound tourism payment needs in Dubai and Cairo gateway cities.
Volume sits with Reloadable Cards; growth tilts toward Virtual Cards.
Application:
Commercial purpose in this category maps directly to regulatory jurisdiction, with payroll disbursement falling under central bank mandates and gifting applications subject to consumer protection frameworks.
- Retail Payments:POS-integrated prepaid acceptance spans supermarket chains and fuel stations across South Africa's formal retail corridor, with biometric authentication reducing PIN dependency for low-literacy user bases.
- Corporate Gifting:Bulk procurement contracts with white-label customization services generate concentrated margin pools through seasonal Ramadan and year-end disbursement cycles in Gulf Cooperation Council states.
- Online Shopping:Virtual card APIs embedded in e-commerce checkout flows address fraud concerns among Nigeria's mobile-first banking adopters.
- Travel Expenses:Expense management integrations serve regional corporate travel between Dubai, Johannesburg, and Lagos financial centers.
Corporate Gifting captures premium pricing; Online Shopping expands most quickly.
End User:
Customer type in this category determines KYC tiering intensity, with corporates triggering simplified due diligence for payroll products and consumers facing stricter identity verification for reloadable instruments.
- Corporates:Construction, hospitality, and domestic labor sector employers across Emirates-based operations require compliant salary disbursement rails, with First Abu Dhabi Bank leveraging government banking relationships to anchor this segment.
- Consumers:Unbanked populations in Nigeria and Kenya access formal payment systems through mobile wallet-linked prepaid cards, with USSD interoperability extending reach beyond smartphone penetration limits.
- Tourists:Inbound visitors to Dubai and Cairo utilize travel cards with locked exchange rates, reducing cash handling risks.
- Students:Educational institution partnerships in South Africa distribute allowance-loaded cards with parental control features.
Corporates dominate transaction value; Consumers drive issuance volume expansion.
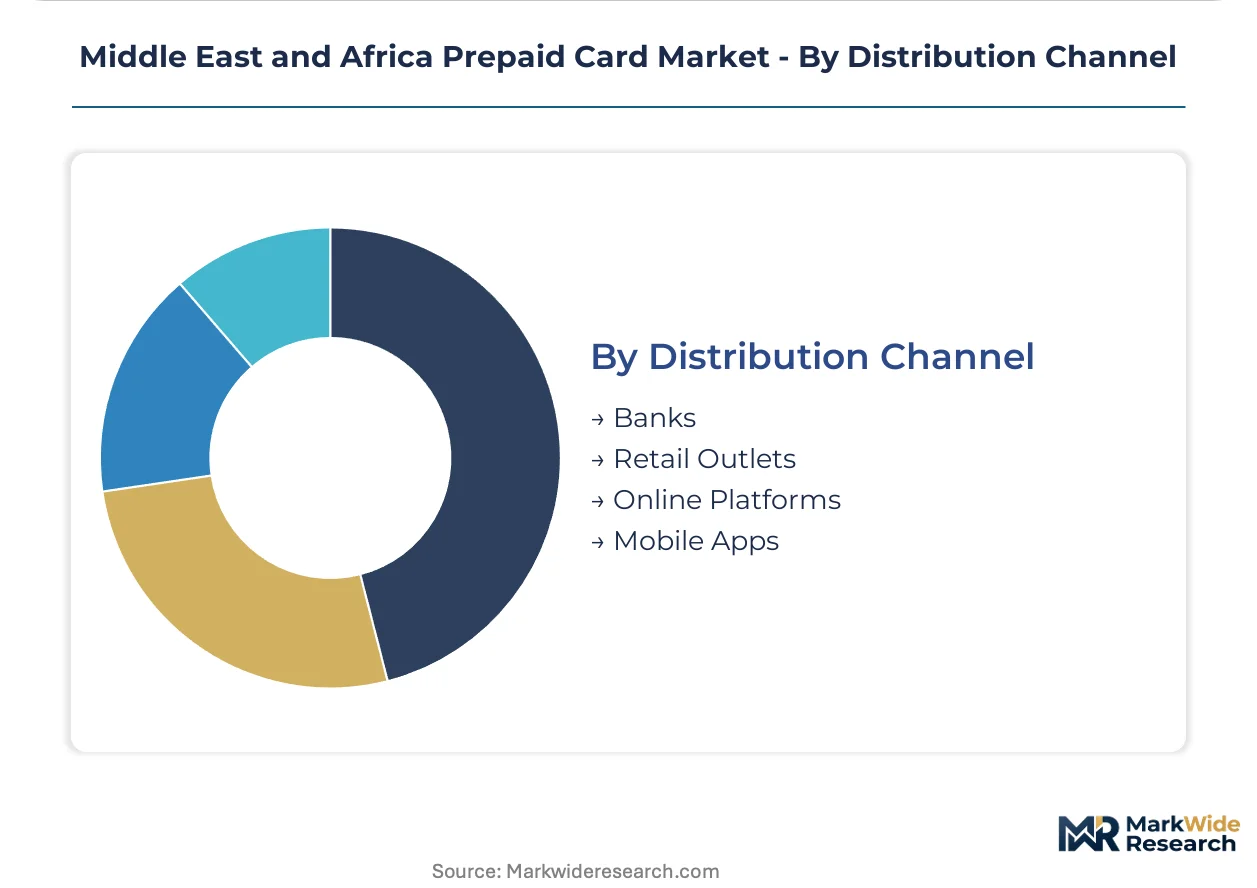
Distribution Channel:
Channel selection in this category reflects infrastructure maturity gradients, with mobile apps penetrating where branch networks fail and retail outlets sustaining cash-loading economics.
- Mobile Apps:Capitec Bank's branch-light digital onboarding anchors South Africa's consumer segment, with biometric identity verification compressing activation timelines below traditional banking benchmarks.
- Banks:Incumbent issuers in Egypt and Morocco face multi-year core system migration timelines to connect prepaid management systems with legacy mainframe infrastructure.
- Retail Outlets:Agent banking networks in rural Kenya and Ethiopia extend cash load access where formal branches are absent.
- Online Platforms:E-commerce checkout integrations enable instant virtual card issuance for single-use security requirements.
Banks retain corporate relationships; Mobile Apps gain share fastest among consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors the Middle East and Africa prepaid card corridor through wage protection system mandates that compress payroll disbursement into electronic rails across Emirates-based employers.
United Arab Emirates
Construction and hospitality employers drive reloadable card demand through central bank compliance requirements. The UAE Central Bank's wage protection system mandates electronic salary distribution for all private sector workers. Dubai's financial district concentrates issuer operations serving domestic labor and corporate payroll segments.
Saudi Arabia
Nitaqat program incentives and labor law reforms accelerate corporate prepaid adoption across construction and services sectors. The Saudi Central Bank's open banking framework enables real-time wallet funding through standardized APIs. Riyadh and Jeddah fintech clusters leverage these rails to deploy hybrid prepaid-debit products.
South Africa
Low-cost digital onboarding and branch-light distribution expand consumer segment penetration among underbanked populations. The Financial Sector Conduct Authority's streamlined e-money licensing reduces capital barriers for fintech entrants. Johannesburg's financial center anchors issuer competition beyond incumbent banking networks.
Nigeria
Mobile wallet integration and USSD interoperability concentrate demand among unbanked populations lacking traditional deposit access. The central bank's tiered KYC framework determines card load limits and cross-border remittance accessibility. Lagos anchors West Africa's prepaid distribution through telecom partnership networks.
Kenya
Agent banking networks extend cash load access to rural areas beyond formal branch infrastructure. Biometric identity verification gaps extend onboarding timelines compared to mobile-native competitor benchmarks. Nairobi's technology corridor concentrates fintech innovation around earned wage access and micro-withdrawal functionality.
Middle East and Africa Prepaid Card Market Competitive Landscape
The competitive structure tilts toward banking incumbents with government relationships and fintech specialists with digital onboarding capabilities. Consolidation pressures emerge around wage protection system compliance contracts and mobile wallet integration partnerships. Two strategic archetypes dominate: legacy banks leveraging regulatory relationships and branch infrastructure, alongside mobile-first challengers compressing activation timelines through biometric verification. Competitive moves concentrate on API partnerships for virtual card issuance and telecom distribution alliances for rural penetration.
Among banking incumbents, First Abu Dhabi Bank exemplifies the government-relationship archetype through its positioning in corporate salary disbursement products. Capitec Bank occupies a parallel position in the consumer segment through branch-light digital distribution. Mastercard represents the technology-layer specialist, competing on virtual card APIs for e-commerce platforms serving regional demographics.
| Leading Market Players |
|---|
| Access Bank Plc |
| Capitec Bank |
| Visa |
| Next Plc |
| Equity Bank |
| American Express |
| First Abu Dhabi Bank |
| Mastercard |
| Alawwal Bank |
| Others |
Supply & Pricing Matrix
UAE wage protection system mandates are forcing construction and hospitality employers to abandon cash salary distribution, compelling prepaid card issuers to absorb scheme fees and biometric KYC costs while competing for bulk corporate contracts. This demand-side regulatory compression reshapes supply economics across EMV chip procurement, personalization bureau capacity, and agent banking network deployment.
Pricing Analysis
Transaction throughput value anchors prepaid card pricing, with issuers charging per-load fees and interchange revenue rather than upfront card costs. Pricing stratifies across premium white-label corporate payroll products, standard reloadable consumer instruments, and economy single-use gift cards. Cost compression in the economy tier intensifies because Naira and Rand depreciation against dollar-denominated scheme fees squeezes margins. Corporate payroll buyers exhibit lowest price sensitivity due to compliance mandate urgency, while unbanked consumer segments demand near-zero activation costs.
Supply Chain Analysis
Card returns and expired instrument refurbishment flows remain minimal in prepaid markets, though reloadable product recovery programs in South Africa and Nigeria extend plastic lifecycle through re-personalization. EMV chip supply concentrates in Taiwan, South Korea, and Germany, while card personalization bureau capacity clusters in UAE, South Africa, and Egypt. Single-source vulnerability runs through Gemalto and Giesecke+Devrient dominance in secure element manufacturing. Distribution runs through telecom agent networks in Nigeria and Kenya, bank branches in UAE and Saudi Arabia, and mobile apps in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepaid card market competition is becoming a vertical-integration race, with players capturing biometric KYC infrastructure and agent banking networks to control customer acquisition costs.
For Market Incumbents: Acquire biometric identity verification platforms to compress onboarding timelines below fintech-native benchmarks. First Abu Dhabi Bank and Capitec Bank must defend corporate payroll relationships through API integration with HR management systems, while fintech challengers threaten margin pools through instant virtual card issuance. Backward integration into personalization bureau capacity in Lagos and Nairobi secures supply continuity against EMV chip shortage risk. For New Entrants and Emerging Players: Mobile app distribution routes offer the lowest customer acquisition friction among underbanked populations in Ethiopia and rural Kenya. White space concentrates in earned wage access products for gig platform workers in Cairo and Johannesburg, where incumbent issuers lack real-time disbursement infrastructure. Partner with ride-hailing and delivery platforms to embed prepaid cards as default payment rails. For Investors and Strategic Acquirers: The window for entry favors fintech specialists with biometric onboarding capabilities and telecom distribution alliances. Long-term viability hinges on regulatory technology infrastructure that satisfies Saudi Central Bank and UAE Central Bank AML mandates. Watch for open banking framework implementation velocity as the inflection signal determining whether prepaid cards become embedded wallet funding rails or face disintermediation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric KYC Platform Acquisition | Capitec Bank's facial recognition onboarding reduces activation abandonment below traditional banking benchmarks. |
| Telecom Distribution Alliance | Equity Bank's Safaricom partnership extends M-Pesa interoperability to prepaid card funding rails. |
| Virtual Card API Launch | Mastercard's instant-issuance infrastructure captures e-commerce fraud-averse demographics in Egypt. |
| Wage Protection System Compliance Contract | First Abu Dhabi Bank anchors Emirates-based construction sector payroll through central bank mandate alignment. |
| Earned Wage Access Feature Integration | Fintech issuers in Riyadh compress float revenue cycles through same-day gig worker disbursement. |
Research Methodology
Central bank regulatory filings, card scheme fee disclosures, and telecom partnership announcements formed the secondary backbone of this analysis. Primary interviews with prepaid product managers at UAE and Saudi banks, fintech CTOs in Lagos and Nairobi, and biometric technology vendors in Johannesburg validated demand assumptions. Financial sector conduct authority licensing databases and e-money issuer registration records anchored bottom-up issuer count estimates, cross-referenced against top-down transaction volume projections from national payment system operators.
Historical trendline analysis across reloadable card activation rates, virtual card issuance velocity, and mobile wallet convergence patterns established baseline growth trajectories. The analytical framework modeled card type, application purpose, end user category, and distribution channel across the projection horizon, with CAGRs derived from regression analysis against wage digitization mandate implementation timelines and open banking framework adoption curves. Biometric authentication penetration rates and agent banking network density served as industry-specific forecast inputs.
The model holds under stable central bank e-money licensing regimes and sustained wage protection system enforcement; deviation in Naira or Rand volatility extremes, or sudden KYC tiering relaxations, would shift issuance volume assumptions. Practitioners should monitor Saudi Central Bank open banking API rollout pace and Ethiopia's telecom-bank partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mpos Terminals Market
Payments
Norway Mobile Payments Market
Payments
Brazil POS Terminal Market
Payments
Smart POS System Market
Payments
Crypto Payment Gateway Market
Payments
Mobile Point of Sale (POS) Market
Payments
Bitcoin Payments Market
Payments
China Forex Cards Market
Payments
Proximity Payment Market
Payments
Bus Card Reader Market
Payments
Transaction Monitoring Market
Payments
Proximity Mobile Payment Market
Payments
Cyprus POS Terminals Market
Payments
Europe Payment Gateways Market
Payments
Malaysia Payments Market
Payments
Global Financial Cards and Payments Market