
 Frozen Vegetables Market | 2026-2036
Frozen Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Vegetables Market Intelligence
Food processing firms is hardening as the dominant end-use vertical, overtaking traditional household channels in volume commitment. Conagra Brands leverages its national retail footprint to sustain frozen vegetable penetration across mass-market grocers. Greenyard anchors European supply through integrated sourcing from contracted growers across Belgium and the Netherlands. Nomad Foods competes aggressively in the branded frozen segment, focusing on premium positioning in British and Scandinavian retail.
Frozen vegetables comprise plant-based produce subjected to rapid temperature reduction, typically at minus 30 to minus 40 degrees Celsius, to arrest enzymatic degradation and preserve nutritional profiles for extended storage. This preservation method serves commercial buyers requiring year-round ingredient consistency regardless of seasonal harvest variability. Mixed vegetables and broccoli command expanding shelf space as food service distributors prioritize SKU consolidation and labor reduction in back-of-house operations. Vacuum packs and cartons capture margin concentration where buyers demand extended shelf stability and visible product integrity at point of purchase.
FDA oversees frozen produce safety under the Food Safety Modernization Act, mandating hazard analysis and preventive controls across processing facilities supplying the United States. EFSA and EU Green Deal frameworks shape European sourcing standards, pushing processors toward lower-carbon freezing technologies and sustainable agricultural partnerships. China's SAMR enforces GB standards for frozen vegetable labeling and additive restrictions, tightening market access for non-compliant imports. Stakeholders must monitor regulatory divergence on pesticide residue thresholds and carbon accounting disclosures as these standards increasingly determine competitive eligibility across major demand centers.
Market Dynamics
Quick-freezing technology adoption and cold chain infrastructure upgrades in emerging economies are compressing harvest-to-freezer windows, reducing quality variance and enabling year-round supply contracts that bypass seasonal price spikes.
Growth Catalysts
- EU Green Deal frameworks:EFSA-aligned sustainability mandates push European processors toward lower-carbon freezing technologies, accelerating capital deployment in ammonia-based and CO2 refrigeration systems.
- Food service distributors:SKU consolidation strategies in institutional catering and quick-service restaurants expand procurement of pre-portioned frozen vegetable blends, reducing back-of-house labor costs.
- Urban China:SAMR-enforced labeling standards build consumer trust in frozen produce, enabling blended fresh-frozen purchasing strategies among middle-income households.
Market Restraints
- Natural gas price volatility:Blast freezing operations remain energy-intensive, with European and North American processors exposed to input cost swings that compress operating margins during price spikes.
- Contracted grower concentration:Belgium and the Netherlands anchor European sourcing through Greenyard-integrated supply chains, creating geographic vulnerability to regional weather shocks and disease outbreaks.
- Fresh produce substitution:Perception gaps around nutritional equivalence persist in premium retail segments, limiting penetration among health-conscious consumers who prioritize farm-direct channels.
Strategic Opportunities
- India cold chain expansion:Government-backed infrastructure investments and FSSAI standardization create entry pathways for processors capable of meeting domestic freezing and packaging requirements.
- Plant-based ready-meal convergence:Frozen spinach and broccoli formulations integrate into vegan protein platforms, capturing demand from flexitarian consumers seeking convenient meal solutions.
- Direct-to-foodservice platforms:Digital procurement channels bypass traditional distributor markups, enabling processors to capture margin concentration through volume commitments with restaurant chains.
Industry Challenges
- Refrigeration technician scarcity:Specialized maintenance skills for ultra-low temperature systems remain concentrated in developed markets, constraining operational uptime in expanding geographies.
- Multi-jurisdictional compliance:Divergent pesticide residue thresholds between FDA, EFSA, and SAMR regimes force processors to maintain parallel supply streams, increasing quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Vegetables Market |
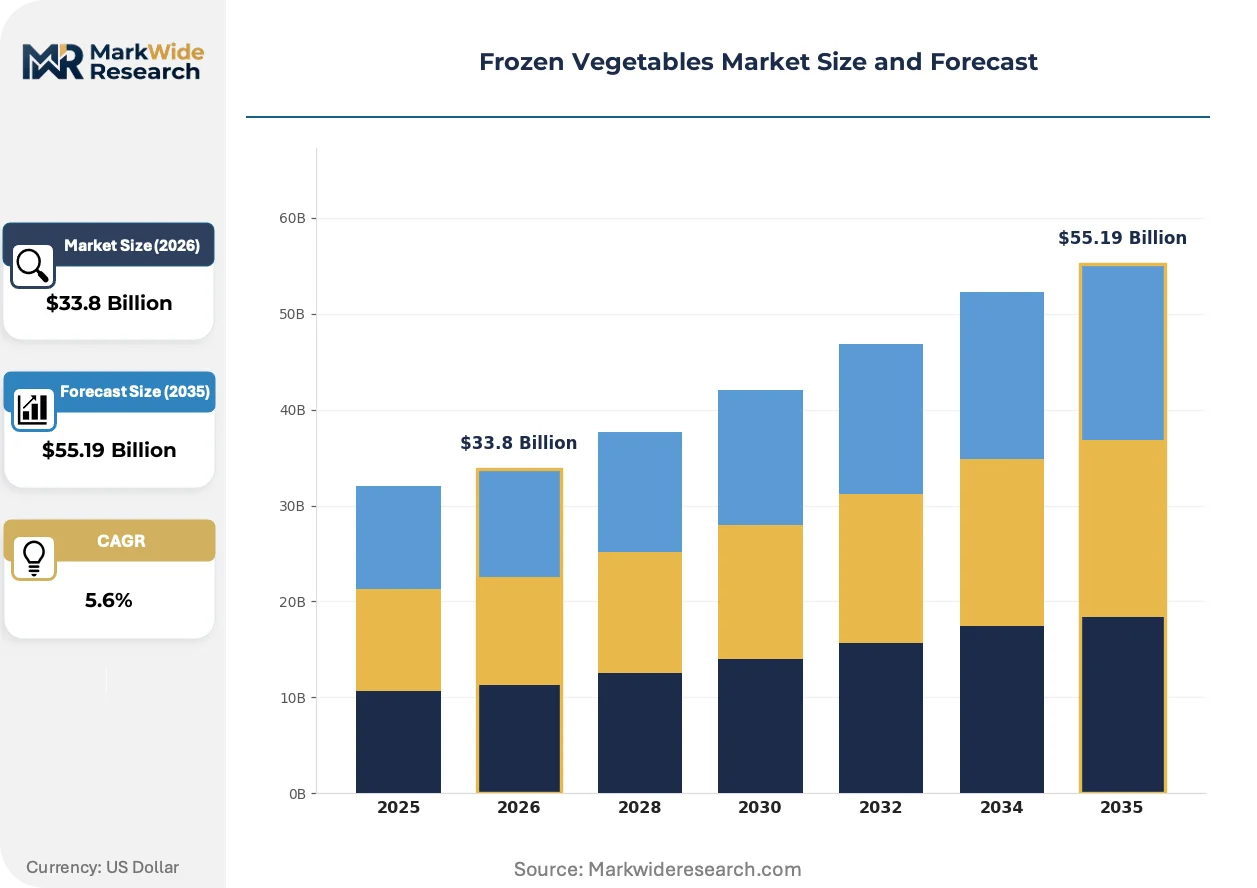
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $55.19 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peas, Corn, Spinach, Mixed Vegetables, Carrots, Broccoli Packaging Type: Plastic Bags, Boxes, Vacuum Packs, Clamshells, Cartons Distribution Channel: Supermarkets, Convenience Stores, Wholesale Clubs, Online Retailers, Food Service Distributors End User: Households, Restaurants, Caterers, Institutional Kitchens, Food Processing Firms |
| Companies Covered | Greenyard, Birds Eye Foods, Ardo Group, Nomad Foods, Simplot Company, Bonduelle, Conagra Brands, Seneca Foods, McCain Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Vegetables Market Strategic Shifts & Innovations
Technology convergence between freezing equipment and packaging materials is compressing cold chain loss rates while regulatory pressure on carbon intensity reshapes capital allocation priorities across processing tiers.
Individual quick freezing (IQF) technology with fluidized bed designs is overtaking traditional blast freezing for delicate vegetables like spinach and peas. Food manufacturers in Western Europe and North America are retrofitting lines at accelerating pace. This equipment is overtaking legacy tunnel systems by reducing clumping damage and enabling precise portion control for automated meal assembly lines.
EU F-Gas Regulation phase-down schedules are mandating transition from hydrofluorocarbon refrigerants to natural alternatives in freezing infrastructure. Processors face accelerated depreciation of installed equipment and compressed replacement timelines. The regulatory pressure falls heaviest on mid-cap European operators lacking capital reserves for simultaneous compliance and capacity expansion.
Blended fresh-frozen basket strategies are emerging among urban Chinese households as SAMR labeling transparency builds category trust. Traditional wet market dominance is fragmenting as supermarket chains and e-commerce platforms capture share through subscription-based frozen vegetable delivery. This behavioral pivot concentrates most visibly in tier-one cities where cold chain last-mile density supports reliable home delivery windows.
Frozen Vegetables Market Segmentation
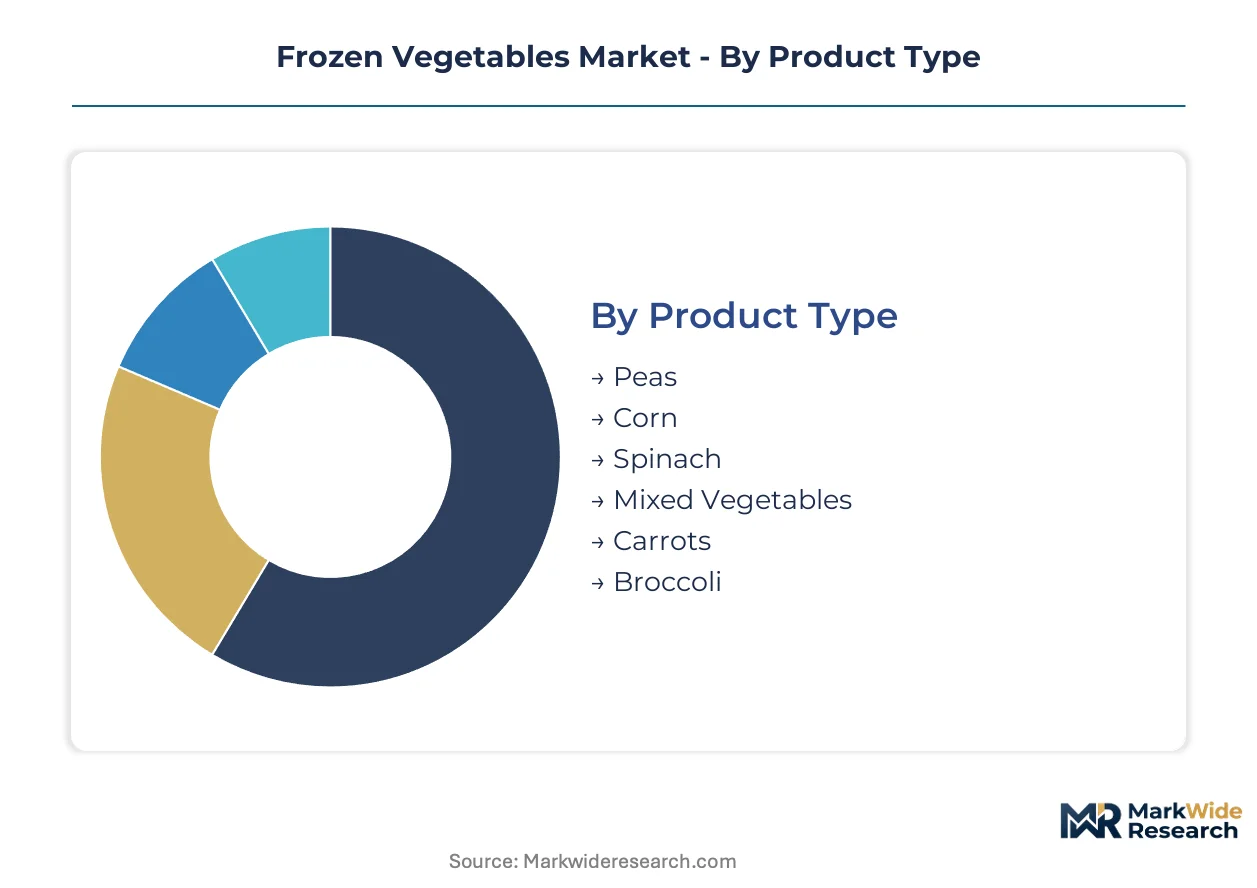
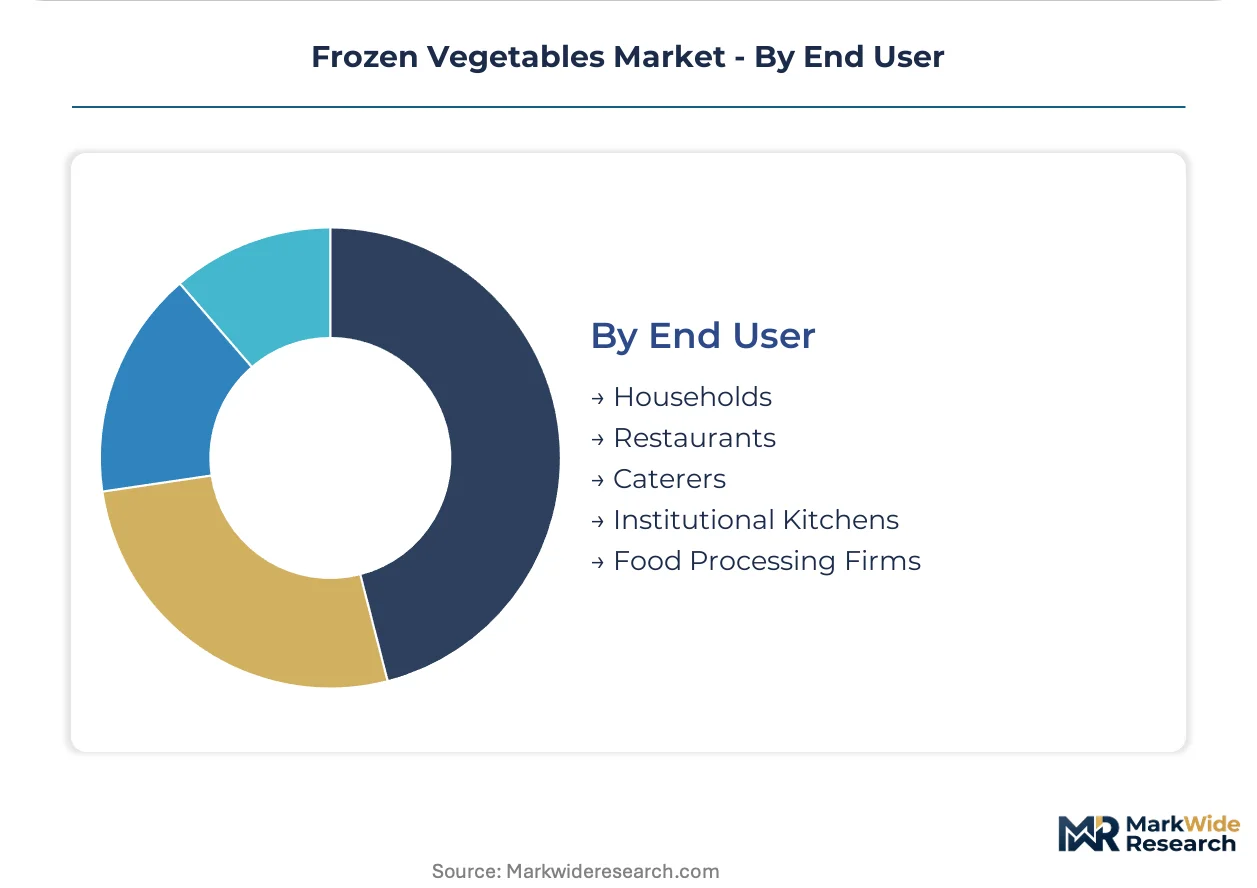
Frozen vegetables demand fragments across multiple axes, with certification requirements varying sharply by end-use destination and packaging format. Processors must maintain parallel compliance streams to serve institutional buyers under FDA preventive controls alongside retail channels subject to SAMR labeling mandates.
Product Type:
Certification burden falls heaviest on organic-labeled and ready-to-eat segments, where EFSA pesticide residue thresholds and FDA hazard analysis protocols demand dedicated processing lines and traceability documentation.
- Mixed Vegetables:Blended formulations of peas, carrots, and corn dominate food service procurement for standardized portioning. Institutional kitchens in the United States and Germany concentrate orders here, driven by SKU consolidation mandates that reduce back-of-house labor.
- Broccoli:IQF-processed florets retain texture integrity through fluidized bed freezing, enabling premium positioning in British and Scandinavian retail. Greenyard-integrated supply chains from Belgium and the Netherlands anchor European availability.
- Peas:Sweet garden varieties command stable procurement volumes from frozen food manufacturers.
- Corn:Cut kernel and cob formats serve distinct channel requirements.
- Spinach:Leafy greens face stringent FDA preventive controls for Listeria mitigation.
- Carrots:Diced and crinkle-cut specifications dominate industrial ingredient sourcing.
Leading the category by volume: Mixed Vegetables. Growing fastest: Broccoli.
Packaging Type:
Cost tier stratification separates premium shelf-stable formats from economy bulk packaging, with margin concentration tracking directly to barrier properties and retail visibility.
- Vacuum Packs:Multi-layer film structures with oxygen scavenging layers extend shelf stability to 24 months, capturing margin concentration where buyers demand visible product integrity. Urban Chinese households through e-commerce subscription channels drive fastest expansion.
- Cartons:Paperboard with polyethylene lining satisfies EU Green Deal circularity preferences in French and German retail. EFSA-aligned sustainability mandates push processors toward fiber-based alternatives despite higher unit costs.
- Plastic Bags:Polyethylene pouches dominate economy-tier household penetration.
- Boxes:Corrugated containers serve wholesale club bulk formats.
- Clamshells:Thermoformed PET enables retail visibility for premium single-serve portions.
Cartons gain share fastest in European markets. Vacuum packs anchor volume in food service.
Distribution Channel:
Application-specific throughput requirements separate high-velocity retail from specialized food service logistics, with cold chain density determining viable service territories.
- Food Service Distributors:Broadline operators consolidate frozen vegetable procurement for restaurant chains and institutional accounts, capturing volume through direct-to-operator platforms that bypass traditional markups. Quick-freezing technology adoption in India and Brazil reshapes supply reliability for expanding geographies.
- Online Retailers:E-commerce platforms in tier-one Chinese cities leverage last-mile cold chain density for subscription-based frozen vegetable delivery, fragmenting traditional wet market dominance.
- Supermarkets:Mass-market grocers sustain penetration through national retail footprints.
- Convenience Stores:Limited frozen capacity restricts assortment to high-rotation SKUs.
- Wholesale Clubs:Bulk formats align with household stockpiling behavior.
Food Service Distributors command highest volume commitment. Online Retailers expand most quickly in urban China.
End User:
Customer type determines specification stringency, with food processing firms imposing ingredient consistency standards that exceed household channel requirements.
- Food Processing Firms:Ready-meal manufacturers expand procurement of frozen spinach and broccoli for vegan protein platform integration, requiring year-round supply contracts that bypass seasonal price spikes. FDA preventive controls and SAMR additive restrictions govern parallel supply streams.
- Restaurants:Quick-service and casual dining operators prioritize pre-portioned blends for labor reduction.
- Households:Traditional retail channel showing relative volume decline as commercial buyers harden dominance.
- Caterers:Event and institutional catering demand concentrates in mixed vegetable formats.
- Institutional Kitchens:Schools and healthcare facilities drive standardized nutrition compliance.
Food Processing Firms overtake Households in volume commitment. Restaurants climb fastest as food service recovery continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and the Netherlands concentrate frozen vegetable processing capacity through integrated grower contracts, while consumption gravity shifts toward China and the United States as urban households adopt blended fresh-frozen purchasing patterns.
United States
Food service distributors and ready-meal manufacturers drive procurement volume for pre-portioned frozen vegetable blends. FDA preventive controls under the Food Safety Modernization Act govern processing facility compliance. Midwest processing clusters in Illinois and Wisconsin anchor domestic freezing capacity for institutional and retail channels.
China
Urban households in tier-one cities are fragmenting traditional wet market dominance through subscription-based frozen vegetable delivery. SAMR enforces GB standards for labeling and additive restrictions that tighten import access. Cold chain last-mile density in Shanghai and Beijing supports reliable home delivery windows for e-commerce platforms.
Germany
Retail chains prioritize paperboard cartons with polyethylene lining to satisfy EU Green Deal circularity preferences. EFSA-aligned sustainability mandates push processors toward ammonia-based and CO2 refrigeration systems. The North Rhine-Westphalia region hosts concentrated freezing infrastructure serving French and Dutch export markets.
India
Government-backed cold chain infrastructure investments and FSSAI standardization create entry pathways for domestic and foreign processors. Quick-freezing technology adoption compresses harvest-to-freezer windows for spinach and broccoli procurement. Maharashtra and Gujarat agricultural belts supply raw material to emerging freezing facilities in Pune and Ahmedabad.
Brazil
Food processing firms expand procurement of frozen vegetables for ready-meal formulations targeting flexitarian consumers. Cold chain infrastructure upgrades reshape supply reliability for expanding urban markets. São Paulo state concentrates both agricultural production and freezing capacity for Mercosur distribution.
Frozen Vegetables Market Key Industry Players
Top-tier vendors anchor integrated supply chains spanning contracted growers and retail distribution, while mid-cap specialists compete on certification tier and regional cold chain density. The market structure tilts toward consolidation through grower-processor integration and national retail footprint scale. Three archetypes dominate: vertically integrated agricultural conglomerates, branded frozen food platforms, and private-label contract manufacturers. Competitive intensity concentrates on M&A-driven capacity consolidation and direct-to-foodservice platform development that bypasses traditional distributor markups.
Among European-integrated operators, Greenyard and Nomad Foods occupy positions exemplifying the grower-processor-retail continuum. Greenyard anchors supply through contracted growers across Belgium and the Netherlands, while Nomad Foods competes in the branded frozen segment with premium positioning in British and Scandinavian retail. Conagra Brands represents the North American mass-market archetype, leveraging national retail footprint to sustain frozen vegetable penetration across grocery channels. These three entities illustrate how geographic sourcing concentration and retail scale differentiate competitive positioning across Atlantic markets.
| Leading Market Players |
|---|
| Greenyard |
| Birds Eye Foods |
| Ardo Group |
| Nomad Foods |
| Simplot Company |
| Bonduelle |
| Conagra Brands |
| Seneca Foods |
| McCain Foods Limited |
| Others |
Cost & Logistics Intelligence
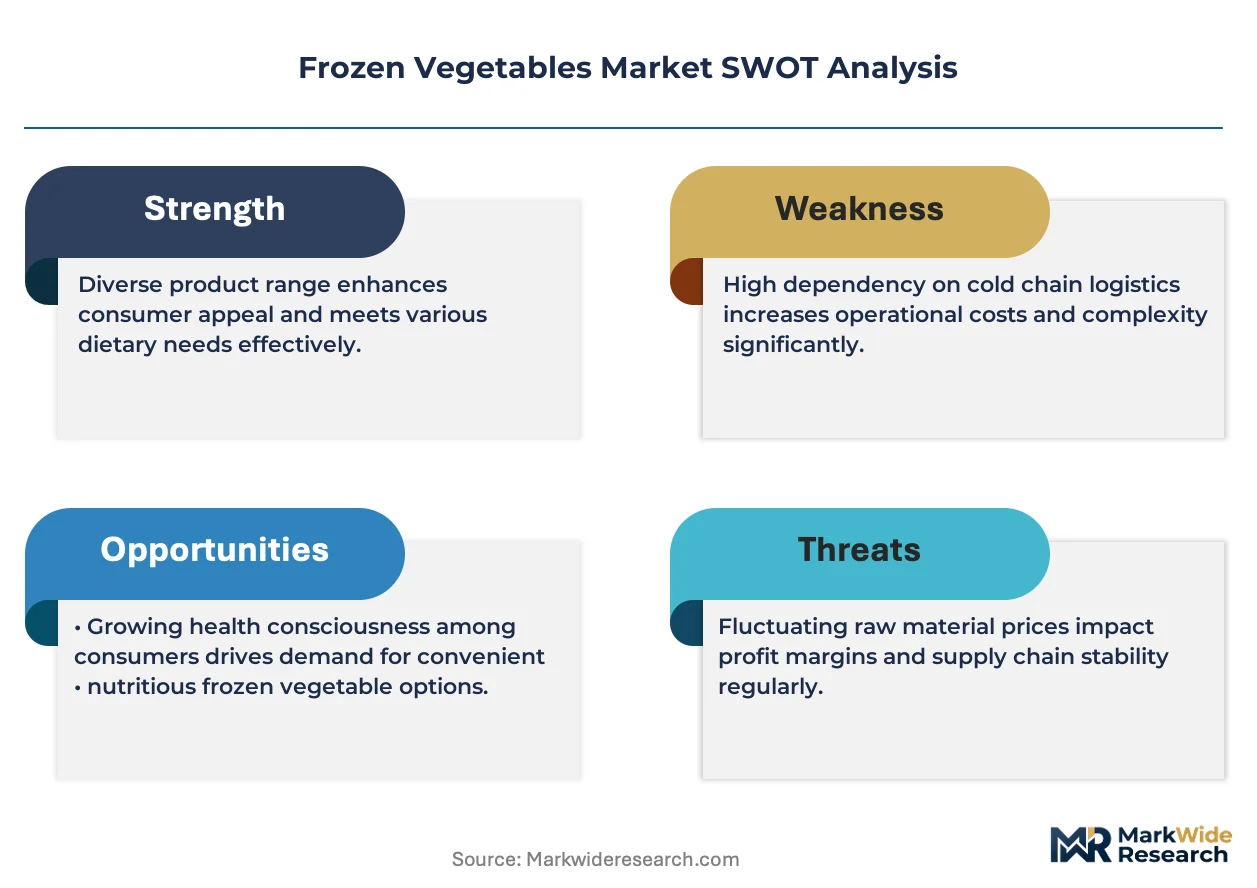
Certification-grade bifurcation between organic-labeled and conventional frozen vegetables manifests in divergent pricing premiums and parallel supply chain configurations, with EFSA-aligned sustainability mandates and FDA preventive controls forcing dedicated processing lines that reshape procurement geography.
Pricing Analysis
Short lead-time premiums for just-in-time food service contracts command pricing advantages over spot inventory held in cold storage, with contract-based long-term offtake dominating institutional procurement. Price differentiation rests on certification level and volume scale, with organic-labeled SKUs capturing margin concentration in European retail. Pricing pressure stems from natural gas volatility in blast freezing operations, compressing margins for mid-cap processors lacking ammonia-based refrigeration. Quick-service restaurant chains exhibit highest price sensitivity, while premium retail channels prioritize visible product integrity over unit cost.
Supply Chain Analysis
Domestic-content rules in India's FSSAI standardization and China's SAMR enforcement are reshaping sourcing toward local grower contracts, displacing import-dependent supply streams. Geographic supply concentration centers on Belgium, the Netherlands, and China, with raw material dependencies spanning spinach from Maharashtra, broccoli from Gujarat, and peas from European contracted growers. Single-source vulnerability to regional weather shocks in the Benelux growing belt threatens year-round availability. Distribution runs through broadline food service operators consolidating procurement for restaurant chains and institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in contracted grower capacity and specialized refrigeration technician scarcity prop pricing power for processors with captive sourcing relationships.
For Market Incumbents: Extend backward integration into contracted grower networks across Belgium and the Netherlands to defend against geographic concentration risk from regional weather shocks. Deepen ammonia-based and CO2 refrigeration system deployment ahead of EU F-Gas Regulation phase-down timelines to capture compliance-driven competitor displacement. For New Entrants and Emerging Players: The premium-economy price-point gap in India's emerging cold chain infrastructure creates white-space opportunity for FSSAI-compliant processors targeting food service distributors in Pune and Ahmedabad. Target direct-to-foodservice digital procurement platforms bypassing traditional distributor markups as the most penetrable channel angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap European operators possessing EFSA-aligned sustainability certifications and ammonia refrigeration conversion capability given EU Green Deal capital deployment acceleration. Monitor cold chain infrastructure investment announcements in tier-one Chinese cities as the inflection indicator for subscription-based frozen vegetable delivery platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contracted Grower Networks | Greenyard-integrated sourcing from Belgium and Netherlands anchors European supply reliability against weather volatility. |
| Ammonia-Based Refrigeration System Deployment | EU F-Gas Regulation phase-down mandates accelerate capital deployment in natural alternative freezing infrastructure. |
| Direct-to-Foodservice Digital Platform Launch | Broadline operator consolidation enables margin capture through volume commitments with restaurant chains. |
| Organic Certification Investment | EFSA pesticide residue thresholds and FDA preventive controls command dedicated processing lines for premium positioning. |
| Cold Chain Infrastructure Partnership | FSSAI standardization in Maharashtra and Gujarat creates entry pathways for domestic and foreign processors. |
Research Approach
Multi-period observation of cold chain infrastructure investments, regulatory filing timelines, and procurement contract structures anchored the trend analysis, supplemented by interviews with freezing equipment engineers, food service procurement directors, contracted grower cooperative managers, and retail category buyers. Secondary validation drew from FDA FSMA compliance records, EFSA sustainability mandate documentation, SAMR GB standard filings, FSSAI cold chain directives, and customs trade data for frozen vegetable flows. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Input-output matrices mapped product type, packaging format, distribution channel, and end-user specifications across the projection horizon. CAGRs were derived from segmented growth rate analysis incorporating quick-freezing technology adoption curves, urban household basket shift velocities in tier-one Chinese cities, and food processing firm procurement expansion trajectories. Industry-specific forecast inputs included natural gas price volatility scenarios and EU F-Gas Regulation compliance cost curves.
Inputs from regulatory filing databases and equipment manufacturer order backlogs were available through the study window; gaps in real-time cold chain infrastructure deployment data introduce uncertainty bands around emerging market penetration assumptions. Forecasts reflect documented assumptions on technology adoption rates and regulatory enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Europe Blueberry Market