
 Herbal Cosmetics Market | 2026-2036
Herbal Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Cosmetics Market Analysis
Botanical actives are replacing synthetic preservatives across mid-premium skincare lines, and this material substitution is expanding unit economics for clean-label manufacturers. L'Oreal SA leverages its botanical research network to secure rare plant extract supply chains. Patanjali Ayurved Ltd. anchors its portfolio in domestically sourced Ayurvedic herbs. Weleda AG differentiates through biodynamic cultivation standards that command shelf price premiums.
Herbal cosmetics comprise topical preparations formulated with plant-derived extracts, essential oils, and natural butters as primary functional ingredients, manufactured through cold-press extraction or supercritical CO2 processing to preserve bioactive compound integrity. These products serve dermatological care and aesthetic enhancement while minimizing petrochemical content. Skincare dominates value contribution due to higher per-unit pricing and repeat purchase frequency. Plant extracts represent the fastest-growing ingredient source category as formulators seek provenance-verified raw materials. Online retail channels capture disproportionate growth among millennial and eco-conscious consumer segments.
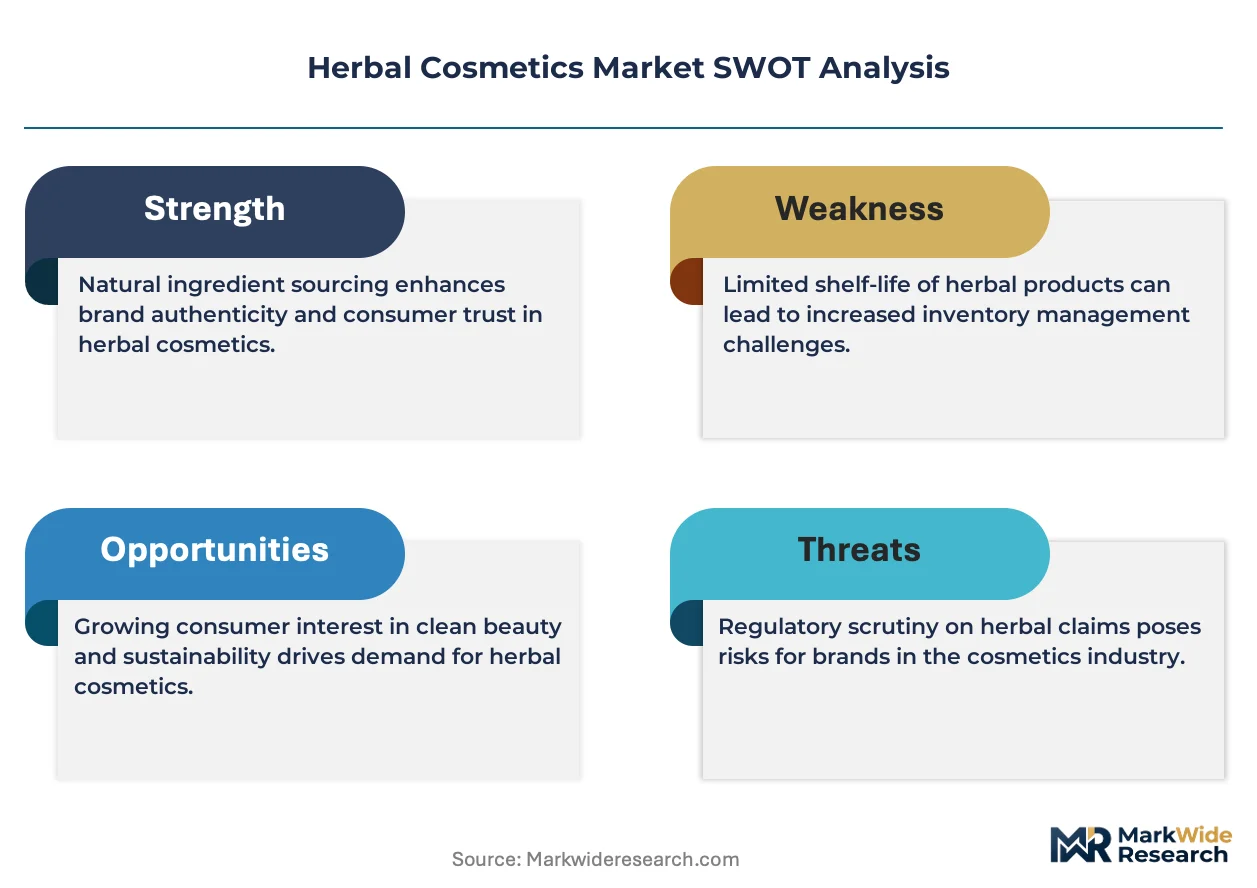
India's CDSCO mandates ingredient disclosure standards for herbal topical products, while REACH in Europe restricts certain botanical allergens in cosmetic formulations. The EU Green Deal accelerates sustainable sourcing requirements across supply chains. India's BIS certification and PLI scheme for herbal product manufacturing create dual compliance and incentive structures. Stakeholders must monitor evolving natural claim substantiation rules across multiple jurisdictions to preserve market access.
Market Dynamics
REACH compliance in Europe and India's PLI scheme are restructuring competitive requirements, forcing manufacturers to choose between premium provenance investments or volume-scale standardization. This regulatory divergence is compressing mid-tier players while rewarding specialists at both ends.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for herbal manufacturing attract domestic and foreign capital into Ayurvedic processing facilities, expanding certified output capacity.
- Millennial dermatological preferences:Plant-based skincare formulations command repeat purchase loyalty among consumers aged 25-40 seeking clean-label transparency.
- Supercritical CO2 extraction:This cold-processing technology preserves heat-sensitive bioactive compounds in botanical actives, enabling premium positioning for functional ingredient suppliers.
Market Restraints
- Botanical allergen restrictions:REACH Annex III limitations on certain plant-derived sensitizers constrain formulation freedom for European manufacturers.
- Provenance verification costs:Supply chain documentation for wild-harvested herbs from Himalayan and Western Ghats regions adds 15-25% to raw material procurement overhead.
- Synthetic preservative performance gap:Natural alternatives struggle to match paraben efficacy in emulsion stability, shortening shelf life and raising spoilage risk.
Strategic Opportunities
- German biodynamic certification:Demeter and Natrue standards command 30-40% shelf price premiums in European pharmacy and specialty retail channels.
- Direct-to-consumer subscription models:Personalized herbal skincare regimens bypass traditional retail markups while capturing lifetime value through recurring revenue.
- EU Green Deal sustainable sourcing mandates:Early compliance with deforestation-free supply chain requirements secures preferential access to regulated European markets.
Industry Challenges
- Phytochemistry analytical talent scarcity:Formulators with expertise in standardization of variable botanical extracts command premium compensation, constraining R&D expansion.
- Multi-jurisdiction claim substantiation:Divergent natural and organic certification requirements across BIS, USDA, and EU 2018/848 create compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Cosmetics Market |
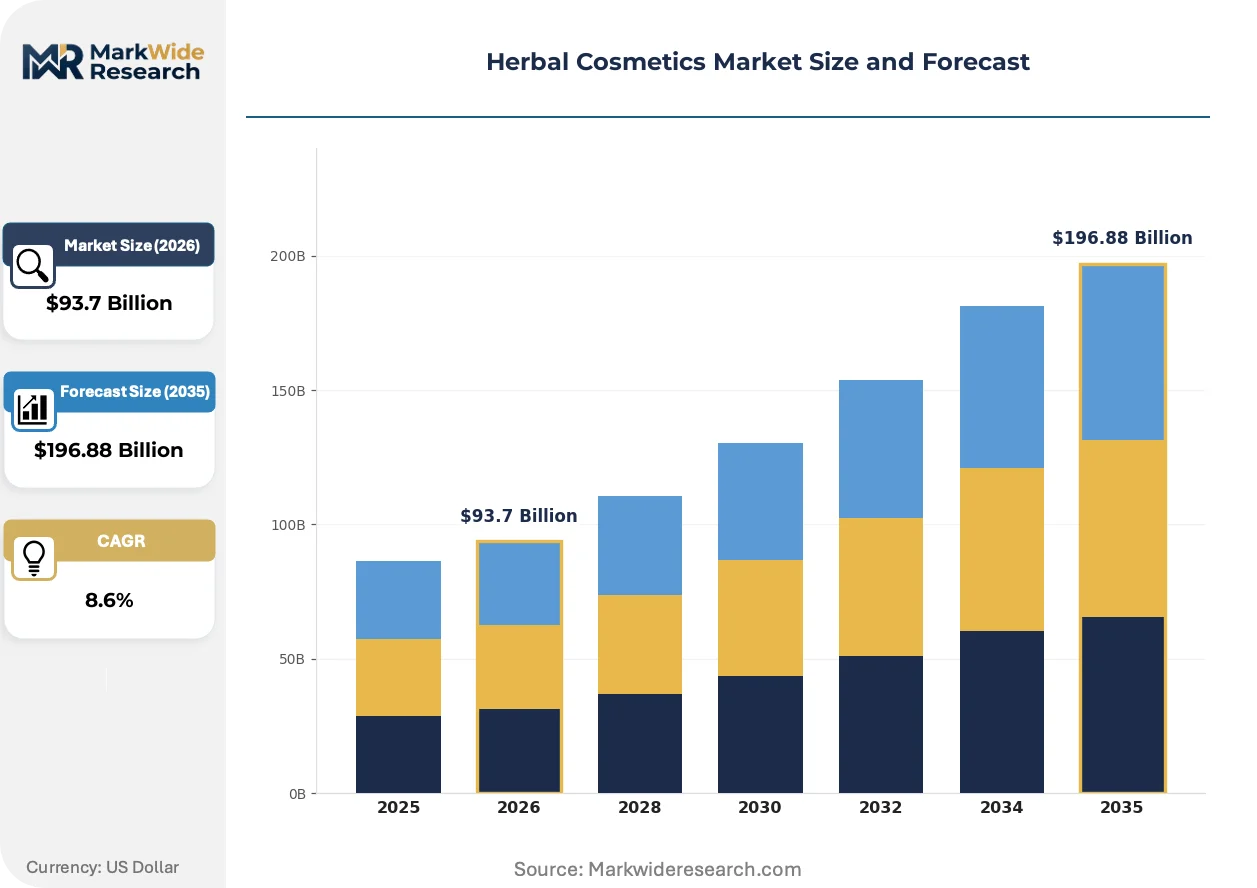
| Market Size in 2026 | $93.7 Billion |
| Market Size in 2035 | $196.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Source: Plant Extracts, Essential Oils, Minerals, Natural Butters Target Audience: Eco-conscious Consumers, Millennials, Dermatologically Sensitive Individuals, Luxury Buyers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Salons |
| Companies Covered | Marico Limited, L'Oreal SA, Procter & Gamble Company, Groupe Rocher, Patanjali Ayurved Ltd., Himalaya Global Holdings Ltd., Weleda AG, Emami Ltd., Dabur Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Cosmetics Market Emerging Trajectories
Biotechnology is penetrating botanical supply chains, altering how manufacturers secure consistent active compound concentrations. These developments are compressing traditional wild-harvesting economics while opening precision-controlled alternatives.
Bioreactor cultivation of plant stem cells is converging with traditional extraction methods, enabling year-round production of rare botanicals without agricultural land use. Premium skincare manufacturers in Germany and South Korea adopt these cell cultures to circumvent climate-dependent harvest volatility. The technology is converging with carbon accounting frameworks, allowing brands to market measurable biodiversity preservation alongside product efficacy.
The EU Green Deal's deforestation-free regulation tightens traceability requirements for imported botanical raw materials. Cosmetic manufacturers must now document geographic origin and harvesting methods for palm derivatives, shea butter, and exotic plant extracts. Small and mid-sized formulators in France and Italy face particular strain, as compliance systems demand capital investments previously reserved for multinational supply chains.
Ingredient provenance has become a primary purchase determinant for millennial and Generation Z consumers, displacing brand heritage as the dominant decision factor. Clean beauty retailers in the United States and United Kingdom now feature supply chain maps alongside product descriptions. This transparency expectation is most pronounced in facial serum and treatment oil categories, where consumers research specific growing regions and extraction methods before committing to purchase.
Herbal Cosmetics Market Segmentation
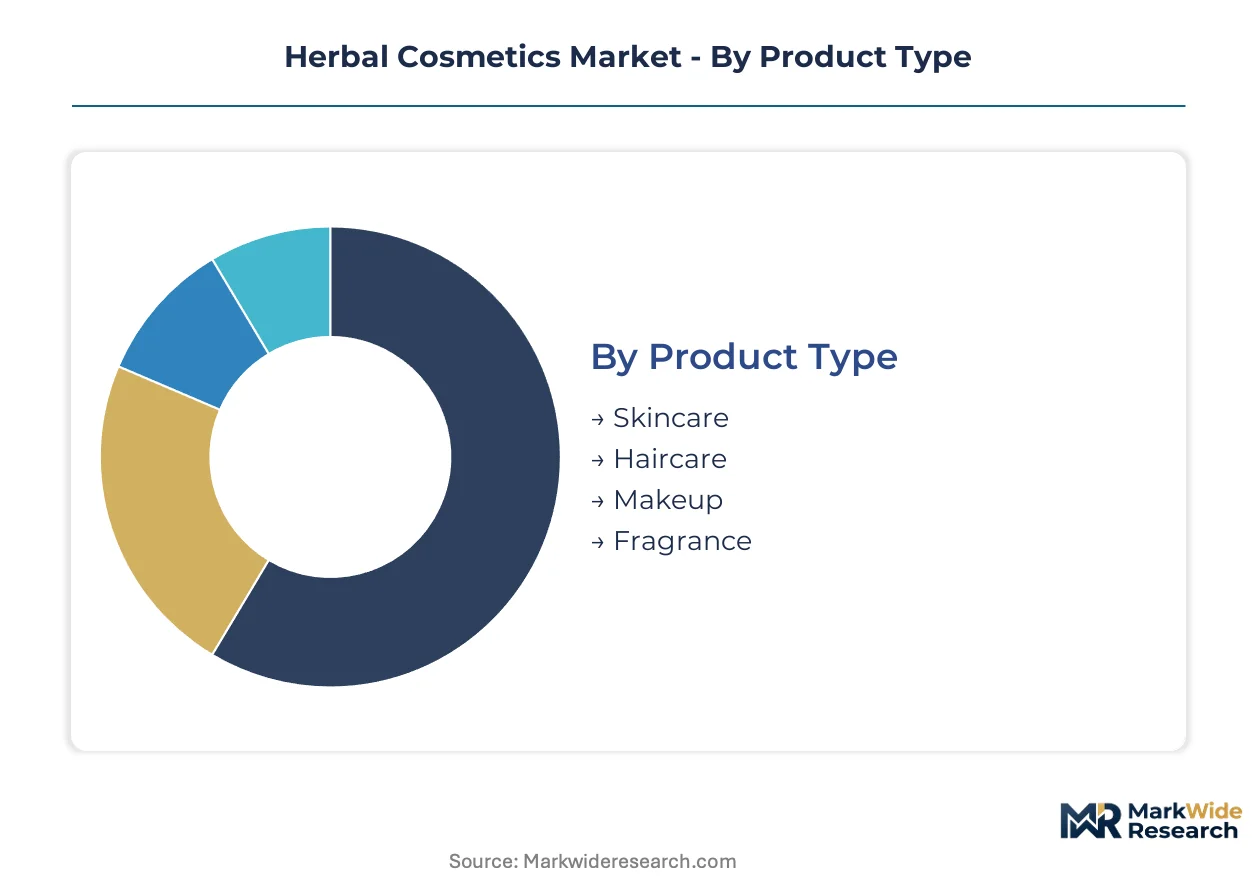
Herbal cosmetics segmentation reveals how supply chain specialization and consumer identity intersect. Product formulation choices determine raw material sourcing geography, while distribution channel selection dictates margin structure and brand positioning.
Product Type:
Supply concentration in cold-press and supercritical CO2 extraction infrastructure favors skincare and haircare manufacturers with captive processing capabilities.
- Skincare:Facial serums, moisturizers, and treatment oils formulated with standardized botanical actives command premium shelf positioning. Demand concentrates among millennial consumers in Germany and India seeking provenance-verified ingredients with documented bioactive compound concentrations.
- Haircare:Shampoos and conditioners leverage Ayurvedic herb traditions from India's Western Ghats and Kerala regions, where BIS-certified processing facilities cluster. The segment climbs fastest as scalp microbiome formulations displace synthetic surfactant alternatives in European pharmacy channels.
- Makeup:Mineral-based color cosmetics with plant-derived binders serve dermatologically sensitive users.
- Fragrance:Essential oil compositions avoid synthetic fixatives through natural extraction methods.
Today's leader: Skincare. Tomorrow's challenger: Haircare.
Ingredient Source:
Cost tier stratification separates commodity-grade suppliers from certified organic and biodynamic sources with documented chain-of-custody.
- Plant Extracts:Standardized polyphenols, flavonoids, and terpenes from identified cultivars provide functional efficacy in anti-aging and brightening formulations. Procurement concentrates in contract cultivation arrangements across India's Madhya Pradesh and Karnataka states, where CDSCO traceability requirements intersect with EU Green Deal deforestation-free mandates.
- Essential Oils:Steam-distilled and cold-pressed aromatic compounds from lavender, tea tree, and sandalwood supply fragrance and therapeutic applications. German and French formulators source through Natrue-certified cooperatives to secure pharmacy channel access.
- Minerals:Iron oxides, zinc oxides, and mica provide color and sun protection in makeup applications.
- Natural Butters:Shea, cocoa, and mango butters deliver emollient properties in body care formulations.
Plant extracts dominate current procurement volumes. Essential oils gain share fastest as fragrance-free claims lose market traction.
Target Audience:
Application intensity varies sharply across consumer psychographic segments, with subscription repurchase rates highest among identity-driven purchasers.
- Eco-conscious Consumers:Carbon-accounting transparency and biodiversity-positive sourcing claims drive purchase decisions. This segment expands most quickly as EU Green Deal compliance becomes a visible differentiator on retail packaging.
- Millennials:Clean-label transparency and ingredient provenance research precede purchase commitment. Demand clusters in direct-to-consumer channels where supply chain maps accompany product descriptions.
- Dermatologically Sensitive Individuals:Fragrance-free and allergen-screened formulations serve reactive skin conditions.
- Luxury Buyers:Rare botanicals and limited-harvest ingredients support price positioning.
Millennials anchor current volume. Eco-conscious consumers represent the steepest expansion trajectory as regulatory disclosure requirements mature.
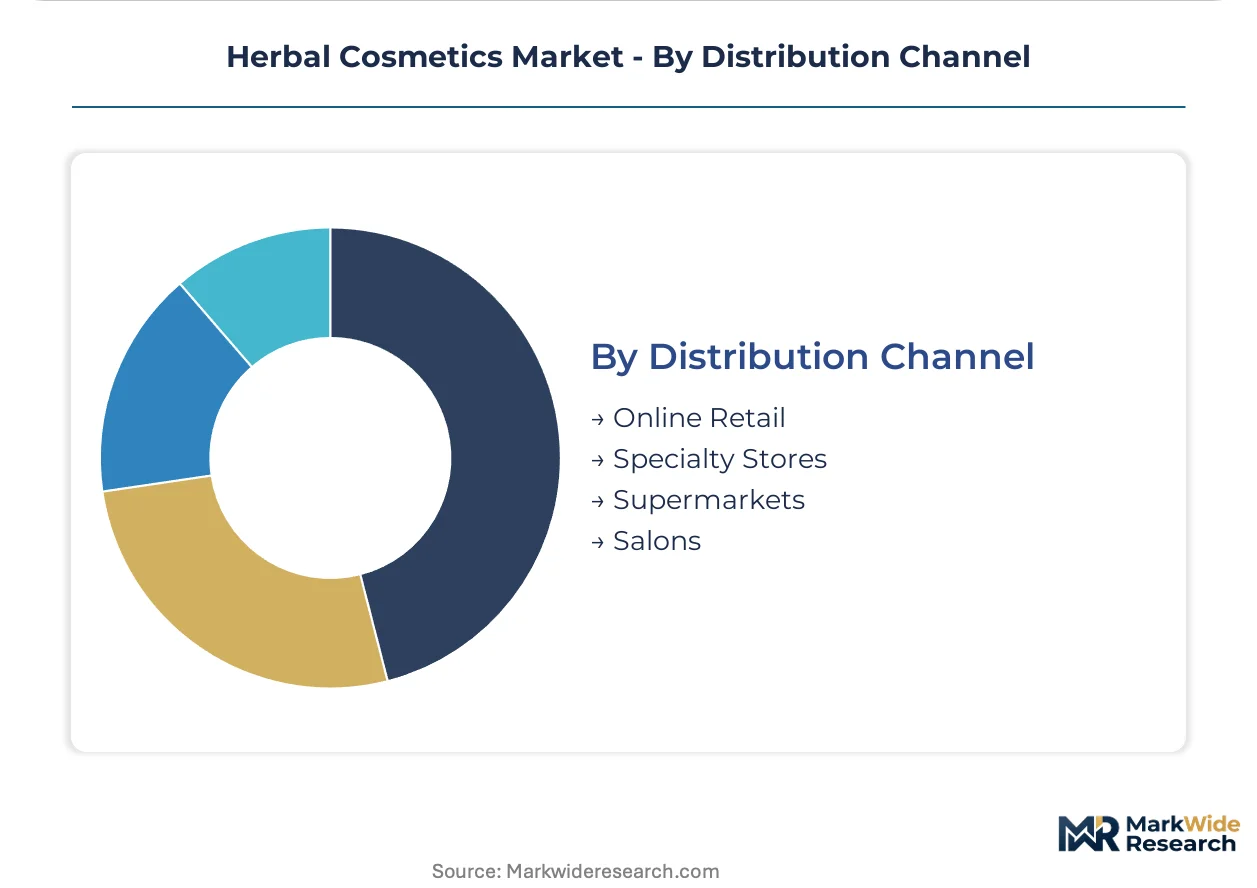
Distribution Channel:
Margin structure diverges between high-touch specialty retail and scalable digital fulfillment, with hybrid models emerging in German and US markets.
- Online Retail:Direct-to-consumer platforms and marketplace listings capture millennial and Generation Z segments through subscription personalization and supply chain transparency tools. The channel gains share fastest as clean beauty retailers integrate origin mapping into digital product pages.
- Specialty Stores:Pharmacy, apothecary, and clean beauty boutiques provide consultation-driven sales for premium and biodynamic-certified lines. German Demeter and Natrue-certified products concentrate here.
- Supermarkets:Mass-market herbal variants compete on shelf price with conventional alternatives.
- Salons:Professional-grade treatments and back-bar products serve aesthetic service providers.
Specialty stores maintain premium positioning. Online retail challenges through recurring revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's herbal cosmetics manufacturing belt spans Maharashtra, Karnataka, and Kerala, where Ayurvedic processing infrastructure clusters around Mumbai, Bengaluru, and Kochi. CDSCO traceability mandates intersect with EU Green Deal deforestation-free requirements, reshaping export-oriented supply chains. Germany's biodynamic certification networks and the United States' direct-to-consumer platforms represent alternative demand poles.
India
Millennial consumers aged 25-40 drive domestic demand for provenance-verified skincare, while Ayurvedic heritage brands capture repeat purchase loyalty. The PLI scheme for herbal manufacturing attracts capital into Madhya Pradesh and Karnataka processing facilities. Mumbai-Pune corridor hosts BIS-certified contract manufacturers serving European pharmacy channels.
Germany
Demeter and Natrue standards command 30-40% shelf price premiums in pharmacy retail, with consumers prioritizing carbon-accounting transparency. REACH Annex III restrictions on botanical allergens constrain formulation portfolios for domestic manufacturers. Baden-Württemberg and Bavaria concentrate biodynamic cultivation research and certified organic processing infrastructure.
United States
Clean beauty retailers integrate supply chain mapping into digital product pages, serving millennial and Generation Z research behaviors. FDA cosmetic labeling requirements overlap with state-level clean beauty legislation in California and New York. Los Angeles and New York City anchor direct-to-consumer brand headquarters and subscription fulfillment networks.
France
Essential oil cooperatives in Provence supply Natrue-certified aromatic compounds to premium skincare formulators. EU Green Deal deforestation-free regulations tighten traceability for shea butter and exotic plant imports. Grasse region maintains traditional extraction expertise while adopting supercritical CO2 processing for heat-sensitive actives.
South Korea
Bioreactor cultivation of plant stem cells gains traction among functional skincare manufacturers seeking climate-independent raw material security. MFDS cosmetic safety standards govern novel botanical ingredient approvals. Seoul Capital Area concentrates biotechnology R&D facilities converging traditional herbal medicine with precision fermentation.
Herbal Cosmetics Market Vendor Landscape
Global majors compete with regional champions across certification standards and distribution channel access, producing a tiered structure where multinational scale advantages confront local heritage positioning. The vendor base stratifies between premium biodynamic specialists, mass-market Ayurvedic heritage brands, and clean-label digital natives. Three archetypes dominate: vertically integrated cultivator-processors, science-marketing hybrids leveraging botanical research networks, and direct-to-consumer subscription operators. Capacity expansion in certified organic extraction and strategic partnerships for rare plant supply security represent the dominant competitive moves.
Within the science-marketing hybrid tier, L'Oreal SA and Weleda AG exemplify divergent approaches to botanical credibility—L'Oreal anchoring global research infrastructure, Weleda occupying biodynamic certification leadership. Among India-based heritage operators, Patanjali Ayurved Ltd. and Dabur Ltd. represent contrasting scale strategies, with Patanjali emphasizing domestic vertical integration and Dabur leveraging established export networks. Himalaya Global Holdings Ltd. sits within the pharmacy-channel specialist archetype, bridging Ayurvedic tradition with clinical positioning in regulated European markets.
| Leading Market Players |
|---|
| Marico Limited |
| L'Oreal SA |
| Procter & Gamble Company |
| Groupe Rocher |
| Patanjali Ayurved Ltd. |
| Himalaya Global Holdings Ltd. |
| Weleda AG |
| Emami Ltd. |
| Dabur Ltd. |
| Others |
Supply Flow & Price Mechanics
Sandalwood oil spot prices in Karnataka auction yards cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for non-certified formulators while biodynamic-certified producers in Germany capture pharmacy channel premiums. REACH compliance costs and EU Green Deal traceability requirements amplify this bifurcation, forcing mid-tier manufacturers toward either volume-scale standardization or provenance-verified specialization.
Pricing Analysis
Input-cost pass-through from wild-harvested Himalayan herbs and Western Ghats botanicals operates through contract-based long-term offtake agreements for certified organic grades, while spot procurement serves commodity-tier manufacturers. Price differentiation rests on biodynamic certification level and volume scale, with Demeter-certified products commanding shelf premiums in German pharmacy channels. Pricing pressure stems from provenance verification documentation burdens adding procurement overhead. Mass-market supermarket buyers exhibit highest price sensitivity, while eco-conscious direct-to-consumer subscribers accept premium positioning for supply chain transparency.
Supply Chain Analysis
Regional distribution centers in Mumbai, Hamburg, and Los Angeles anchor hub-and-spoke patterns for finished goods, while raw material concentration spans India, Germany, and France. Supply chains draw from contract cultivation in Madhya Pradesh, biodynamic farms in Baden-Württemberg, and essential oil cooperatives in Provence. Single-source vulnerability persists for rare botanicals dependent on climate-dependent harvest cycles. Distribution runs through specialty pharmacy channels for certified premium tiers and direct-to-consumer platforms for millennial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as millennial and Generation Z purchasers displace brand heritage with ingredient provenance research as the dominant purchase determinant.
For Market Incumbents: Acquire captive extraction infrastructure in BIS-certified Madhya Pradesh and Karnataka processing zones to secure supply continuity against climate-dependent harvest volatility. Deepen backward integration into contract cultivation arrangements with documented chain-of-custody to satisfy EU Green Deal deforestation-free mandates. Patent standardized botanical actives to defend formulation portfolios against bioreactor-cultivated stem cell substitutes. For New Entrants and Emerging Players: Begin with scalp microbiome haircare formulations targeting European pharmacy channels, where synthetic surfactant displacement creates white-space opportunity among dermatologically sensitive consumers. Exploit underpenetrated direct-to-consumer subscription models in the United States, where supply chain mapping integration differentiates digital-native brands. Pursue Natrue certification as the go-to-market anchor for German market access. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated cultivator-processors combining biodynamic certification with captive supercritical CO2 extraction capabilities. Long-term viability favors operators with deforestation-free compliance systems already deployed across Indian and African raw material sourcing bases. Monitor bioreactor cultivation cost curves as the inflection signal for traditional wild-harvesting economics compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Demeter and Natrue standards unlock 30-40% pharmacy channel premiums in Germany. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture bypasses retail markups while serving millennial transparency expectations. |
| Backward Integration into Cultivation | Contract farming in Madhya Pradesh secures CDSCO-compliant traceability for EU export eligibility. |
| Bioreactor Stem Cell Adoption | Climate-independent production of rare botanicals insulates supply against harvest volatility. |
| EU Green Deal Compliance System | Deforestation-free documentation preserves market access as traceability mandates tighten. |
Methodological Framework
Bottom-up end-use consumption modeling reconciled against top-down supply-side capacity tracking forms the analytical core of this study. Primary interviews with Ayurvedic processing facility managers, pharmacy category buyers in Germany, clean beauty brand managers, and CDSCO regulatory affairs specialists combined with secondary validation from BIS certification databases, EU ECHA REACH filings, and customs trade records. Cross-referencing of PLI scheme beneficiary disclosures against Madhya Pradesh and Karnataka state industrial development data enabled triangulation of certified capacity expansion.
Historical trendline analysis of cold-press and supercritical CO2 extraction infrastructure deployment informed projection modeling across the analysis window. Segmentation dimensions span product type, ingredient source, certification tier, and distribution channel, with CAGRs derived from regression against millennial demographic penetration rates and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal implementation timelines and India's PLI scheme disbursement patterns.
Several conditions sit outside the modeled scope, including unforeseen botanical allergen restrictions under REACH Annex III amendments and abrupt climate events affecting Western Ghats harvest yields. Forecasts reflect documented assumptions around sustained millennial preference for clean-label transparency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Beauty Fridge Market