
 Italy Beauty and Personal Care Products Market | 2026-2036
Italy Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Beauty and Personal Care Products Market Foresight
The capital-intensity divergence between mass-market manufacturers and prestige houses is redrawing competitive boundaries in Italy. L'Oréal S.A. leverages integrated R&D centers near Clichy to sustain rapid product iteration for Southern European palettes. Coty Inc. anchors its fragrance dominance through licensed luxury portfolios distributed via Italian airport retail and city-center flagships. Kenvue Inc. competes on pharmacy-channel depth, where Johnson & Johnson Inc. legacy brands control shelf positioning through decades of clinician endorsement.
Beauty and personal care products encompass chemically formulated or naturally derived substances applied to skin, hair, or body for cleansing, protection, or aesthetic enhancement, typically requiring stability testing at 40°C/75% relative humidity to verify shelf integrity. Their primary commercial purpose centers on consumer self-care rituals and appearance management across daily grooming routines. Skincare commands margin concentration due to serum and active-ingredient premiumization, while fragrance depends on Italian contract perfumery expertise in Grasse-supplied compositions. Specialty stores retain experiential loyalty through diagnostic consultations, though online channels capture trial-driven replenishment cycles among digitally native subgroups.
Italy's national health ministry enforces EU Cosmetics Regulation compliance through pre-market notification portals and banned-substance lists updated by the Scientific Committee on Consumer Safety. The EU Green Deal and CSRD reporting obligations pressure manufacturers to document supply-chain carbon intensity and packaging recyclability percentages. REACH chemical registration requirements further constrain raw-material sourcing flexibility for colorants and preservatives. Stakeholders must monitor pending EU microplastic restrictions in rinse-off products, which threaten formulation architectures across exfoliating and styling segments.
Market Dynamics
Reformulation mandates under EU Cosmetics Regulation (EC) No 1223/2009 are forcing domestic manufacturers to rebuild supply chains around banned-substance compliance and clean-label transparency, redrawing competitive boundaries between capital-heavy prestige houses and agile contract manufacturers.
Growth Catalysts
- Clean-label chemistry:Italian millennials and Gen Z consumers are accelerating demand for transparent ingredient sourcing, pushing domestic brands to invest in natural-derived actives and microbiome-friendly formulations.
- EU Green Deal alignment:Carbon-intensity documentation and packaging recyclability mandates under CSRD reporting obligations are creating first-mover advantages for manufacturers with verified circular supply chains.
- Northern industrial clustering:Concentrated contract manufacturing and indie brand incubation around Milan and Bologna generate knowledge spillovers and reduce formulation-to-shelf cycle times.
Market Restraints
- REACH chemical registration:Raw-material sourcing flexibility for colorants and preservatives faces structural constraints from ECHA compliance timelines and restricted substance candidate lists.
- Grasse supply concentration:Fragrance composition expertise remains geographically locked to southeastern France, exposing Italian houses to input cost volatility and limited perfumer mobility.
- Microplastic formulation risk:Pending EU restrictions on rinse-off microplastics threaten exfoliating and styling product architectures, requiring costly base-rebuild investments.
Strategic Opportunities
- Pharmacy channel deepening:Clinician-endorsed positioning in Lombardy and Veneto retail networks offers margin protection against price-pressured mass-market competition.
- Airport retail expansion:Licensed luxury fragrance portfolios capture high-spending transit consumers through duty-advantaged pricing and exclusive travel-retail SKUs.
- Biotechnology convergence:Fermentation-derived actives and precision fermentation platforms enable novel peptide and postbiotic ingredient claims with differentiated regulatory pathways.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in stability testing at 40°C/75% relative humidity and EU safety assessment protocols concentrates among aging technical workforces in Emilia-Romagna.
- Legacy system integration:Pre-market notification portal compliance and supply-chain carbon accounting require ERP upgrades that strain mid-cap manufacturer IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Beauty and Personal Care Products Market |
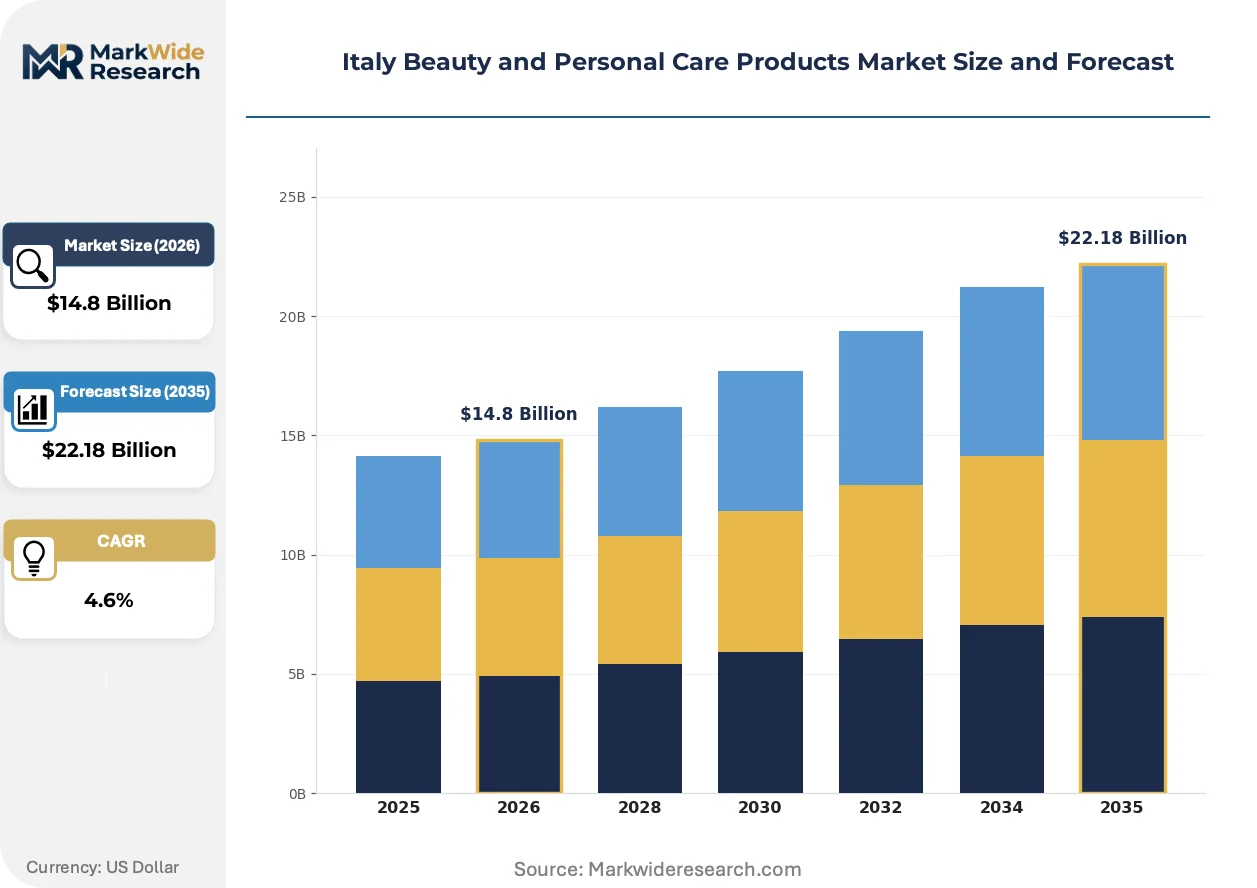
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores End User: Women, Men, Unisex, Teenagers Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Beiersdorf AG, Colgate-Palmolive Company Limited, L'Oréal S.A., Coty Inc., Johnson & Johnson Inc., Procter & Gamble Company, The Estée Lauder Companies Inc., Kenvue Inc., Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Beauty and Personal Care Products Market Shifts & Advancements
Biotechnology-derived actives and digital diagnostic retail formats are compressing traditional formulation-development cycles while elevating consumer expectations for personalized efficacy claims.
Precision fermentation for ceramide and peptide production is supplanting petrochemical-derived emollients in premium skincare lines. Northern Italian indie brands and contract manufacturers are adopting these platforms within eighteen-month innovation windows. This shift is compressing R&D timelines for active-ingredient premiumization while raising barriers for formulators without biotech partnerships.
EU Cosmetics Regulation pre-market notification portals and Scientific Committee on Consumer Safety banned-substance list updates are tightening ingredient approval pathways. Domestic manufacturers face compressed formulation windows as safety assessment documentation requirements expand. Fragrance and colorant segments bear the heaviest compliance burden, accelerating partnerships with toxicology consultancies in Milan.
Diagnostic skin-analysis consultations in specialty stores are displacing self-directed trial-and-repeat purchasing among digitally native subgroups. Online channels now capture replenishment cycles while flagship locations retain acquisition and education functions. This bifurcation is most visible in metropolitan Milan and Rome, where experiential loyalty competes with subscription-model convenience.
Italy Beauty and Personal Care Products Market Segmentation
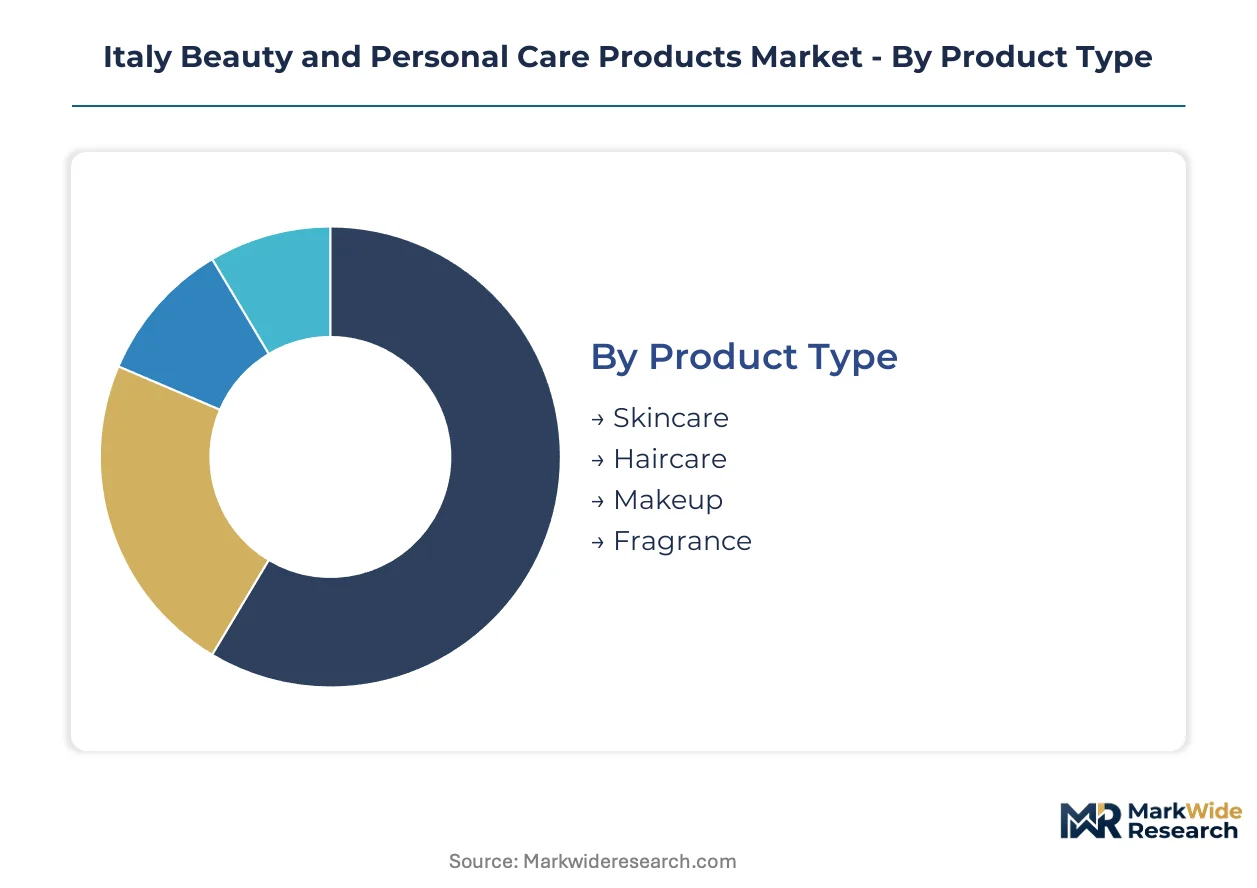
Segmentation in Italy's beauty and personal care market reveals how regulatory pressure and channel specialization create distinct competitive arenas. Manufacturers must align formulation investments with distribution-specific compliance requirements and consumer price sensitivity thresholds.
Product Type:
EU Cosmetics Regulation (EC) No 1223/2009 applies differential safety assessment intensity across product categories, with leave-on skincare facing stricter documentation than rinse-off alternatives.
- Skincare:Serum and active-ingredient formulations dominate margin concentration, with ceramide and peptide premiumization accelerating in Lombardy incubation clusters. Northern Italian contract manufacturers prioritize stability testing at 40°C/75% relative humidity for these high-value lines.
- Fragrance:Licensed luxury portfolios depend on Grasse-supplied compositions, exposing Italian houses to input cost volatility from southeastern France concentration. Airport retail and city-center flagships capture transit-driven replenishment cycles.
- Haircare:Microbiome-friendly shampoo and conditioner formulations gain traction among millennial consumers in Milan and Bologna metropolitan zones.
- Makeup:Colorant segments bear heavy REACH compliance burdens, accelerating toxicology consultancy partnerships in Emilia-Romagna.
Established volume favors Fragrance; emerging adoption favors Skincare.
Distribution Channel:
Channel selection dictates margin architecture and regulatory exposure, with pharmacy networks offering clinician-endorsed positioning against price-pressured mass-market alternatives.
- Pharmacies:Johnson & Johnson legacy brands control shelf positioning through decades of clinician endorsement in Lombardy and Veneto retail networks, protecting margin structures against supermarket competition.
- Specialty Stores:Diagnostic skin-analysis consultations in metropolitan Milan and Rome locations displace self-directed trial-and-repeat purchasing among digitally native subgroups.
- Online:Subscription-model convenience captures replenishment cycles, though acquisition and education functions remain concentrated in flagship locations.
- Supermarkets:Price-pressured mass-market competition dominates volume throughput for basic hygiene and grooming essentials.
Margin protection concentrates in Pharmacies; volume scale concentrates in Supermarkets.
End User:
Generational and gender-based demand fragmentation requires distinct formulation architectures and marketing investment profiles across Italian consumer segments.
- Women:Multi-step skincare rituals and fragrance layering drive the highest per-capita spending, with clean-label transparency demands accelerating among Gen Z cohorts in northern industrial clusters.
- Unisex:Gender-neutral fragrance and skincare lines expand most quickly, capturing cross-demographic trial through minimalist positioning and shared household purchasing.
- Men:Grooming category extension beyond basic hygiene remains underdeveloped relative to Northern European benchmarks, presenting white-space opportunity.
- Teenagers:Social media-influenced trial behavior concentrates in online channels, with influencer-endorsed indie brands capturing initial category entry.
Spending intensity favors Women; demographic expansion favors Unisex.
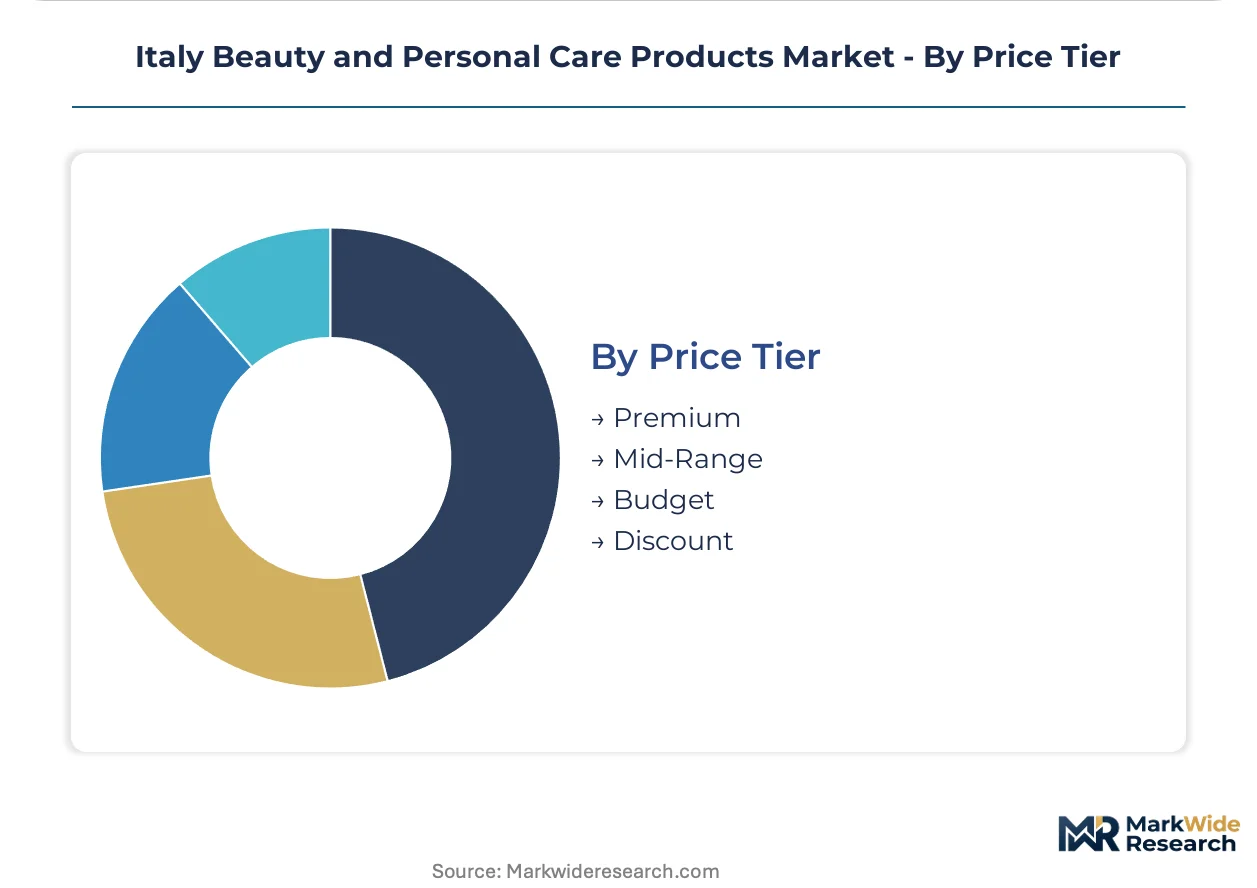
Price Tier:
Three-tier pricing structure across premium, standard, and economy levels reflects supply chain configuration and certification-grade differentiation rather than simple ingredient cost stacking.
- Premium:Biotechnology-derived actives from precision fermentation platforms command formulation premiums, with circular supply chain verification under CSRD reporting obligations creating first-mover advantages.
- Mid-Range:Domestic indie brands and contract manufacturers compress R&D timelines through Milan-Bologna knowledge spillovers, occupying the contested center of retail shelf positioning.
- Budget:Mass-market manufacturers face capital-intensity divergence against prestige houses, with reformulation investments for EU Cosmetics Regulation compliance straining mid-tier margin structures.
- Discount:Price-driven volume competes primarily through promotional intensity and retailer-owned label penetration in supermarket channels.
Margin sustainability favors Premium; volume throughput favors Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Italian metropolitan zones consume premium skincare and fragrance at intensities unmatched by southern regions, where pharmacy-channel basic hygiene dominates purchasing patterns.
Lombardy
Milan anchors Italy's highest per-capita beauty spending, with Gen Z consumers driving clean-label serum demand through specialty-store diagnostic consultations. EU Cosmetics Regulation (EC) No 1223/2009 compliance costs concentrate here, as domestic brands navigate pre-market notification portals. The Milan-Bologna industrial corridor incubates indie brands leveraging precision fermentation platforms for peptide production.
Veneto
Pharmacy-channel depth in Verona and Padua sustains clinician-endorsed positioning for dermocosmetic lines, protecting margin structures against supermarket price pressure. Italy's national health ministry enforces banned-substance list updates through regional inspectorates. Venice metropolitan retail networks capture tourism-driven fragrance replenishment cycles, particularly for licensed luxury portfolios.
Emilia-Romagna
Bologna hosts the densest concentration of contract manufacturers serving European indie brands, with formulation chemist expertise concentrating in aging technical workforces. REACH chemical registration requirements constrain raw-material sourcing flexibility for colorants produced in regional plants. Stability testing at 40°C/75% relative humidity facilities cluster along the Via Emilia manufacturing belt.
Piedmont
Turin's heritage fragrance houses maintain Grasse-supplied composition relationships, exposing operations to southeastern France input cost volatility. The EU Green Deal pressures manufacturers to document supply-chain carbon intensity for CSRD reporting obligations. Regional perfumery expertise concentrates in family-owned laboratories with limited mobility to northern industrial clusters.
Lazio
Rome specialty stores compete with Milan for experiential loyalty through flagship skin-analysis consultations, though online channels capture replenishment cycles among digitally native subgroups. Pending EU microplastic restrictions threaten exfoliating product architectures distributed through capital-region retail networks. Airport retail expansion at Fiumicino captures transit-driven duty-advantaged fragrance purchasing.
Italy Beauty and Personal Care Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with prestige houses commanding biotechnology R&D partnerships while agile contract manufacturers compress formulation-to-shelf timelines. The structure rewards capital-heavy compliance investments for EU Cosmetics Regulation documentation and penalizes mid-cap players lacking ERP upgrades for carbon accounting. Three archetypes dominate: integrated multinational houses with captive perfumery relationships, pharmacy-channel specialists leveraging clinician endorsement, and indie incubators exploiting Milan-Bologna knowledge spillovers. Competitive moves center on M&A for biotech platform access and strategic partnerships with northern Italian contract manufacturers.
Within the integrated multinational tier, L'Oréal S.A. and Coty Inc. exemplify divergent positioning archetypes, with the former representing rapid product iteration capabilities and the latter anchoring licensed luxury fragrance dominance through airport retail channels. Kenvue Inc. occupies a position within the pharmacy-channel specialist archetype, leveraging Johnson & Johnson Inc. legacy brand equity for clinician-endorsed shelf positioning in Lombardy and Veneto networks.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Colgate-Palmolive Company Limited |
| L'Oréal S.A. |
| Coty Inc. |
| Johnson & Johnson Inc. |
| Procter & Gamble Company |
| The Estée Lauder Companies Inc. |
| Kenvue Inc. |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Precision fermentation-derived ceramides replacing petrochemical emollients simultaneously redraws raw-material sourcing geography toward northern Italian biotech clusters and compresses premium-tier pricing power through shortened innovation cycles.
Pricing Analysis
Contract structures favor project-based formulation partnerships between indie brands and Milan-Bologna contract manufacturers over long-term offtake agreements. Price differentiation rests on CSRD-verified circular supply chains and EU Cosmetics Regulation safety documentation depth. Pricing pressure intensifies in mid-range tiers as REACH compliance costs accumulate without offsetting brand premium. Mass-market supermarket buyers exhibit highest price sensitivity; prestige pharmacy and airport retail segments sustain margin insulation through clinician endorsement and duty-advantaged positioning.
Supply Chain Analysis
Inventory strategies favor just-in-time active-ingredient procurement from French and Swiss suppliers over strategic stockpiling of volatile fragrance compositions. Geographic supply concentration centers on Grasse for perfumery, northern Italy for formulation, and Germany for packaging equipment. Raw material dependencies encompass southeastern France fragrance compositions, REACH-registered colorants, and fermentation-derived peptides. Single-source vulnerability pervades Grasse-sourced luxury fragrance bases. Distribution runs through pharmacy networks for dermocosmetics and specialty retail for experiential skincare acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-model replenishment services for serum and active-ingredient lines expand faster than one-time hardware purchases, transforming unit economics toward recurring revenue attachment.
For Market Incumbents: Compound pharmacy-channel depth through clinician endorsement programs in Lombardy and Veneto to offset mass-market price erosion. Deepen backward integration into precision fermentation platforms for peptide production. Accelerate ERP upgrades for CSRD carbon-accounting compliance before regulatory deadlines tighten.
For New Entrants and Emerging Players: EU Cosmetics Regulation pre-market notification fast-tracks through Milan toxicology consultancies enable rapid clean-label serum launches. Target underpenetrated men's grooming segments in metropolitan Rome and Turin. Deploy influencer-native digital acquisition for Gen Z trial conversion before specialty-store flagship expansion.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotech-platform acquirers over pure-brand aggregators. Five-to-ten-year viability hinges on fermentation-derived active pipelines and verified circular supply chains. Target contract manufacturers with captive formulation chemist expertise in Emilia-Romagna. Monitor EU microplastic restriction implementation timelines as margin inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Acquisition | Fermentation-derived ceramide production secures differentiated active-ingredient sourcing from northern Italian biotech clusters. |
| Pharmacy Channel Expansion | Clinician-endorsed positioning in Lombardy and Veneto retail networks protects margin structures against supermarket competition. |
| CSRD Compliance Investment | Carbon-intensity documentation and packaging recyclability verification creates first-mover advantage under EU Green Deal mandates. |
| Airport Retail SKU Development | Exclusive travel-retail fragrance formats capture high-spending transit consumers through duty-advantaged pricing at Fiumicino and Malpensa. |
| Diagnostic Consultation Format Rollout | Skin-analysis flagship experiences in Milan and Rome specialty stores displace self-directed trial among digitally native subgroups. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Cosmetics Regulation pre-market notification databases, REACH chemical registration filings, and CSRD sustainability disclosure repositories. Interviews with formulation chemists in Emilia-Romagna, pharmacy category buyers in Lombardy, airport retail procurement managers, and contract manufacturing executives informed demand-side validation. Bottom-up product-type and channel segmentation triangulates against top-down national health ministry market sizing and trade association production data.
Segmentation dimensions modeled encompass product type, distribution channel, generational end-user cohort, and price tier across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory phase-in schedules and channel-shift elasticity parameters. Forecast inputs incorporate REACH compliance cost pass-through rates and precision fermentation platform adoption curves in northern Italian manufacturing clusters.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Cosmetics Regulation enforcement intensity and stable Grasse fragrance supply; material deviation would warrant model refresh. Revision becomes warranted when EU microplastic restriction implementation crosses enforcement thresholds or when biotechnology platform partnerships achieve scale inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Hair Removal Wax Warmer Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
North America Setting Spray Market