
 Slimming Cream Market | 2026-2036
Slimming Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Slimming Cream Market Analysis
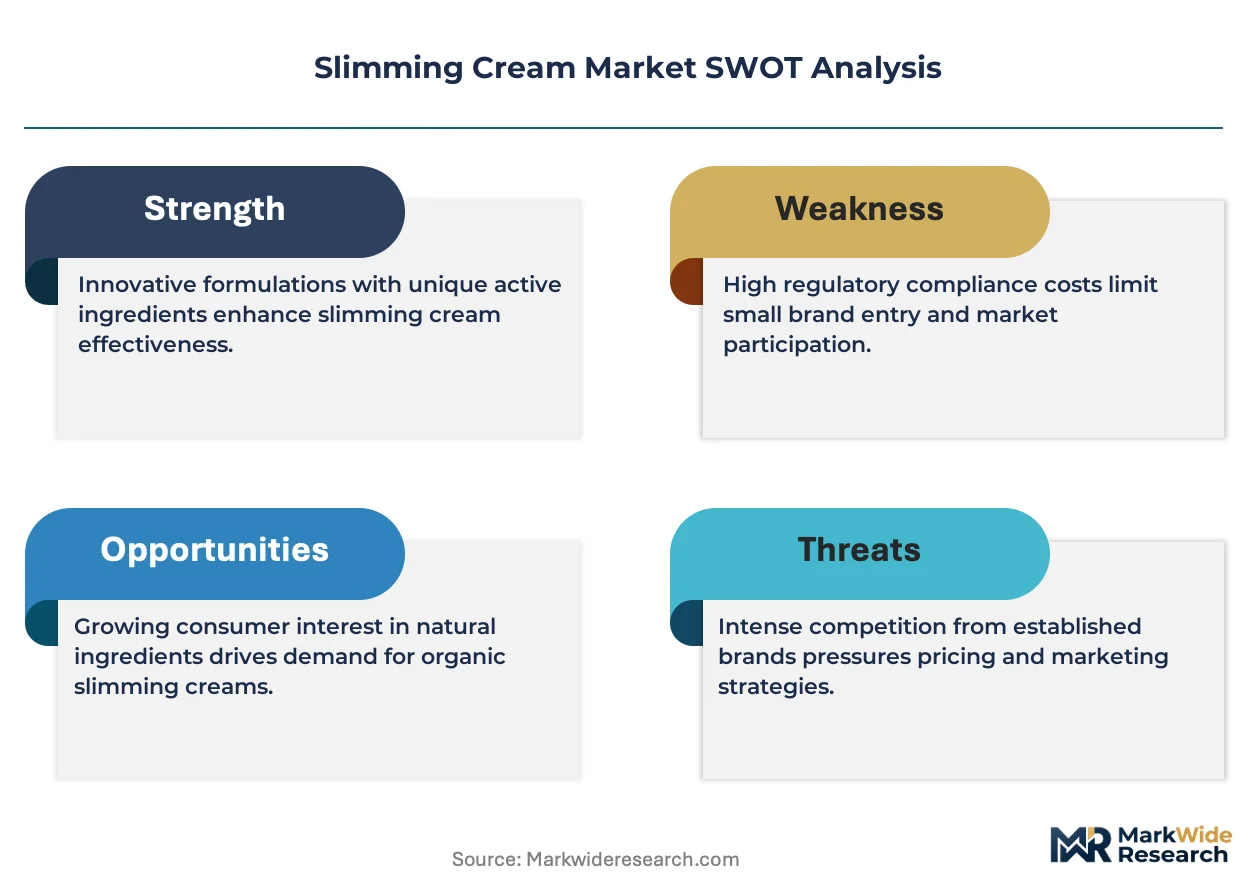
Natural emulsifiers and cold-pressed botanical oils is restructuring cost structures across the Slimming Cream Market, displacing petroleum-derived bases that once dominated mass-production lines. L'Oréal leverages captive sourcing of shea derivatives from West African cooperatives to secure margin stability. Beiersdorf anchors its European manufacturing footprint with certified organic supply chains for Nivea-branded body-contour lines. Shiseido Company competes through fermentation-derived adipose-targeting compounds developed at its Yokohama research center.
Slimming creams are topical cosmetic formulations containing lipolytic actives, penetration enhancers, and firming polymers designed to reduce subcutaneous fat appearance and improve skin elasticity through transdermal delivery mechanisms. The products primarily serve consumer aesthetics markets, bridging dermatology and over-the-counter beauty sectors with claims centered on circumference reduction and dermal texture improvement. Ingredient Type segmentation shows caffeine and green tea extract commanding the largest volume share due to established clinical visibility around lipolysis stimulation, while retinol-based variants capture premium pricing through collagen-remodeling positioning. Application segmentation reveals cellulite reduction as the most mature functional claim, whereas stretch mark prevention exhibits faster growth velocity among postpartum and weight-fluctuation demographics.
The US FDA exercises oversight through cosmetic labeling requirements and strict prohibition of drug-like efficacy claims without NDAs, while the EU ECHA enforces REACH restrictions on synthetic preservatives that force reformulation cycles across export portfolios. China's NMPA and SAMR mandate animal-testing alternatives for imported cosmetics, reshaping how international brands validate new slimming actives for Asian market entry. Stakeholders must monitor evolving cross-jurisdictional ingredient blacklists and pre-market notification timelines to avoid stranded inventory in key retail channels.
Market Dynamics
Plant-based emulsifier substitution is compressing petroleum-derived input costs while EU REACH disclosure mandates force rapid reformulation cycles across export portfolios. This dual pressure reshapes competitive positioning between legacy chemical suppliers and botanical ingredient networks.
Growth Catalysts
- Fitness Enthusiast Integration:Body-sculpting regimens now incorporate topical solutions as daily routine components, expanding addressable demand beyond traditional cosmetic buyers.
- REACH Framework Compliance:The EU Cosmetics Regulation tightens ingredient disclosure requirements, accelerating brand migration toward certifiable plant-based actives with traceable supply chains.
- Brazilian Pharmacy Channel Penetration:Aesthetic culture concentration sustains category momentum through established dermo-cosmetic retail infrastructure.
Market Restraints
- Cold-Pressed Botanical Oil Volatility:Shea and specialty oil harvest fluctuations in West African sourcing regions create margin compression during poor crop cycles.
- Synthetic Preservative Restrictions:ECHA enforcement of REACH limitations on paraben alternatives forces costly reformulation without equivalent shelf-life performance.
- Clinical Validation Barriers:FDA prohibition of drug-like efficacy claims without NDAs restricts marketing language and consumer education effectiveness.
Strategic Opportunities
- Postpartum Stretch Mark Positioning:Weight-fluctuation demographics demonstrate faster adoption velocity than mature cellulite reduction segments.
- Fermentation-Derived Actives:Biotechnology convergence with adipose-targeting compounds enables novel lipolytic mechanisms distinct from caffeine-based formulations.
- China NMPA Alternative Testing:Animal-testing waiver pathways for imported cosmetics accelerate Asian market entry timelines for reformulated SKUs.
Industry Challenges
- Cross-Jurisdictional Blacklist Monitoring:Stakeholders must track evolving ingredient prohibitions across FDA, ECHA, and SAMR regimes to prevent stranded inventory.
- Pre-Market Notification Compression:Shortened validation timelines in multiple geographies strain regulatory affairs capacity without proportional staff expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slimming Cream Market |
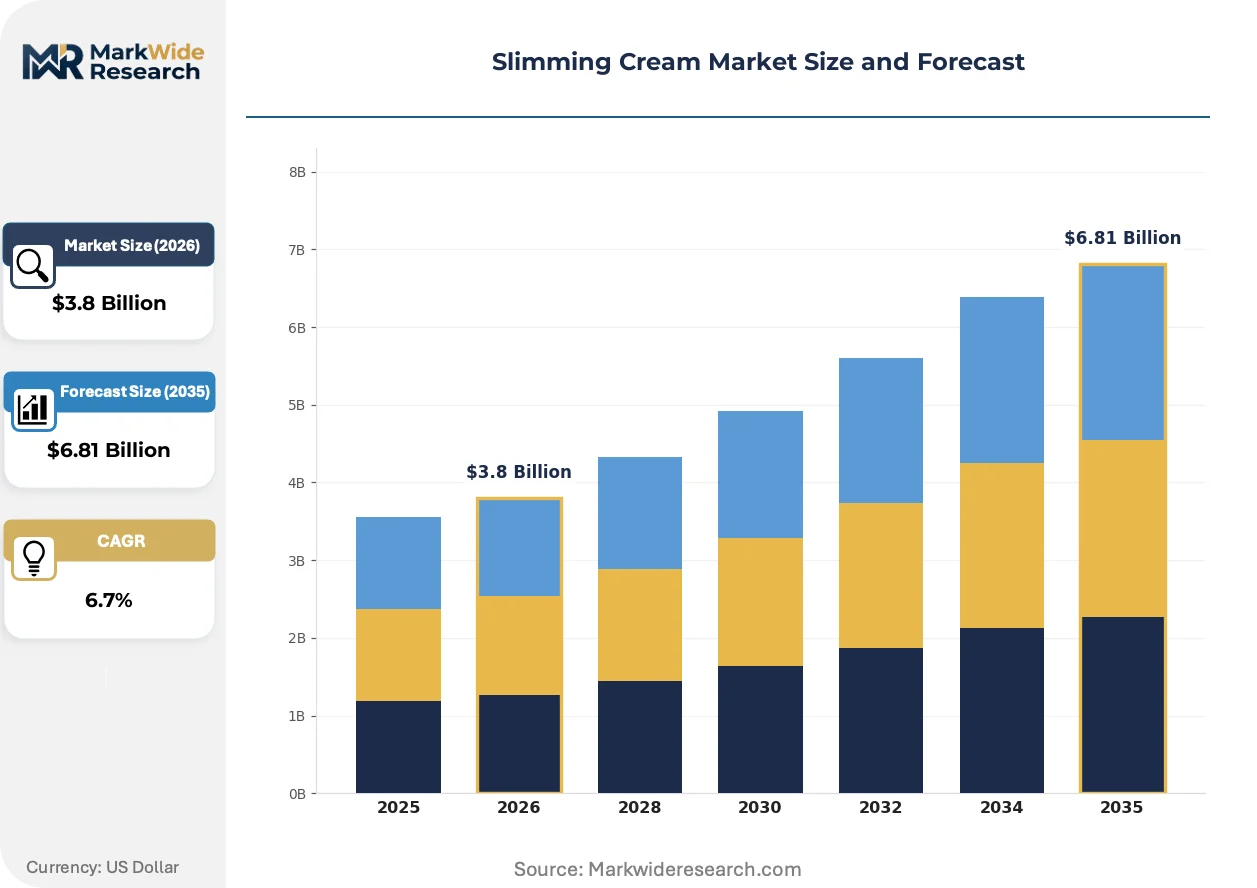
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Body Firming, Skin Tightening, Cellulite Reduction, Stretch Mark Prevention Ingredient Type: Caffeine, Green Tea Extract, Retinol, Aloe Vera End User: Women, Men, Fitness Enthusiasts, Aging Population Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | L'Oréal, Beiersdorf, Unilever, Clarins Group, Mary Kay Inc, Shiseido Company, Estée Lauder Companies, Procter & Gamble, Amorepacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slimming Cream Market Emerging Trajectories
Biotechnology integration with traditional cosmetic chemistry is restructuring how lipolytic actives reach subcutaneous tissue. These convergences compress development cycles while raising technical barriers for non-specialized competitors.
Encapsulation technology using liposomal delivery systems is converging with transdermal penetration research to enhance caffeine and green tea extract bioavailability. Dermatology clinics and medi-spa channels adopt these advanced formulations at accelerated rates. The convergence is compressing efficacy timelines and forcing mass-market brands toward ingredient transparency claims.
China's NMPA and SAMR now mandate animal-testing alternatives for all imported cosmetic registrations, including slimming cream categories. This regulatory shift requires brands to validate new actives through reconstructed human epidermis models or OECD-accepted in-vitro protocols. Asian market entry strategies are restructuring around Shanghai-based testing partnerships and accelerated safety dossier preparation.
Subscription-based replenishment models are displacing traditional pharmacy and department store purchasing for body-contour products. Direct-to-consumer channels capture postpartum and fitness-enthusiast segments with personalized regimen bundling. Brazil and South Korea demonstrate the strongest channel migration velocity, where mobile-first beauty commerce already dominates skincare categories.
Slimming Cream Market Segmentation
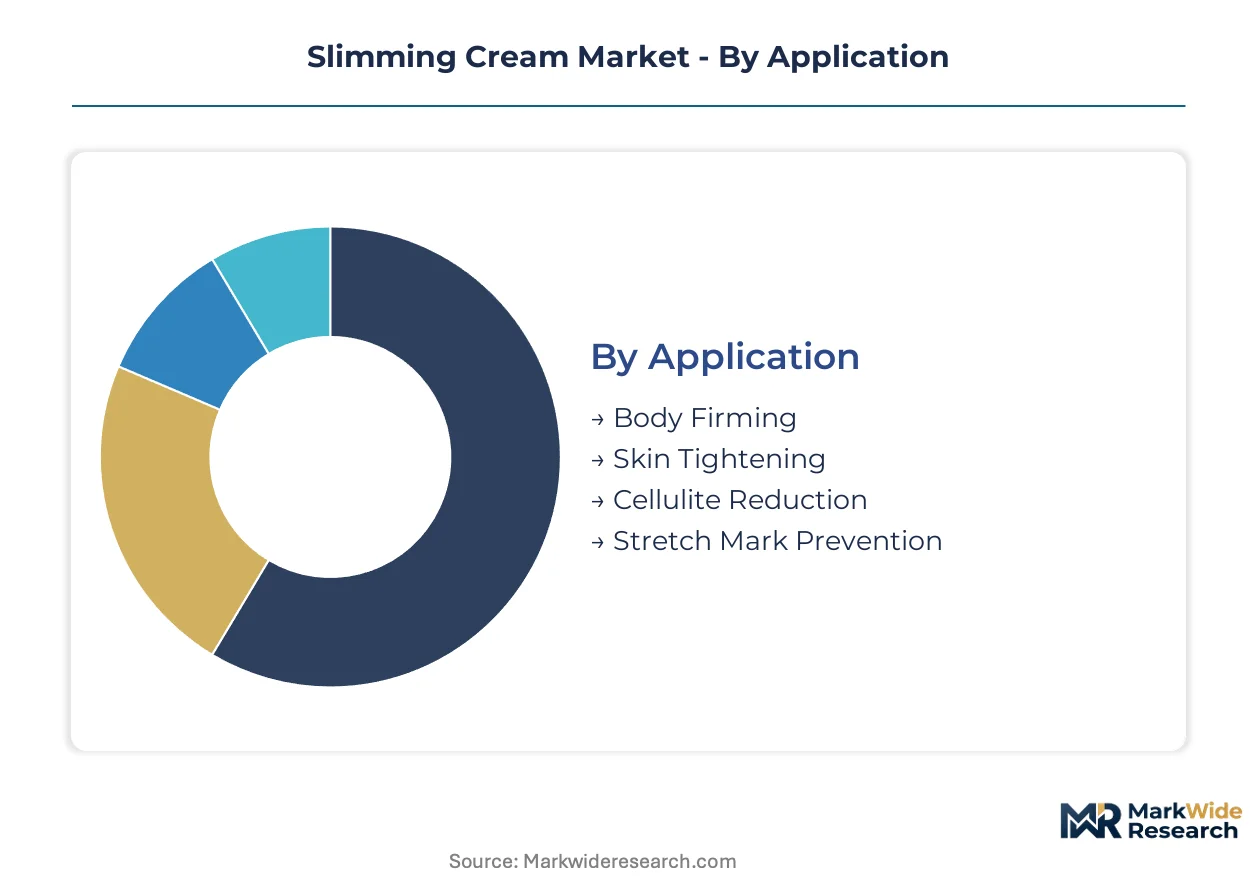
Slimming cream segmentation reveals how formulation chemistry, consumer physiology, and channel infrastructure intersect to create distinct value propositions. Manufacturers align R&D investment with the highest-margin application clusters while navigating divergent regulatory thresholds across distribution pathways.
Application:
Functional claims determine both clinical validation requirements and permissible marketing language in major jurisdictions.
- Cellulite Reduction:Maturest claim category with established lipolytic testing protocols. Demand concentrates in Brazil and Mediterranean markets where dermo-cosmetic pharmacy channels sustain premium positioning despite saturated competitive density.
- Stretch Mark Prevention:Postpartum and weight-fluctuation demographics drive adoption velocity faster than legacy cellulite segments. North American direct-to-consumer brands leverage subscription bundling to capture repeat purchase cycles in this emerging functional space.
- Body Firming:Polymer-based tightening actives target aging skin elasticity degradation.
- Skin Tightening:Collagen-stimulating formulations compete with minimally invasive aesthetic procedures.
Cellulite Reduction leads on scale; Stretch Mark Prevention leads on momentum.
Ingredient Type:
Raw material sourcing geography and extraction method determine margin stability across formulation portfolios.
- Caffeine:Synthetic and natural variants command volume leadership through proven lipolysis stimulation mechanisms. Brazilian pharmacy-channel penetration sustains category dominance despite commodity price volatility in green coffee bean supply chains.
- Retinol:Premium pricing reflects collagen-remodeling dermatological positioning and stability challenges requiring sophisticated encapsulation technology. Japanese fermentation-derived alternatives are gaining formulation share in Asian export portfolios.
- Green Tea Extract:Polyphenol standardization drives sourcing concentration in Chinese and Japanese tea-growing regions.
- Aloe Vera:Cold-pressed gel formulations serve sensitive-skin positioning in Middle Eastern and North African markets.
Caffeine leads on scale; Retinol leads on momentum.
End User:
Physiological differences and routine integration patterns reshape product format and messaging requirements.
- Fitness Enthusiasts:Fastest-expanding segment as body-sculpting regimens integrate topical solutions into daily post-workout protocols. European gym-channel partnerships and Asian fitness-app commerce integrations accelerate adoption beyond traditional cosmetic buyers.
- Women:Historical category anchor with established pharmacy and department store purchasing patterns.
- Men:Emerging segment targeted through simplified packaging and performance-oriented claims in urban Asian markets.
- Aging Population:Skin elasticity concerns drive demand in Japanese and Western European demographic clusters.
Women leads on scale; Fitness Enthusiasts leads on momentum.
Distribution Channel:
Channel selection determines regulatory compliance burden and consumer education depth requirements.
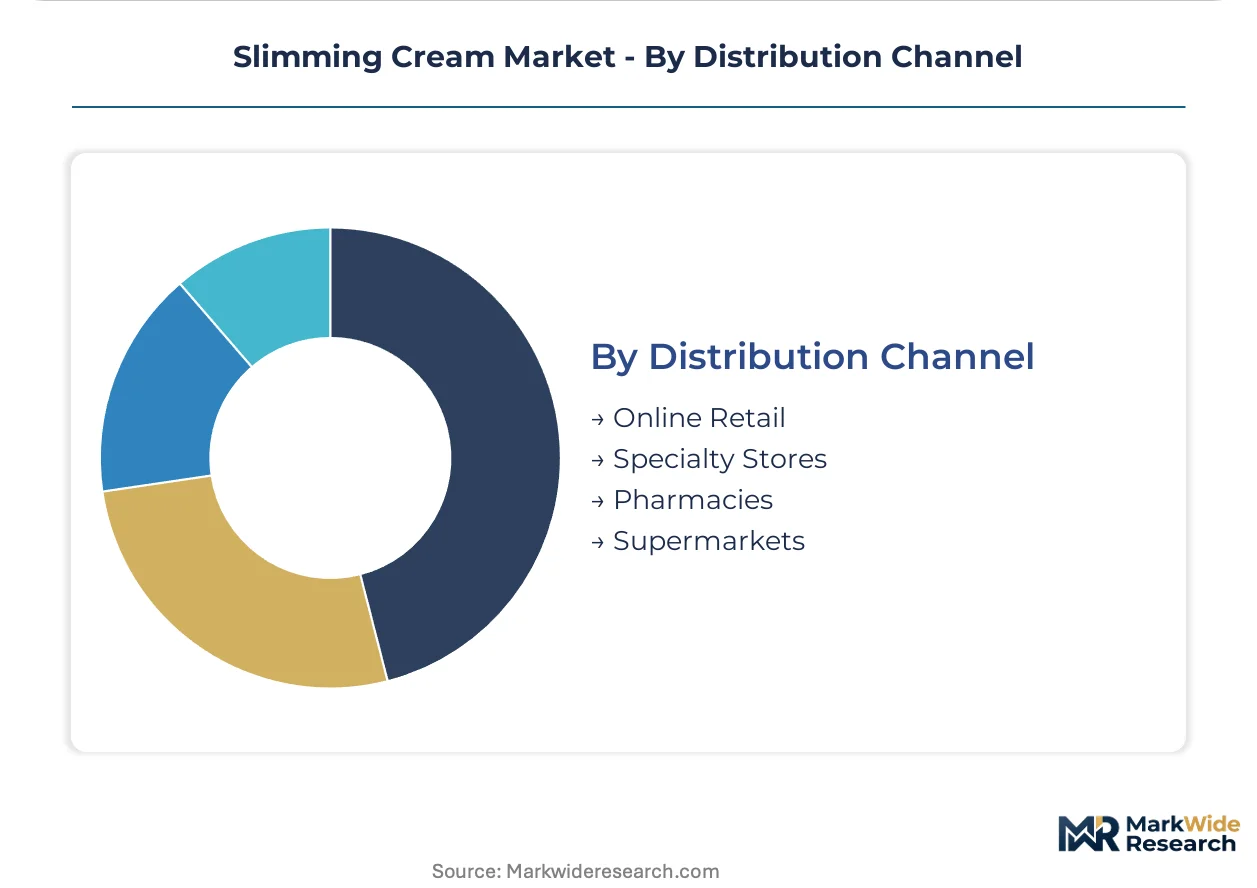
- Pharmacies:Dermo-cosmetic positioning enables clinical-adjacent claims in Brazilian and European markets where pharmacist consultation drives trial conversion. EU REACH disclosure mandates accelerate brand migration toward traceable supply chains to satisfy professional channel scrutiny.
- Online Retail:Subscription replenishment models displace traditional purchasing in South Korean and Brazilian mobile-first beauty commerce ecosystems. Direct-to-consumer bundling captures fitness-enthusiast and postpartum segments with personalized regimen algorithms.
- Specialty Stores:Premium positioning through sensory experience and trained consultation staff.
- Supermarkets:Mass-market penetration with simplified claims and price-competitive formulations.
Pharmacies leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian pharmacy networks anchor regional demand concentration for body-contour formulations, with São Paulo's dermo-cosmetic retail infrastructure sustaining category momentum through trained consultation channels.
United States
Fitness-enthusiast adoption and subscription replenishment models drive channel migration toward direct-to-consumer platforms. FDA cosmetic labeling requirements prohibit drug-like efficacy claims without NDAs, constraining marketing language. California's Silicon Valley beauty-tech clusters incubate personalized regimen algorithms for postpartum and weight-fluctuation demographics.
Brazil
Aesthetic culture penetration and established pharmacy-channel infrastructure sustain volume leadership in Latin America. ANVISA pharmaceutical regulations govern dermo-cosmetic positioning and professional consultation protocols. São Paulo's concentration of trained pharmacists drives trial conversion rates above mass-market retail benchmarks.
Germany
EU REACH disclosure mandates accelerate brand migration toward certifiable plant-based actives with traceable supply chains. ECHA enforcement of synthetic preservative restrictions forces reformulation cycles across export portfolios. Hamburg anchors Beiersdorf's European manufacturing footprint with certified organic supply chain integration.
China
NMPA and SAMR mandates for animal-testing alternatives reshape validation protocols for imported cosmetics. Shanghai-based testing partnerships accelerate safety dossier preparation for reconstructed human epidermis models. Yangtze River Delta biotechnology clusters develop fermentation-derived adipose-targeting compounds for Asian export portfolios.
Japan
Aging-population skin elasticity concerns and fermentation-derived active research drive premium formulation development. PMDA oversight ensures rigorous safety documentation for collagen-stimulating claims. Yokohama research centers anchor Shiseido's biotechnology convergence with traditional cosmetic chemistry.
Slimming Cream Market Vendor Landscape
Global majors compete with regional champions across formulation technology and channel access dimensions. The vendor base stratifies between consolidated multinational portfolios and specialized botanical ingredient networks. Three archetypes dominate: scale-driven mass-market brands with captive supply chains, premium dermatology-positioned specialists, and Asia-Pacific biotechnology convergents. Competitive moves concentrate on M&A for regional channel access and strategic partnerships for alternative testing validation.
Within the scale-driven tier, L'Oréal and Unilever occupy positions anchored by West African cooperative sourcing and mass-production line integration. Beiersdorf exemplifies the European certified-organic archetype with Hamburg-based manufacturing. Shiseido Company sits within the biotechnology-convergent segment, representing fermentation-derived active development from Yokohama research infrastructure. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across petroleum-displacement and plant-based formulation trajectories.
| Leading Market Players |
|---|
| L'Oréal |
| Beiersdorf |
| Unilever |
| Clarins Group |
| Mary Kay Inc |
| Shiseido Company |
| Estée Lauder Companies |
| Procter & Gamble |
| Amorepacific Corporation |
| Others |
Supply Flow & Price Mechanics
EU REACH disclosure mandates gate qualified supply access and premium-tier pricing power, forcing brands to absorb certification costs for traceable botanical actives or surrender margin to petroleum-based competitors locked out of pharmacy channels.
Pricing Analysis
Input-cost pass-through from shea and cold-pressed botanical oil volatility compresses mass-market margins while insulating premium retinol-based tiers. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived actives from commodity caffeine formulations from petroleum-based legacy lines. Pricing pressure stems from ECHA synthetic preservative restrictions forcing reformulation without equivalent shelf-life performance. Fitness enthusiasts demonstrate lowest price sensitivity through subscription bundling; supermarket buyers exhibit highest.
Supply Chain Analysis
Shea butter supply rests on West African cooperative networks in Ghana, Burkina Faso, and Mali, with green tea extract concentration in Chinese and Japanese tea-growing regions. Raw material dependencies include cold-pressed botanical oils, fermentation-derived adipose-targeting compounds, and liposomal encapsulation substrates. Single-source vulnerability in West African shea harvests creates margin compression during poor crop cycles. Distribution runs through Brazilian pharmacy networks, South Korean mobile commerce platforms, and North American direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slimming cream manufacturing arbitrage favors Asian biotechnology clusters over European REACH compliance costs, with Shanghai-based testing partnerships offering faster NMPA validation timelines against Hamburg's certified-organic supply chain premiums.
For Market Incumbents: Acquire fermentation-derived active portfolios to offset caffeine commodity volatility and ECHA reformulation cycles. Defend pharmacy-channel positioning in Brazil through ANVISA-compliant dermo-cosmetic consultation protocols. Lock West African cooperative sourcing contracts before harvest fluctuations intensify. For New Entrants and Emerging Players: Encapsulation technology convergence offers entry into medi-spa and dermatology clinic channels bypassing mass-market saturation. White-space concentrates in postpartum stretch mark prevention subscriptions and men's performance-oriented urban Asian markets. Launch through fitness-app commerce integrations with personalized regimen algorithms. For Investors and Strategic Acquirers: Roll-up economics work for Asia-Pacific biotechnology convergents because fermentation-derived active development raises technical barriers for non-specialized competitors. Five-to-ten year viability hinges on NMPA animal-testing alternative validation capacity. Watch China NMPA pre-market notification compression timelines as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Shea Cooperatives | L'Oréal's captive sourcing from Ghana secures margin stability against harvest volatility. |
| Fermentation-Derived Active Development | Shiseido's Yokohama research center enables novel lipolytic mechanisms distinct from caffeine. |
| Direct-to-Consumer Subscription Launch | South Korean mobile-first beauty commerce captures fitness-enthusiast repeat purchase cycles. |
| REACH-Compliant Reformulation Cycle | Beiersdorf's Hamburg manufacturing satisfies ECHA synthetic preservative restrictions. |
| NMPA Alternative Testing Partnership | Shanghai-based reconstructed human epidermis validation accelerates Asian market entry. |
Methodological Framework
Bottom-up fitness-enthusiast and postpartum demographic modeling reconciled against top-down botanical ingredient supply tracking forms the analytical core. Primary interviews with brand managers, category buyers at Brazilian pharmacies, supply planners at West African cooperatives, and regulatory affairs leads at NMPA testing partnerships combined with secondary validation from EU ECHA REACH filings, ANVISA dermo-cosmetic registrations, and South Korean mobile commerce transaction data.
Input-output matrix framing connects caffeine and retinol formulation chemistry to end-use adoption rates across cellulite reduction and stretch mark prevention applications. Segmentation dimensions include ingredient type, functional claim, end-user physiology, and distribution channel regulatory burden. CAGRs derive from penetration curve analysis and pricing elasticity modeling across pharmacy, online retail, and specialty store channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to West African shea harvest cycles, ECHA ingredient blacklist expansions, and NMPA pre-market notification timeline shifts. A small set of named triggers—fermentation-derived active clinical validation, China animal-testing waiver pathway maturation, and Brazilian pharmacy channel consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
Organic Liquid Soaps Market