
 At Home Hair Dye Market | 2026-2036
At Home Hair Dye Market Size, Share, and Industry Trends Forecast 2026-2036
At Home Hair Dye Market Analysis
South Korean contract manufacturers is realigning global supply for at-home colorant brands. L'Oréal Paris leverages its dermatological testing infrastructure to sustain premium positioning across European pharmacies. Henkel anchors Central European production capacity with dedicated ammonia-free lines. Godrej dominates South Asian distribution through dense general trade networks.
At-home hair dye denotes oxidative and non-oxidative colorant systems formulated for consumer self-application, typically containing dye intermediates such as p-phenylenediamine or henna-derived lawsone in cream, foam, or powder bases designed to alter hair melanin structure. Permanent color systems command the largest volume share due to gray coverage needs among aging populations, while vegan ingredient formulations represent the fastest-expanding margin pool as clean-label preferences intensify across North American and Western European retail channels.
FDA oversight of coal-tar hair dye exemptions and REACH restrictions on sensitizing aromatic amines jointly constrain formulation freedom across the Atlantic. The EU Green Deal chemical sustainability targets and state-level California Proposition 65 labeling requirements add compliance layers that favor reformulation investments by multinational suppliers. Stakeholders must monitor evolving hazard classifications for paraphenylenediamine derivatives and pre-position alternative dye precursor portfolios before regulatory thresholds tighten.
Market Dynamics
Ammonia-free chemistry migration is compressing legacy formulation margins while forcing capital redeployment toward plant-derived precursor synthesis. This structural pivot favors suppliers with captive biotech fermentation capacity and dermatological testing infrastructure.
Growth Catalysts
- REACH aromatic amine restrictions:EU regulatory pressure on sensitizing dye intermediates accelerates reformulation roadmaps and creates first-mover advantage for paraphenylenediamine-free portfolios.
- Gray coverage demand among working-age cohorts:Professional salon cost inflation drives permanent oxidative system adoption in the 35-54 age bracket across United States and German retail channels.
- Plant-derived pigment biotechnology:Microbial fermentation of lawsone analogues and indigo precursors is reducing agricultural feedstock dependency while improving batch consistency.
Market Restraints
- Coal-tar dye precursor supply concentration:Bulk p-phenylenediamine production clusters in Shandong province and the US Gulf Coast, exposing brands to single-point disruption risk.
- FDA exemption complexity:The coal-tar hair dye provision requires adverse event reporting without pre-market approval, creating liability asymmetry that deters smaller entrants.
- Natural pigment lightfastness limitations:Henna-derived colorants exhibit faster washout rates than oxidative systems, constraining permanent segment penetration.
Strategic Opportunities
- Men's grooming channel expansion:Beard and facial hair colorant formats remain underdeveloped in North American mass retail relative to scalp applications.
- California Proposition 65 labeling differentiation:Early compliance with warning-label requirements creates shelf-space advantage in specialty beauty retail.
- Foam delivery system patent expirations:Open-source aerated emulsion technology enables private-label entrants to replicate premium application experiences.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning both oxidative chemistry and natural product extraction commands premium compensation in South Korea and Germany.
- Dual regulatory dossier maintenance:Parallel FDA cosmetic notification and EU REACH registration requirements extend product launch timelines by 14-18 months.
- Legacy brand SKU rationalization:Ammonia-containing portfolio wind-downs face distributor resistance and trade promotion contract renegotiation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At Home Hair Dye Market |
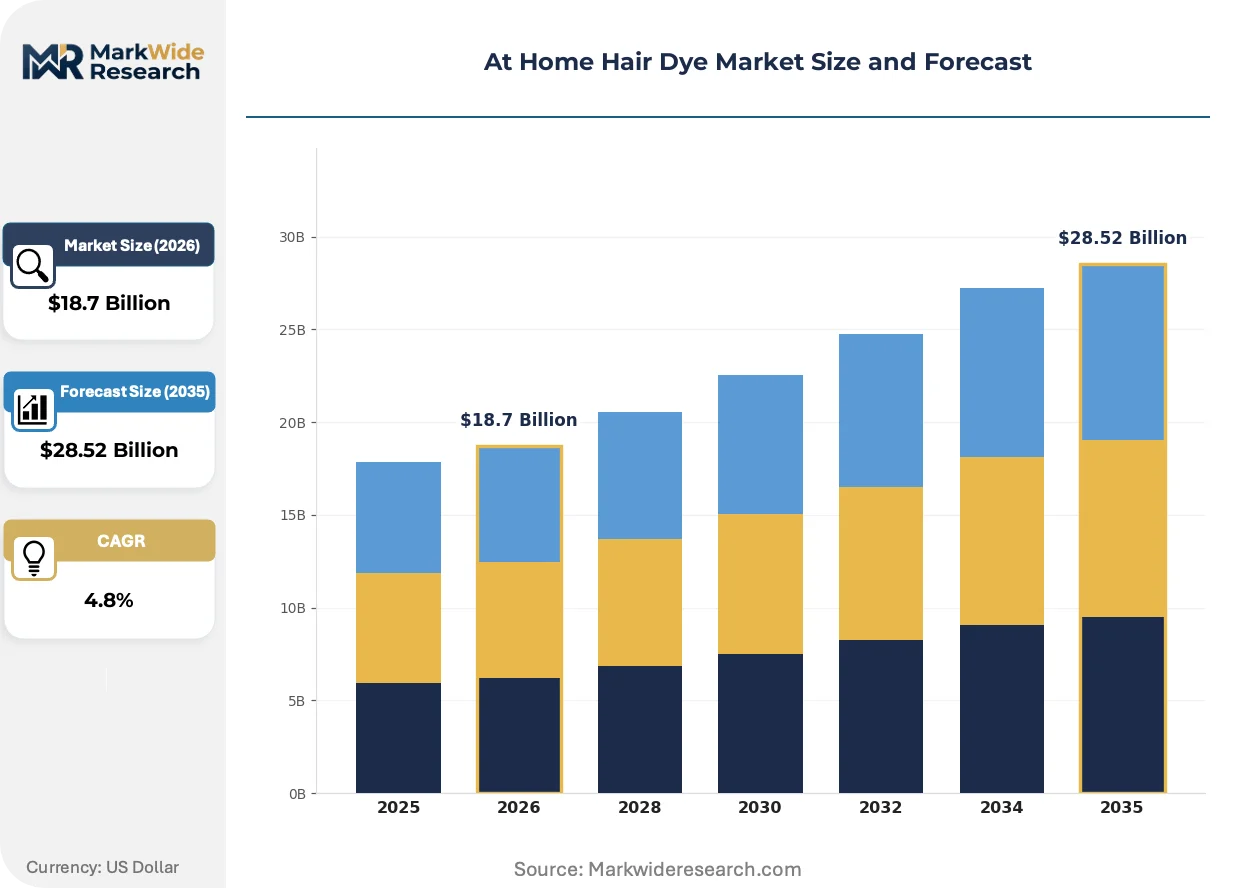
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Color, Semi-Permanent Color, Temporary Color, Highlights Ingredient Type: Organic, Chemical-Based, Vegan, Natural Target Demographic: Teens, Adults, Seniors, Unisex Packaging Type: Tubes, Bottles, Kits, Sachets |
| Companies Covered | Wella, HOYU, L'Oréal Paris, Revlon, Godrej, Garnier, Clairol, Combe Incorporated, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At Home Hair Dye Market Emerging Trajectories
Formulation science and application technology are converging to reduce consumer error rates while extending color durability. This convergence is compressing the performance gap between professional salon results and at-home outcomes.
Micro-pigment encapsulation technology is consolidating competitive positioning among premium tier suppliers. The technology functions by time-releasing dye intermediates during the oxidation window, reducing scalp irritation while improving gray coverage uniformity. Working-age professionals in Germany and the United States are adopting encapsulated systems at triple the rate of conventional creams. This adoption pattern is consolidating market share among suppliers with patented lipid-shell manufacturing capabilities.
EU Green Deal chemical sustainability targets are forcing raw material sourcing audits across the entire dye precursor supply chain. The framework mandates carbon footprint disclosure for imported cosmetic ingredients starting with aromatic amine categories. Permanent colorant manufacturers dependent on Asian petrochemical feedstocks face the steepest compliance cost escalation. German and French suppliers with regional biotech sourcing networks are capturing pharmacy channel placement advantages.
Subscription-based replenishment models are displacing traditional retail stocking patterns among high-frequency users. Direct-to-consumer platforms capture purchase history data to automate shade-matching and timing reminders. This channel shift is most visible in United States urban markets where same-day delivery infrastructure supports just-in-time inventory. Mass retailers are responding with locked-shelf dispensing systems that replicate the convenience proposition while preserving foot traffic.
At Home Hair Dye Market Segmentation
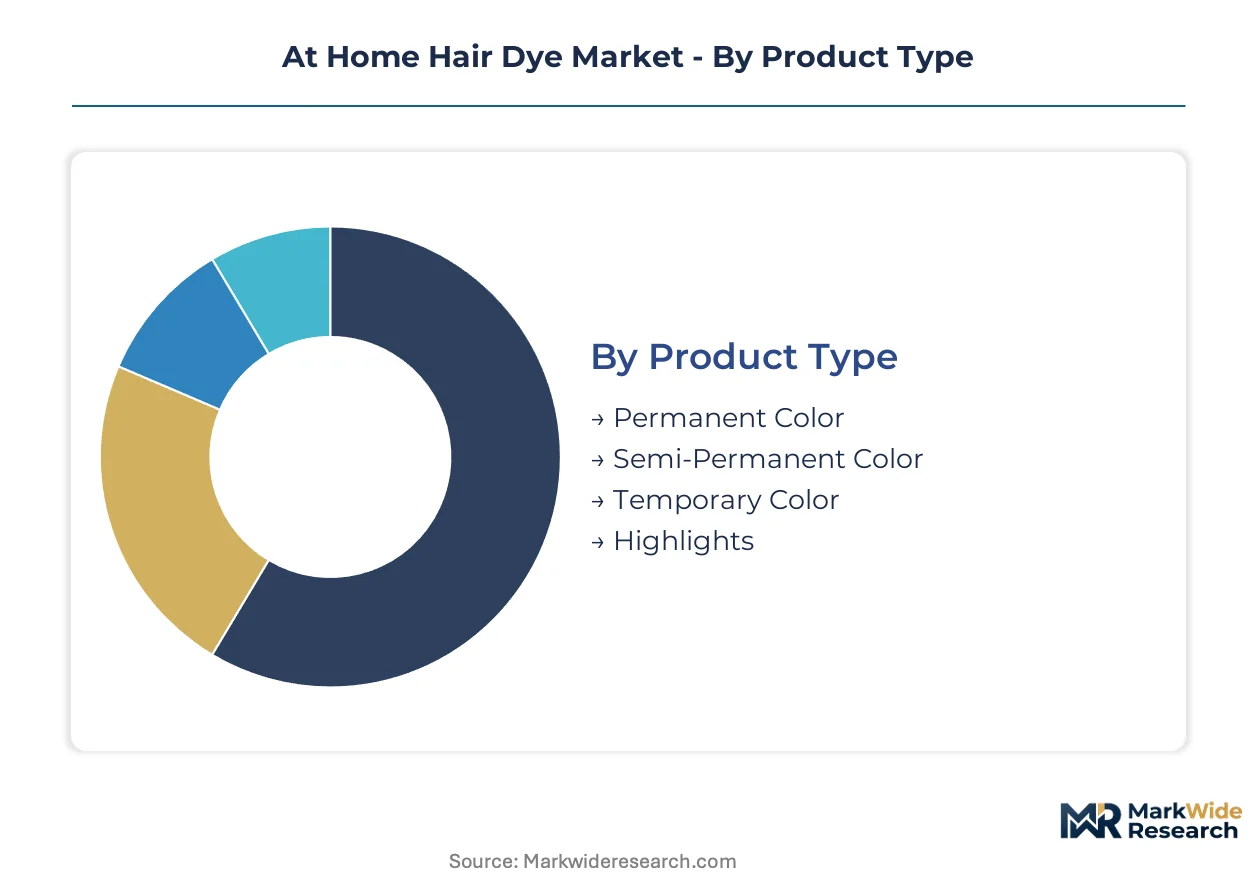
Consumer upgrade cycles in at-home hair colorants differ sharply across permanence levels and ingredient philosophies. Formulation investments and packaging innovation follow distinct demand rhythms in each segment cluster.
Product Type:
Replacement frequency drives margin architecture, with permanent systems commanding sustained repurchase loyalty while temporary formats accelerate trial velocity.
- Permanent Color:Oxidative systems containing p-phenylenediamine derivatives penetrate the hair cortex for lasting melanin alteration. Demand concentrates among working-age adults in the United States and Germany seeking gray coverage without salon cost inflation. Regulatory pressure from REACH aromatic amine restrictions is forcing reformulation toward paraphenylenediamine-free alternatives.
- Semi-Permanent Color:These direct dyes deposit color onto the cuticle layer without ammonia or developer, typically persisting through 4-12 washes. Adoption clusters among younger demographics in urban Chinese markets experimenting with fashion shades. The shorter replacement cycle supports higher frequency purchasing relative to permanent alternatives.
- Temporary Color:Surface-coating pigments wash out in 1-3 shampoos, enabling low-commitment experimentation. Festival and event-driven demand in South Korea sustains niche volume.
- Highlights:Cap-and-hook or brush-on lightening systems target specific strand sections rather than full-head application. DIY balayage tutorials on social platforms are expanding trial among North American millennials.
Volume placements concentrate in Permanent Color; the faster expansion belongs to Semi-Permanent Color.
Ingredient Type:
Clean-label migration is restructuring raw material procurement, with biotechnology-derived precursors displacing petrochemical feedstocks at the premium tier.
- Organic:Certification requires third-party verification of agricultural sourcing without synthetic pesticides. Supply chains in India and Morocco dominate henna and indigo cultivation.
- Chemical-Based:Conventional oxidative chemistry relies on aromatic amine precursors manufactured in Shandong province and the US Gulf Coast. Legacy brand portfolios face SKU rationalization pressure as ammonia-free alternatives gain shelf space.
- Vegan:Excludes all animal-derived ingredients including keratin additives and certain glycerin sources. Microbial fermentation of lawsone analogues is reducing agricultural dependency while improving batch consistency. Demand is climbing fastest in North American specialty beauty retail.
- Natural:Plant-derived colorants including henna, cassia, and indigo appeal to ingredient-transparent consumers. Lightfastness limitations constrain permanent segment penetration.
Supply concentration favors Chemical-Based formulations; Vegan ingredient systems are gaining share fastest.
Target Demographic:
Application confidence and color complexity tolerance vary by life stage, shaping format preferences and price elasticity.
- Teens:Temporary and semi-permanent formats dominate, with social media discovery driving impulse purchases. Sachet packaging supports low-entry-price experimentation.
- Adults:The 35-54 bracket sustains permanent oxidative system volume through gray coverage needs. Subscription replenishment models capture high-frequency users in United States urban markets.
- Seniors:Simplified application formats and scalp-sensitive formulations address dexterity and skin tolerance concerns. Pharmacy channel placement concentrates in Germany and Japan.
- Unisex:Neutral packaging and universal shade ranges target household consolidation purchasing. Beard and facial hair colorant formats remain underdeveloped relative to scalp applications.
Volume concentrates in Adults; Unisex positioning is expanding most quickly.
Packaging Type:
Application precision and storage convenience trade off against unit economics and retail shelf efficiency.
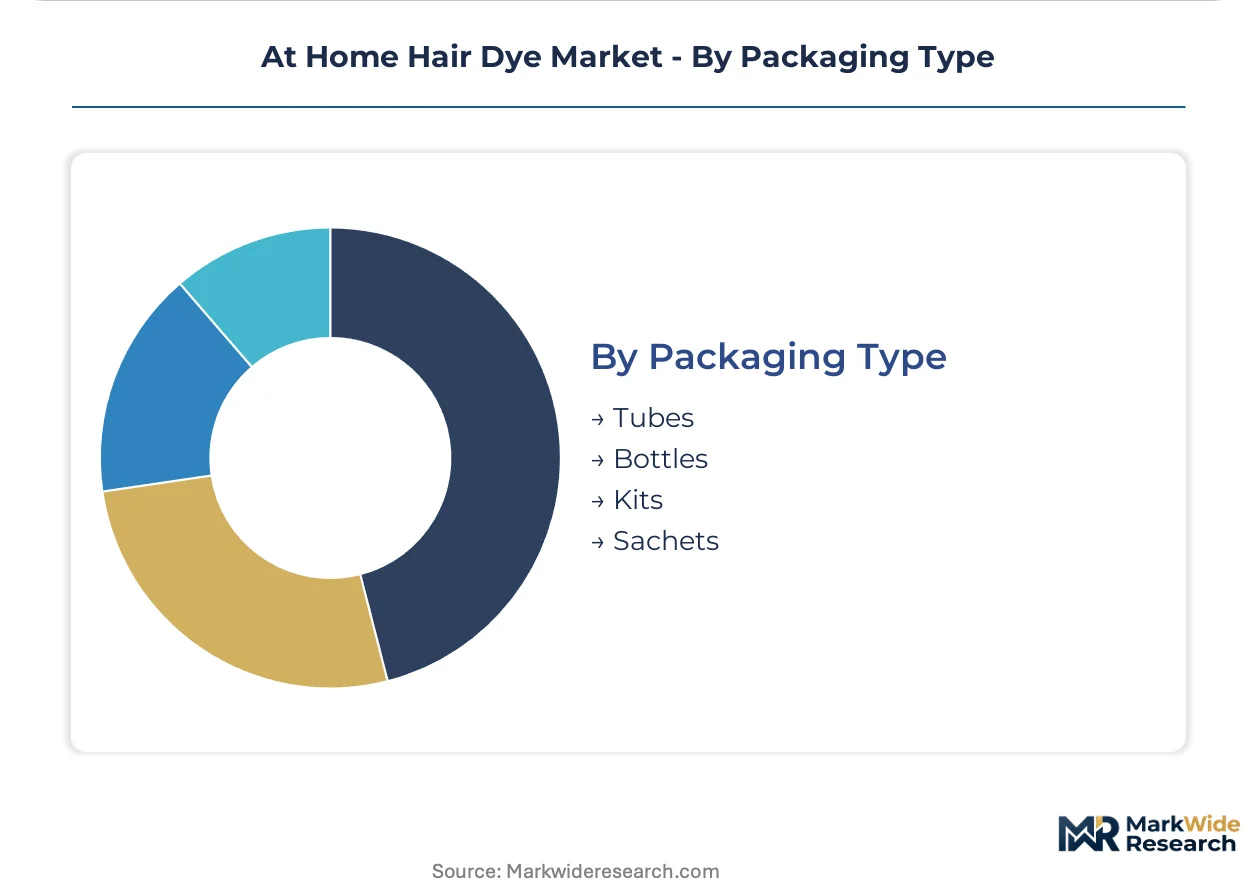
- Tubes:Squeeze-dispense formats enable controlled portioning for root touch-up applications. Standard in European pharmacy channels.
- Bottles:Flip-cap or pump dispensers suit liquid and foam formulations. Mass retail stocking favors this format for brand visibility.
- Kits:Bundled developer, colorant, conditioner, and application tools reduce consumer error rates. Premium tier positioning leverages micro-pigment encapsulation technology.
- Sachets:Single-use pouches minimize upfront commitment and support trial sampling. Dense general trade networks in South Asia favor this low-unit-cost format.
Kit packaging commands premium placement; sachet volume is climbing fastest in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province petrochemical feedstocks anchor oxidative precursor supply for at-home colorant manufacturers worldwide. This concentration pattern shapes regional demand clusters as brands seek proximity to raw material security and regulatory compliance expertise.
United States
Gray coverage demand among working-age professionals drives permanent oxidative system volume through mass retail and pharmacy channels. FDA coal-tar hair dye exemption requirements create compliance asymmetry that favors established portfolios with adverse event reporting infrastructure. New Jersey and Ohio host contract manufacturing clusters serving private-label brands with ammonia-free formulation capabilities.
Germany
Pharmacy channel placement concentrates demand for dermatologically tested, paraphenylenediamine-free alternatives among ingredient-conscious consumers. EU REACH aromatic amine restrictions and ECHA hazard classification updates accelerate reformulation investments by domestic suppliers. The Rhine-Ruhr industrial corridor houses dedicated ammonia-free production lines and biotech fermentation facilities for plant-derived pigment synthesis.
China
Urban working-age cohorts in tier-one cities adopt permanent color systems for gray coverage as salon service costs escalate. NMPA cosmetic registration requirements and GB standards for hair dye safety govern product entry, with Shandong province maintaining bulk p-phenylenediamine production concentration. Yangtze River Delta contract manufacturers are expanding capacity for export-oriented at-home colorant brands.
South Korea
Fashion-forward semi-permanent color experimentation among younger demographics sustains high trial velocity through e-commerce and social commerce channels. MFDS cosmetic safety standards and ingredient disclosure requirements shape formulation transparency expectations. Seoul Capital Area contract manufacturers are realigning global supply chains for ammonia-free and plant-derived product portfolios.
India
Dense general trade networks in urban and semi-urban markets drive sachet-format volume for low-commitment colorant trial. BIS cosmetic standards and FSSAI labeling requirements govern product safety and ingredient transparency claims. Maharashtra and Gujarat host henna and indigo agricultural supply chains feeding natural and organic formulation segments.
At Home Hair Dye Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label specialization and direct-to-consumer subscription models. The vendor base spans multinational consumer goods conglomerates with dermatological testing infrastructure, regional specialists with dense distribution networks, and biotech-enabled challengers with fermentation-derived pigment capabilities. Three archetypes dominate: legacy brand owners with pharmacy channel anchoring, contract manufacturers with flexible formulation platforms, and digital-native brands with data-driven shade-matching. Competitive moves center on SKU rationalization of ammonia-containing portfolios and strategic partnerships with biotech suppliers for precursor security.
Among multinational consumer goods conglomerates, L'Oréal Paris and Henkel exemplify the pharmacy-channel archetype with European regulatory compliance depth. Godrej occupies a position within the regional specialist tier, leveraging dense general trade penetration across South Asian markets. These three entities represent distinct strategic postures: dermatological testing infrastructure, dedicated ammonia-free production capacity, and distribution network density respectively.
| Leading Market Players |
|---|
| Wella |
| HOYU |
| L'Oréal Paris |
| Revlon |
| Godrej |
| Garnier |
| Clairol |
| Combe Incorporated |
| Henkel |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical sustainability targets gate qualified supply access and premium-tier pricing power for at-home hair dye manufacturers. REACH carbon footprint disclosure mandates for aromatic amine imports force reformulation investments that stratify pricing tiers between compliant biotech-sourced portfolios and legacy petrochemical-dependent alternatives.
Pricing Analysis
Service bundling separates kit formats with included developer and conditioner from unbundled tube-and-bottle alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects dermatological certification grade and subscription replenishment access. Cost compression in ammonia-free chemistry tiers is intensifying because Shandong province feedstock concentration exposes brands to input volatility. Mass retail buyers exhibit highest price sensitivity; pharmacy channel purchasers demonstrate lowest elasticity due to ingredient transparency preferences.
Supply Chain Analysis
Dual-sourcing requirements for p-phenylenediamine derivatives mandate qualification of both Shandong province and US Gulf Coast suppliers. Raw material dependencies center on aromatic amine precursors, henna agricultural feedstocks from India and Morocco, and microbial fermentation capacity in Germany and South Korea. Single-source vulnerability in Shandong petrochemical clustering presents structural risk amid tariff exposure. Distribution runs through mass retail chains, pharmacy channels, and direct-to-consumer platforms with subscription infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over biotech fermentation capacity and downstream subscription data assets determines margin durability. Players are pursuing captive supply of plant-derived dye precursors to escape petrochemical price volatility.
For Market Incumbents: Cement pharmacy channel anchoring through paraphenylenediamine-free certification investments before REACH hazard classification updates tighten. Acquire South Korean contract manufacturing capacity with dedicated ammonia-free lines to preempt emerging entrant scale. Vertical integration into Moroccan and Indian henna agricultural networks secures organic segment feedstock against climate-driven harvest variability. For New Entrants and Emerging Players: Capture underdeveloped men's grooming white space through beard and facial hair colorant formats in North American mass retail. Exploit foam delivery system patent expirations to replicate premium application experiences with private-label positioning. Direct-to-consumer shade-matching algorithms paired with same-day delivery infrastructure offer the most penetrable go-to-market angle in United States urban markets. For Investors and Strategic Acquirers: MFDS cosmetic safety standard updates in South Korea are the leading indicator that ammonia-free formulation capabilities will command acquisition premiums. Long-term viability rests on biotech-enabled suppliers with microbial fermentation of lawsone analogues and indigo precursors. Target acquisition archetype: mid-cap contract manufacturers with flexible formulation platforms and existing pharmacy channel relationships. The signal to watch is SKU rationalization announcements from legacy brands winding down ammonia-containing portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biotech Fermentation | Captive supply of plant-derived pigments reduces agricultural feedstock dependency for German and South Korean manufacturers. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models with automated shade-matching capture high-frequency user data in United States urban markets. |
| Paraphenylenediamine-Free Certification | EU REACH compliance creates pharmacy channel placement advantage against legacy ammonia-containing portfolios. |
| Men's Grooming Format Extension | Beard and facial hair colorant development addresses underpenetrated segment relative to scalp applications in North America. |
| Sustainability Repositioning | California Proposition 65 early compliance generates shelf-space differentiation in specialty beauty retail channels. |
Methodological Framework
Trade databases, regulatory filings, and customs records formed the secondary backbone of this analysis. Primary interviews with cosmetic chemists, pharmacy category buyers, contract manufacturing executives, and brand formulation directors validated demand assumptions. Bottom-up segment sizing triangulated against top-down macroeconomic indicators produced volume and value estimates.
Historical trendline analysis of permanent, semi-permanent, and temporary colorant demand patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, ingredient philosophy, target demographic, and packaging format dimensions with regional regulatory cluster variations. CAGRs derived from elasticity-adjusted replacement cycle frequencies and channel shift velocity parameters.
The model holds under stable REACH enforcement timelines and FDA coal-tar dye exemption continuity; deviation in aromatic amine hazard reclassification or California Proposition 65 expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Europe Male Grooming Products Market