
 India Cosmetics Products Market | 2026-2036
India Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Cosmetics Products Market Foresight
E-commerce platforms is reconfiguring how cosmetics reach Indian consumers beyond metropolitan boundaries. Nykaa leverages its proprietary fulfillment network to sustain same-day delivery in twelve cities. Honasa Consumer anchors its portfolio in toxin-free formulations that dominate digital shelf space. L'Oréal SA extends its salon-professional channel to compete with mass-market direct-to-consumer brands.
Cosmetics products encompass topical formulations for skin, hair, and personal adornment, typically comprising emulsifiers, active ingredients, and preservatives manufactured through batch processing or continuous compounding systems designed for sensory performance and dermatological safety. Skincare leads volume contribution as consumers prioritize preventive routines over corrective treatments. Haircare occupies the fastest-expanding margin pool driven by specialized solutions for tropical climate conditions. Makeup differentiates through shade-range breadth calibrated to Indian skin tones, while fragrance competes on affordable luxury positioning.
BIS mandatory certification and CDSCO color-additive regulations govern product safety standards, with FSSAI overlap on cosmeceutical claims creating layered compliance obligations for domestic and imported brands. The PLI scheme for personal care manufacturing is reshaping where companies locate formulation and packaging operations. Stakeholders must monitor how state-level drug control administrations interpret ingredient bans versus central ministry guidance.
Market Dynamics
Digital commerce infrastructure is redrawing distribution economics for cosmetics in India, compressing the traditional multi-tier wholesale structure that historically gated market access for regional and insurgent brands.
Growth Catalysts
- PLI scheme for personal care manufacturing:Central government production-linked incentives are attracting formulation and packaging investment to Gujarat and Maharashtra industrial corridors.
- Tier-two and tier-three city digital literacy:Smartphone penetration and vernacular e-commerce interfaces are unlocking first-time cosmetics buyers in Indore, Lucknow, and Coimbatore.
- Salon-professional channel expansion:Trained beautician networks in Delhi NCR and Bangalore are converting service relationships into product recommendation engines.
Market Restraints
- Palm oil and surfactant input volatility:Import dependency on Southeast Asian oleochemical supply creates margin compression for mass-market shampoo and cleanser producers.
- BIS certification bottlenecks:Bureau of Indian Standards testing queue delays average four to six months for new skincare formulations.
- CDSCO color-additive compliance costs:Central Drugs Standard Control Organization notification requirements for imported pigments raise working capital intensity for indie makeup brands.
Strategic Opportunities
- Men's grooming underpenetration:Male consumers in Kerala and Tamil Nadu represent white space for beard care and skin-brightening portfolios.
- Ayurveda-cosmeceutical convergence:FSSAI-recognized functional claims for turmeric and neem extracts enable premium positioning in domestic and export markets.
- Direct-to-consumer subscription models:Replenishment algorithms for sunscreen and serum categories are locking in recurring revenue streams.
Industry Challenges
- Formulation chemist talent scarcity:Qualified cosmetic scientists command premium salaries in Mumbai and Hyderabad, constraining R&D scaling for mid-tier brands.
- Legacy ERP integration with DTC analytics:Manufacturers with SAP deployments face data architecture friction when connecting to Shopify and proprietary e-commerce stacks.
- Ingredient traceability documentation:CDSCO and BIS dual audit trails require blockchain or equivalent verification systems that smaller suppliers cannot fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cosmetics Products Market |
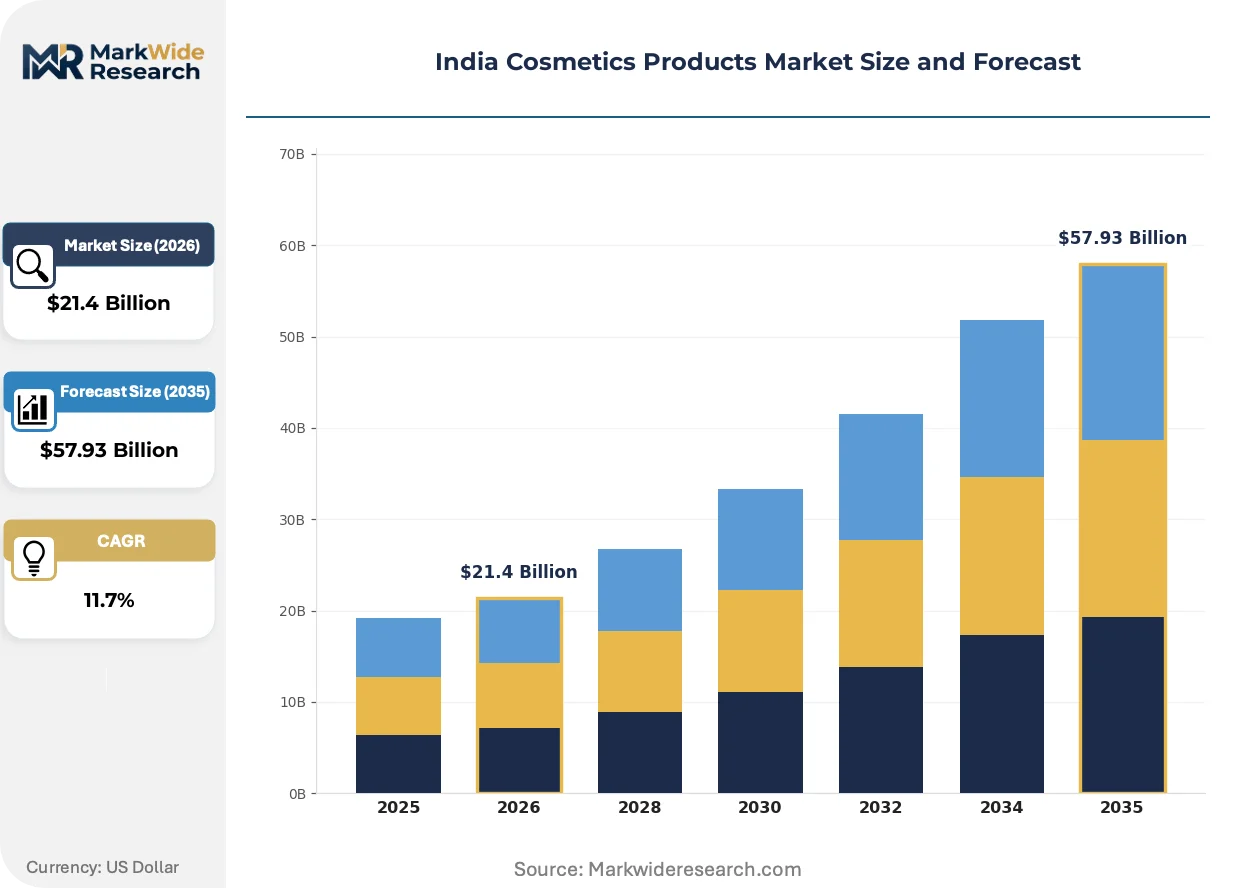
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $57.93 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance End User: Men, Women, Teens, Children Distribution Channel: Online, Offline, Drugstores, Supermarkets Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | FSN E-Commerce Ventures Ltd (Nykaa), Honasa Consumer Ltd (Mamaearth), L'Oréal SA, Colorbar Cosmetics Pvt Ltd, Lotus Herbals Pvt Ltd, Unilever PLC, Vellvette Lifestyle Pvt. Ltd. (Sugar Cosmetics), Lakmé, The Estée Lauder Companies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cosmetics Products Market Shifts & Advancements
Clean beauty claims are hardening into enforceable standards as Indian consumers develop sophistication around ingredient transparency and environmental footprint verification.
Biotechnology-derived actives are migrating from niche dermatology channels to mass-market facial serums. Fermentation-produced hyaluronic acid and ceramides now anchor Rs 500-1500 price point moisturizers. Nykaa and direct-to-consumer brands are compressing the traditional four-year ingredient diffusion cycle into eighteen months.
BIS mandatory certification expansion is tightening safety documentation for all imported cosmetics. The 2024 notification extending standards to hair dyes and nail polishes forces reformulation of legacy European and Korean product lines. Maharashtra and Karnataka state drug control administrations are interpreting ingredient bans more strictly than central ministry guidance.
Consumption patterns are fragmenting across occasion-based micro-routines rather than broad skin-type segmentation. Consumers in Bangalore and Pune maintain separate morning defense and evening repair regimens with distinct product sets. This behavior is compressing brand loyalty and expanding average SKU counts per household.
India Cosmetics Products Market Segmentation
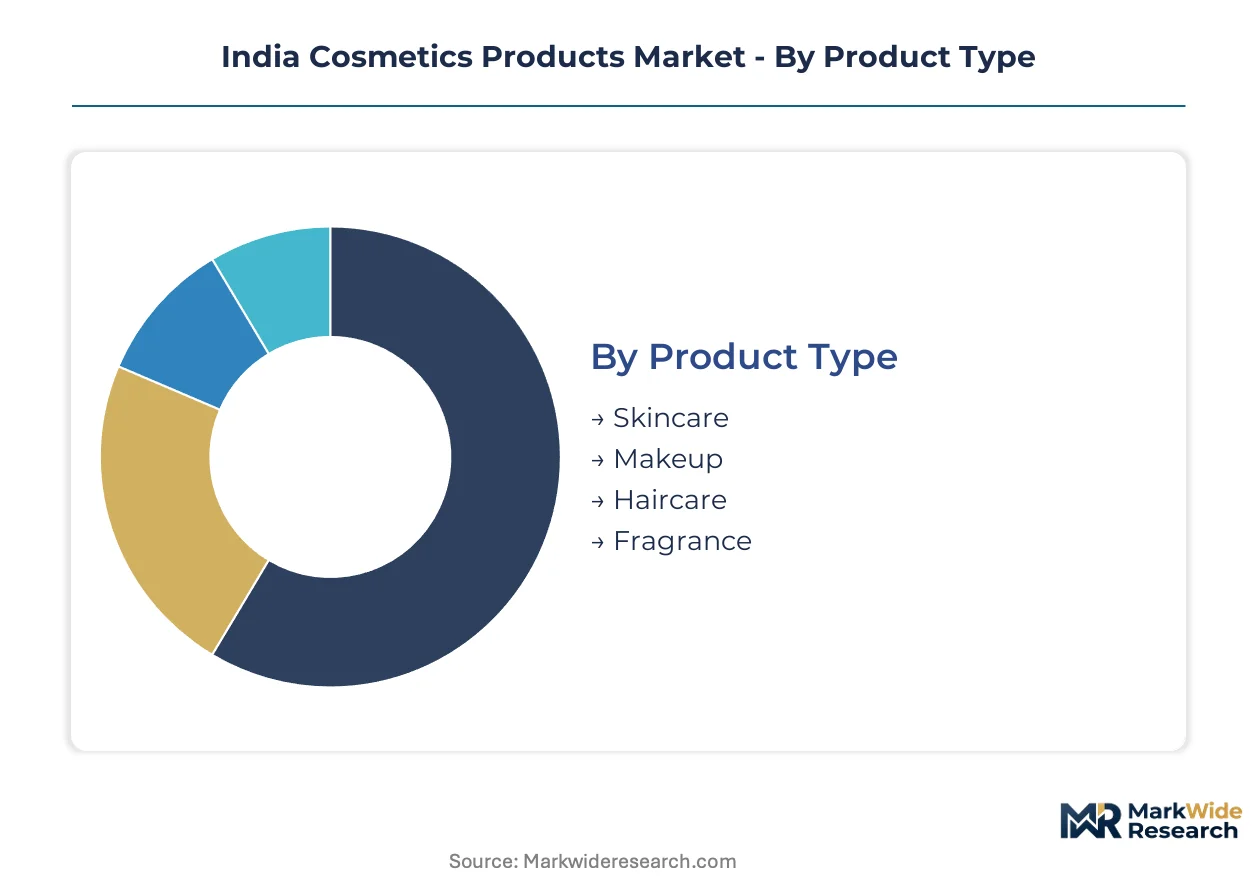
Segmentation in India's cosmetics market reveals how purchasing decisions bifurcate between metropolitan sophistication and emerging city pragmatism. Understanding these divisions exposes where formulation investments, channel partnerships, and regulatory compliance resources generate disproportionate returns.
Product Type:
Use cases span preventive dermatology, aesthetic enhancement, climate adaptation, and sensory identity expression.
- Skincare:Emulsions, serums, and sunscreens formulated with ceramides, niacinamide, and SPF actives for barrier repair and photoprotection. Demand concentrates in Maharashtra and Karnataka where humidity-indexed formulations address tropical oxidative stress.
- Haircare:Shampoos, conditioners, and scalp treatments engineered with cationic surfactants and protein complexes for hard water tolerance and monsoon frizz management. Specialized anti-pollution ranges are climbing the fastest in Delhi NCR as particulate exposure intensifies.
- Makeup:Color cosmetics with iron oxide and mica-based pigments calibrated to Fitzpatrick Type III-V skin tones.
- Fragrance:Eau de toilette and attar-based formats competing on affordable luxury positioning and occasion-specific gifting rituals.
Established volume favors Skincare; emerging adoption favors Haircare.
End User:
Demographic targeting must navigate divergent price sensitivity, ingredient literacy, and channel preferences across life stages.
- Women:Primary purchasers across all categories, driving 70%+ of household cosmetics decisions with established routines in anti-aging and pigmentation correction. Concentrated demand in tier-one cities for clinical-grade actives; tier-two cities favor Ayurveda-positioned mass brands.
- Men:Beard oils, skin-brightening moisturizers, and deodorant formats targeting Kerala and Tamil Nadu where grooming social norms are shifting fastest. Subscription models for daily-use categories are locking in recurring revenue streams.
- Teens:Acne-specific cleansers and tinted sunscreens distributed through Instagram-native DTC brands with influencer co-creation.
- Children:Tear-free formulations and mineral-based sunscreens governed by FSSAI safety thresholds for pediatric topical exposure.
Women anchor current revenue; men represent the steepest expansion trajectory.
Distribution Channel:
Channel economics determine working capital intensity, margin retention, and consumer data capture depth.
- Online:Proprietary e-commerce platforms and marketplace aggregators with same-day fulfillment in twelve cities. Nykaa's logistics infrastructure and vernacular interfaces are unlocking first-time buyers in Indore, Lucknow, and Coimbatore.
- Offline:Department store counters and standalone brand stores with trained beauty advisor consultation in Delhi NCR and Bangalore.
- Drugstores:Pharmacy-affiliated retail with pharmacist endorsement for sensitive skin and dermatologist-recommended ranges.
- Supermarkets:Mass-market shampoos and soaps in modern trade formats with high-frequency replenishment purchasing.
Online is gaining share fastest; offline retains premium conversion rates.
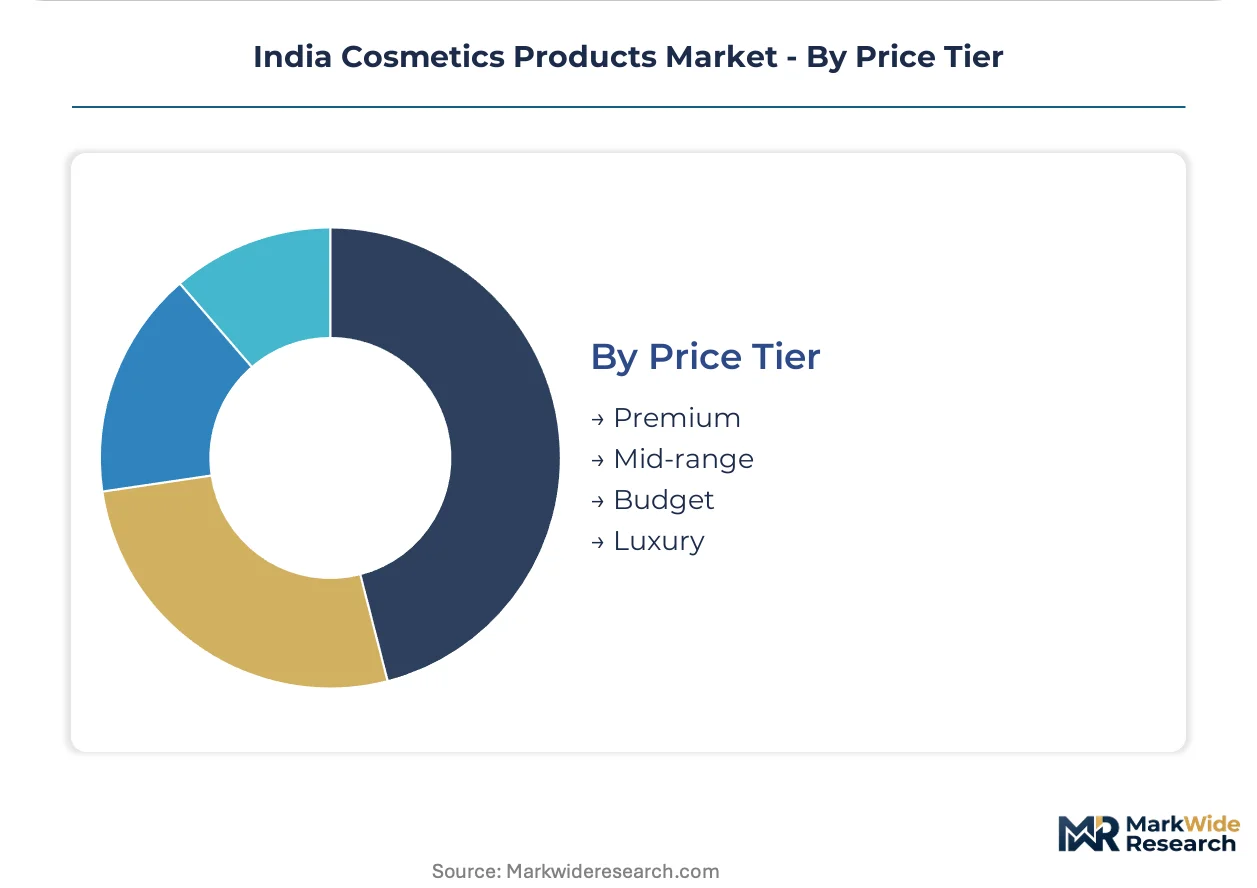
Price Tier:
Pricing stratification reflects ingredient grade certification, packaging material costs, and marketing spend intensity.
- Premium:Clinically tested formulations with BIS compliance documentation and airless pump packaging. Concentrated in Maharashtra and Karnataka where organized retail density supports experiential trial.
- Mid-range:Ayurveda-positioned brands with FSSAI-recognized functional claims for turmeric and neem extracts.
- Budget:Sachet and mini-format mass products with surfactant-heavy formulations for rural and small-town penetration.
- Luxury:Imported European and Korean lines with CDSCO color-additive clearance and duty-absorbed landed costs.
Mid-range captures volume expansion; luxury faces BIS certification bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust cargo corridors and the Western Dedicated Freight Corridor link Maharashtra's manufacturing clusters to domestic distribution networks. These logistics arteries enable same-day replenishment cycles for e-commerce fulfillment centers.
Maharashtra
Mumbai and Pune drive premium skincare consumption through organized retail density and dermatologist clinic networks. BIS mandatory certification requirements govern all imported formulations entering through JNPT customs. The Bhiwandi warehousing belt hosts Nykaa's largest automated fulfillment center with cold-chain capabilities for temperature-sensitive actives.
Karnataka
Bangalore's salon-professional channel converts service relationships into product recommendation engines for clinical-grade haircare. CDSCO oversight on color additives forces reformulation of Korean and European makeup imports. The Whitefield industrial corridor attracts PLI scheme beneficiaries for personal care manufacturing.
Delhi NCR
Anti-pollution skincare ranges climb fastest as particulate exposure intensifies across Gurgaon and Noida. FSSAI overlap on cosmeceutical claims creates layered compliance obligations for turmeric-positioned brands. The Manesar logistics hub enables four-hour delivery radii into Uttar Pradesh and Haryana secondary cities.
Gujarat
Central government production-linked incentives anchor formulation and packaging investment to Sanand and Vithalapur industrial corridors. DGFT import duty structures on Southeast Asian oleochemicals determine surfactant cost bases for mass-market shampoo producers. The Mundra port linkage reduces landed costs for Malaysian palm oil derivatives.
Tamil Nadu
Chennai and Coimbatore represent white space for men's grooming portfolios as beard care social norms shift. State drug control administrations interpret ingredient bans more strictly than central ministry guidance on formaldehyde-releasing preservatives. The Sriperumbudur electronics manufacturing zone spurs packaging material supplier clustering.
India Cosmetics Products Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational heritage houses and insurgent digital-native brands. Tier-one metropolitan markets sustain premium salon-professional channels while tier-two cities unlock through vernacular e-commerce interfaces. Three strategic archetypes dominate: vertically integrated Ayurveda-positioned domestic players, direct-to-consumer specialists with proprietary fulfillment infrastructure, and multinational incumbents extending salon networks. Competitive moves concentrate on portfolio diversification into adjacent personal care categories and backward integration into captive formulation facilities.
Within the digital-native tier, FSN E-Commerce Ventures Ltd (Nykaa) and Honasa Consumer Ltd (Mamaearth) exemplify divergent platform strategies. L'Oréal SA anchors the multinational salon-professional vector. These three occupy positions across the pricing spectrum from mass-market sachets to premium imported lines, each representing distinct supply chain configurations for reaching first-time buyers in Indore, Lucknow, and Coimbatore.
| Leading Market Players |
|---|
| FSN E-Commerce Ventures Ltd (Nykaa) |
| Honasa Consumer Ltd (Mamaearth) |
| L'Oréal SA |
| Colorbar Cosmetics Pvt Ltd |
| Lotus Herbals Pvt Ltd |
| Unilever PLC |
| Vellvette Lifestyle Pvt. Ltd. (Sugar Cosmetics) |
| Lakmé |
| The Estée Lauder Companies Inc. |
| Others |
Supply & Pricing Matrix
Bhiwandi's automated fulfillment infrastructure anchors Maharashtra's cosmetics distribution economics, compressing same-day delivery radii across twelve cities and concentrating pricing power among vertically integrated platform operators. This logistics density enables volume-discount tiering that mass-market sachet producers cannot match, widening spreads between premium serum formulations and surfactant-heavy budget alternatives.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between e-commerce platforms and contract manufacturers, with annual offtake commitments securing landed cost advantages. Price differentiation hinges on BIS certification documentation and airless pump packaging material grades. Pricing pressure stems from palm oil derivative volatility imported through Mundra Port, compressing margins for shampoo and cleanser producers. Budget sachet buyers in tier-three cities exhibit highest price sensitivity; premium serum purchasers in Bangalore and Pune demonstrate lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Nykaa's logistics arm compress working capital cycles for mid-tier Ayurveda brands, reducing cash conversion periods. Geographic supply concentration draws from Malaysia for palm oil derivatives, South Korea for fermentation-derived hyaluronic acid, and Switzerland for fragrance compounds. Raw material dependencies rest on cationic surfactants, iron oxide pigments, and ceramide actives. Single-source vulnerability concentrates in Southeast Asian oleochemical feedstock. Distribution runs through Bhiwandi warehousing clusters with cold-chain capabilities for temperature-sensitive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's cosmetics sector sits at a platform-economics inflection where proprietary fulfillment networks interoperate with vernacular e-commerce interfaces, collapsing traditional wholesale intermediaries. This ecosystem shift rewards captive logistics infrastructure over brand equity alone.
For Market Incumbents: Insulate salon-professional channel relationships in Delhi NCR and Bangalore through exclusive product lines and trained beautician certification programs. Backward integration into captive formulation facilities in Gujarat's PLI corridors secures margin control against surfactant input volatility. CDSCO compliance documentation investments create switching costs for indie makeup competitors dependent on imported pigment supply.
For New Entrants and Emerging Players: Kerala and Tamil Nadu men's grooming segments offer penetrable white space as beard care social norms shift fastest in southern states. Teen acne-specific cleansers distributed through Instagram-native influencer co-creation unlock first-mover advantage in unclaimed digital shelf space. Ayurveda-cosmeceutical convergence with FSSAI-recognized functional claims enables premium positioning without multinational R&D overhead.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because replenishment algorithms for sunscreen and serum categories lock in predictable cash flows. Acquisition targets should emphasize proprietary fulfillment infrastructure over pure brand assets. The signal to watch is same-day delivery radius expansion into tier-three cities as digital literacy spreads.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Replenishment algorithms for sunscreen categories lock recurring revenue streams in Bangalore and Pune households. |
| Ayurveda-Cosmeceutical Certification Investment | FSSAI-recognized functional claims for turmeric extracts enable premium positioning in domestic and export markets. |
| Proprietary Fulfillment Infrastructure Buildout | Nykaa's Bhiwandi cold-chain capabilities compress delivery radii and raise switching costs for platform sellers. |
| Salon-Professional Channel Expansion | Trained beautician networks in Delhi NCR convert service relationships into product recommendation engines. |
| Backward Integration into Formulation Facilities | PLI scheme beneficiaries in Gujarat industrial corridors secure margin control against oleochemical input volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS certification databases, CDSCO color-additive notifications, and customs import records for oleochemical derivatives. Interviews with brand managers at direct-to-consumer platforms, category buyers at organized retail chains, supply planners at contract manufacturers, and regulatory affairs leads at multinational houses inform demand and compliance dynamics. Secondary validation draws from DGFT trade statistics, FSSAI functional claim registries, and PLI scheme beneficiary disclosures. Bottom-up SKU-level demand modeling triangulates against top-down market sizing from distribution channel revenue aggregation.
Forecast inputs incorporate product type segmentation across skincare, haircare, makeup, and fragrance; end-user splits between women, men, teens, and children; distribution channel dynamics spanning online, offline, drugstore, and supermarket; and price tier stratification from budget sachets through luxury imports. CAGRs derive from regression analysis of historical volume trajectories against smartphone penetration curves and vernacular interface adoption rates in tier-two and tier-three cities. Industry-specific inputs include BIS certification queue durations and CDSCO notification processing timelines for imported pigments.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates affecting landed costs for Korean and European formulations would shift the trajectory. Forecasts assume documented regulatory processing timelines and PLI scheme continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Electric Nail Files Market
Beauty & Personal Care
Waterless Cosmetics Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Global Personal Care Market