
 Europe Hair Conditioner Market | 2026-2036
Europe Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Conditioner Market Foresight
Buyer concentration among European salon chains and e-commerce platforms is hardening as procurement consolidates around fewer distributors with national coverage. L'Oréal S.A. leverages its Paris-based R&D hub to sustain innovation pipelines for professional-grade formulations. Henkel AG & Co. KGaA anchors its position through Schwarzkopf brand strength in German drugstore channels. Unilever competes aggressively on mid-range price positioning across Southern European supermarkets.
Europe hair conditioner encompasses rinse-off and leave-in formulations designed to deposit cationic surfactants, silicones, or plant-derived oils onto the hair cuticle to reduce friction, improve combability, and seal moisture. Manufacturing typically involves emulsion-phase processing at controlled temperatures to preserve active ingredient stability. Repairing conditioners lead volume demand among consumers with chemically treated or heat-damaged hair, while color-protecting variants capture premium margin pools tied to salon-aftercare routines. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer subscription models displace traditional supermarket stocking.
REACH regulations enforced by ECHA mandate full ingredient disclosure and restrict certain preservative chemistries, compelling reformulation investments across the sector. The EU Green Deal and CSRD reporting requirements pressure brands to document supply-chain carbon intensity and packaging recyclability. EMA and national cosmetics regulators in France and Germany conduct post-market surveillance that shapes labeling standards and advertising claims. Stakeholders must monitor evolving biodegradability thresholds and packaging waste directives that will determine which formulations retain shelf access across the continent.
Market Dynamics
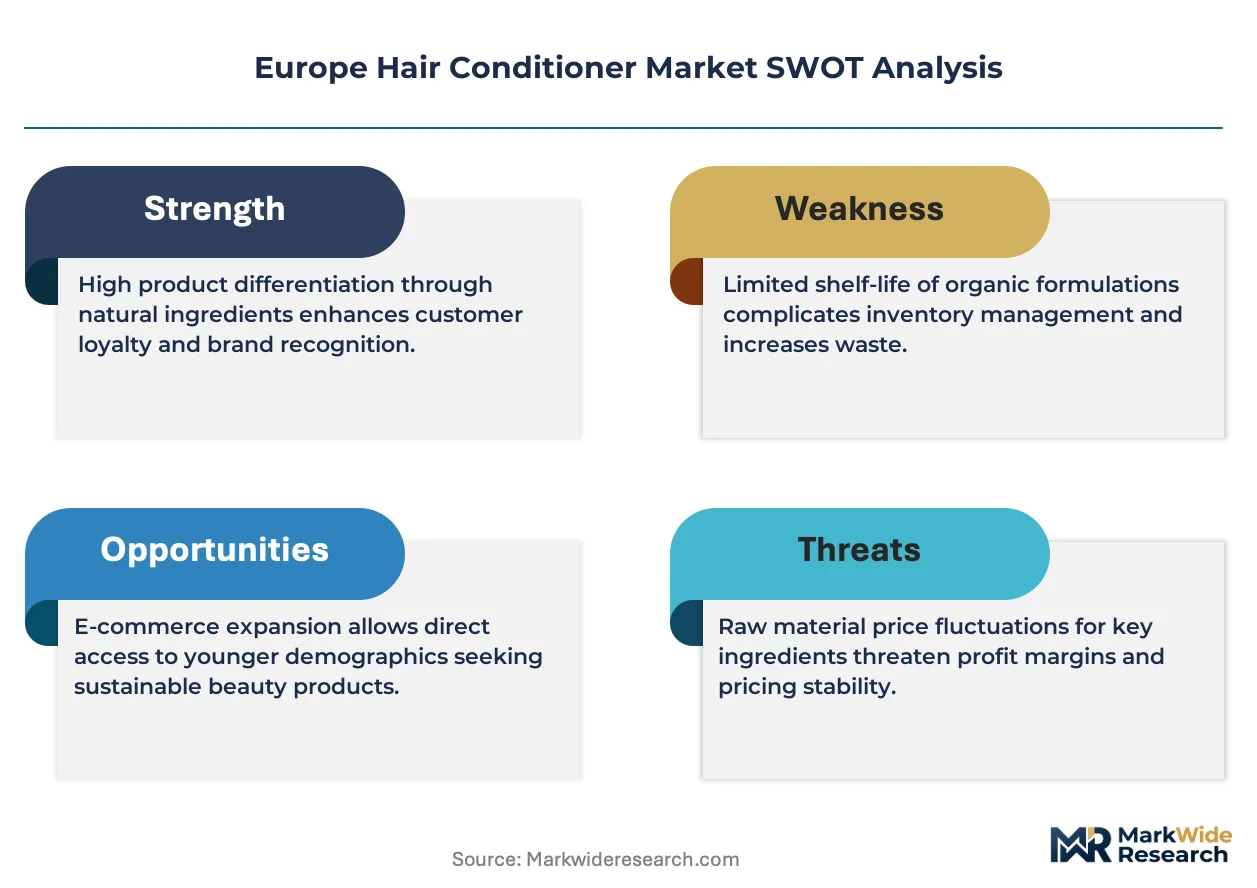
REACH compliance and the EU Green Deal are forcing wholesale reformulation across European hair conditioner manufacturing, converting biodegradable surfactant mandates into competitive moats for early-adopting producers while raising entry barriers for import-dependent brands.
Growth Catalysts
- Salon-aftercare routines:Professional stylists in Germany and France now prescribe repair-focused conditioners as standard post-color treatment, embedding premium SKUs into recurring client protocols.
- CSRD reporting requirements:The EU Corporate Sustainability Reporting Directive compels mid-tier brands to document supply-chain carbon intensity, accelerating consolidation around certified low-footprint contract manufacturers.
- Biodegradable cationic surfactants:New enzymatic processing methods enable plant-derived conditioning agents to match silicone performance, unlocking reformulation pathways previously blocked by efficacy gaps.
Market Restraints
- Palm-derived emollient volatility:Southeast Asian feedstock supply disruptions transmit directly into European conditioner cost structures, compressing margins on mass-market SKUs.
- ECHA preservative restrictions:REACH Annex XVII updates continue delisting conventional biocides, forcing costly stability re-testing for legacy formulations.
- Water footprint constraints:The EU Green Deal's anticipated water-use thresholds threaten concentrated rinse-off products that rely on high-aqueous processing.
Strategic Opportunities
- Polish and Romanian pharmacy channels:Underdeveloped professional haircare infrastructure in these markets creates first-mover openings for salon-distribution partnerships.
- Direct-to-consumer subscription models:Nordic consumers demonstrate highest European adoption of auto-replenishment platforms, offering margin recovery bypassing retail slotting fees.
- Packaging waste directive alignment:Early compliance with evolving EU recyclability mandates positions brands for preferred listing as retailers enforce shelf-access criteria.
Industry Challenges
- Cosmetic formulation chemist scarcity:Specialized expertise in cationic emulsion stability commands premium compensation, constraining R&D throughput for mid-cap producers.
- Multi-jurisdiction labeling complexity:Divergent national interpretations of ECHA guidance across France, Germany, and Italy generate compliance overhead for pan-European SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Conditioner Market |
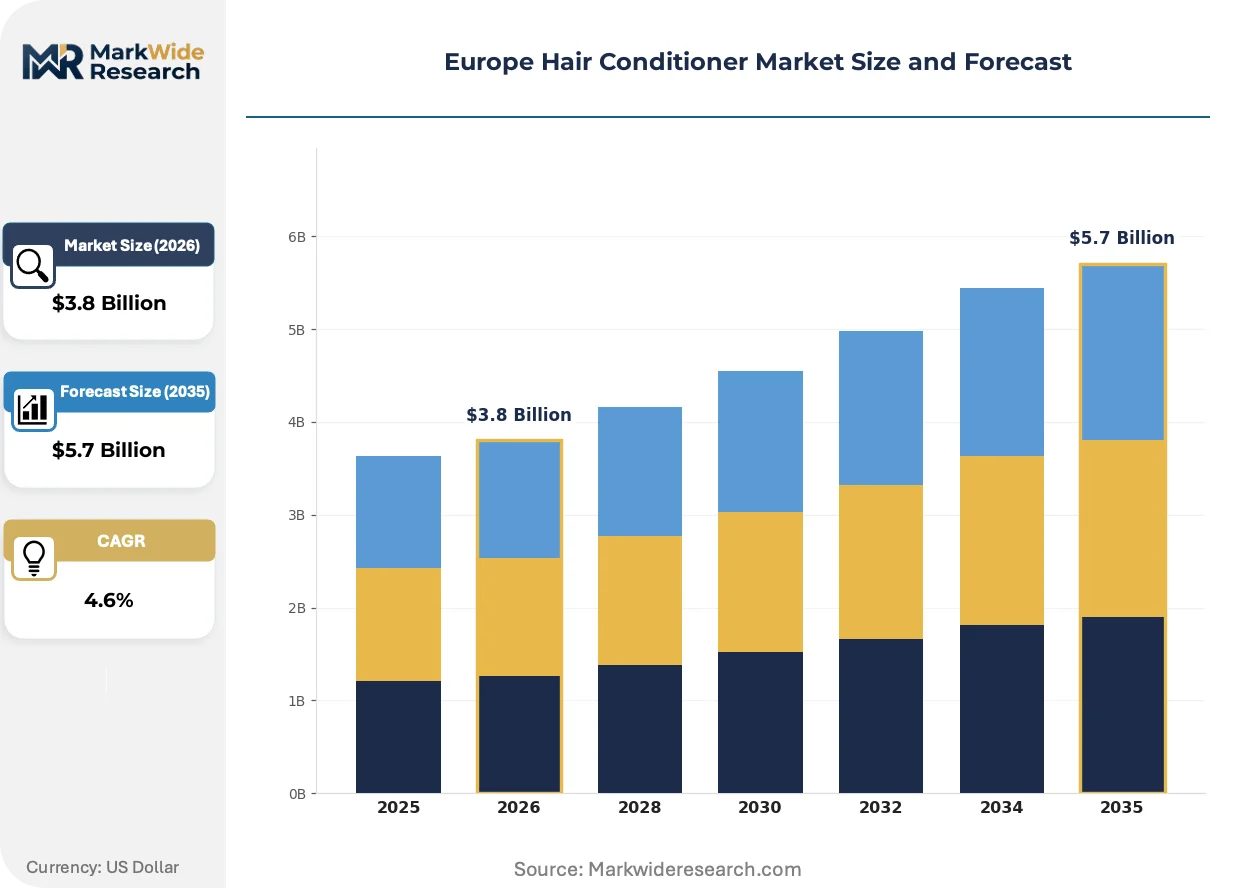
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Repairing, Color-Protecting, Smoothing Hair Type: Curly, Straight, Wavy, Coily Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Drugstores Price Tier: Premium, Mid-Range, Economy, Luxury |
| Companies Covered | Procter & Gamble Company, L'Oréal S.A., Henkel AG & Co. KGaA, Unilever, Shiseido Company Limited, Avon Products Inc., Kao Corporation, Estée Lauder Companies Inc., Coty Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Conditioner Market Shifts & Advancements
European hair conditioner development is pivoting from incremental hydration claims toward measurable scalp microbiome modulation, with instrumentation from adjacent skincare sectors migrating into claims substantiation protocols.
Artificial intelligence-driven formulation screening is automating the identification of synergistic botanical-cationic combinations that manual testing protocols miss. R&D teams at German and French headquarters deploy machine learning models trained on historical stability datasets to compress development cycles. This capability is automating the displacement of traditional empirical testing hierarchies, reallocating laboratory resources toward sensory validation rather than compatibility screening.
REACH Annex XVII expansions enforced by ECHA now mandate pre-market notification for novel preservative systems, extending registration timelines by twelve to eighteen months for reformulated conditioners. The regulation's industrial consequence is a bifurcation between legacy brands with established safety dossiers and challengers facing delayed market entry. Color-protecting variants containing azo-derived pigments face heightened scrutiny, with French ANSM conducting enhanced post-market surveillance on salon-professional SKUs.
Subscription-based replenishment is capturing conditioner purchasers who previously bought on supermarket auto-pilot, with Nordic consumers leading European adoption. Direct-to-consumer platforms displace traditional drugstore stocking by capturing usage-data that enables personalized regimen recommendations. This shift concentrates most visibly in Denmark and Sweden, where digital-native brands now command double-digit shares of premium conditioner volume through owned-channel strategies.
Europe Hair Conditioner Market Segmentation
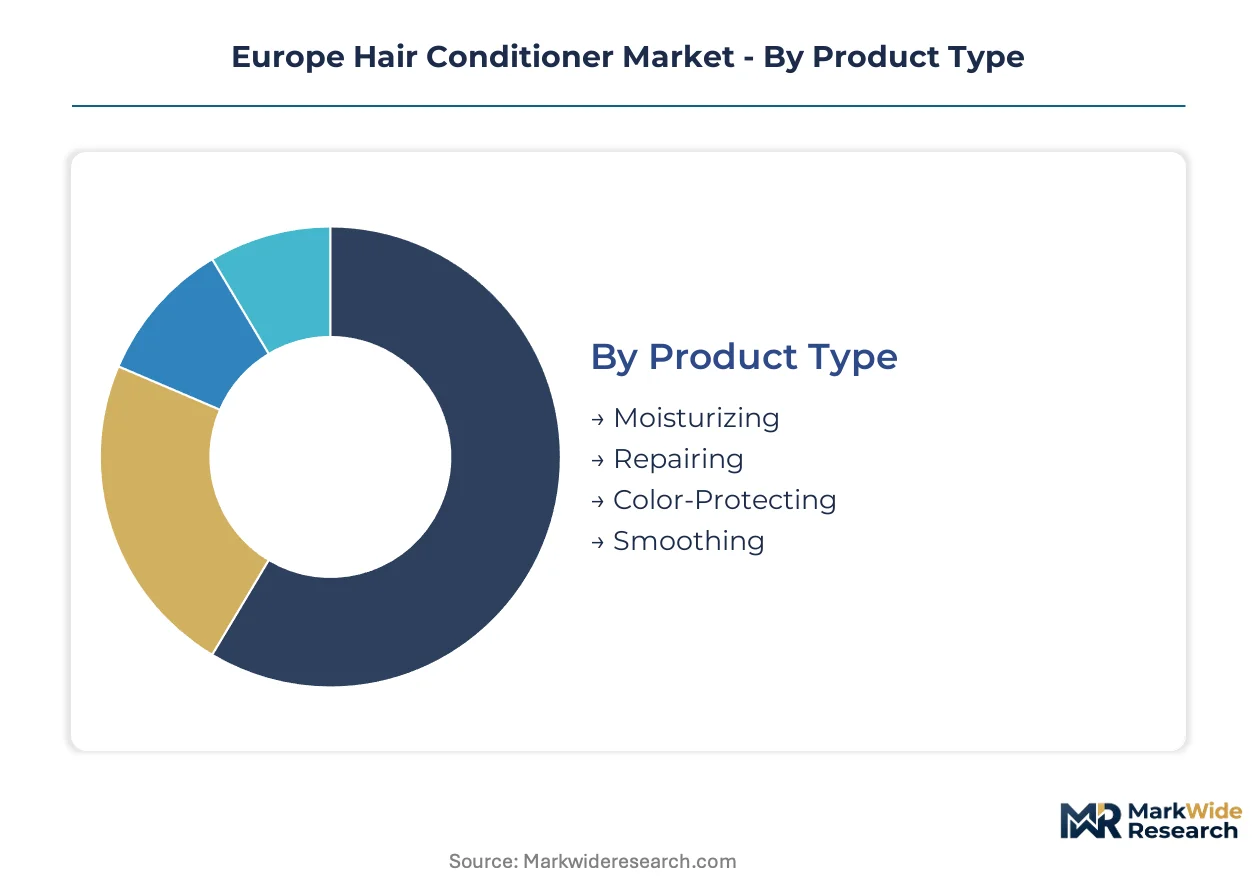
European hair conditioner purchasing patterns fragment across formulation chemistry, hair texture specificity, and channel convenience. Manufacturers must align SKU portfolios with divergent national regulatory thresholds and retailer sustainability mandates.
Product Type:
Supply concentration among German and French contract manufacturers favors emulsion-phase expertise, concentrating volume production in facilities with REACH pre-registration dossiers.
- Moisturizing:Glycerin and panthenol-based formulations dominate mass-market production. German drugstore chains command highest volume offtake for daily-use variants with ECHA-compliant preservative systems.
- Repairing:Keratin and ceramide-enriched conditioners target chemically treated hair with measurable cuticle-sealing claims. Salon professionals in France prescribe these as mandatory post-color protocols, embedding premium SKUs into recurring client revenue streams.
- Color-Protecting:UV-filter and antioxidant complexes extend dye vibrancy. ANSM surveillance of azo-pigment safety elevates compliance costs for challengers without established dossiers.
- Smoothing:Silicone and plant-derived oil emulsions reduce frizz through cuticle alignment. Italian consumers demonstrate highest per-capita preference for heat-activated variants.
Today's leader: Repairing. Tomorrow's challenger: Color-Protecting.
Hair Type:
Formulation R&D investment concentrates on texture-specific rheology, with Paris-based laboratories pioneering curl-pattern specific deposit systems.
- Curly:High-molecular-weight conditioning polymers define coil definition without weight buildup. United Kingdom consumers drive fastest adoption of specialty curl-care sub-brands through Boots and Superdrug pharmacy channels.
- Straight:Lightweight, water-soluble silicones deliver shine without residue. Spanish supermarket volume sustains economy-tier production runs for this segment.
- Wavy:Hybrid formulations balance moisture retention with volume preservation. Nordic direct-to-consumer brands capture premium positioning through personalized regimen algorithms.
- Coily:Dense butter and oil emulsions address porosity challenges in tight curl patterns. Underdeveloped professional infrastructure in Poland creates first-mover openings for salon-distribution partnerships.
Curly commands current margin premiums. Coily offers steepest expansion trajectory as Eastern European distribution matures.
Distribution Channel:
Channel cost structures diverge sharply, with online retail bypassing slotting fees that consume 12-18% of supermarket net revenue.
- Online Retail:Subscription auto-replenishment captures usage-data for personalized recommendations. Danish and Swedish consumers lead European adoption, with digital-native brands commanding double-digit premium volume shares.
- Supermarkets:Mid-range SKUs depend on promotional calendar coordination across Carrefour, Tesco, and REWE networks. Southern European price sensitivity compresses margin recovery.
- Specialty Stores:Sephora and Douglas anchor prestige positioning with in-salon sampling protocols. German consumers demonstrate highest conversion rates from tester to full-size purchase.
- Drugstores:dm-drogerie markt and Rossmann sustain mass-market volume through private-label competition. REACH compliance documentation requirements favor established suppliers with pre-registered safety dossiers.
Online Retail is gaining share fastest. Drugstores defend volume leadership through convenience density.
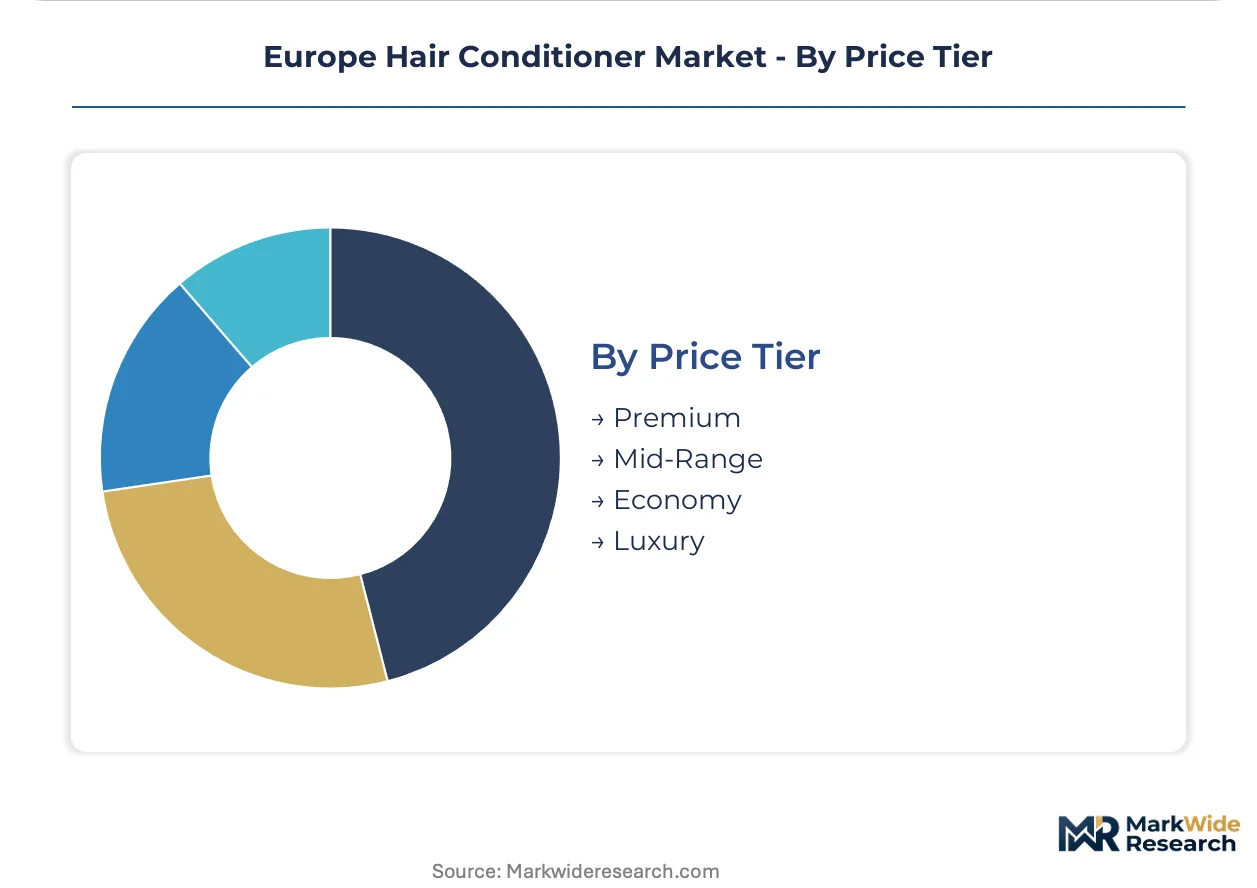
Price Tier:
Raw material cost volatility in palm-derived emollients and biodegradable surfactants compresses mid-range positioning flexibility.
- Premium:Salon-exclusive and professional-aftercare variants command 3-4x mass-market unit economics. French pharmacy channel concentration sustains highest per-liter pricing.
- Mid-Range:Supermarket and drugstore mainstream positioning balances formulation quality with promotional elasticity. Unilever competes aggressively through Southern European retail network density.
- Economy:Private-label and value-brand production concentrates in high-volume German contract manufacturing. Water footprint constraints under EU Green Deal threaten concentrated rinse-off formats in this tier.
- Luxury:Limited-distribution artisan and fragrance-house extensions target gift purchasing occasions. Packaging waste directive compliance costs disproportionately impact small-batch producers.
Premium captures margin concentration. Economy faces structural pressure from sustainability compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest per-capita conditioner expenditure in Europe, while France concentrates salon-professional volume through its pharmacy channel infrastructure. The United Kingdom anchors e-commerce penetration, with Polish and Spanish markets expanding fastest from lower bases.
Germany
dm-drogerie markt and Rossmann sustain mass-market volume through private-label competition and dense retail networks. ECHA REACH compliance documentation requirements favor established suppliers with pre-registered safety dossiers. The Rhine-Ruhr industrial corridor hosts contract manufacturing clusters specializing in emulsion-phase processing for biodegradable surfactant formulations.
France
Salon professionals embed repair-focused conditioners into mandatory post-color client protocols, generating recurring premium SKU revenue. ANSM conducts enhanced post-market surveillance on azo-pigment containing color-protecting variants, elevating compliance costs. Paris-based R&D laboratories pioneer curl-pattern specific deposit systems and scalp microbiome modulation claims.
United Kingdom
Boots and Superdrug pharmacy channels drive fastest adoption of specialty curl-care sub-brands among texture-specific consumers. CSRD reporting requirements pressure mid-tier brands to document supply-chain carbon intensity through certified contract manufacturers. Greater London concentrates direct-to-consumer brand headquarters leveraging subscription auto-replenishment data for personalized regimen algorithms.
Poland
Underdeveloped professional haircare infrastructure creates first-mover openings for salon-distribution partnerships targeting coily hair texture formulations. EU Green Deal water footprint constraints threaten concentrated rinse-off economy-tier products dependent on high-aqueous processing. The Warsaw metropolitan area attracts regional distribution center investments bypassing traditional German wholesale channels.
Spain
Supermarket price sensitivity compresses margin recovery for mid-range SKUs competing through promotional calendar coordination across Carrefour networks. ECHA preservative restrictions under REACH Annex XVII force costly stability re-testing for legacy formulations. Barcelona and Madrid anchor Southern European manufacturing for lightweight silicone formulations serving straight-hair consumer preferences.
Europe Hair Conditioner Market Competitive Landscape
French and German producers anchor the premium tier through R&D-intensive professional formulations; Anglo-Dutch conglomerates hold volume positioning through supermarket network density. The market exhibits consolidated leadership at the top with fragmented mid-tier competition among regional specialists and private-label suppliers. Three archetypes dominate: integrated beauty conglomerates with salon distribution control, drugstore-channel mass-market operators, and digital-native direct-to-consumer challengers. Competitive maneuvering concentrates on sustainability certification races and subscription platform buildouts rather than price warfare.
Among the integrated beauty conglomerates, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify divergent geographic anchoring strategies—Paris-based R&D hub concentration versus German drugstore channel dominance—while Unilever occupies a position bridging mid-range supermarket positioning across Southern European markets. Procter & Gamble Company sits within the mass-market archetype alongside these players, representing scale-driven formulation standardization approaches.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Unilever |
| Shiseido Company Limited |
| Avon Products Inc. |
| Kao Corporation |
| Estée Lauder Companies Inc. |
| Coty Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal water footprint thresholds gate qualified supply for premium-tier conditioner formulations while compressing margin recovery in economy-tier rinse-off segments dependent on high-aqueous processing. REACH-compliant biodegradable surfactant certification now functions as a pricing moat, separating dossier-holding German and French contract manufacturers from import-dependent challengers facing reformulation cost barriers.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for mid-range SKUs as new emulsion-phase facilities undercut legacy German manufacturing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ECHA compliance documentation depth and salon-channel exclusivity. Pricing pressure stems from palm-derived emollient feedstock volatility transmitting directly into European cost structures. Supermarket buyers in Southern Europe exhibit highest price sensitivity, while French pharmacy channel consumers demonstrate lowest elasticity for professional-aftercare variants.
Supply Chain Analysis
Dual-sourcing requirements mandated by major European salon chains and e-commerce platforms compel qualification of at least two REACH-registered contract manufacturers per SKU. Supply concentrates in Germany, France, and Italy, with the Rhine-Ruhr corridor anchoring emulsion-phase expertise for biodegradable surfactant formulations. Raw material dependencies center on Southeast Asian palm-derived emollients, enzymatically processed plant-based cationic surfactants, and specialty preservative chemistries. Single-source vulnerability in palm feedstock supply chains poses structural risk amid Indonesian and Malaysian export policy shifts. Distribution runs through consolidated national distributors with ECHA dossier capabilities, bypassing fragmented regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European hair conditioner hinges on biodegradable surfactant scale economies and subscription-platform data monetization displacing slotting-fee-dependent supermarket channels.
For Market Incumbents: Acquire enzymatic processing capabilities and pre-registered REACH safety dossiers to preempt challenger entry. Consolidate around certified low-footprint contract manufacturers before CSRD reporting requirements harden procurement criteria. Defensive priority centers on locking salon-distribution partnerships in Poland and Romania before infrastructure matures. For New Entrants and Emerging Players: Underserved coily-hair consumers in Eastern European pharmacy channels present first-mover white-space opportunity. Nordic direct-to-consumer subscription platforms offer penetrable entry with highest European auto-replenishment adoption rates. Go-to-market angle should leverage personalized regimen algorithms using usage-data capture bypassing traditional retail gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap REACH-compliant contract manufacturers because ECHA registration timelines create twelve-to-eighteen month entry barriers for unqualified challengers. Long-term viability concentrates on facilities with established biodegradable surfactant processing and salon-channel relationships. Watch enzymatic cationic surfactant cost parity with silicone benchmarks as inflection indicator for reformulation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Scale-Up | REACH Annex XVII compliance converts into shelf-access advantage at dm-drogerie markt and Douglas. |
| Direct-to-Consumer Subscription Launch | Nordic consumer adoption patterns enable margin recovery bypassing Carrefour and Tesco slotting fees. |
| Salon-Distribution Partnership Expansion | Underdeveloped professional infrastructure in Warsaw and Krakow creates first-mover positioning for coily-hair formulations. |
| CSRD-Aligned Supply Chain Certification | Documented carbon intensity reporting secures preferred listing as retailers enforce sustainability criteria. |
| AI-Driven Formulation Screening Investment | Machine learning compression of development cycles reallocates laboratory resources toward sensory validation. |
Research Methodology
Bottom-up salon and pharmacy channel modeling reconciled against top-down contract manufacturing capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, category buyers at Boots and Sephora, procurement leads at German drugstore chains, and salon distribution managers combined with secondary validation from ECHA registration databases, EU customs trade data, and Nielsen retail audit filings. Triangulation across stakeholder inputs and documentary sources ensures cross-verification of volume and value estimates.
Historical trendline analysis of conditioner SKU velocities across moisturizing, repairing, color-protecting, and smoothing segments established baseline growth patterns over the projection horizon. Segmentation modeling incorporated formulation chemistry, hair texture specificity, distribution channel cost structures, and price tier positioning. CAGRs were derived from regression analysis of salon-aftercare protocol adoption rates and subscription platform penetration curves, with enzymatic surfactant cost trajectories and REACH compliance investment cycles as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online retail and premium salon channels carry tighter precision than fragmented economy-tier supermarket sales. Forecasts reflect assumptions regarding ECHA enforcement consistency, palm feedstock supply stability, and EU Green Deal water threshold implementation timelines. Deviation in biodegradable surfactant cost parity achievement or REACH Annex XVII expansion scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Colombia Cosmetics Products Market