
 Asia Pacific Herbal Beauty Products Market | 2026-2036
Asia Pacific Herbal Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Herbal Beauty Products Market Outlook
Aftermarket service revenue from ayurvedic consultation and personalized regimen subscriptions is reshaping how value migrates from product-only transactions to recurring wellness relationships. Himalaya Wellness Company leverages its integrated herb cultivation networks across the Himalayan foothills to control raw material quality from seed to shelf. Dabur India Ltd. anchors its competitive stance through deep distribution into India's tier-two and tier-three retail channels. Shiseido Company, Limited differentiates by blending Japanese fermentation biotechnology with traditional Asian botanical extracts in premium skincare formulations.
Asia Pacific herbal beauty products encompass cosmeceutical formulations derived from plant extracts, essential oils, and naturally occurring bioactive compounds, typically manufactured through cold-press extraction, steam distillation, or supercritical CO2 processing to preserve phytochemical integrity. These products serve therapeutic and aesthetic functions including skin barrier repair, melanin regulation, and scalp microbiome balancing. Skincare dominates value generation due to higher per-unit pricing and repeat purchase frequency among millennial consumers seeking clean-label alternatives. Online retail channels represent the fastest-expanding distribution vector, though specialty stores retain margin density through experiential consultation services. Ginseng-based formulations command premium positioning in East Asian markets where traditional medicine associations strengthen brand equity.
India's CDSCO and BIS enforce progressive tightening of heavy-metal limits and labeling disclosures for ayurvedic cosmetics, compelling reformulation investments across domestic manufacturers. South Korea's MFDS and China's NMPA maintain divergent botanical ingredient approval lists, fragmenting regional product registration strategies and extending time-to-market for multi-country portfolios. Stakeholders must monitor regulatory harmonization initiatives between ASEAN member states while building flexible formulation platforms that accommodate jurisdiction-specific compliance thresholds.
Market Dynamics
Millennial consumers across Asia Pacific are forcing formulation transparency and traceability standards that reshape competitive positioning. India's PLI scheme for herbal formulations and China's tightening GB standards create divergent compliance architectures that manufacturers must navigate simultaneously.
Growth Catalysts
- Regulatory Harmonization Pressure:ASEAN member states are advancing mutual recognition frameworks for botanical ingredient safety assessments, reducing redundant testing burdens for multi-market portfolios.
- Fermentation Biotechnology Convergence:Japanese koji and Korean makgeolli-derived bioactive extraction methods are unlocking novel phytochemical delivery systems with enhanced skin penetration profiles.
- Urban Cluster Demand Density:Maharashtra and Gujarat states in India alongside Seoul-Incheon corridor in South Korea concentrate purchasing power for premium ayurvedic and hanbang formulations.
Market Restraints
- Raw Material Volatility:Himalayan foothill herb cultivation faces climate-induced yield variability, compressing margins for vertically integrated suppliers dependent on captive sourcing.
- Regulatory Fragmentation:Divergent botanical approval lists between South Korea's MFDS and China's NMPA extend product registration timelines and inflate compliance overhead.
- Heavy Metal Compliance Costs:India's CDSCO progressive tightening of arsenic and lead limits for ayurvedic cosmetics forces reformulation investments across domestic manufacturing bases.
Strategic Opportunities
- Subscription Wellness Models:Personalized regimen services and ayurvedic consultation platforms are migrating value from transactional product sales to recurring revenue relationships.
- Clean-Label Certification Tailwinds:India's BIS voluntary organic cosmetics standards and China's green manufacturing incentives reward early compliance investments with preferential retail placement.
- Tier-Two Distribution Penetration:India's tier-two and tier-three retail channels remain underpenetrated for premium herbal skincare relative to saturated metro markets.
Industry Challenges
- Phytochemical Standardization Complexity:Batch-to-batch bioactive consistency in cold-press and supercritical CO2 extraction requires sophisticated analytical chemistry capabilities scarce in contract manufacturing networks.
- Multi-Jurisdiction Registration Friction:Staggered approval timelines across MFDS, NMPA, and CDSCO fragment product launch synchronization and strain working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Herbal Beauty Products Market |
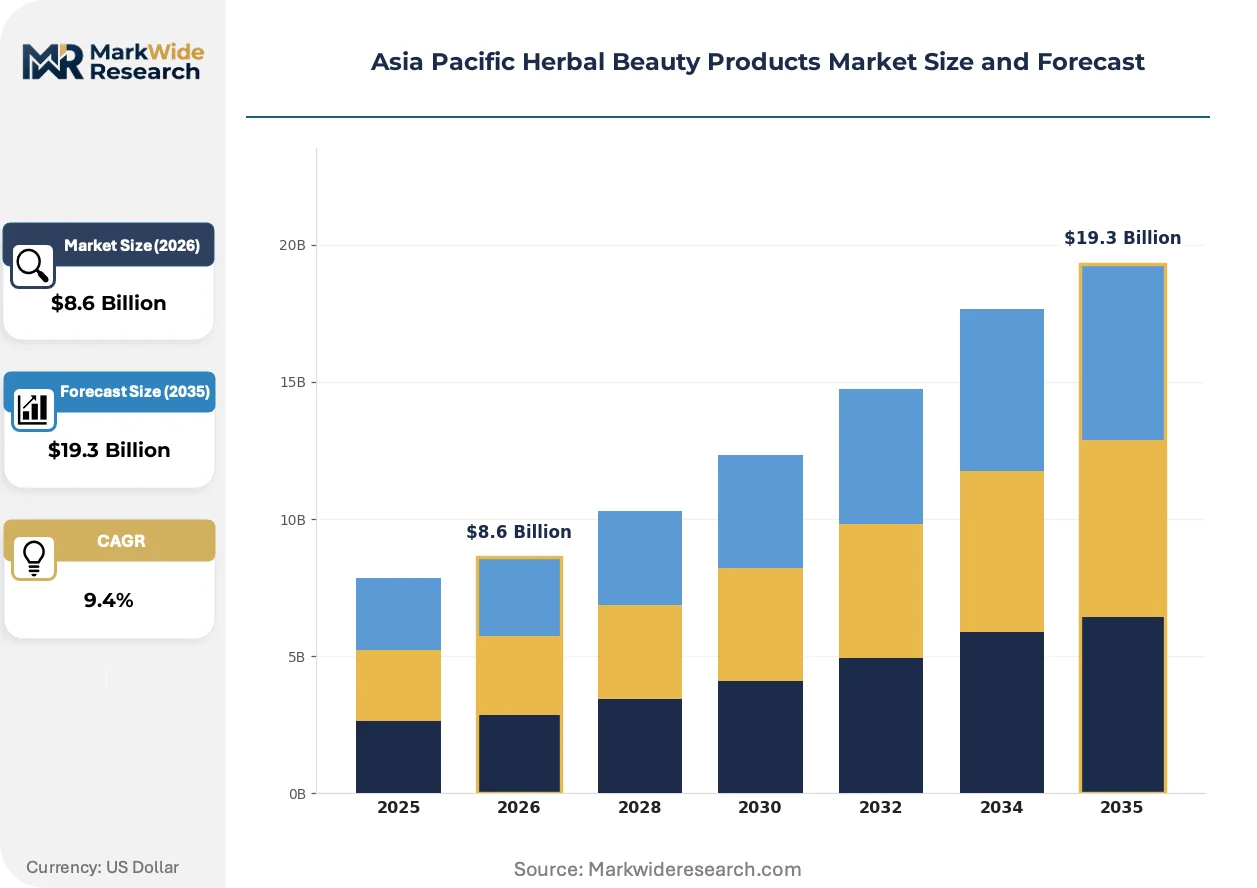
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $19.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient: Aloe Vera, Green Tea, Turmeric, Ginseng Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Consumer Age Group: Teens, Millennials, Gen X, Seniors |
| Companies Covered | Himalaya Wellness Company, Dabur India Ltd., Patanjali Ayurved Ltd., Lotus Herbals Pvt. Ltd., Forest Essentials, Shahnaz Husain Group, Shanghai Jahwa United Co., Ltd, Innisfree, Shiseido Company, Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Herbal Beauty Products Market Strategic Shifts
Digital traceability infrastructure and biotechnology-enhanced extraction methods are converging to redefine quality assurance and efficacy claims across Asia Pacific herbal beauty. These developments compress traditional supply chain intermediaries while elevating scientific substantiation requirements.
Blockchain-enabled seed-to-shelf tracking is virtualizing provenance verification for Himalayan herb supply chains. Premium skincare brands in South Korea and Japan are deploying distributed ledger systems to authenticate wild-harvested botanical sourcing claims. This technology is virtualizing third-party certification bodies by embedding compliance documentation directly into consumer-facing digital interfaces.
China's NMPA is implementing stricter GB standards for cosmetic safety assessments of traditional Chinese medicine-derived ingredients. The regulations mandate expanded toxicological testing for botanical extracts previously grandfathered under historical use exemptions. Domestic manufacturers are responding by restructuring R&D budgets toward standardized phytochemical characterization protocols.
Millennial buyers are compressing purchase cycles through social commerce discovery and direct-to-brand engagement. Specialty stores with experiential consultation services are ceding traffic to live-streaming commerce platforms in China and influencer-curated marketplaces in India. This behavioral shift is most pronounced in Seoul and Mumbai, where digital-native consumers prioritize algorithmic personalization over in-store sensory evaluation.
Asia Pacific Herbal Beauty Products Market Segmentation
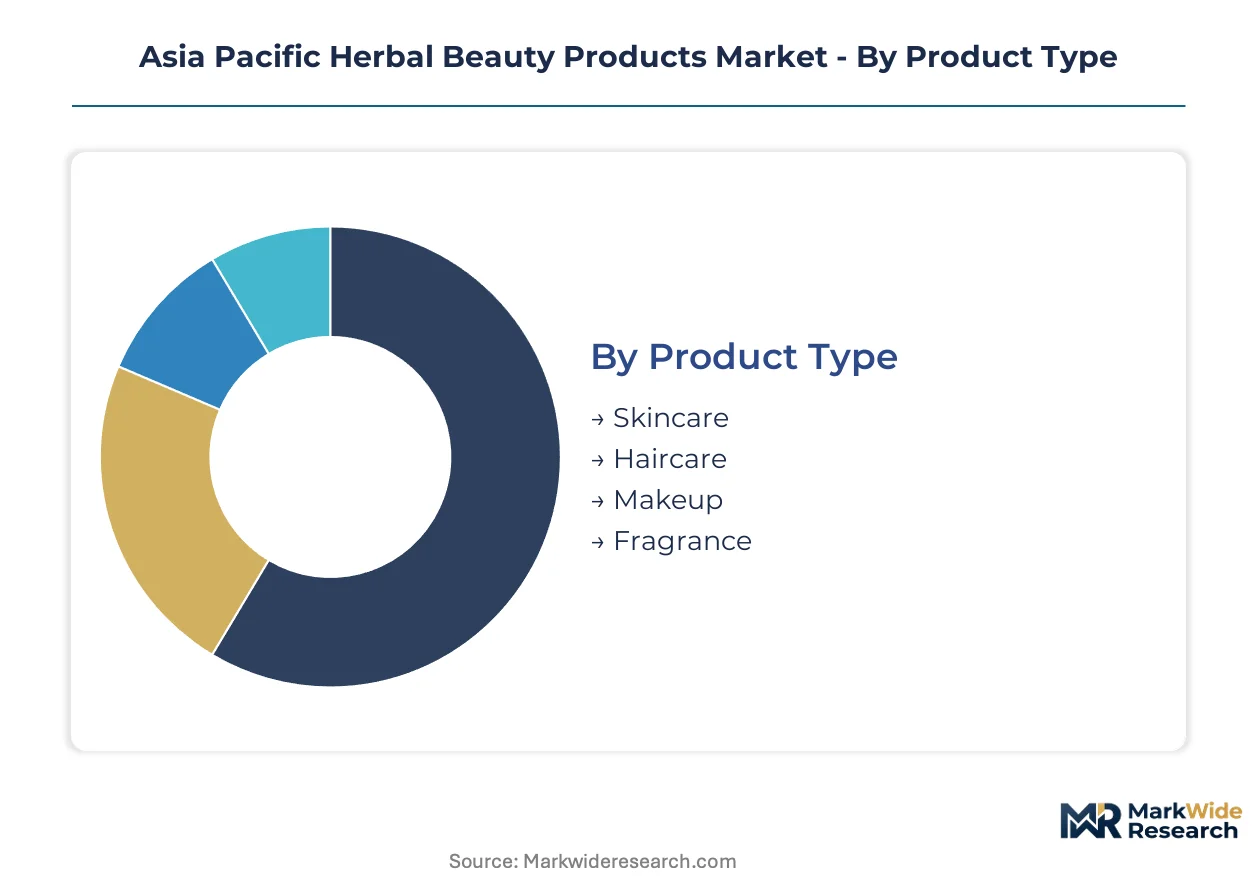
Asia Pacific herbal beauty products fragment across four distinct dimensions that shape procurement priorities and margin structures. Product type and ingredient sourcing determine formulation complexity and regulatory compliance burden. Distribution channel selection and age-targeted positioning dictate working capital intensity and customer acquisition economics.
Product Type:
Application determines pricing power and repeat purchase cadence across the Asia Pacific herbal beauty landscape.
- Skincare:Cold-pressed botanical serums and fermentation-enhanced essences command per-unit premiums through bioactive standardization. Maharashtra and Gujarat states concentrate demand for ayurvedic facial oils as urban millennials prioritize barrier repair formulations. CDSCO heavy-metal compliance costs compress margins for domestic manufacturers reformulating traditional recipes.
- Haircare:Scalp microbiome balancers and herbal anti-dandruff treatments leverage supercritical CO2 extraction to preserve volatile compounds. Seoul-Incheon corridor consumers drive premium positioning for hanbang-inspired scalp tonics. MFDS botanical approval requirements extend registration timelines for multi-country portfolios.
- Makeup:Mineral-based foundations and plant-derived colorants serve clean-label preferences with shorter ingredient lists.
- Fragrance:Steam-distilled essential oil blends target niche wellness positioning through aromatherapy associations.
Skincare commands the established base. The steepest expansion runs through haircare as scalp health positioning gains traction.
Ingredient:
Sourcing geography and extraction method determine phytochemical consistency and supply security.
- Aloe Vera:Cold-pressed leaf gel formulations dominate soothing and hydration claims with established supply chains across Rajasthan and Tamil Nadu cultivation zones. BIS organic certification standards reward early compliance investments with preferential retail placement in Indian metro markets.
- Green Tea:Catechin-standardized extracts from Japanese and Korean processing facilities anchor antioxidant positioning. NMPA expanded toxicological testing requirements for TCM-derived ingredients force restructuring of R&D budgets toward characterization protocols.
- Turmeric:Curcuminoid-rich rhizome extracts serve traditional ayurvedic whitening and anti-inflammatory applications.
- Ginseng:Saponin-standardized root extracts command premium positioning in East Asian markets through traditional medicine brand equity.
Ginseng anchors premium tier pricing. Green tea extraction methods are climbing the fastest as biotechnology convergence unlocks novel delivery systems.
Distribution Channel:
Channel selection shapes margin capture and customer relationship depth.
- Online Retail:Algorithmic personalization and live-streaming commerce platforms compress discovery-to-purchase cycles. Mumbai and Seoul digital-native consumers prioritize convenience over in-store sensory evaluation. Social commerce integration enables direct-to-brand engagement bypassing traditional wholesale markups.
- Specialty Stores:Experiential consultation services retain margin density through regimen customization and ayurvedic diagnostic tools. Tier-two and tier-three Indian cities remain underpenetrated relative to saturated metro markets.
- Supermarkets:Mass-market herbal variants compete on shelf placement and promotional frequency.
- Pharmacies:Dermocosmetic positioning leverages clinical credibility for sensitive skin formulations.
Specialty stores hold the established margin structure. Online retail channels are gaining share fastest as millennial purchase behavior shifts toward mobile-first discovery.
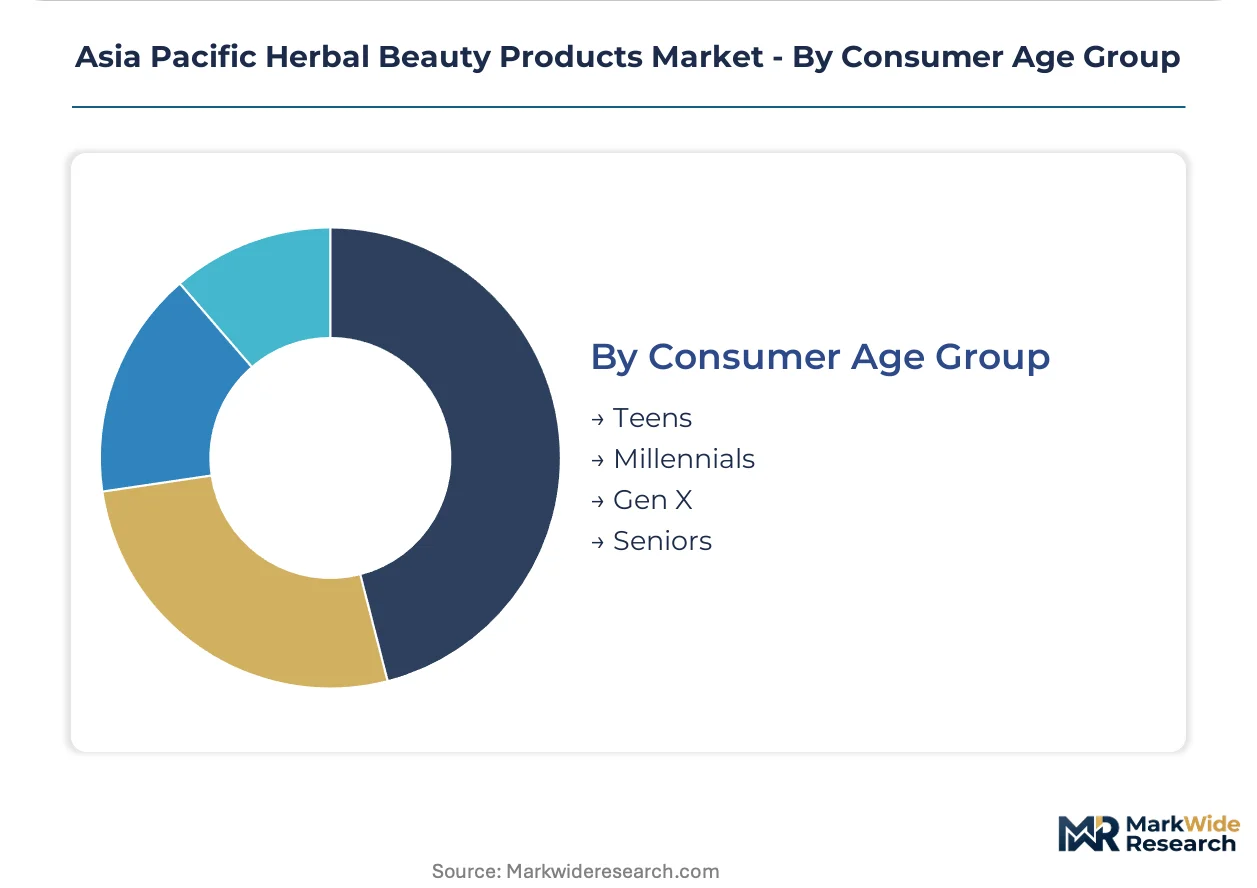
Consumer Age Group:
Life-stage positioning determines formulation complexity and communication strategy.
- Millennials:Transparency demands and traceability expectations force seed-to-shelf documentation and blockchain-enabled provenance verification. Himalayan herb supply chains virtualize compliance through distributed ledger systems embedded in consumer-facing interfaces.
- Gen X:Preventive aging formulations with standardized bioactive concentrations target established skincare routines.
- Teens:Acne-focused botanical treatments with simplified ingredient lists address entry-level clean-label preferences.
- Seniors:Barrier repair and melanin regulation claims serve age-related skin physiology with gentler extraction methods.
Millennials concentrate purchasing power for premium positioning. Teens represent the steepest expansion trajectory as early clean-label adoption extends into formative brand relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
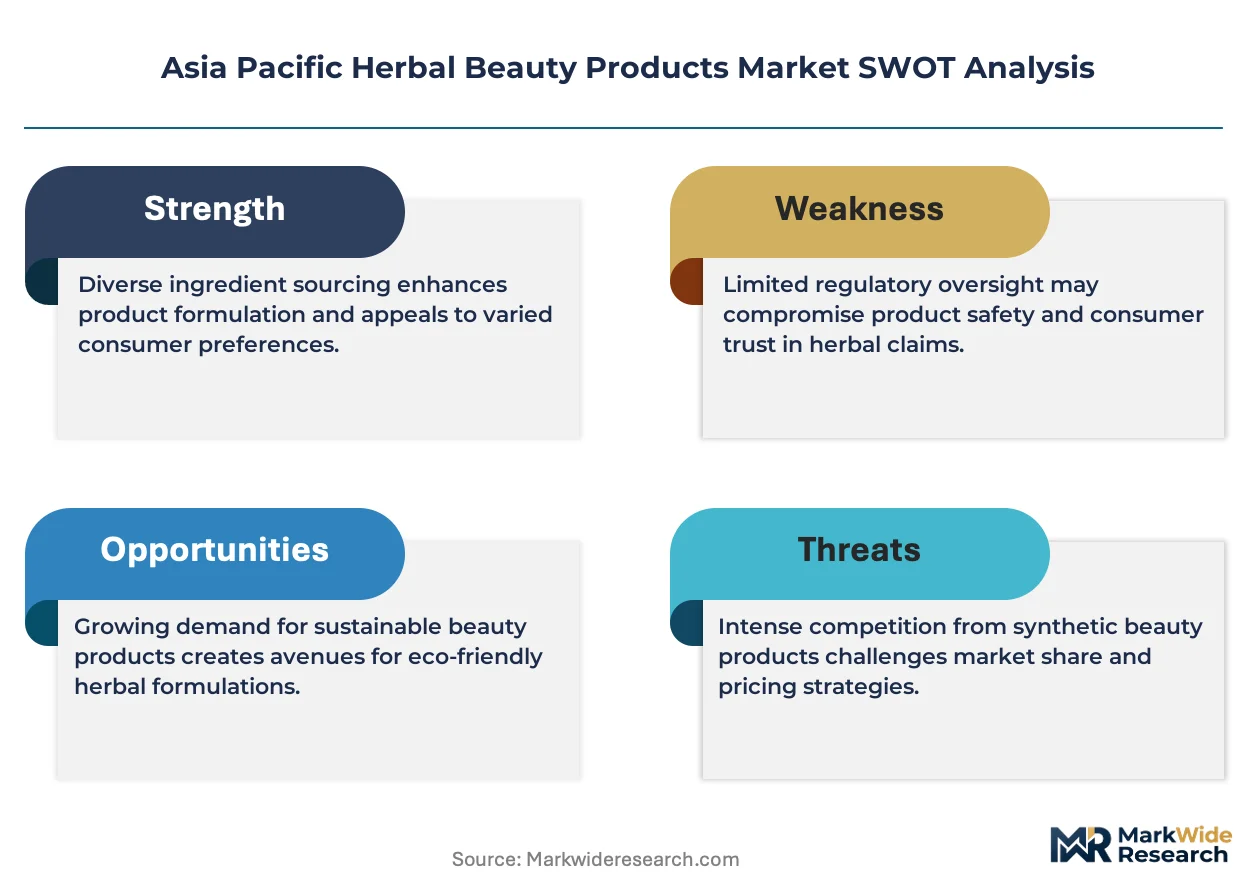
Cultivation networks across the Himalayan foothills and fermentation biotechnology clusters in Northeast Asia concentrate supply-side capabilities for herbal beauty manufacturing. CDSCO, NMPA, and MFDS regulatory divergence fragments product registration pathways across the region. Maharashtra, Gujarat, and the Seoul-Incheon corridor concentrate demand density for premium ayurvedic and hanbang formulations.
India
Maharashtra and Gujarat states drive ayurvedic skincare demand as urban millennials prioritize barrier repair formulations with traceable herb sourcing. CDSCO progressive tightening of arsenic and lead limits forces domestic manufacturers into reformulation investments. The Himalayan foothill cultivation zones supply captive raw material networks for vertically integrated producers.
China
NMPA expanded toxicological testing requirements for traditional Chinese medicine-derived ingredients restructure domestic R&D budgets toward phytochemical characterization protocols. GB standards for cosmetic safety assessments mandate compliance documentation previously exempt under historical use clauses. Yangtze River Delta manufacturing clusters concentrate fermentation biotechnology capabilities for botanical extraction.
South Korea
MFDS botanical ingredient approval lists diverge from Chinese and Indian regulatory frameworks, extending registration timelines for multi-country portfolios. Seoul-Incheon corridor consumers command premium positioning for hanbang-inspired scalp tonics and ginseng-based skincare. Korean makgeolli-derived bioactive extraction methods unlock novel phytochemical delivery systems.
Japan
METI oversight of cosmetic safety standards converges with traditional koji fermentation biotechnology in premium skincare development. Japanese manufacturers blend fermentation-enhanced extraction with standardized botanical actives for melanin regulation claims. Kanto region R&D clusters advance supercritical CO2 processing capabilities for volatile compound preservation.
Australia
TGA regulatory frameworks for complementary medicines create alternative approval pathways for herbal beauty products with therapeutic positioning. Clean-label certification demand from export-oriented consumers rewards early organic compliance investments. Sydney and Melbourne concentrate distribution infrastructure for Asia-Pacific market access.
Asia Pacific Herbal Beauty Products Market Competitive Environment
Ayurvedic heritage houses and fermentation biotechnology specialists split the market across distinct value-creation models. The competitive structure organizes around three strategic archetypes: vertically integrated herb cultivators controlling seed-to-shelf supply chains, distribution-heavy domestic incumbents penetrating tier-two and tier-three retail channels, and premium biotechnology blenders commanding per-unit premiums through scientific substantiation. Capacity expansion in Himalayan foothill cultivation zones and technology licensing for standardized extraction methods represent dominant competitive moves.
Within the ayurvedic heritage tier, Himalaya Wellness Company and Dabur India Ltd. exemplify contrasting strategic positioning. Himalaya anchors the vertically integrated archetype through captive herb cultivation networks. Dabur occupies the distribution-depth position with penetration into India's secondary retail markets. Shiseido Company, Limited represents the biotechnology convergence archetype, blending Japanese fermentation methods with traditional botanical extracts.
| Leading Market Players |
|---|
| Himalaya Wellness Company |
| Dabur India Ltd. |
| Patanjali Ayurved Ltd. |
| Lotus Herbals Pvt. Ltd. |
| Forest Essentials |
| Shahnaz Husain Group |
| Shanghai Jahwa United Co., Ltd |
| Innisfree |
| Shiseido Company, Limited |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta fermentation biotechnology clusters is forcing contract manufacturers to absorb margin compression while premium Himalayan herb suppliers maintain pricing power through captive cultivation networks. This utilization asymmetry rewards backward-integrated producers with raw material sovereignty and exposes toll manufacturers to cost pass-through demands from CDSCO compliance investments.
Pricing Analysis
India's BIS voluntary organic cosmetics standards dictate the pricing tier structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with blockchain-verified Himalayan sourcing commanding substantial premiums. Cost compression in the standard tier is intensifying because CDSCO heavy-metal compliance investments inflate domestic manufacturing overhead. Tier-two and tier-three retail channels exhibit highest price sensitivity, while Seoul-Incheon corridor millennials demonstrate lowest elasticity for ginseng-based formulations.
Supply Chain Analysis
Extended payment terms from South Korean makgeolli-derived extraction specialists are straining working capital for mid-tier formulators. Geographic supply concentrates in India's Himalayan foothills, China's Yangtze River Delta, and South Korea's Seoul-Incheon corridor. Raw material dependencies center on wild-harvested ginseng roots, cold-pressed aloe vera gel, and supercritical CO2-processed green tea catechins. Single-source vulnerability from climate-induced Himalayan herb yield variability threatens batch consistency. Distribution runs through specialty stores in saturated metros and live-streaming commerce platforms in emerging urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millennial buyer consolidation around algorithmic personalization platforms is shifting negotiation leverage toward retail aggregators and away from fragmented brand portfolios. This concentration elevates channel control as the decisive competitive variable.
For Market Incumbents: Harden regulatory compliance infrastructure against CDSCO, NMPA, and MFDS divergence by building flexible formulation platforms accommodating jurisdiction-specific thresholds. Deepen backward integration into Himalayan foothill cultivation networks to secure phytochemical consistency against climate volatility. Channel control through tier-two and tier-three retail penetration remains essential as metro markets saturate. For New Entrants and Emerging Players: Tier-two Indian cities with underpenetrated specialty store infrastructure represent the most penetrable entry point for premium ayurvedic positioning. Subscription wellness models with personalized regimen services offer defensible recurring revenue relationships against transactional competitors. A go-to-market angle leveraging blockchain-enabled provenance verification targets millennial transparency demands in Seoul and Mumbai. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated herb cultivators with seed-to-shelf quality control and established CDSCO compliance track records. Long-term viability rests on regulatory navigation capabilities across fragmented Asia Pacific approval frameworks. The signal to watch is ASEAN mutual recognition framework advancement reducing redundant testing burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Himalayan Cultivation | Captive herb sourcing secures phytochemical consistency against climate-induced yield volatility. |
| Blockchain Provenance Verification Deployment | Distributed ledger systems virtualize compliance documentation for millennial transparency demands. |
| Tier-Two Distribution Channel Expansion | Secondary Indian cities remain underpenetrated relative to saturated metro retail markets. |
| Fermentation Biotechnology Licensing | Korean makgeolli-derived extraction methods unlock novel bioactive delivery systems. |
| Regulatory Harmonization Platform Investment | Flexible formulation architectures accommodate divergent CDSCO, NMPA, and MFDS thresholds. |
Study Parameters
A spread of perspectives from brand managers at ayurvedic heritage houses, category buyers at specialty retailers, supply planners at fermentation biotechnology facilities, and regulatory affairs leads at multi-market formulators converged on the working assumptions. Secondary validation drew from CDSCO cosmetic safety filings, NMPA GB standard documentation, MFDS botanical approval registers, and ASEAN harmonization initiative records. Bottom-up demand modeling and top-down supply capacity assessments triangulated volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, ingredient sourcing geography, distribution channel, and consumer age cohort. CAGRs emerged from fitted growth curves calibrated against historical penetration patterns and regulatory milestone timelines. Forecast inputs included CDSCO heavy-metal limit progression schedules and NMPA toxicological testing requirement phase-ins.
Macroeconomic conditions sit as an overlay; deviation in regional consumer discretionary spending or cross-border trade facilitation would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and biotechnology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Hairstyling Products Market