
 Middle East Herbal Shampoo Market | 2026-2036
Middle East Herbal Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Herbal Shampoo Market Foresight
Salon professionals are reorganizing procurement priorities across the Middle East, shifting from conventional chemical-based products to botanical formulations that reduce scalp irritation complaints. Dabur India Limited leverages its Ayurvedic heritage to anchor distribution through specialty beauty retailers in the GCC. Himalaya Drug Company sustains manufacturing scale advantages via captive herb cultivation networks. VLCC Personal Care Ltd. differentiates through clinic-salon hybrid channels that bundle diagnostic services with product recommendations.
Middle East herbal shampoo denotes a surfactant-based cleansing preparation incorporating plant-derived extracts such as aloe vera polysaccharides, tea tree oil terpinen-4-ol, or henna leaf tannins as functional actives, manufactured through cold-process emulsification to preserve bioactive integrity, primarily serving consumers seeking alternatives to synthetic preservative systems. Moisturizing variants occupy the largest volume share as arid climate conditions elevate hydration positioning. Hair Growth formulations register the fastest expansion, driven by mineral oil avoidance trends among male demographics. Anti-Dandruff SKUs retain margin concentration due to longer replacement cycles and higher per-unit pricing.
Saudi Arabia's SFDA mandates full botanical ingredient traceability for cosmetic registrations, while the UAE's MOHAP enforces halal certification compliance across personal care imports. These frameworks elevate compliance costs for new entrants but reinforce quality signaling for established brands. Stakeholders must monitor evolving Gulf standardization initiatives that could unify labeling requirements across GCC customs territories.
Market Dynamics
Salon professionals across the GCC are reorganizing procurement priorities, abandoning conventional chemical-based products for botanical formulations that reduce scalp irritation complaints and align with tightening disclosure mandates from Saudi Arabia's SFDA.
Growth Catalysts
- SFDA Ingredient Disclosure Mandates:Saudi Arabia's tightened cosmetic registration rules force reformulation toward transparent botanical sourcing, accelerating premium herbal SKU development.
- Arid Climate Hydration Demand:Moisturizing variants dominate volume as desert conditions elevate consumer willingness to pay for aloe vera polysaccharide formulations.
- Halal Certification Alignment:The UAE's MOHAP enforcement across personal care imports creates compliant market access for sulfate-free entrants.
Market Restraints
- Captive Herb Cultivation Requirements:Cold-process emulsification demands bioactive preservation that locks suppliers into multi-year agricultural contracts with Indian and Egyptian growers.
- Traceability Compliance Costs:Full botanical ingredient documentation for SFDA registration elevates new entrant barriers beyond mid-tier capital thresholds.
- Synthetic Surfactant Substitution:Conventional sulfate-based shampoos retain price advantage in mass retail channels across price-sensitive North African markets.
Strategic Opportunities
- Clinic-Salon Hybrid Channels:Diagnostic-service bundling with product recommendations opens margin capture in Dubai-Abu Dhabi corridor premium positioning.
- Hair Growth Male Demographics:Mineral oil avoidance trends among Gulf male consumers create expansion space for caffeine and saw palmetto formulations.
- GCC Standardization Convergence:Pending Gulf customs territory labeling unification would streamline multi-country distribution for compliant established brands.
Industry Challenges
- Cold-Process Technical Talent Scarcity:Bioactive integrity preservation requires specialized emulsification chemists concentrated in Indian and Lebanese formulation hubs.
- Halal Certification Timeline Compression:MOHAP compliance documentation cycles extend product launch windows by four to six months versus conventional cosmetic registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Herbal Shampoo Market |
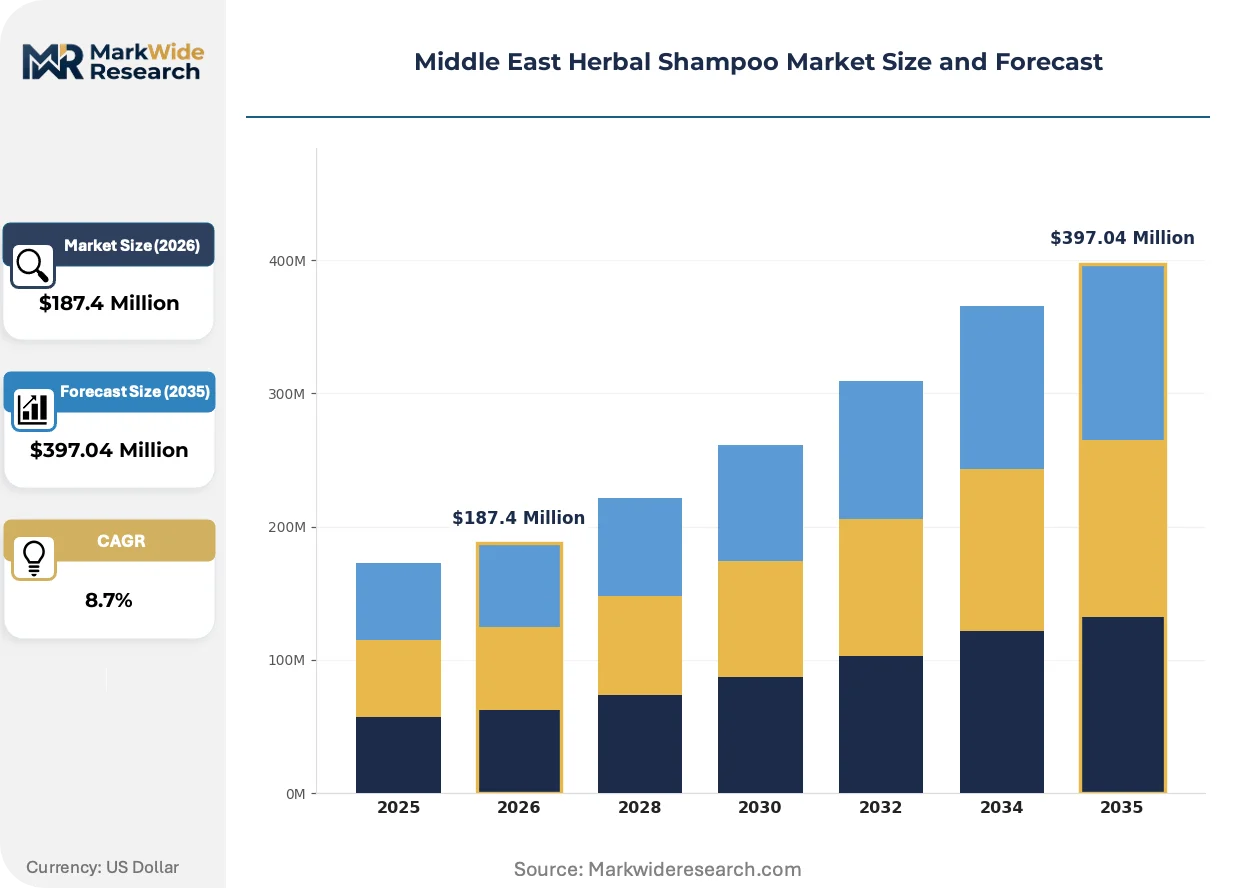
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Dandruff, Moisturizing, Hair Growth, Color Protect Ingredient Type: Aloe Vera, Tea Tree Oil, Henna, Coconut Oil End User: Women, Men, Children, Salons Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies |
| Companies Covered | Unilever, Bio Veda Action Research Co., Dabur India Limited, VLCC Personal Care Ltd., Khadi Global, Himalaya Drug Company, Patanjali Ayurved Limited, Emami Limited, Procter & Gamble, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Herbal Shampoo Market Shifts & Advancements
Formulation science and distribution architecture are undergoing parallel transformation across Middle East herbal shampoo markets, with technology fragmentation and regulatory tightening reshaping competitive entry points.
Supercritical CO2 extraction technology is fragmenting botanical active concentration methods across premium manufacturing facilities. Cold-process emulsification adopters in UAE-based production sites are capturing shelf space from heat-degraded competitors. This fragmentation is compressing batch consistency advantages previously held by established Ayurvedic suppliers.
Saudi Arabia's SFDA botanical traceability mandates are forcing ingredient documentation retrofits across existing cosmetic registrations. Manufacturers must now submit full supply chain audits for tea tree oil and henna leaf sourcing. Anti-dandruff SKUs face the steepest compliance recertification burdens due to longer replacement cycles locking in legacy formulations.
Salon professionals are consolidating procurement through institutional sulfate-free contracts that bundle diagnostic training with volume commitments. Traditional distributor networks in Kuwait and Bahrain are losing share to direct-manufacturer relationships. This channel compression is most visible in Dubai's Jumeirah salon cluster, where premium positioning now requires exclusive botanical line partnerships.
Middle East Herbal Shampoo Market Segmentation
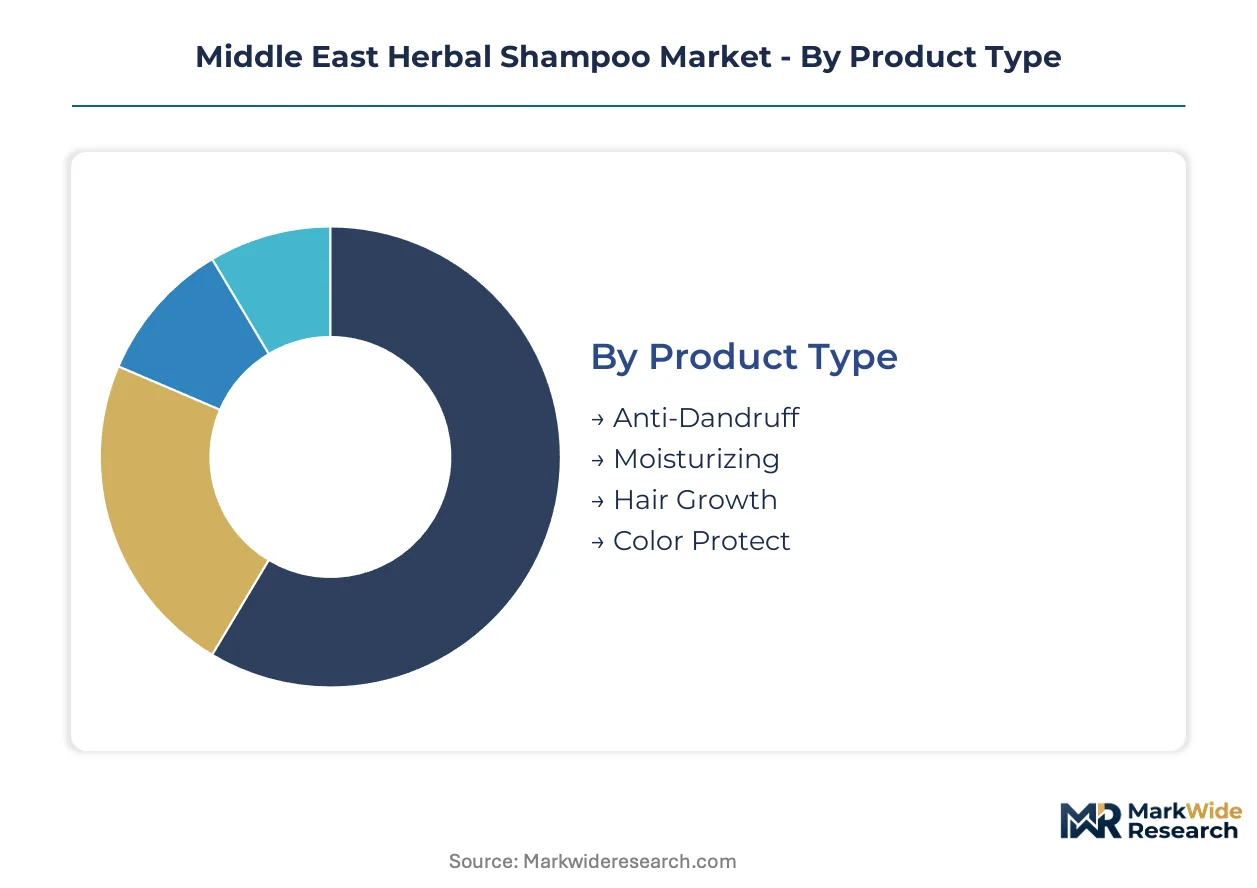
Segmentation in Middle East herbal shampoo markets reveals distinct procurement patterns across arid-climate hydration needs, halal certification requirements, and institutional salon purchasing. Each dimension carries regulatory and technical implications that reshape competitive entry points.
Product Type:
Domestic formulation development concentrates in UAE and Saudi manufacturing corridors, while export-led SKU innovation flows from Indian Ayurvedic laboratories serving GCC distribution.
- Moisturizing:Aloe vera polysaccharide formulations dominate volume through cold-process emulsification preserving bioactive integrity. Demand concentrates in Dubai-Abu Dhabi corridor retail where arid climate conditions elevate consumer willingness to pay for hydration positioning. Saudi Arabia's SFDA disclosure mandates accelerate premium SKU development in this category.
- Hair Growth:Caffeine and saw palmetto formulations target mineral oil avoidance trends among Gulf male demographics. Clinic-salon hybrid channels in the UAE bundle diagnostic services with product recommendations, opening margin capture opportunities. This segment climbs the fastest as institutional procurement shifts toward sulfate-free alternatives.
- Anti-Dandruff:Tea tree oil terpinen-4-ol formulations retain margin concentration due to longer replacement cycles and higher per-unit pricing.
- Color Protect:Henna leaf tannin variants serve color-treated hair maintenance in specialty beauty retailers across Kuwait and Bahrain.
Moisturizing holds the largest share; momentum sits with Hair Growth.
Ingredient Type:
Cost tier stratification separates captive cultivation investments from spot-market sourcing, with premium positioning requiring multi-year agricultural contracts.
- Aloe Vera:Polysaccharide extraction demands supercritical CO2 technology for bioactive concentration in UAE-based production sites. Volume concentrates in moisturizing variants where desert climate conditions drive repeat purchase frequency.
- Tea Tree Oil:Terpinen-4-ol standardization requires full supply chain audits for SFDA registration compliance. Anti-dandruff SKUs face steepest recertification burdens due to legacy formulation lock-in.
- Henna:Leaf tannin sourcing from Egyptian growers supports color protect positioning in specialty channels.
- Coconut Oil:Lauric acid formulations serve mass-market hydration needs through supermarket distribution.
Aloe Vera commands the volume base; Tea Tree Oil generates the steepest expansion trajectory.
End User:
Customer type fragmentation splits between individual consumption patterns and institutional procurement contracts with divergent certification requirements.
- Salons:Institutional sulfate-free contracts bundle diagnostic training with volume commitments, consolidating procurement through direct-manufacturer relationships. Dubai's Jumeirah salon cluster demands exclusive botanical line partnerships for premium positioning. SFDA tightening accelerates this segment's expansion.
- Women:Individual purchasers drive moisturizing variant volume through supermarket and online retail channels.
- Men:Mineral oil avoidance trends concentrate demand in hair growth formulations through pharmacy distribution.
- Children:Gentle formulation requirements create halal certification compliance priorities for MOHAP-regulated imports.
Women represent the largest addressable base; Salons gain share fastest.
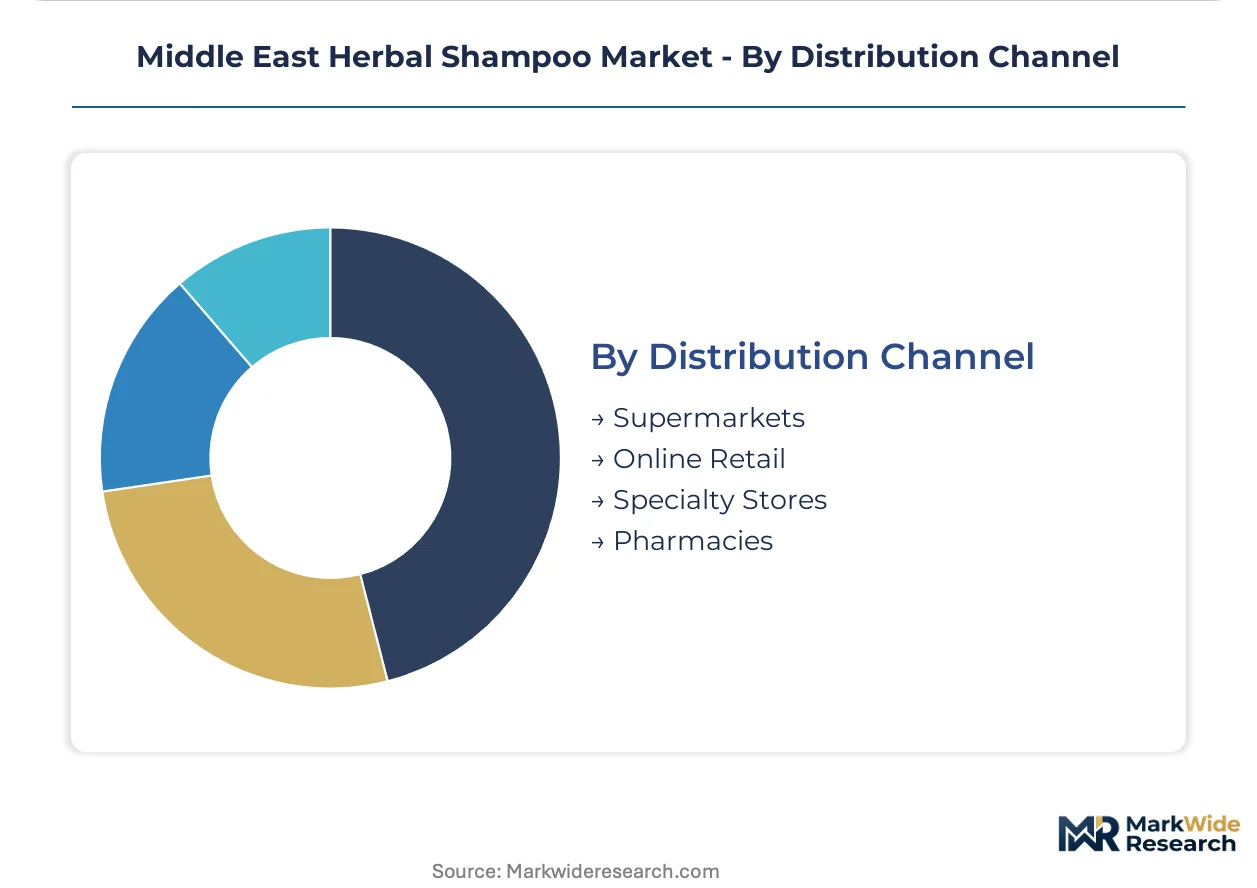
Distribution Channel:
Supply concentration favors direct-manufacturer relationships over traditional distributor networks, with channel compression most visible in premium positioning corridors.
- Specialty Stores:Ayurvedic heritage anchors distribution through beauty retailers in the GCC where diagnostic-service bundling opens margin capture. Dabur and Himalaya sustain shelf space through captive herb cultivation scale advantages.
- Supermarkets:Mass-market volume flows through conventional sulfate-free variants with price-sensitive positioning.
- Online Retail:Direct-to-consumer channels expand reach into North African markets where synthetic surfactant substitution retains price advantage.
- Pharmacies:Anti-dandruff and hair growth SKUs leverage healthcare-adjacent positioning for male demographic targeting.
Specialty Stores retain the highest margin concentration; Online Retail scales most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port in Dubai anchors GCC distribution for herbal shampoo imports, channeling Indian and Egyptian botanical supplies through bonded warehousing before duty-paid release into Saudi and Kuwaiti markets.
Saudi Arabia
Riyadh's salon procurement contracts drive institutional sulfate-free volume as male consumers avoid mineral oil formulations. The country's national pharmaceutical regulator mandates full botanical ingredient traceability for cosmetic registrations, forcing reformulation cycles. Jeddah's industrial corridor hosts cold-process emulsification facilities serving domestic retail chains.
United Arab Emirates
Dubai-Abu Dhabi corridor retail commands premium shelf space for aloe vera polysaccharide moisturizers suited to arid climate conditions. The Ministry of Health and Prevention enforces halal certification compliance across personal care imports, elevating entry barriers. Jumeirah salon clusters demand exclusive botanical line partnerships for positioning.
Kuwait
Specialty beauty retailers in Kuwait City concentrate Ayurvedic heritage brand distribution through diagnostic-service bundling. The country's national standards body aligns with Gulf standardization initiatives for unified labeling requirements. Salmiya district hosts clinic-salon hybrid channels capturing margin through product recommendations.
Bahrain
Manama's traditional distributor networks lose share to direct-manufacturer relationships as institutional procurement consolidates. The country's national pharmaceutical regulator enforces cosmetic ingredient disclosure parallel to Saudi frameworks. Seef Mall retail clusters anchor premium positioning for henna leaf tannin color protect variants.
Qatar
Doha's pharmacy distribution channels target male demographics with hair growth formulations featuring caffeine and saw palmetto. The country's national health authority mandates halal certification for personal care imports through MOHAP-aligned standards. Lusail development corridor attracts specialty store expansion for premium botanical positioning.
Middle East Herbal Shampoo Market Competitive Landscape
Concentration sits with Ayurvedic heritage specialists commanding specialty retail shelf space through captive herb cultivation networks. The competitive structure tiers between multinational consumer goods conglomerates with mass-market sulfate-free lines and mid-scale botanical formulators serving salon institutional contracts. Two strategic archetypes dominate: vertically integrated Ayurvedic laboratories leveraging backward integration into Indian agricultural supply chains, and clinic-salon hybrid operators bundling diagnostic services with product recommendations. Capacity expansion into UAE-based cold-process facilities and direct-manufacturer relationship building with GCC salon chains represent the dominant competitive moves.
Within the heritage Ayurvedic tier, Dabur India Limited and Himalaya Drug Company exemplify scale-driven botanical sourcing advantages, while VLCC Personal Care Ltd. occupies a position bridging clinic-service integration with product distribution. These three anchors demonstrate how Indian-origin formulators leverage multi-year agricultural contracts and diagnostic-channel bundling to defend positioning against multinational entrants.
| Leading Market Players |
|---|
| Unilever |
| Bio Veda Action Research Co. |
| Dabur India Limited |
| VLCC Personal Care Ltd. |
| Khadi Global |
| Himalaya Drug Company |
| Patanjali Ayurved Limited |
| Emami Limited |
| Procter & Gamble |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day botanical ingredient lead times from Indian and Egyptian growers compress margin flexibility for UAE-based cold-process manufacturers, concentrating pricing power with vertically integrated Ayurvedic suppliers while forcing spot-market dependent formulators into defensive discounting.
Pricing Analysis
Volume-discount tiering structures separate institutional salon contracts from individual retail purchases across the Middle East herbal shampoo market. Three-tier pricing stratification across premium sulfate-free salon lines, standard Ayurvedic heritage SKUs, and economy coconut-oil mass variants reflects halal certification grade and captive herb cultivation scale. Pricing pressure intensifies in supermarket channels as synthetic surfactant substitutes retain cost advantage among North African price-sensitive buyers. Salon professionals demonstrate lowest price sensitivity due to diagnostic-service bundling, while online retail consumers exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Jebel Ali Port fluctuate with container availability on India-UAE and Egypt-UAE trade lanes, compressing working capital cycles for cold-process emulsification facilities. Raw material sourcing concentrates in India for aloe vera polysaccharides and Ayurvedic actives, Egypt for henna leaf tannins, and Indonesia for coconut oil derivatives. Supply chain risk centers on single-source vulnerability for supercritical CO2 extraction equipment concentrated in German and Italian manufacturing hubs. Distribution runs through bonded warehousing at Jebel Ali before duty-paid release into Saudi and Kuwaiti retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
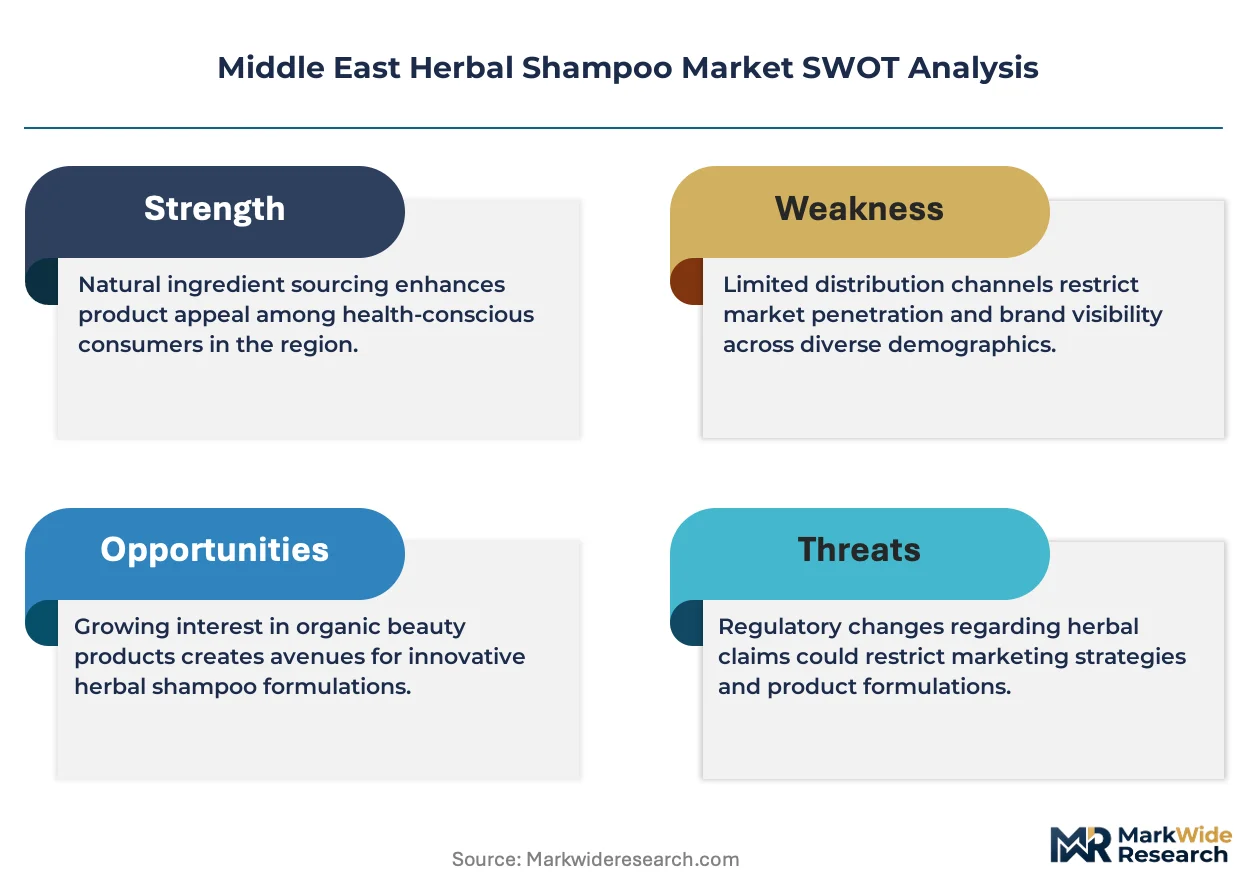
The Middle East herbal shampoo market sits in early-cycle expansion as SFDA disclosure mandates and halal certification requirements accelerate institutional procurement shifts toward transparent botanical formulations.
For Market Incumbents: Consolidate procurement relationships with GCC salon chains through exclusive sulfate-free line partnerships that bundle diagnostic training. Deepen backward integration into captive herb cultivation networks across Indian agricultural corridors to defend margin position against spot-market volatility. Lock in multi-year supply contracts before SFDA traceability documentation requirements elevate new entrant barriers further.
For New Entrants and Emerging Players: Differentiate on male-targeted hair growth formulations featuring caffeine and saw palmetto actives, where mineral oil avoidance trends create whitespace in pharmacy distribution channels. Target Qatar and Bahrain clinic-salon hybrid segments where diagnostic-service bundling remains underdeveloped relative to Dubai-Abu Dhabi corridor saturation. Pursue direct-manufacturer relationships bypassing traditional Kuwaiti distributor networks to capture institutional contract flow.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-process emulsification capacity expansion as supercritical CO2 extraction technology demands specialized equipment investment. The five-to-ten year viability window favors acquisition targets with existing SFDA registration portfolios and captive agricultural supply chains rather than formulation-only players. Watch for Gulf standardization initiative announcements signaling unified GCC labeling requirements as inflection indicator for multi-country distribution scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Process Capacity Expansion | UAE-based facilities capture shelf space from heat-degraded competitors through bioactive integrity preservation. |
| Captive Herb Cultivation Contracts | Multi-year agricultural agreements with Indian and Egyptian growers lock in supply security for SFDA compliance. |
| Clinic-Salon Hybrid Channel Development | Diagnostic-service bundling in Dubai-Abu Dhabi corridor opens margin capture through product recommendation integration. |
| Halal Certification Investment | MOHAP-aligned compliance documentation streamlines UAE import access and accelerates product launch timelines. |
| Direct-Manufacturer Relationship Building | Bypassing traditional Kuwait and Bahrain distributor networks captures institutional procurement consolidation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with salon procurement managers, Ayurvedic brand category heads, UAE-based cold-process facility chemists, and GCC regulatory affairs specialists. Secondary validation drew from SFDA cosmetic registration filings, MOHAP halal certification databases, Jebel Ali Port customs records, and Indian agricultural export statistics. Bottom-up volume triangulation across product type, ingredient category, and distribution channel segments was cross-checked against top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, ingredient concentration technology, end-user procurement pattern, and country-level regulatory cluster. CAGRs were derived from regression analysis of historical volume flows projected through adoption curve modeling for sulfate-free institutional contracts. Industry-specific inputs included salon professional training program expansion rates and supercritical CO2 extraction technology penetration curves in UAE manufacturing facilities.
The analysis sits within stated boundaries; outcomes outside sustained SFDA enforcement intensity, stable India-UAE botanical trade flows, or continued Gulf halal certification alignment would require recalibration. Forecasts reflect documented assumptions around institutional procurement shift velocity and cold-process technical talent availability. Specific risks that could revise projections include unified GCC labeling requirement delays, Egyptian henna harvest volatility, or synthetic surfactant price collapse in North African markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
Hair Salon Equipment Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Hair Removal Wax Market