
 Natural Cosmetics Market | 2026-2036
Natural Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cosmetics Market Outlook
Biotechnology-derived actives is narrowing the performance gap between synthetic and plant-based formulations. L'Oreal SA leverages its integrated green chemistry pipeline to secure botanical supply chains. Estée Lauder Companies Inc. anchors its premium positioning through controlled distribution in specialty retail. Herbivore Botanicals differentiates via minimalist ingredient transparency and direct-to-consumer channel control.
Natural cosmetics comprise personal care products formulated with plant-derived, mineral, or organically certified ingredients, typically excluding synthetic fragrances, parabens, and petroleum-based compounds, manufactured through cold-press extraction, fermentation, or supercritical CO2 processing to preserve bioactive integrity. These products serve consumers seeking reduced dermal exposure to petrochemicals while maintaining functional efficacy in cleansing, moisturizing, and protection applications. Skincare commands the dominant value share as consumers prioritize serum and facial oil investments over color cosmetics. The botanical ingredient segment leads volume throughput, though organic-certified inputs capture disproportionate margin pools due to supply scarcity and certification costs. Online distribution is accelerating fastest among channels, yet specialty stores retain higher conversion rates for premium natural fragrance and professional-grade haircare.
The EU Green Deal and REACH frameworks mandate ingredient disclosure and restrict certain synthetic preservatives, compelling reformulation investments across export-oriented manufacturers. The FDA maintains less prescriptive cosmetic regulations than pharmaceutical oversight, creating a bifurcated compliance landscape where brands self-certify "natural" claims without standardized federal definition. South Korea's MFDS and China's SAMR impose distinct registration requirements for imported natural products, fragmenting market access protocols. Stakeholders must monitor evolving certification standards and supply chain traceability mandates to anticipate which ingredient categories face restriction or premium positioning.
Market Dynamics
Biotechnology-derived actives and precision fermentation are compressing the efficacy gap between synthetic and botanical formulations, forcing incumbent manufacturers to restructure R&D pipelines and ingredient sourcing strategies.
Growth Catalysts
- EU Green Deal chemical mandates:REACH framework restrictions on synthetic preservatives compel reformulation investments, expanding addressable market for clean-label alternatives.
- Millennial and Gen Z salon professionals:This demographic segment accelerates clean beauty adoption through professional channel endorsement and social media amplification.
- Supercritical CO2 extraction:Advanced processing technology preserves bioactive integrity in botanical actives, enabling premium positioning for facial oils and serums.
Market Restraints
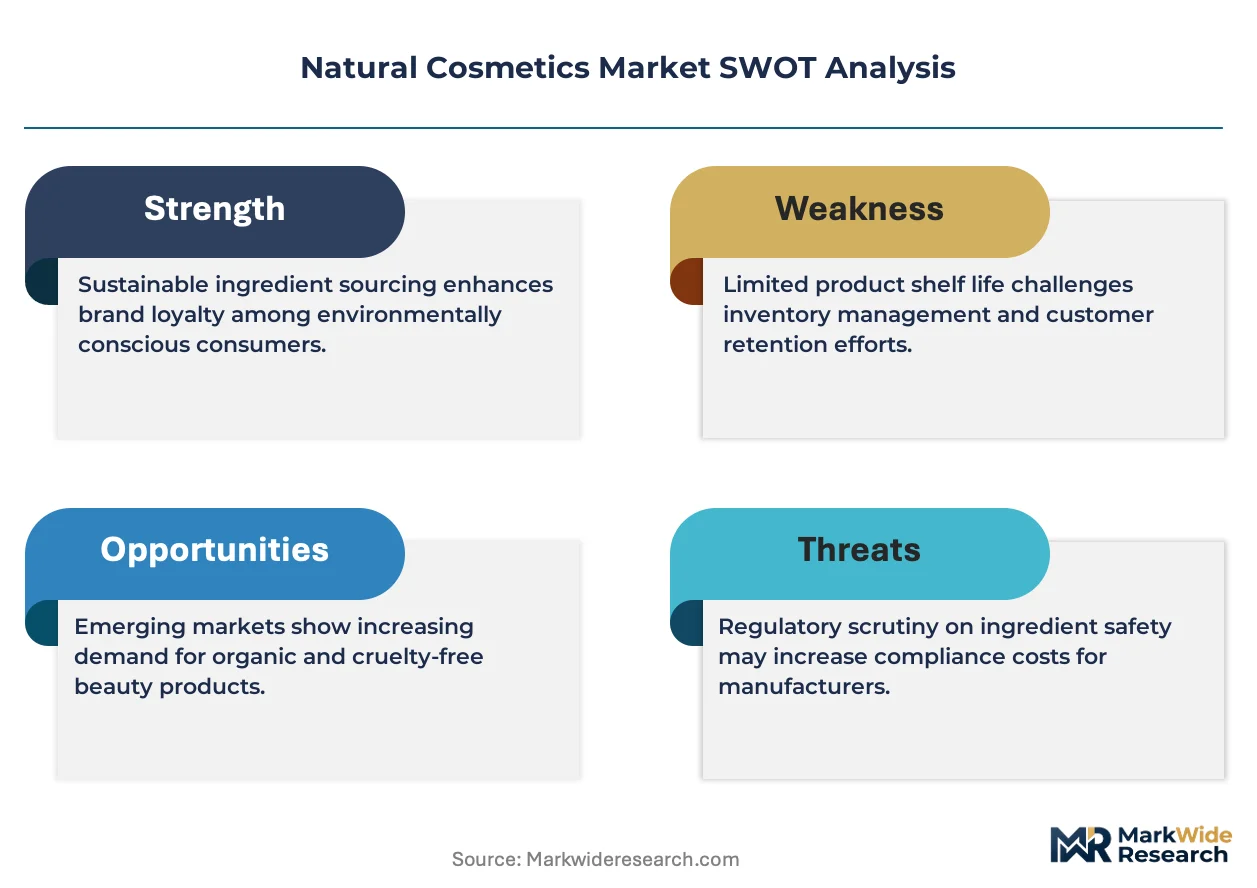
- Organic-certified input scarcity:Supply bottlenecks in certified botanicals inflate raw material costs and compress gross margins for mass-market positioning.
- Fragmented registration protocols:South Korea's MFDS and China's SAMR impose distinct import requirements, lengthening time-to-market for cross-border brands.
- Petrochemical-based preservative substitution limits:Technical constraints in natural preservation systems restrict shelf-life extension and geographic distribution reach.
Strategic Opportunities
- Direct-to-consumer channel control:Vertical integration into owned e-commerce platforms captures margin pools previously allocated to specialty retail intermediaries.
- Fermentation-converged biotechnology:Microbial production of rare botanical actives eliminates agricultural supply risk while standardizing output quality.
- France premium skincare hub:Paris and Lyon cluster concentration offers proximity to formulation talent and luxury retail gatekeepers.
Industry Challenges
- Green chemistry talent scarcity:Shortage of formulation scientists trained in cold-press and supercritical extraction methods constrains product pipeline velocity.
- Multi-jurisdiction certification timelines:Organic and natural standard harmonization delays across EU, US, and Asian markets fragment compliance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cosmetics Market |
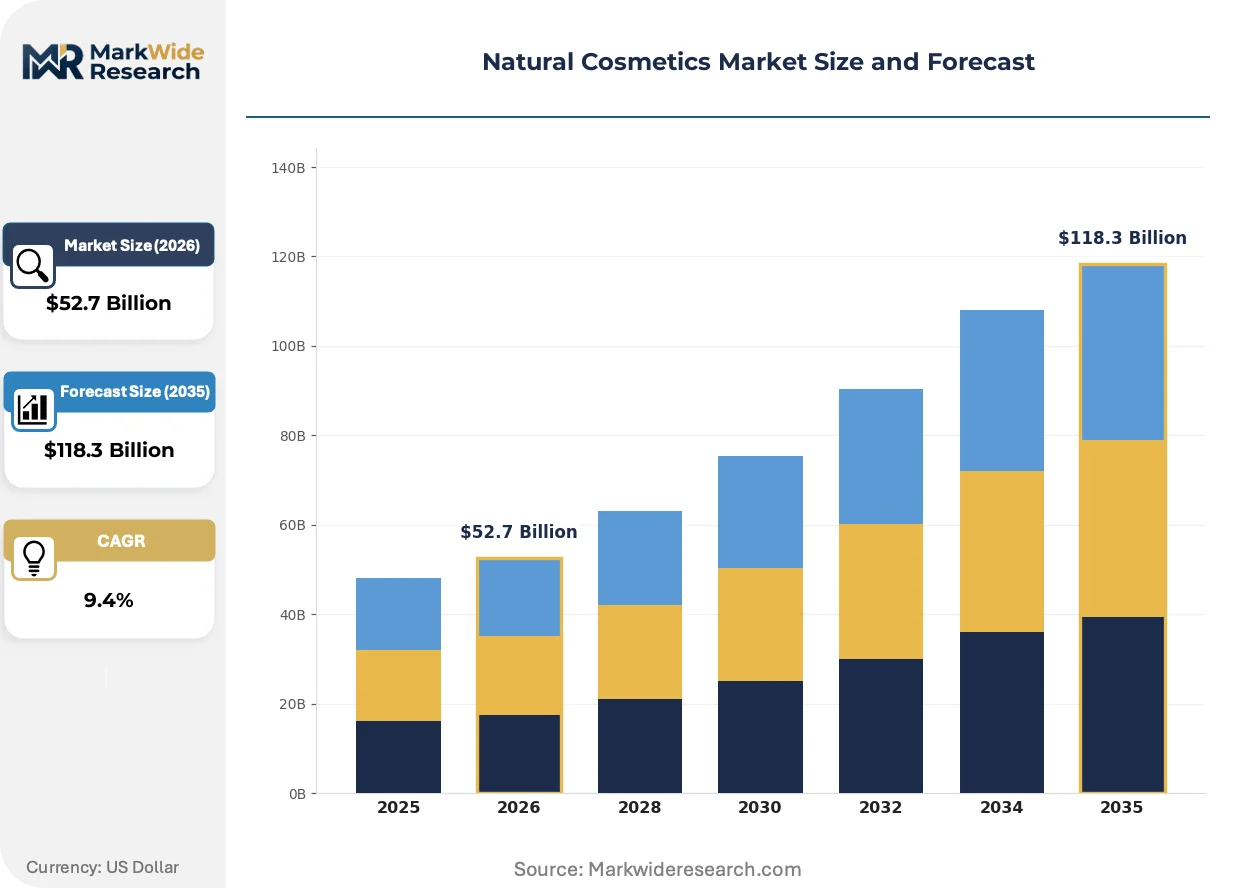
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $118.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Ingredient Source: Botanical, Mineral, Organic, Natural Distribution Channel: Online, Retail Stores, Specialty Stores, Salons End User: Women, Men, Teens, Professionals |
| Companies Covered | Shiseido Co., Ltd., Coty Inc., L'Oreal SA, Herbivore Botanicals, Burt's Bees, Estée Lauder Companies Inc., Johnson & Johnson, Weleda, Procter & Gamble Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cosmetics Market Strategic Shifts
Active ingredient manufacturing is bifurcating between precision biotechnology and artisanal sourcing, with downstream brands forced to signal their technological commitment through transparent supply chain architecture.
Precision fermentation for rare botanical actives is rendering obsolete traditional agricultural cultivation of high-value ingredients like squalane and resveratrol. Premium skincare formulators in France and South Korea are adopting these inputs at accelerated procurement cycles. The structural consequence compresses price premiums previously commanded by limited-harvest botanicals.
REACH authorization requirements for preservative systems are forcing systematic elimination of parabens and formaldehyde-releasing compounds from export-oriented formulations. Manufacturers serving EU markets must validate alternative preservation through extensive stability testing. Color cosmetics and water-based skincare face the steepest compliance cost escalation.
Ingredient transparency platforms are replacing third-party certification as the primary consumer trust mechanism. Direct-to-consumer brands deploy blockchain-anchored supply chain visualization, displacing reliance on organic seals. This behavioral shift concentrates in US and French metropolitan markets where digital-native consumers dominate premium purchasing.
Natural Cosmetics Market Segmentation
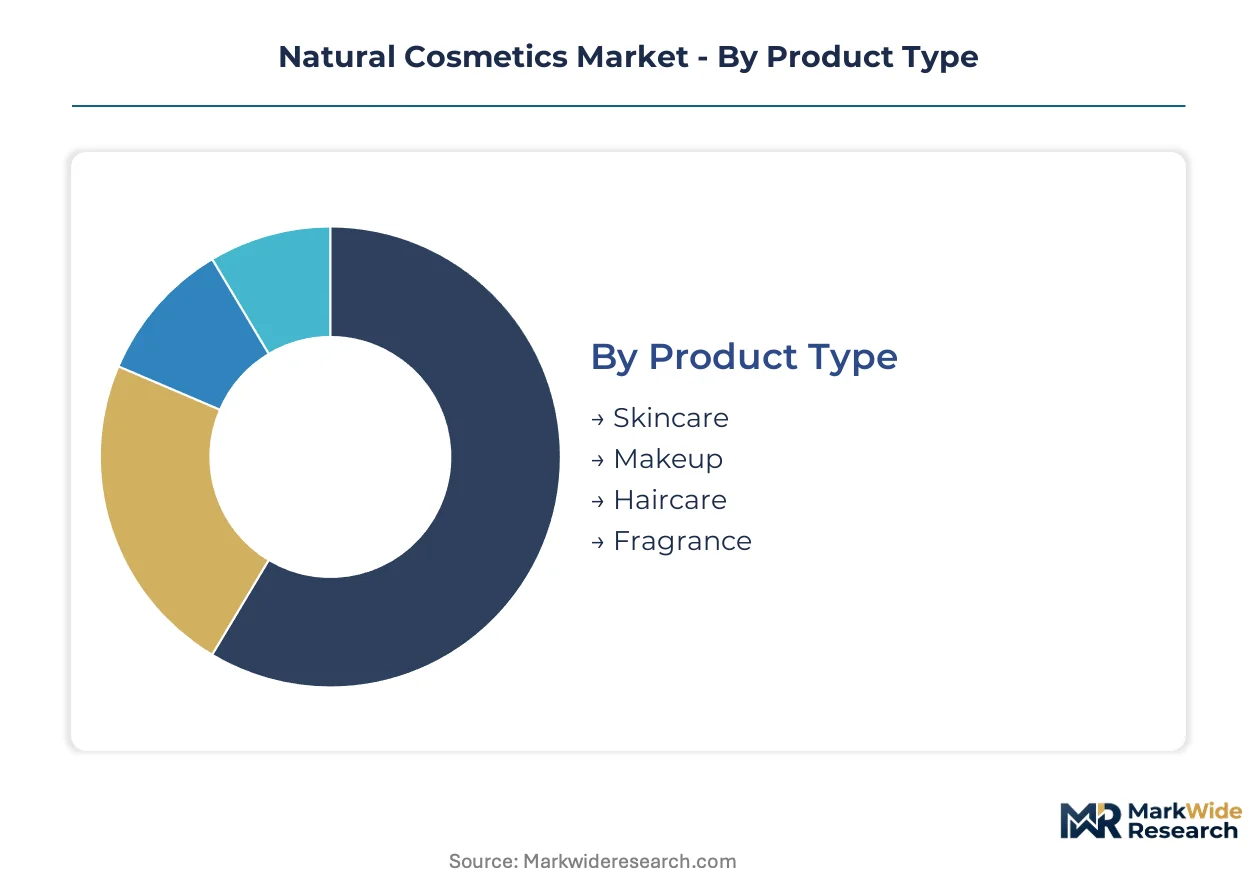
Natural cosmetics segmentation reveals distinct velocity patterns across product categories. Skincare commands premium investment cycles while color cosmetics turn inventory faster. Channel and ingredient stratification determines margin capture and regulatory exposure.
Product Type:
Skincare operates on extended replenishment cycles driven by serum and treatment loyalty, whereas makeup refreshes seasonally with faster inventory velocity.
- Skincare:Facial serums, oils, and moisturizers formulated through cold-press extraction and supercritical CO2 processing command the highest per-unit margins. Demand concentrates in France and South Korea where consumers prioritize bioactive integrity over synthetic performance alternatives.
- Makeup:Color cosmetics face compressed formulation timelines due to REACH-mandated preservative substitutions. Professional channel endorsement from Millennial and Gen Z salon artists accelerates clean beauty trial in metropolitan US markets.
- Haircare:Professional-grade natural shampoos and conditioners serve salon distribution with recurring purchase patterns.
- Fragrance:Natural perfume oils and alcohol-free formulations target specialty retail with limited-batch production constraints.
Skincare dominates installed base. Makeup is where expansion concentrates.
Ingredient Source:
Certification tier drives procurement cost structure and supply security exposure.
- Organic:Certified botanical inputs carry scarcity premiums due to agricultural yield constraints and multi-year soil conversion requirements. France and South Korea import markets absorb disproportionate margin inflation for certified supply.
- Botanical:Plant-derived actives from conventional cultivation feed mass-market positioning with standardized quality protocols. Precision fermentation is displacing agricultural sourcing for rare compounds like squalane.
- Mineral:Zinc oxide and iron oxide pigments serve color cosmetics with established safety profiles under FDA and REACH oversight.
- Natural:Uncertified plant and mineral blends occupy entry-price positioning with self-verified claims.
Organic commands price premiums. Botanical is climbing the fastest.
Distribution Channel:
Channel selection determines margin retention and consumer education burden.
- Online:Direct-to-consumer platforms enable blockchain-anchored transparency and subscription replenishment models. US and French metropolitan consumers drive premium conversion through digital-native discovery.
- Specialty Stores:Curated retail environments sustain higher conversion rates for natural fragrance and professional haircare through tactile sampling.
- Retail Stores:Mass-market shelf placement requires formulation scale and conventional preservation compromises.
- Salons:Professional endorsement channels transmit credibility to consumer home-care purchases with recurring revenue attachment.
Specialty stores anchor premium positioning. Online is gaining share fastest.
End User:
Demographic segmentation aligns product sophistication with purchasing authority and ingredient literacy.
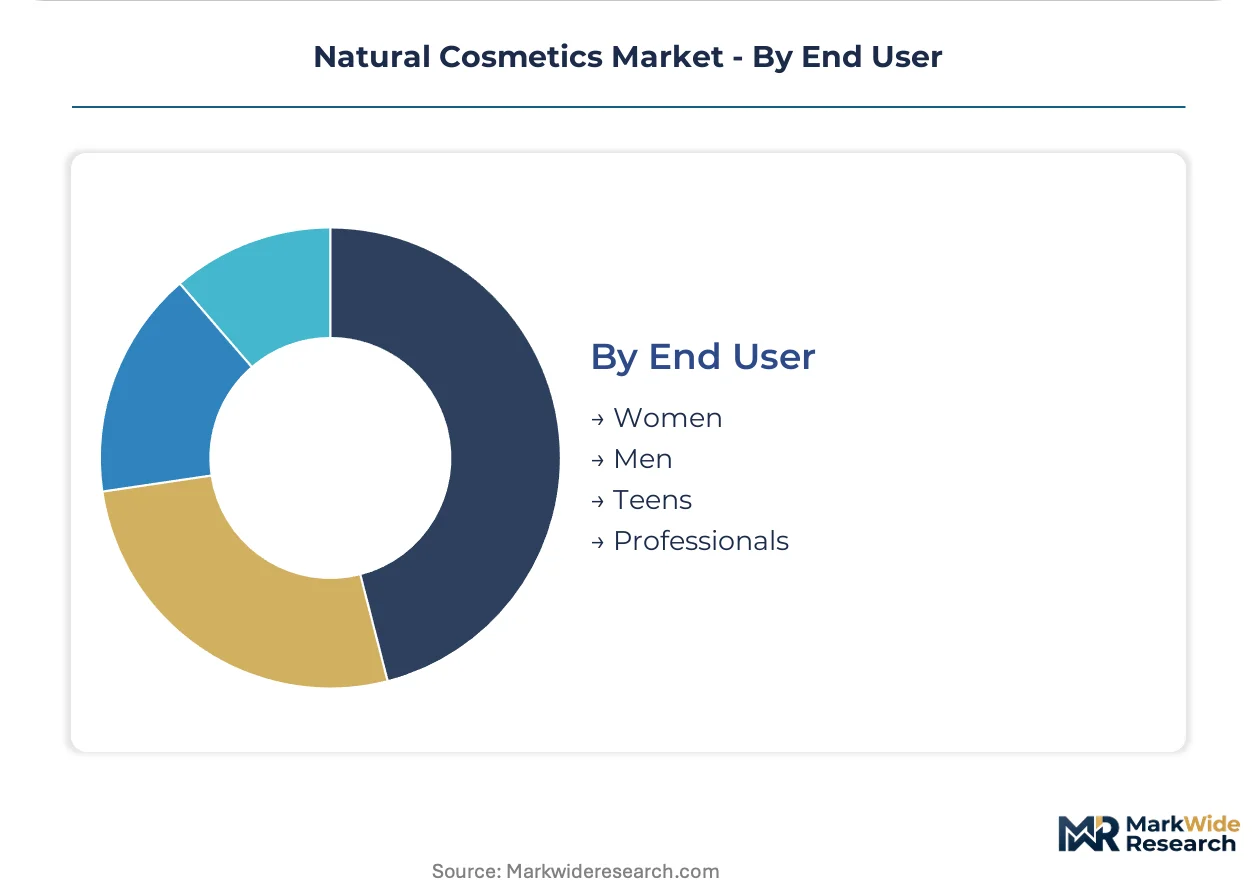
- Women:Core volume purchasers across all product categories with established brand loyalty patterns in skincare.
- Men:Emerging segment concentrated in grooming and skincare basics with simplified routine expectations.
- Teens:Digital-native discovery through social platforms with price sensitivity and trend-driven trial behavior.
- Professionals:Salon and spa practitioners who influence downstream consumer adoption through service integration.
Women represent the largest installed base. Professionals drive category expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports premium natural skincare formulations to South Korea and the United States, establishing the dominant trade-flow corridor in high-margin botanical actives. This triad of demand centers concentrates procurement authority and shapes regulatory compliance investments across export-oriented manufacturers.
France
Paris and Lyon clusters anchor European formulation talent for luxury facial oils and serums. The EU Green Deal's REACH framework mandates systematic elimination of parabens from export-bound products. Grasse perfume houses and Lyon biotech incubators converge on fermentation-derived rare actives.
South Korea
Seoul Capital Area consumers prioritize bioactive integrity in serum investments over synthetic alternatives. The MFDS imposes distinct registration requirements for imported natural products that fragment cross-border brand entry. Busan-Ulsan manufacturing corridors integrate precision fermentation for squalane production.
United States
Metropolitan digital-native consumers drive premium conversion through blockchain-anchored supply chain transparency. The FDA maintains less prescriptive cosmetic regulations than pharmaceutical oversight, enabling self-certified "natural" claims without standardized federal definition. Greater Boston and Pacific Northwest clusters concentrate clean beauty venture formation.
Germany
Baden-Württemberg and Bavaria host precision engineering suppliers for supercritical CO2 extraction equipment. ECHA authorization timelines for alternative preservative systems extend reformulation cycles for color cosmetics. Hamburg trading houses coordinate organic-certified botanical imports from Mediterranean suppliers.
Japan
Kanto region consumers demonstrate established loyalty patterns in extended replenishment skincare routines. METI standards for quasi-drug classification create distinct compliance pathways for functional natural products. Osaka-Kobe manufacturing bases specialize in cold-press extraction methods for sensitive-skin formulations.
Natural Cosmetics Market Competitive Environment
On the supply side, the industry is bifurcating between integrated multinational pipelines and agile direct-to-consumer specialists. Consolidation pressure concentrates among mid-scale brands lacking captive biotechnology capabilities. Two strategic archetypes dominate: fermentation-converged biotechnology adopters and transparency-platform direct-to-consumer operators. Capacity expansion in precision fermentation and strategic partnerships for supply chain traceability represent the dominant competitive moves.
Among integrated multinationals, L'Oreal SA and Estée Lauder Companies Inc. exemplify archetypes of green chemistry pipeline control and premium distribution gatekeeping respectively. Herbivore Botanicals occupies a position within the specialist tier representing minimalist transparency and channel ownership. These three anchors illustrate the structural tension between scale-driven biotechnology investment and agility-focused consumer proximity.
| Leading Market Players |
|---|
| Shiseido Co., Ltd. |
| Coty Inc. |
| L'Oreal SA |
| Herbivore Botanicals |
| Burt's Bees |
| Estée Lauder Companies Inc. |
| Johnson & Johnson |
| Weleda |
| Procter & Gamble Co. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Grasse freight corridor carries cold-pressed botanical oils and supercritical CO2 extracts from Mediterranean cultivation zones to French formulation clusters, with freight cost volatility transmitting directly into premium serum pricing while compressing margins for mass-market brands dependent on organic-certified inputs.
Pricing Analysis
Prior-generation cold-press extraction methods command commodity pricing for conventional botanicals, current-generation supercritical CO2 processing sustains mid-tier premiums for bioactive preservation, and next-generation precision fermentation inputs are collapsing scarcity premiums for rare actives like squalane. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and extraction technology. Pricing pressure stems from organic-certified input scarcity inflating raw material costs. Mass-market positioning faces acute price sensitivity; luxury serum segments absorb cost pass-through with minimal volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Lyon-based biotech incubators and Busan-Ulsan fermentation corridors, with Grasse perfume houses retaining artisanal capacity for limited-batch natural fragrances. Geographic supply concentration centers on France, South Korea, and the United States for formulation and biotechnology production. Raw material dependencies draw from Mediterranean botanical cultivation zones, Australian sandalwood plantations, and Brazilian açaí harvests. Single-source vulnerability in organic-certified agricultural supply creates exposure to climate-driven yield volatility. Distribution runs through direct-to-consumer platforms for premium skincare, specialty retail for fragrance, and professional salon channels for haircare.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation scientists trained in green chemistry extraction methods represent the critical capability gap constraining product pipeline velocity, with incumbent R&D teams and emerging biotech specialists competing for limited talent pools.
For Market Incumbents: Pre-empt biotechnology talent poaching by anchoring fermentation-converged R&D capabilities in Lyon and Busan clusters before precision fermentation commoditizes rare botanical actives. Incumbents must defend margin position through backward integration into captive supercritical CO2 extraction capacity, insulating against organic input scarcity while accelerating reformulation timelines for REACH-compliant preservative systems. For New Entrants and Emerging Players: German precision-engineering corridors for extraction equipment represent underpenetrated white-space for clean beauty manufacturing partnerships. New entrants should target professional salon distribution in metropolitan US markets where Millennial and Gen Z practitioners accelerate clean beauty trial through service integration. Direct-to-consumer launch with blockchain-anchored transparency platforms offers the most penetrable go-to-market angle against certification-fatigued consumers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational personal care conglomerates seeking to divest non-core natural brands lacking captive biotechnology pipelines. Long-term viability hinges on distinguishing fermentation-capable assets from artisanal positioning vulnerable to synthetic-bio price compression. Investors should monitor MFDS and SAMR registration clearance timelines as inflection indicators for cross-border brand scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Eliminates agricultural supply risk for squalane and resveratrol while standardizing output quality. |
| Blockchain Supply Chain Transparency | Displaces third-party certification reliance for digital-native consumers in US and French metropolitan markets. |
| REACH-Compliant Preservative Reformulation | Validates alternative preservation systems for EU market access and paraben-free positioning. |
| Professional Salon Channel Expansion | Captures recurring revenue attachment through service-integrated home-care recommendations. |
| Direct-to-Consumer Platform Launch | Captures margin pools previously allocated to specialty retail intermediaries in premium skincare. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, ECHA authorization databases, and retail audit data from metropolitan French and US markets. Interviews with formulation R&D directors, professional salon channel managers, organic certification auditors, and biotech fermentation specialists were combined with bottom-up SKU-level analysis and top-down category value triangulation.
Forecast inputs include supercritical CO2 equipment deployment timelines, precision fermentation capacity buildouts, and REACH authorization progressions across the projection horizon. Segmentation dimensions span product type, ingredient certification tier, distribution channel, and regional regulatory cluster. CAGRs were derived from modeled unit economics and adoption curve penetration rates, with biotechnology substitution velocity and organic supply elasticity as key sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation specialists or EU regulatory accelerators would shift outcomes beyond modeled ranges. Cross-checking against MFDS and SAMR registration clearance databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Gua Sha Tools Market