
 US Personal Care Products Market | 2026-2036
US Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Personal Care Products Market Insights
Direct-to-consumer subscription revenue is reshaping margin distribution across the US personal care landscape. Procter & Gamble (P&G) Company leverages its manufacturing scale to dominate mass-market shelf space. L'Oréal Group anchors its position through R&D intensity in dermatological skincare. Estee Lauder Companies, Inc. specializes in prestige fragrance and makeup, commanding premium price tiers.
US personal care products encompass topical formulations—emulsions, surfactant-based cleansers, and active-ingredient suspensions—manufactured through batch processing with specified pH stability and preservative efficacy parameters, designed for hygiene, appearance enhancement, and skin barrier maintenance. Skincare leads product type value generation, with clinical-grade retinoids and peptide complexes capturing the fastest expansion. Natural and organic ingredient type segments attract margin premiums, though synthetic actives retain volume dominance in mass haircare and antiperspirant applications.
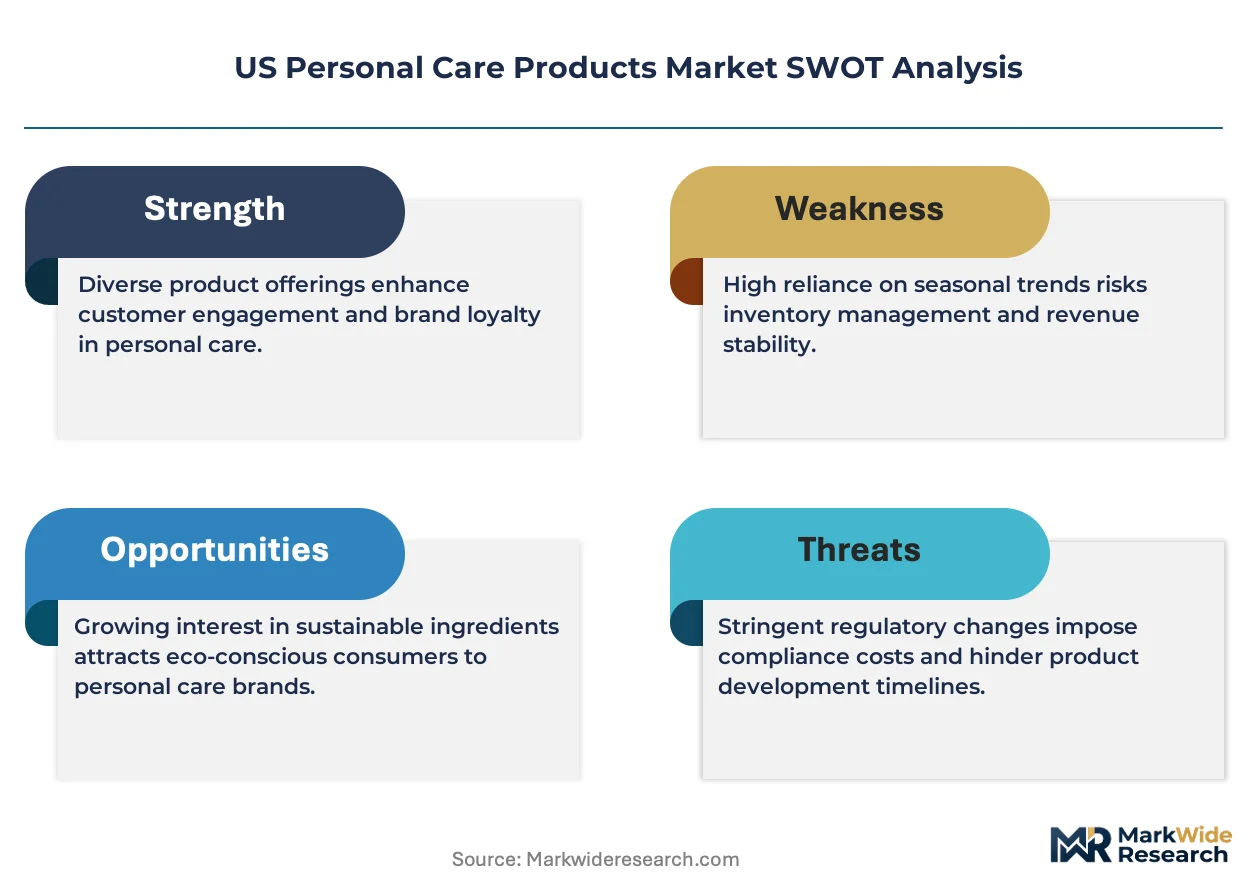
FDA oversight through MoCRA mandates adverse event reporting and good manufacturing practice compliance, elevating compliance costs for smaller entrants. The FTC enforces substantiation standards for clean beauty and anti-aging claims, reshaping marketing language across digital channels. California's Proposition 65 and the state's cosmetic fragrance ingredient disclosure law add layered state-level compliance burdens. Stakeholders must monitor evolving state patchwork regulations alongside federal harmonization efforts to anticipate reformulation and labeling investments.
Market Dynamics
MoCRA's facility registration mandates and adverse event reporting requirements are compressing margins for mid-tier manufacturers while accelerating consolidation among contract manufacturers serving direct-to-consumer brands.
Growth Catalysts
- Clean Beauty Certification:California's cosmetic fragrance ingredient disclosure law drives reformulation investments. Third-party verification programs like EWG Verified and Leaping Bunny attract premium positioning.
- Peptide Complex Innovation:Clinically validated signaling peptides in topical applications command price premiums. Dermatology clinics and medical spas drive professional-grade adoption.
- Subscription Commerce Infrastructure:Replenishment algorithms and personalized regimen curation lock in recurring revenue. Direct-to-consumer brands bypass traditional retail slotting fees.
Market Restraints
- Preservative System Volatility:Natural preservative alternatives exhibit batch-to-batch efficacy variation. Phenoxyethanol and paraben avoidance limits formulation stability windows.
- Active Ingredient Supply Concentration:Retinol and ascorbic acid precursor manufacturing clusters in China. Tariff exposure and shipping disruptions create input cost spikes.
- Biodegradability Performance Gap:Surfactant alternatives to sulfates compromise foaming and sensorial attributes. Mass-market consumers reject texture trade-offs.
Strategic Opportunities
- Men's Grooming Underpenetration:Male-specific skincare and body care categories remain underserved versus women's segments. Barbershop and gym channel partnerships unlock trial.
- Biotechnology-Derived Actives:Lab-grown collagen and fermented postbiotics reduce agricultural supply dependencies. Precision fermentation scales independent of climate volatility.
- Telehealth Integration:Virtual dermatology consultations prescribe clinical-grade regimens. Prescription-strength retinoids and azelaic acid drive pharmacy channel expansion.
Industry Challenges
- Formulation Chemist Scarcity:Cosmetic science programs graduate insufficient talent for clean beauty formulation demands. Emulsion stability expertise with natural emulsifiers commands salary premiums.
- MoCRA Compliance Timeline Compression:Facility registration deadlines and serious adverse event reporting infrastructure require IT system overhauls. Smaller brands lack dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Personal Care Products Market |
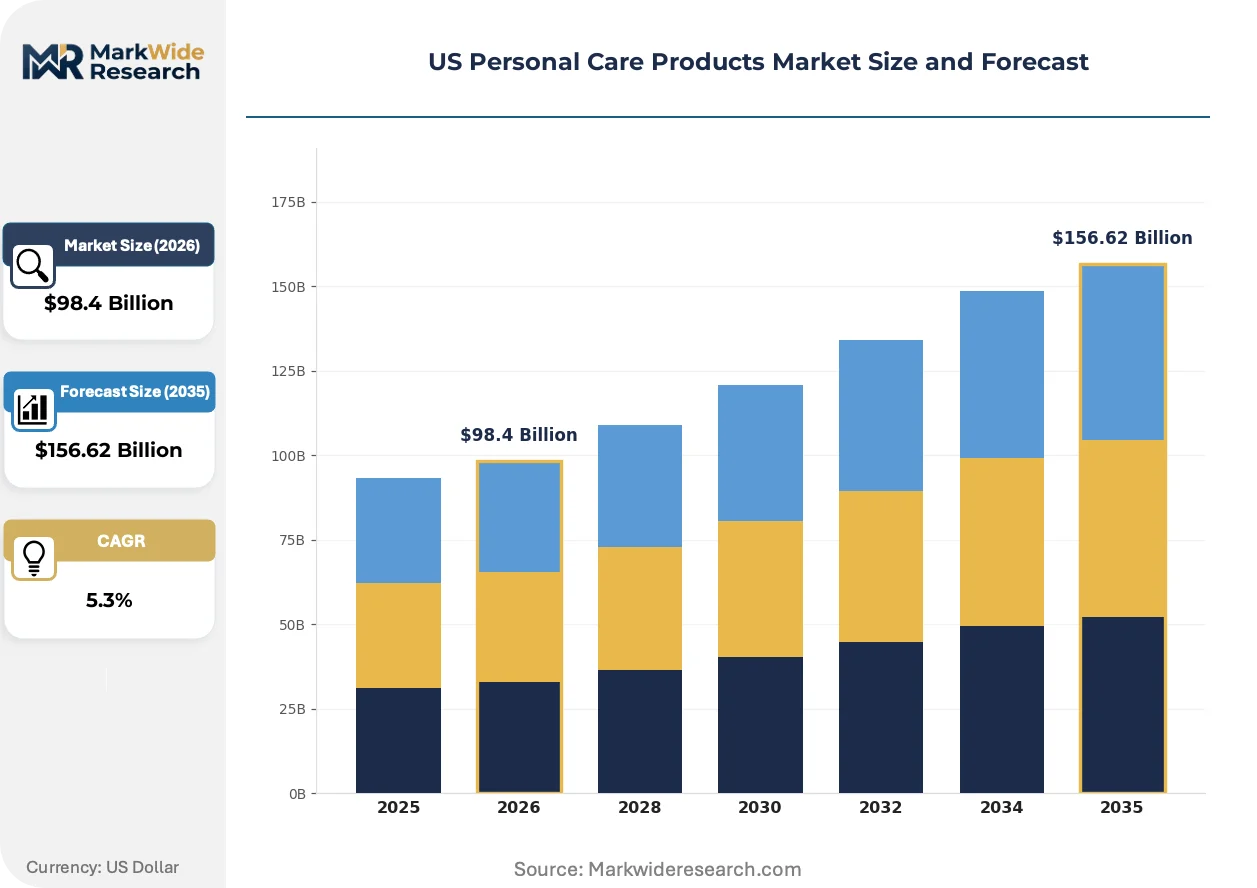
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $156.62 Billion |
| CAGR (2026 – 2036) | 5.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores Customer Type: Men, Women, Teens, Seniors Ingredient Type: Natural, Organic, Synthetic, Biodegradable |
| Companies Covered | Procter & Gamble (P&G) Company, L’Oréal Group, Unilever plc, Estee Lauder Companies, Inc., Coty Inc., Johnson & Johnson, Beiersdorf AG, Henkel AG & Co KGaA, Revlon Consumer Products LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Personal Care Products Market Trends and Innovations
Biotechnology and artificial intelligence are converging to reshape ingredient discovery and personalization engines, compressing development cycles while fragmenting mass-market positioning.
Microbiome-targeted skincare is migrating from niche dermatological applications toward mainstream retail shelves. Brands like Gallinée and Mother Dirt demonstrated efficacy for sensitive skin conditions. Mass-market retailers now allocate shelf space to prebiotic and postbiotic formulations, forcing legacy brands to reformulate or acquire biotech capabilities.
FDA's MoCRA enforcement priorities elevate good manufacturing practice scrutiny for contract manufacturers. The agency's inspection backlog and resource constraints create compliance uncertainty. Small-to-mid-sized brands face facility qualification delays, pushing volume toward established manufacturers with validated quality systems.
Ingredient transparency expectations reshape purchasing behavior across millennial and Gen Z cohorts. QR-code-linked supply chain disclosure replaces static label claims. California and New York consumers demonstrate willingness to pay premiums for batch-level traceability, forcing national brands to adopt uniform disclosure standards rather than state-specific labeling.
US Personal Care Products Market Segmentation
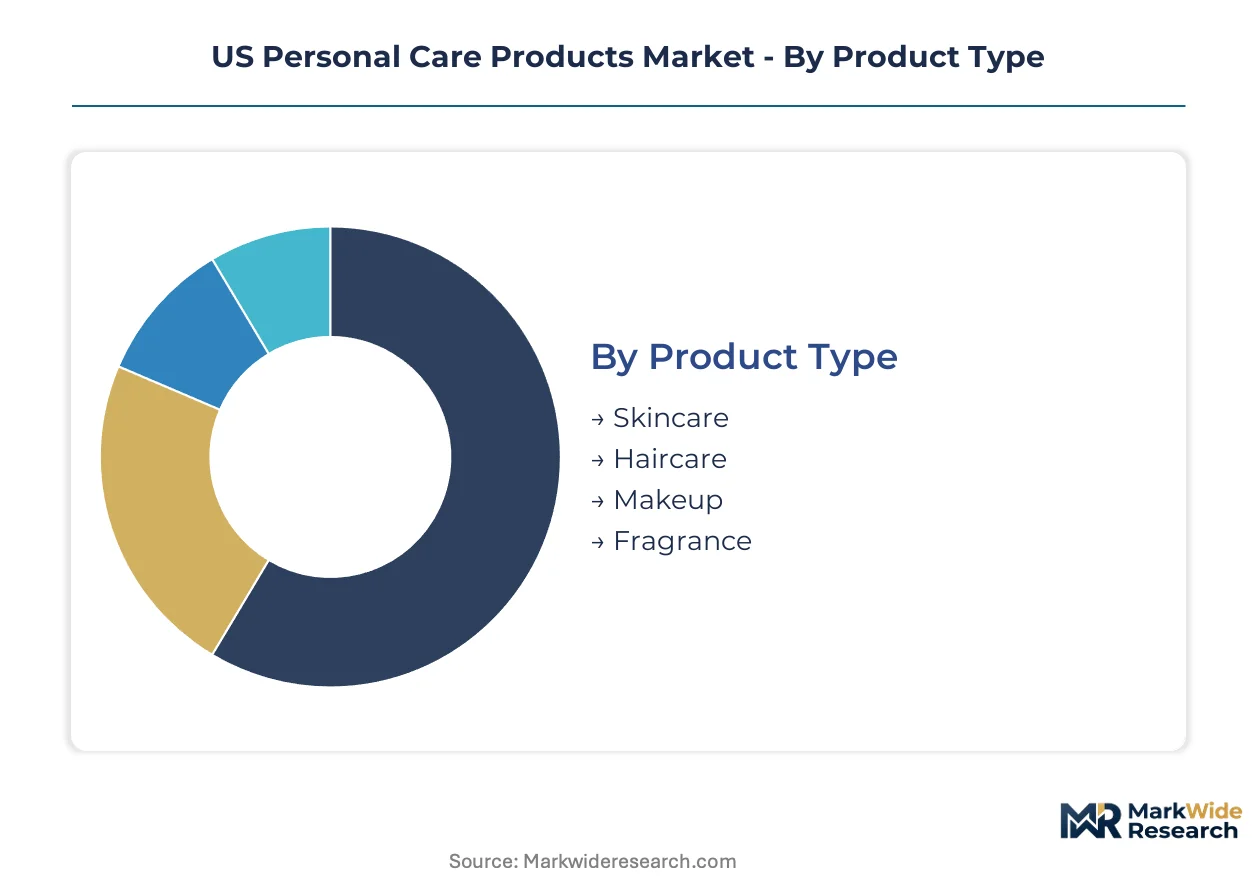
US personal care segmentation reveals distinct margin architectures across product hierarchies. Channel mix and ingredient sourcing strategies determine competitive positioning within each slice.
Product Type:
Cost tier separation drives portfolio architecture across mass, prestige, and clinical-grade offerings.
- Skincare:Emulsion-based formulations with specified pH stability and preservative efficacy parameters command formulation R&D intensity. California and New York consumers concentrate demand for peptide complexes and retinoid suspensions as FDA MoCRA elevates manufacturing compliance costs.
- Haircare:Surfactant-based cleansers and conditioning polymers dominate volume throughput. Sulfate-free alternatives face biodegradability performance gaps that mass-market consumers reject despite sustainability positioning.
- Makeup:Pigment dispersion technology and wear-time claims define competitive differentiation.
- Fragrance:California's cosmetic fragrance ingredient disclosure law forces reformulation transparency investments.
Skincare holds installed capacity. Haircare is rotating up the share rankings.
Distribution Channel:
Volume concentration shifts between physical retail slotting fees and direct-to-consumer subscription infrastructure.
- Online Retail:Replenishment algorithms and personalized regimen curation lock recurring revenue streams. Direct-to-consumer brands bypass traditional supermarket and drugstore slotting fees while capturing millennial and Gen Z trial.
- Supermarkets:Mass-market shelf space concentration rewards manufacturing scale and promotional spend depth. Procter & Gamble leverages batch processing volume to defend position.
- Drugstores:Pharmacy channel expansion accelerates through telehealth-integrated prescription-strength skincare.
- Specialty Stores:Clean beauty retail density concentrates in California and New York metro corridors.
Online Retail captures margin expansion. Specialty Stores are climbing the fastest.
Customer Type:
Application-specific need states fragment product development pipelines across demographic cohorts.
- Women:Prestige fragrance and clinical-grade skincare command premium price tiers with established regimen loyalty.
- Men:Male-specific categories remain underserved versus women's segments. Barbershop and gym channel partnerships unlock trial in body care and facial formulations.
- Teens:Acne-targeted active ingredients and social-native discovery drive purchase behavior.
- Seniors:Barrier maintenance and sensitivity-focused formulations attract reformulation investment.
Women anchor revenue concentration. Men represent the steepest expansion trajectory.
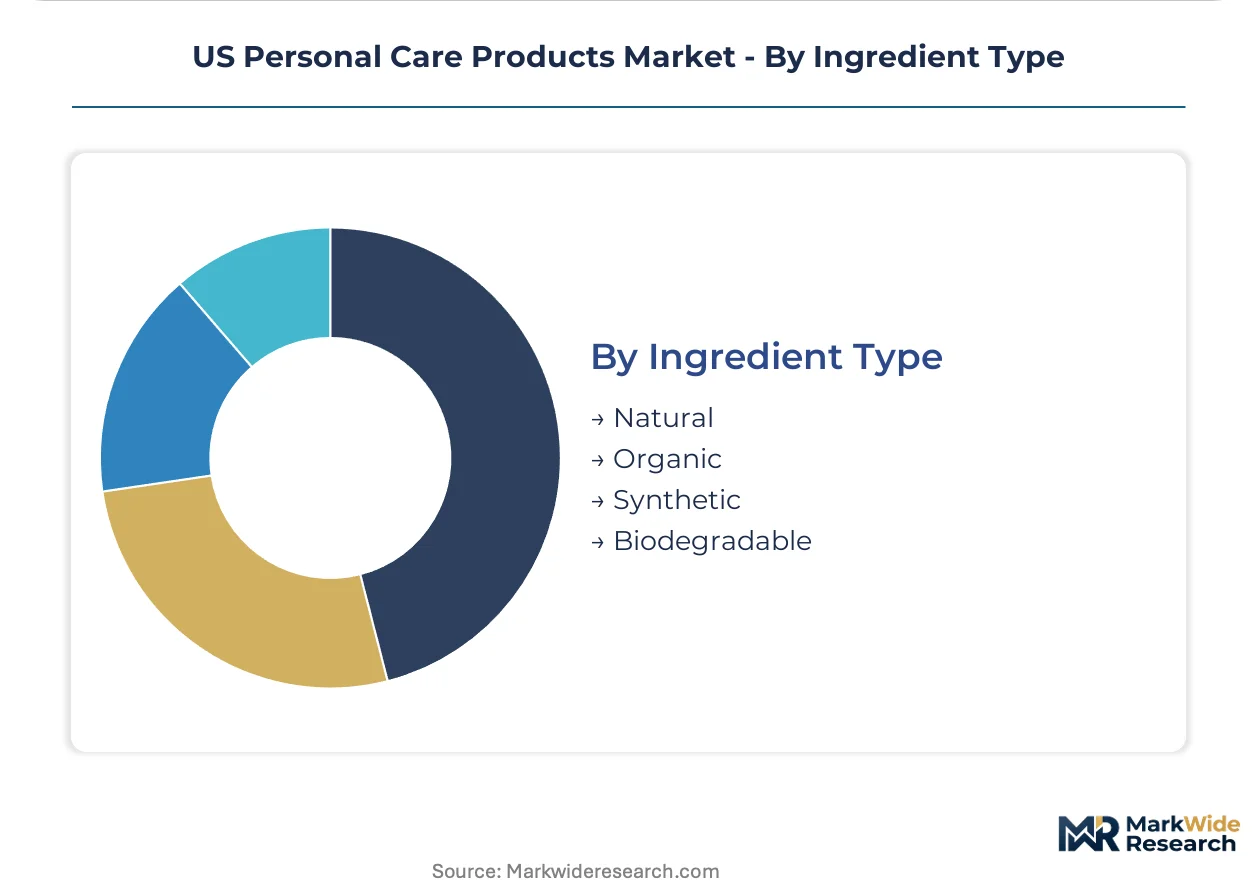
Ingredient Type:
Margin premiums attach to certification grade while synthetic actives retain volume dominance.
- Natural:Plant-derived emulsifiers and preservative alternatives exhibit batch-to-batch efficacy variation. EWG Verified and Leaping Bunny certification programs attract premium positioning in California markets.
- Organic:Agricultural supply dependencies create input cost volatility relative to synthetic alternatives.
- Synthetic:Retinol and ascorbic acid precursor manufacturing concentrates in China, exposing tariff and shipping disruption risk.
- Biodegradable:Surfactant alternatives compromise foaming and sensorial attributes that mass-market consumers reject.
Synthetic retains volume leadership. Natural is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing for personal care formulations clusters in the Midwest and Southeast, where batch processing infrastructure and FDA-registered facilities concentrate capacity. State-level disclosure mandates in California and New York fragment labeling requirements, forcing national brands toward uniform compliance investments.
California
Clean beauty retail density peaks in Los Angeles and San Francisco metro corridors, where millennial and Gen Z consumers drive peptide complex and retinoid suspension demand. Proposition 65 and the state's cosmetic fragrance ingredient disclosure law impose layered compliance burdens exceeding federal MoCRA requirements. Biotech-derived active ingredient startups cluster in South San Francisco and San Diego, leveraging proximity to venture capital and precision fermentation infrastructure.
New York
Prestige fragrance and clinical-grade skincare command premium price tiers in Manhattan and Brooklyn direct-to-consumer channels. The state's environmental conservation law adds packaging waste regulations atop federal FTC substantiation standards. Specialty retailers in SoHo and Williamsburg anchor discovery-driven trial for microbiome-targeted and EWG Verified formulations.
Texas
Mass-market haircare and antiperspirant manufacturing scales through Dallas-Fort Worth and Houston batch processing hubs. OSHA workplace chemical exposure standards intersect with FDA MoCRA facility registration mandates for regional contract manufacturers. Distribution infrastructure radiates from Houston's port complex to Latin American export markets.
Illinois
Chicago anchors Midwest supply chain coordination for surfactant-based cleansers and conditioning polymers. The state's environmental protection agency enforces industrial discharge standards affecting preservative system wastewater management. R&D partnerships between University of Illinois polymer science programs and regional formulators accelerate natural emulsifier stability research.
Florida
Senior-focused barrier maintenance formulations concentrate demand in Miami and Tampa retirement corridors. The state's department of agriculture regulates organic ingredient claims under USDA National Organic Program alignment. Telehealth-integrated prescription-strength skincare pilots operate through Jacksonville and Orlando health system partnerships.
US Personal Care Products Market Competitive Landscape
Conglomerate-scale manufacturers and direct-to-consumer specialists split the market across mass, prestige, and clinical-grade tiers. Mass-market shelf space rewards batch processing volume and promotional spend depth, while subscription commerce infrastructure favors algorithm-driven replenishment and personalized regimen curation. Strategic archetypes include manufacturing-scale defenders, R&D-intensive dermatological anchors, and digital-native challengers bypassing retail slotting fees. Competitive moves concentrate on MoCRA compliance infrastructure acquisition and biotechnology-derived active ingredient pipeline licensing.
Among conglomerate-scale manufacturers, Procter & Gamble Company and L'Oréal Group occupy positions reflecting divergent strategic emphases. Procter & Gamble exemplifies manufacturing-scale defense through batch processing volume concentration. L'Oréal represents R&D intensity in dermatological skincare formulation. Estee Lauder Companies, Inc. anchors prestige fragrance and makeup positioning. Direct-to-consumer challengers sit outside this tier, leveraging subscription infrastructure to capture millennial and Gen Z trial without traditional retail slotting fee burdens.
| Leading Market Players |
|---|
| Procter & Gamble (P&G) Company |
| L'Oréal Group |
| Unilever plc |
| Estee Lauder Companies, Inc. |
| Coty Inc. |
| Johnson & Johnson |
| Beiersdorf AG |
| Henkel AG & Co KGaA |
| Revlon Consumer Products LLC |
| Others |
Pricing and Supply Chain Analysis
Los Angeles-Long Beach port corridor freight volatility compresses margin buffers for peptide complex and retinoid suspension importers, concentrating pricing power among domestic batch processors with validated FDA MoCRA facilities while forcing direct-to-consumer brands toward subscription bundling to offset landed cost spikes.
Pricing Analysis
Subscription renewal revenue streams anchor lifetime value capture for direct-to-consumer personal care brands. Three-tier pricing structure across premium peptide complexes, standard emulsion formulations, and economy surfactant cleansers stratifies margin profiles. Pricing pressure stems from China-origin retinol precursor tariff exposure and shipping disruption surcharges. Mass-market supermarket consumers exhibit highest price sensitivity, while clinical-grade dermatology clinic channels tolerate premium positioning.
Supply Chain Analysis
Upstream surfactant and emulsifier feedstock manufacturing clusters in China, Germany, and India, with active ingredient precursor synthesis concentrating in Chinese chemical parks. Retinol, ascorbic acid precursors, and peptide raw materials draw from these hubs, exposing formulators to single-source vulnerability for high-purity inputs. Distribution runs through Midwest and Southeast contract manufacturing facilities to California and New York retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment and personalized regimen curation services expand faster than hardware product sales, converting transactional personal care purchases into recurring revenue architectures with superior retention economics.
For Market Incumbents: Entrench manufacturing-scale advantages through backward integration into precision fermentation capacity for lab-grown collagen and postbiotics, insulating against agricultural supply volatility while accelerating MoCRA compliance infrastructure acquisition to compress mid-tier competitor margins. For New Entrants and Emerging Players: Build out barbershop and gym channel partnerships for male-specific skincare and body care white space, leveraging trial-sized formats and social-native discovery to bypass supermarket slotting fee barriers before scaling to direct-to-consumer subscription infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate personal care divisions with underutilized FDA-registered facilities and dormant peptide formulation pipelines; long-term viability hinges on biotechnology-derived active ingredient licensing momentum and telehealth integration capabilities, with prescription-strength azelaic acid pharmacy channel expansion serving as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MoCRA Compliance Infrastructure Acquisition | Facility registration and adverse event reporting systems accelerate consolidation among mid-tier contract manufacturers serving direct-to-consumer brands. |
| Precision Fermentation Scale-Up | Lab-grown collagen and fermented postbiotics reduce agricultural supply dependencies while commanding EWG Verified certification premiums. |
| Telehealth Platform Integration | Virtual dermatology consultations channel prescription-strength retinoids and azelaic acid through pharmacy partnerships. |
| Men's Grooming Channel Expansion | Barbershop and gym partnerships unlock trial in underserved male-specific skincare and body care categories. |
| Biotechnology Pipeline Licensing | Signaling peptide and microbiome-targeted formulation IP acquisitions accelerate clinical-grade positioning against legacy mass-market competitors. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulation chemists, direct-to-consumer brand founders, contract manufacturing operations directors, and FDA regulatory affairs specialists, and refined through secondary validation across FDA MoCRA facility registration databases, California Proposition 65 enforcement records, and Nielsen retail audit data for clean beauty channel performance, with bottom-up volume modeling triangulated against top-down market sizing.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, ingredient certification grade, distribution channel, and customer demographic cohort, with CAGRs derived from historical growth rate pattern analysis and adjusted for MoCRA compliance cost absorption and subscription commerce penetration trajectories in millennial and Gen Z cohorts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biotechnology-derived active ingredient specialists or telehealth-integrated prescription skincare platforms would shift outcomes beyond modeled ranges. Cross-checking against Circana retail velocity benchmarks and FDA adverse event reporting volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Europe Hair Styling Products Market