
 Body Mist Market | 2026-2036
Body Mist Market Size, Share, and Industry Trends Forecast 2026-2036
Body Mist Market Analysis
A capital-intensity divergence between mass-market and prestige players is reorganizing competitive dynamics in body mist manufacturing. Coty Inc. leverages its fragrance-forward supply chain to dominate premium scent portfolios, while Unilever anchors mass-market volume through supermarket and drugstore channel control. Kao Corporation differentiates via water-based formulation expertise across Asian markets.
Body mist denotes a low-concentration fragrance product, typically containing two to five percent aromatic compounds suspended in an alcohol, water, or oil carrier, designed for lighter, more frequent application than eau de parfum. The category serves both functional hydration and scent-layering purposes in daily personal care routines. Fragrance infusion leads product type revenue due to established brand loyalty, while hydrating mist posts the fastest structural expansion as consumers prioritize skin-beneficial claims. Online retail captures growing share among teenagers, though specialty stores sustain margin pools through experiential sampling and gift-set bundling.
REACH governs chemical safety and allergen labeling for body mists sold across Europe, directly raising reformulation costs for fragrance houses. The FDA oversees cosmetic labeling and ingredient safety in the United States, while the EPA regulates volatile organic compound emissions from aerosolized delivery systems. Stakeholders must monitor evolving clean-beauty certification standards and decide whether to absorb compliance costs or reformulate around restricted fragrance molecules.
Market Dynamics
REACH allergen disclosure mandates in Europe are forcing simultaneous reformulation across fragrance portfolios, compressing R&D timelines while elevating compliance costs for mid-tier manufacturers without captive regulatory teams.
Growth Catalysts
- EU REACH Framework:Tightened allergen labeling rules create first-mover advantages for brands with pre-positioned clean-ingredient supply chains, accelerating market share capture by compliant players.
- Teenage Digital Commerce:Social media-driven discovery on TikTok and Instagram is pulling first-time buyers toward body mist trial sizes, expanding category penetration among consumers aged 16-22.
- Water-Based Formulation Chemistry:Advances in microemulsion stabilization enable alcohol-free mists with equivalent scent longevity, opening dermatological positioning in sensitive-skin segments.
Market Restraints
- Ethanol Price Volatility:Biofuel demand competition for corn and sugarcane feedstocks squeezes alcohol carrier margins, particularly for aerosol-dependent product lines.
- Propellant Supply Concentration:Hydrocarbon aerosol propellant production clusters in the US Gulf Coast and Rotterdam corridor, exposing brands to hurricane and refinery outage risks.
- Fragrance Molecular Restrictions:IFRA standards on synthetic musks and phthalates eliminate legacy scent bases, requiring complete portfolio rebuilds for heritage formulations.
Strategic Opportunities
- India Tier-2 Urban Expansion:Modern trade penetration in cities like Jaipur and Lucknow outpaces metro saturation, creating whitespace for affordable mist portfolios in organized retail.
- Biodegradable Microcapsule Technology:Convergence of encapsulation science with marine-safe chemistry enables "swim-friendly" claims, unlocking beach and fitness verticals previously closed to fragrance wear.
- Refill Station Infrastructure:Loop-style circular retail partnerships in France and Germany allow premium brands to bypass single-use packaging regulations while capturing repeat traffic.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise spanning both fragrance performance and skin microbiome compatibility concentrates at a handful of specialized universities in Switzerland and France.
- Clean Beauty Certification Lag:EWG Verified and COSMOS timelines stretch 14-18 months, delaying product launches behind competitor windows and eroding first-mover positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Mist Market |
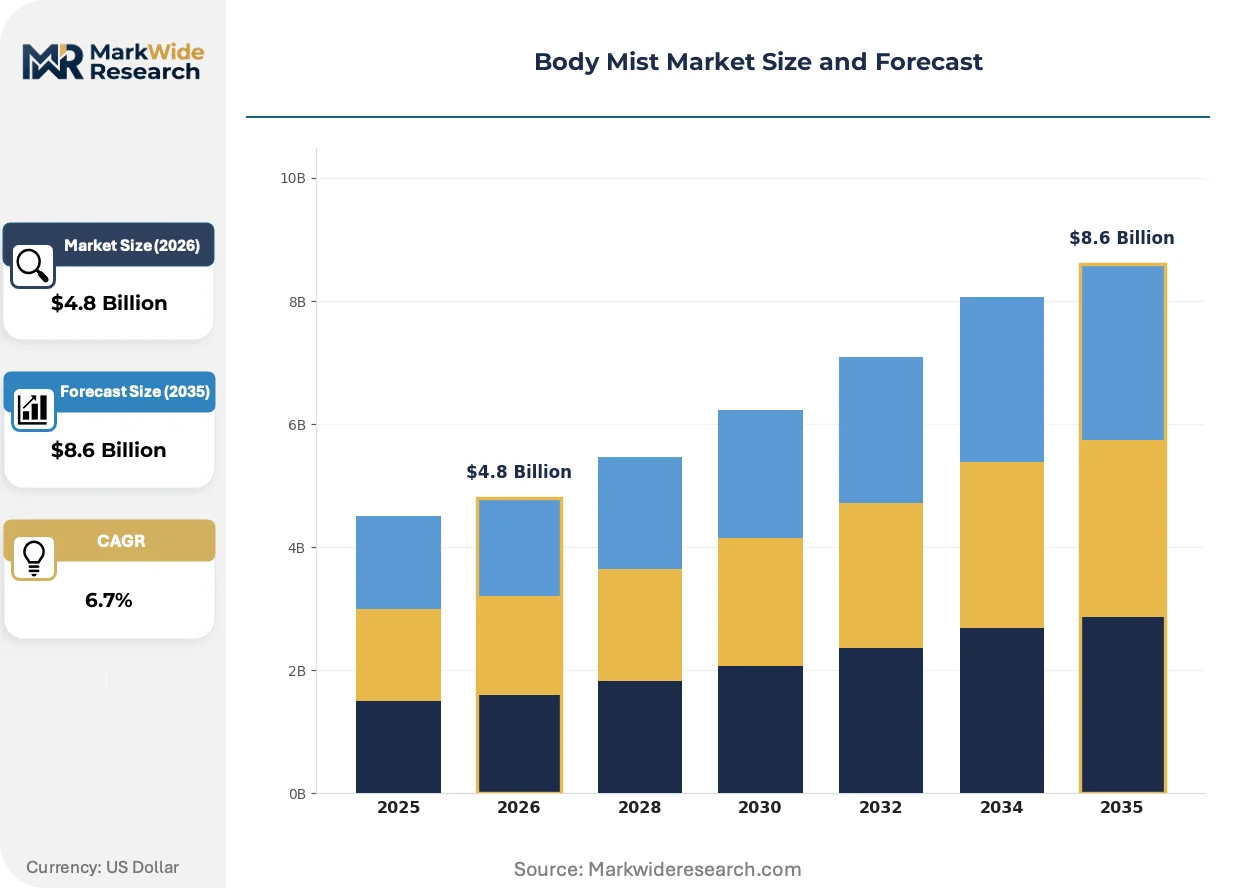
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance Infusion, Hydrating Mist, Scented Water, Cooling Spray End User: Women, Men, Unisex, Teenagers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Drugstores Formulation: Alcohol-Based, Oil-Based, Water-Based, Organic |
| Companies Covered | Coty Inc., Henkel, Unilever, Kao Corporation, Revlon, Estée Lauder Companies, Beiersdorf, Shiseido, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Mist Market Emerging Trajectories
Water-based microemulsion systems are actively displacing traditional alcohol-dominant carriers, while regulatory pressure on volatile organic compounds accelerates delivery mechanism innovation across all price tiers.
Spray-dried fragrance encapsulation is supplanting liquid alcohol solutions as the dominant delivery architecture for body mists targeting gym and workplace reapplication occasions. Young adult buyers in North American and German markets are adopting these formats at three times the rate of conventional sprays. This shift is compressing fill-finish equipment amortization cycles and forcing contract manufacturers toward dual-capability production lines.
REACH Annex XVII restrictions on allergenic fragrance compounds are mandating ingredient-by-ingredient safety dossiers for all new launches across the European Economic Area. Fragrance houses must now submit extended safety data sets to ECHA before market entry, adding 8-12 months to development timelines. Premium and masstige brands with dedicated regulatory affairs teams are absorbing these costs more readily than indie labels dependent on shared manufacturing facilities.
Subscription-based scent curation is fragmenting traditional seasonal purchase patterns among millennial and Gen-Z consumers in the United States and United Kingdom. Quarterly discovery boxes from specialized retailers are replacing department store counter browsing as the primary trial mechanism. This channel rotation is most pronounced in coastal metropolitan areas where direct-to-consumer logistics networks achieve same-day or next-day delivery density.
Body Mist Market Segmentation
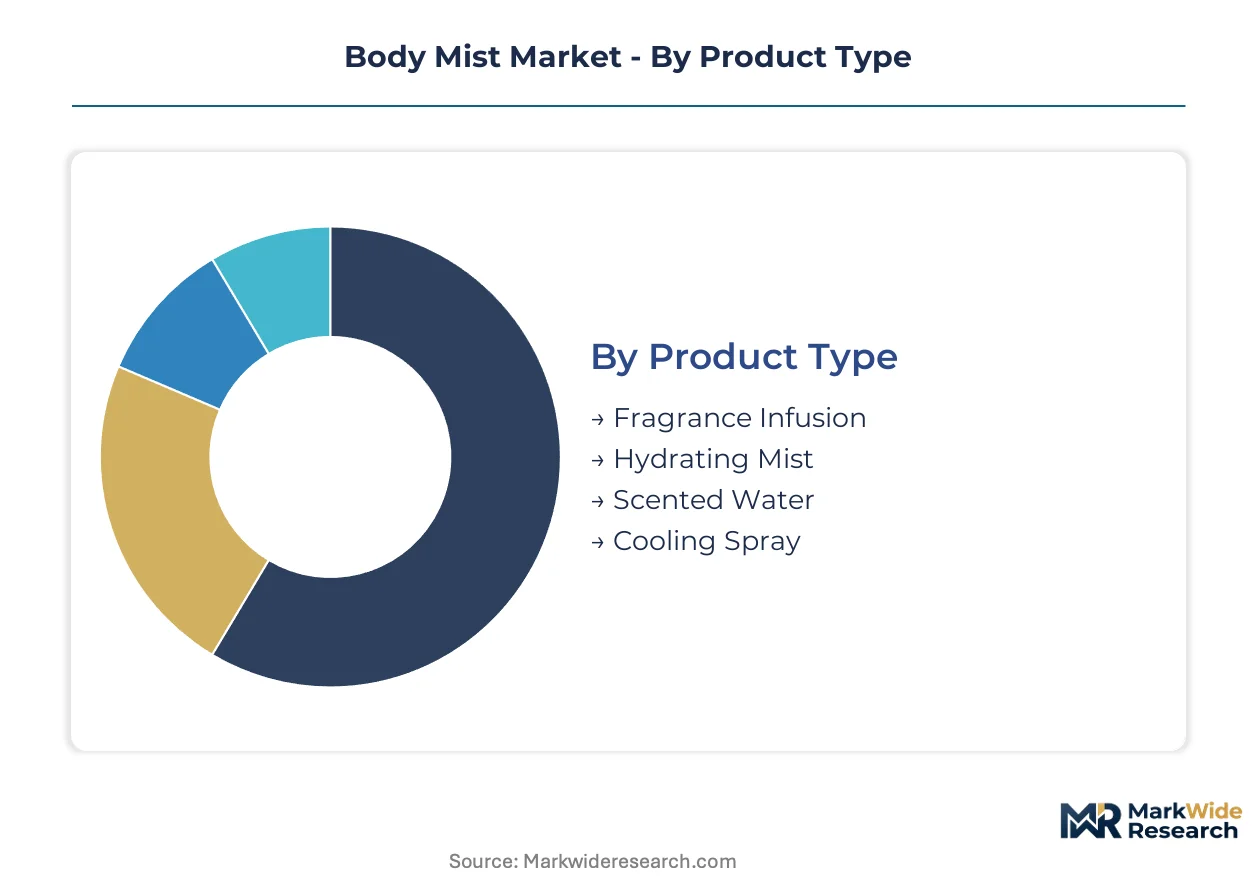
Body mist segmentation reveals how formulation chemistry and channel economics intersect. Product architecture determines margin pools, while distribution access dictates which consumer cohorts brands can profitably serve.
Product Type:
Channel placement varies sharply by scent concentration and functional positioning. Premium fragrance portfolios anchor specialty retail, while functional formats penetrate mass grocery and pharmacy channels.
- Fragrance Infusion:Contains two to five percent aromatic compounds in alcohol or water carriers, designed for scent-layering with eau de parfum. Demand concentrates in North American department store counters and German drugstore chains where brand loyalty sustains replenishment rates. Coty Inc. and L'Oréal dominate shelf space through exclusive fragrance licensing agreements.
- Hydrating Mist:Water-dominant formulations with humectants and low fragrance load, marketed for post-shower or mid-day skin refreshment. German and French consumers drive category expansion as dermatological positioning displaces purely aesthetic claims. Kao Corporation's microemulsion expertise captures Asian market share in this segment.
- Scented Water:Minimal aromatic concentration below two percent, positioned as entry-level trial formats for teenagers and price-sensitive buyers. Primarily distributed through supermarket end-cap displays and online flash sales.
- Cooling Spray:Menthol or thermal-regulating additives targeting fitness and outdoor recreation occasions. Seasonal demand spikes in US Sun Belt states and Australian coastal cities during summer months.
By volume, Fragrance Infusion leads. By growth pace, Hydrating Mist is climbing the fastest.
End User:
Gendered marketing architectures are fragmenting as unisex positioning captures younger demographics, though formulation chemistry and packaging aesthetics still diverge by target cohort.
- Women:Traditional core segment with established replenishment patterns around seasonal fragrance launches. Specialty stores sustain margin through gift-set bundling and loyalty program lock-in.
- Teenagers:Digital-native discovery via TikTok and Instagram drives trial-size purchases. Online retail captures this cohort at three times the rate of older demographics, with quarterly subscription boxes displacing counter browsing.
- Men:Emerging segment as grooming routines expand beyond deodorant and aftershave. Sports and fitness verticals provide entry points for cooling and post-workout variants.
- Unisex:Clean-beauty and minimalist positioning attracts millennial and Gen-Z buyers seeking to avoid gendered marketing. EWG Verified and COSMOS certifications command price premiums in this segment.
Women generate the largest revenue base. Teenagers show the steepest expansion trajectory in first-time buyer acquisition.
Distribution Channel:
Margin structures and consumer touchpoint intensity vary dramatically across channel types, with experiential sampling capabilities determining brand positioning feasibility.
- Specialty Stores:Sephora and Douglas-operated counters provide scent sampling and personalized consultation, sustaining premium price tiers through service differentiation. Gift-set bundling captures holiday purchase concentration.
- Online Retail:Direct-to-consumer platforms and Amazon marketplace listings achieve next-day delivery density in coastal US and UK metropolitan areas. Teenage discovery and subscription curation concentrate here.
- Supermarkets:Mass-market volume anchors for affordable portfolios, with end-cap placement driving impulse purchase. Unilever and Procter & Gamble leverage buyer power for shelf positioning.
- Drugstores:CVS, Walgreens, and dm-drogerie markt chains blend convenience with accessible price points. German drugstores particularly favor hydrating and dermatologically-positioned variants.
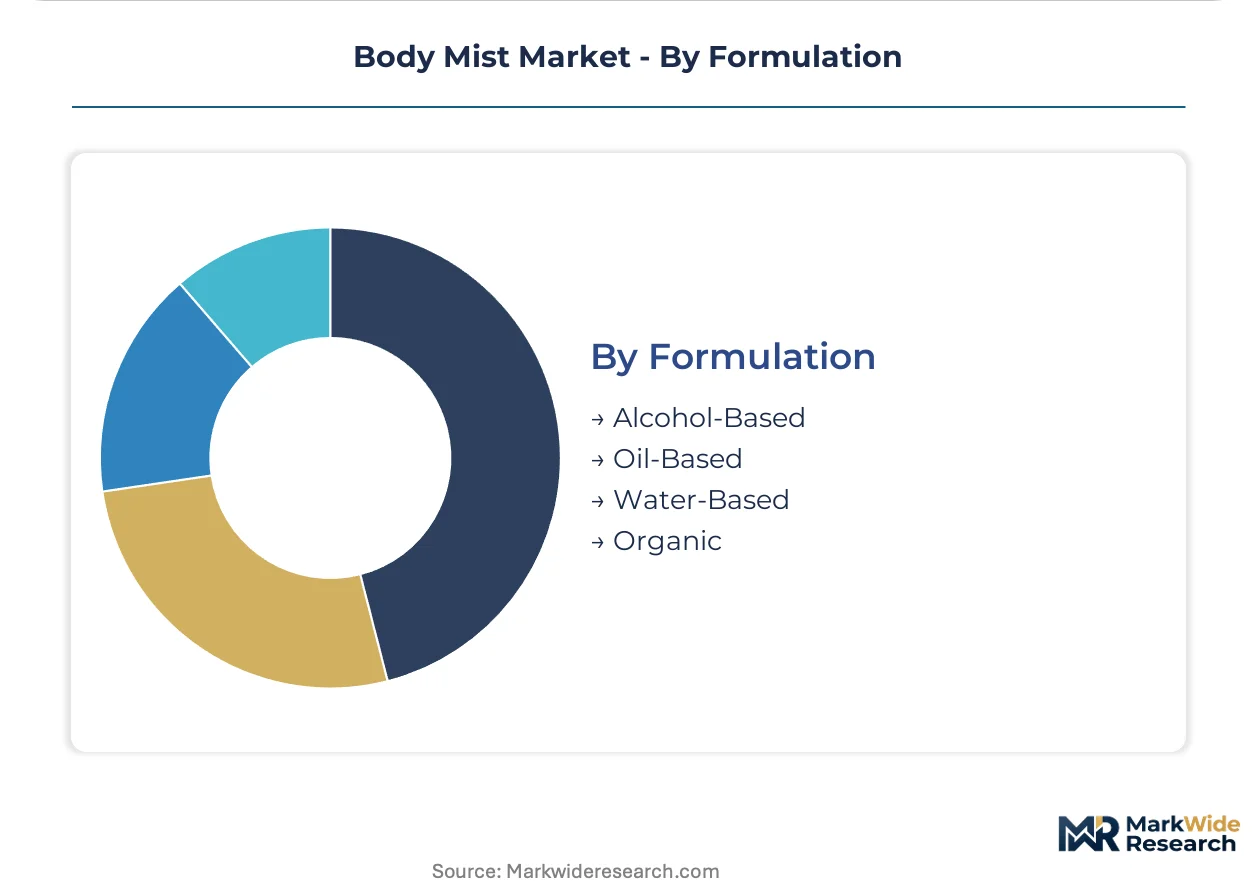
- Water-Based:Microemulsion-stabilized systems eliminate alcohol content, opening sensitive-skin and pediatric positioning. REACH VOC restrictions and consumer clean-beauty preferences accelerate adoption.
- Alcohol-Based:Traditional ethanol-dominant carriers provide optimal fragrance diffusion and dry-down performance. Biofuel demand competition for corn and sugarcane feedstocks squeezes input cost stability.
- Oil-Based:Slower-evaporating carriers extend scent longevity on dry skin types. Niche positioning in premium and natural-product channels with limited mass-market penetration.
- Organic:COSMOS or USDA Organic certification requires supply chain segregation and documentation overhead. Fourteen to eighteen month certification timelines delay launch windows behind conventional formulations.
Supermarkets move the highest unit volumes. Online retail gains share fastest among demographic shifts toward digital discovery.
Formulation:
Carrier chemistry determines regulatory exposure, production equipment requirements, and skin-compatibility marketing claims across all price tiers.
Alcohol-Based formulations retain volume leadership. Water-Based chemistry is expanding most quickly on regulatory and consumer-preference tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German and French consumers absorb premium pricing for dermatologically-positioned hydrators, while Indian and Brazilian buyers gravitate toward entry-level scented waters and trial formats.
United States
Teenage digital discovery on TikTok and Instagram drives trial-size purchases through direct-to-consumer channels. The FDA oversees cosmetic labeling and ingredient safety, while the EPA regulates volatile organic compound emissions from aerosolized delivery systems. New York and Los Angeles coastal metros sustain same-day delivery density for subscription-based scent curation services.
Germany
Hydrating mist demand concentrates among consumers prioritizing skin-beneficial claims over purely aesthetic fragrance. The EU REACH framework mandates ingredient-by-ingredient safety dossiers through ECHA, extending development timelines. Cologne and Hamburg anchor specialized retail networks where experiential sampling sustains premium price tiers.
France
Prestige fragrance infusion maintains strong replenishment patterns around seasonal launches. REACH Annex XVII restrictions on allergenic compounds force reformulation of heritage scent bases. Paris and Lyon host refill station infrastructure partnerships allowing premium brands to bypass single-use packaging regulations.
India
Modern trade penetration in Jaipur and Lucknow outpaces metro saturation, creating whitespace for affordable mist portfolios. The country's national cosmetic regulator enforces labeling standards through BIS certification requirements. Mumbai and Delhi-NCR organize mass-market volume through supermarket and drugstore channel control.
Brazil
Entry-level scented water formats capture price-sensitive teenage and young adult buyers through supermarket end-cap placement. ANVISA oversees cosmetic safety and ingredient disclosure requirements. São Paulo anchors organized retail expansion while Rio de Janeiro sustains seasonal demand spikes for cooling spray variants.
Body Mist Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in body mist manufacturing. Coty Inc. and L'Oréal leverage fragrance-forward supply chains and exclusive licensing agreements to dominate premium scent portfolios, while Unilever anchors mass-market volume through supermarket and drugstore channel control. Three strategic archetypes define competitive positioning: integrated fragrance houses with captive regulatory affairs teams, mass-market consumer goods conglomerates with buyer power over shelf placement, and water-based formulation specialists with microemulsion expertise. Dominant competitive moves include portfolio diversification into clean-beauty certified lines and geographic expansion through modern trade partnerships in emerging urban clusters.
Within the integrated fragrance house tier, Coty Inc. and L'Oréal exemplify players leveraging exclusive licensing agreements and dedicated regulatory teams to absorb REACH compliance costs more readily than smaller competitors. Among mass-market conglomerates, Unilever occupies a position defined by supermarket and drugstore channel control and volume-scale manufacturing economics. Kao Corporation represents the water-based formulation specialist archetype, with microemulsion expertise capturing share in sensitive-skin and pediatric-positioned segments across Asian markets.
| Leading Market Players |
|---|
| Coty Inc. |
| Henkel |
| Unilever |
| Kao Corporation |
| Revlon |
| Estée Lauder Companies |
| Beiersdorf |
| Shiseido |
| L'Oréal |
| Others |
Supply Flow & Price Mechanics
Contract manufacturing scale economies in aerosol and liquid fill-finish operations concentrate production among facilities achieving 80 percent-plus utilization rates, compressing per-unit costs for volume players while fragmenting price floors across specialty and mass-market tiers. REACH compliance investments and ethanol feedstock competition for biofuel markets simultaneously elevate cost baselines and reshape procurement priorities across European and North American supply networks.
Pricing Analysis
Refill station partnerships and subscription curation services now drive lifetime value beyond initial product purchase, particularly in French and German urban markets where Loop-style circular retail captures repeat traffic. Three-tier pricing structure across premium, standard, and economy levels separates dermatologically-certified hydrators from conventional fragrance infusions and entry-level scented waters. Pricing pressure stems from ethanol cost volatility as biofuel demand competes for corn and sugarcane feedstocks. Teenage buyers through digital channels exhibit highest price sensitivity, while prestige fragrance loyalists in specialty retail absorb premium positioning.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for fragrance compound shipments originating in Switzerland and France. Manufacturing concentrates in Germany, the United States, and China, with hydrocarbon propellant production clustering in the US Gulf Coast and Rotterdam corridor. Raw material dependencies span ethanol carriers, synthetic fragrance molecules, and aluminum aerosol canisters. Single-source vulnerability in propellant supply exposes brands to hurricane and refinery outage risks. Distribution runs through supermarket and drugstore mass-market channels alongside direct-to-consumer platforms achieving same-day delivery density in coastal metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based microemulsion chemistry represents a high-growth disruption as REACH VOC restrictions and clean-beauty certification demand converge, creating first-mover advantages for brands with pre-positioned alcohol-free formulation expertise.
For Market Incumbents: Consolidate regulatory affairs capabilities to absorb ECHA dossier requirements and 8-12 month development timeline extensions more readily than shared-manufacturing competitors. Deepen captive supply of fragrance-forward formulation expertise through exclusive licensing agreements, while expanding water-based portfolio share to defend against clean-beauty certified entrants. For New Entrants and Emerging Players: Lead with dermatological positioning in German and French hydrating mist segments where skin-beneficial claims command price premiums and certification timelines create incumbent delay. Target India tier-2 urban expansion through modern trade partnerships in Jaipur and Lucknow, exploiting whitespace before metro saturation closes distribution access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors water-based formulation specialists with microemulsion expertise and captive regulatory teams over alcohol-dependent legacy portfolios. Long-term viability hinges on clean-beauty certification completion and refill infrastructure partnerships. The signal to watch is EWG Verified and COSMOS approval velocity as competitive moat indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Beauty Certification Investment | EWG Verified and COSMOS approval unlocks premium pricing in unisex and sensitive-skin segments. |
| Water-Based Formulation Transition | Microemulsion expertise captures REACH-compliant positioning as VOC restrictions tighten. |
| Refill Station Infrastructure Partnership | Loop-style circular retail in France and Germany bypasses single-use packaging regulations. |
| Direct-to-Consumer Platform Launch | Same-day delivery density in coastal US and UK metros captures teenage digital discovery. |
| India Tier-2 Urban Distribution Expansion | Modern trade penetration in Jaipur and Lucknow outpaces metro saturation for affordable portfolios. |
Methodological Framework
Initial hypotheses were tested against primary input from fragrance house R&D directors, cosmetic regulatory affairs managers, retail category buyers, and contract manufacturing procurement leads and refined through secondary validation against REACH Annex XVII filings, ECHA safety dossier databases, Nielsen retail audit data, and customs import records. Bottom-up volume estimates from product-level SKU data were triangulated against top-down category spending figures derived from national cosmetic trade associations.
Variance decomposition across the projection horizon isolates drivers by formulation chemistry, distribution channel economics, and regional regulatory cluster. Segmentation dimensions modeled include product architecture, end-user demographic, carrier chemistry, and channel access tier. CAGRs were derived from fitted growth curves applied to baseline volume and value estimates, incorporating ethanol price indices, clean-beauty certification velocity, and digital commerce penetration rates as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or abrupt biofuel policy shifts would require recalibration. Practitioners should keep alternative scenarios live as ECHA allergen disclosure mandates and volatile organic compound restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Eyelash Curler Market